
 Custom Hearing Aids Market | 2026-2036
Custom Hearing Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Hearing Aids Market Outlook
European component manufacturing is decoupling from final assembly in Asian contract facilities. Sonova Holding AG leverages its Swiss R&D base to sustain premium digital signal processing leadership. Starkey Hearing Technologies anchors its competitive stance through in-house production of custom shells and deep audiology channel relationships.
Custom hearing aids are individually molded amplification devices fitted to a patient's ear anatomy, typically incorporating digital signal processors with 16-24 frequency channels and real-time feedback cancellation for speech intelligibility restoration. Behind-the-Ear and Receiver-in-Canal formats dominate volume due to their acoustic flexibility and easier repairability, while Completely-in-Canal variants command margin premiums from cosmetic-conscious adult users. Bluetooth-enabled wireless technology is displacing analog circuitry as the default configuration, with distribution gravitating toward audiology clinics where professional fitting justifies higher price realization.
The FDA regulates custom hearing aids as Class I or Class II medical devices under 21 CFR 874.3320, with the 2022 over-the-counter rule creating a parallel pathway for mild-to-moderate loss consumers. The EU Medical Device Regulation and CE marking requirements enforce clinical performance documentation and post-market surveillance across European markets. Stakeholders must monitor how reimbursement policy evolution and direct-to-consumer channel expansion reshape the economics of professional fitting services.
Market Dynamics
The FDA's 2022 over-the-counter hearing aid rule is fragmenting the traditional audiology channel by enabling direct-to-consumer access for mild-to-moderate hearing loss, forcing established manufacturers to defend professional fitting margins while new entrants capture price-sensitive demand.
Growth Catalysts
- Aging Demographics:The United States population aged 65 and above is expanding rapidly, creating sustained demand for personalized amplification solutions fitted through independent audiology clinics.
- Bluetooth Wireless Integration:Real-time streaming connectivity with smartphones and televisions is elevating consumer willingness to upgrade from analog devices to digitally fitted custom instruments.
- Reimbursement Policy Evolution:Medicare Advantage expansion and private payer coverage adjustments in the United States are reducing out-of-pocket costs for prescription-grade custom devices.
Market Restraints
- Semiconductor Supply Concentration:Advanced digital signal processors depend on concentrated Asian foundry capacity, exposing manufacturers to lead-time volatility and input cost pressure.
- OTC Channel Substitution:Self-fitting amplification devices priced below professional solutions threaten to commoditize the mild-to-moderate loss segment and compress average selling prices.
- Regulatory Friction from MDR:The European Union Medical Device Regulation imposes enhanced clinical documentation and post-market surveillance burdens on custom shell manufacturers exporting to European markets.
Strategic Opportunities
- Underpenetrated Emerging Markets:India and Brazil exhibit significant unmet need for hearing rehabilitation, with nascent audiology infrastructure creating first-mover advantages for quality-focused entrants.
- Remote Fitting Technology:Teleaudiology platforms enabling real-time programming adjustments are opening professional-grade service delivery to rural and homebound patient populations.
- AI-Powered Personalization:Machine learning algorithms processing environmental acoustic data are converging with custom hardware to enable adaptive amplification profiles without manual intervention.
Industry Challenges
- Audiologist Workforce Scarcity:The limited pipeline of certified professionals trained in digital fitting software is constraining clinic capacity expansion and extending patient wait times.
- Legacy System Integration:Established manufacturers face complex software migration challenges when connecting new wireless-enabled devices to proprietary fitting platforms inherited through acquisition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Hearing Aids Market |
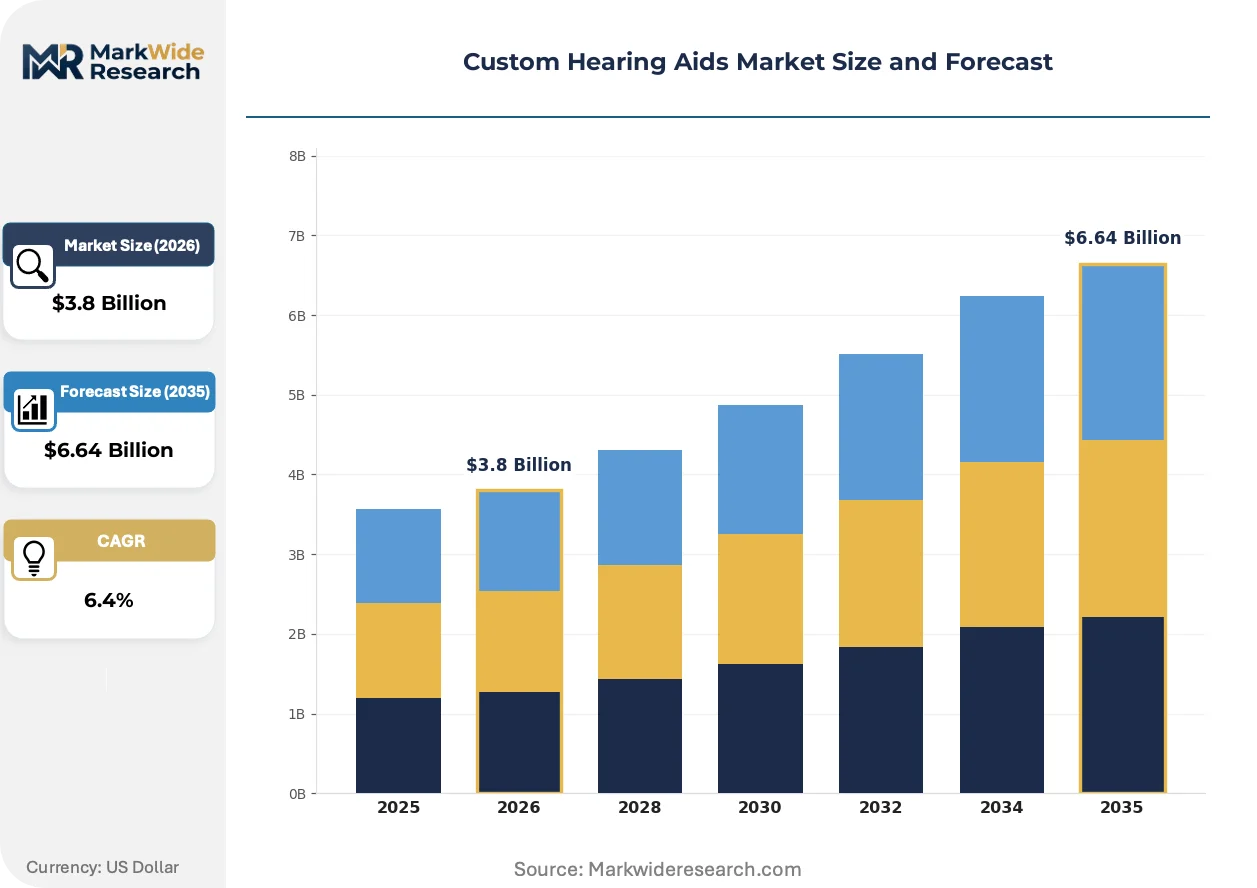
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Behind-the-Ear, In-the-Ear, Completely-in-Canal, Receiver-in-Canal End User: Seniors, Adults, Teens, Children Technology: Analog, Digital, Wireless, Bluetooth Distribution Channel: Online Sales, Audiology Clinics, Retail Stores, Hospitals |
| Companies Covered | Cochlear Limited, Sonova Holding AG, Starkey Hearing Technologies, Demant A/S, GN Hearing, WS Audiology A/S, Eargo, Amplifon, Oticon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Hearing Aids Market Strategic Shifts
Wireless connectivity architectures are restructuring how hearing rehabilitation is delivered, with three concurrent developments altering competitive boundaries between professional and self-directed care models.
Edge-based machine learning is decentralizing signal processing from clinic-based computers directly into the hearing instrument itself. Adult users with mild-to-moderate loss are adopting these self-optimizing devices at accelerating rates. This capability compression is enabling OTC-compliant products to approximate professional fitting outcomes without audiology intervention.
The FDA's over-the-counter rule has bifurcated the United States regulatory pathway into prescription and self-fitting categories with distinct labeling and marketing requirements. Manufacturers must now maintain dual quality systems and clinical evidence portfolios to serve both channels. Prescription-grade custom shell producers are responding by emphasizing medical-grade materials and severe-to-profound loss capabilities that fall outside OTC eligibility.
Subscription-based hearing rehabilitation bundles are displacing traditional device-plus-service transactions in metropolitan audiology practices. These arrangements combine hardware, remote adjustments, and battery replacement into predictable monthly fees. The United States coastal markets exhibit the highest concentration of this model, with independent clinics using it to defend patient relationships against retail pharmacy OTC distribution.
Custom Hearing Aids Market Segmentation
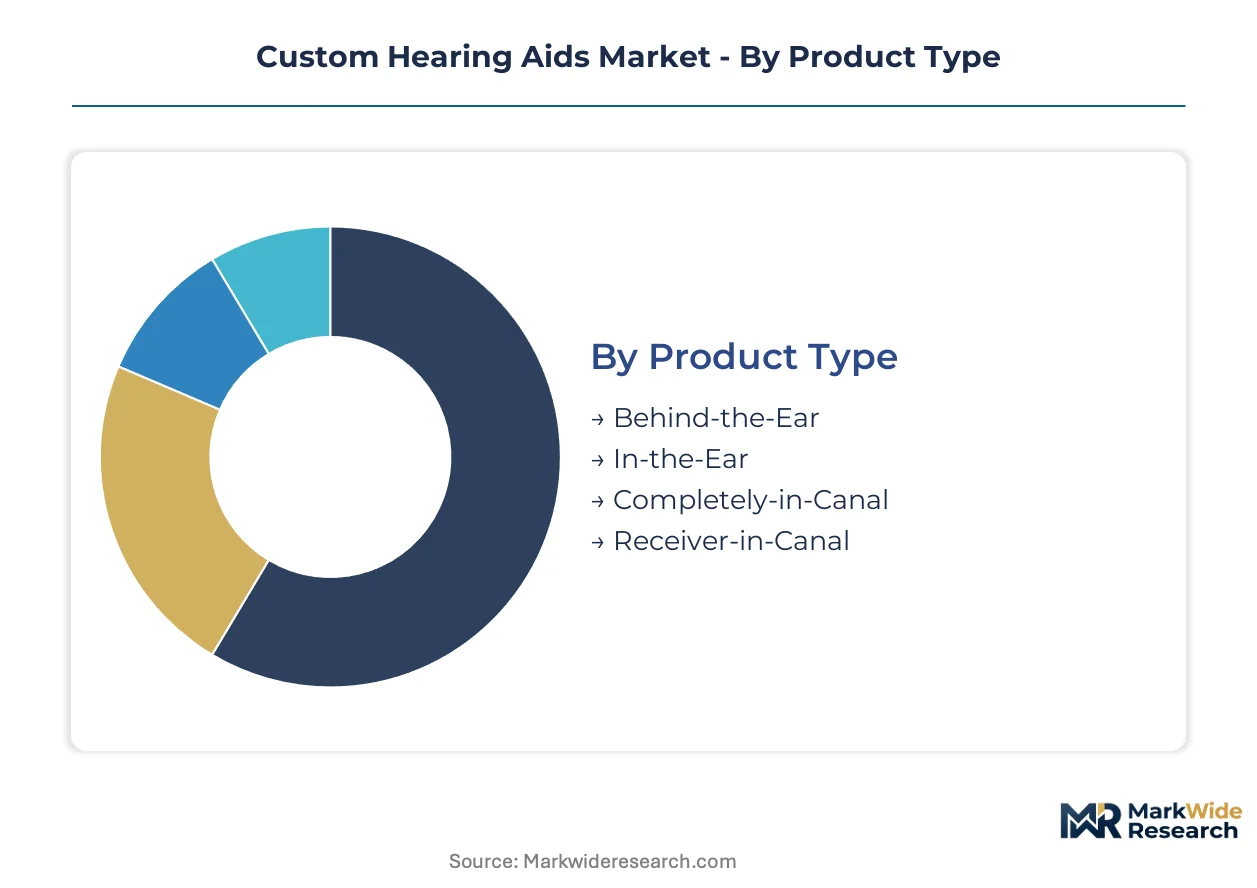
Segmentation in custom hearing aids reveals how capital deployment, patient anatomy, and channel economics fragment manufacturing priorities. Shell fabrication complexity and signal processing requirements vary dramatically across product architectures, dictating which configurations sustain premium pricing.
Product Type:
Capital intensity escalates with miniaturization and acoustic precision requirements across shell geometries.
- Behind-the-Ear:External housings accommodate larger batteries and robust digital signal processors with 16-24 frequency channels. Demand concentrates in Medicare-eligible populations across the United States where repairability and battery longevity outweigh cosmetic concerns.
- Receiver-in-Canal:Thin-wire architecture separates processor from receiver, enabling acoustic flexibility with reduced occlusion. German audiology chains favor this format for its balance of amplification power and discretion in professional fitting environments.
- In-the-Ear:Custom-molded shells fill the concha bowl, demanding precise impression capture and CNC milling investment.
- Completely-in-Canal:Deep canal placement requires medical-grade silicone expertise and micro-component assembly tolerances.
Behind-the-Ear absorbs the bulk of installed capacity; Receiver-in-Canal is expanding most quickly.
End User:
Reimbursement eligibility and loss severity thresholds segment addressable populations across age cohorts.
- Seniors:Presbycusis-driven demand dominates volume, with United States Medicare Advantage expansion reducing out-of-pocket exposure for prescription-grade digital instruments.
- Adults:Occupational noise exposure and early-onset genetic conditions sustain mid-life fitting volumes, particularly in manufacturing-heavy Midwestern states.
- Teens:Pediatric audiology protocols and educational accommodation requirements drive fitting through hospital-based clinics.
- Children:Congenital loss interventions require frequent shell remakes as ear canals grow, compressing margin per patient.
Seniors command the deepest fitting infrastructure; Adults show the steepest expansion trajectory in Bluetooth-enabled upgrades.
Technology:
Semiconductor content and wireless certification burdens stratify manufacturing cost structures.
- Digital:Multi-channel compression and feedback cancellation algorithms now constitute the baseline prescription standard across Swiss and Danish manufacturing facilities.
- Bluetooth:Real-time smartphone streaming and teleaudiology connectivity command hardware premiums in coastal United States markets.
- Analog:Simple amplification circuits persist in price-sensitive emerging market segments with limited audiology access.
- Wireless:Proprietary radio protocols for television and accessory pairing add licensing costs to bill-of-materials.
Digital platforms anchor production volumes; Bluetooth integration is climbing the fastest as iOS and Android compatibility becomes mandatory.
Distribution Channel:
Professional service bundling versus self-directed purchasing splits margin capture between manufacturers and retailers.
- Audiology Clinics:Independent practices in the United States sustain premium pricing through fitting software expertise and ongoing adjustment services.
- Online Sales:Direct-to-consumer platforms capture OTC-eligible mild-to-moderate loss demand with compressed margins and minimal service attachment.
- Retail Stores:Pharmacy and big-box electronics channels are gaining OTC shelf space following FDA rule implementation.
- Hospitals:Pediatric and severe-to-profound loss cases require medical-grade documentation and surgeon collaboration.
Audiology Clinics retain the highest revenue per unit; Online Sales are gaining share fastest among first-time adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone feedstock from Wacker Chemie's Burghausen facility anchors European custom shell production. Asian foundries in Taiwan and South Korea supply the digital signal processors that power amplification algorithms. Distribution economics favor regional assembly hubs positioned near audiology clinic density.
United States
Medicare Advantage expansion and the FDA's 2022 OTC rule are bifurcating demand between prescription and self-fitting channels. The FDA regulates custom devices as Class I or Class II medical devices under 21 CFR 874.3320, with distinct pathways for professional versus direct-to-consumer distribution. Minnesota's Twin Cities corridor hosts Starkey Hearing Technologies' integrated manufacturing campus for custom shell fabrication.
Germany
Aging demographics and statutory health insurance reimbursement sustain premium digital fitting volumes. The EU Medical Device Regulation enforces clinical performance documentation and post-market surveillance for CE-marked exports. The hearing technology cluster around Erlangen and Fürth concentrates DSP engineering talent and audiology research infrastructure.
Switzerland
Private healthcare financing and high disposable income support premium-priced custom instrumentation. Swissmedic maintains stringent quality system requirements for domestic manufacturing and import authorization. The Zürich-Stäfa corridor anchors Sonova Holding AG's R&D operations and precision assembly facilities.
Japan
Super-aging population dynamics and long-term care insurance coverage drive sustained fitting demand. METI oversees medical device standards alignment with international harmonization frameworks. The Kansai region around Osaka-Kobe hosts established audiology chains and hearing instrument distribution networks.
Denmark
Universal healthcare coverage and centralized procurement create stable demand for prescription-grade devices. The Danish Medicines Agency implements EU MDR requirements with accelerated post-market surveillance protocols. The Copenhagen-Roskilde corridor concentrates Demant A/S and GN Hearing's European headquarters and clinical research operations.
Custom Hearing Aids Market Competitive Environment
Global majors compete with regional champions across audiology channel relationships and digital signal processing capabilities. The vendor base concentrates around vertically integrated hearing instrument specialists and diversified medical device conglomerates with audiology divisions. Three archetypes dominate: Swiss-Danish premium DSP leaders, American integrated shell manufacturers, and European audiology service consolidators. Competitive moves center on teleaudiology platform licensing and backward integration into MEMS microphone supply.
Within the integrated manufacturing tier, Starkey Hearing Technologies exemplifies captive shell production and deep clinic channel embedding. Sonova Holding AG and Demant A/S occupy positions as European R&D-intensive specialists with premium positioning. WS Audiology A/S represents scale-driven consolidation across multiple regional brands and fitting software ecosystems.
| Leading Market Players |
|---|
| Cochlear Limited |
| Sonova Holding AG |
| Starkey Hearing Technologies |
| Demant A/S |
| GN Hearing |
| WS Audiology A/S |
| Eargo |
| Amplifon |
| Oticon |
| Others |
Value Chain & Pricing Dynamics
Family-owned audiology service networks and private-equity-rolled-up clinic chains exercise divergent procurement strategies, with the former prioritizing long-term manufacturer relationships while the latter squeeze supplier terms through volume aggregation. This ownership fragmentation shapes how custom shell manufacturers calibrate pricing discipline against patient lifetime value calculations.
Pricing Analysis
Warranty and service bundling separate prescription-grade custom devices from unbundled OTC alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects DSP channel count and Bluetooth certification tier. Cost compression in the economy segment is intensifying because retail pharmacy chains are extracting slotting-fee concessions for OTC shelf space. First-time adopters in online direct-to-consumer channels exhibit the highest price sensitivity, while severe-to-profound loss patients in hospital-based audiology departments accept premium positioning.
Supply Chain Analysis
Dual-sourcing mandates from major audiology chains require manufacturers to qualify alternative MEMS microphone and medical-grade silicone suppliers. Component supply draws from Taiwan and South Korea for DSP fabrication, Germany for silicone feedstock, and Switzerland for precision assembly equipment. Single-source vulnerability concentrates in advanced DSP foundry capacity. Distribution runs through independent audiology practices for prescription devices and retail pharmacy networks for OTC-compliant products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Custom hearing aid manufacturing is becoming a vertical-integration race, with captive shell production and proprietary fitting software emerging as the decisive downstream control points.
For Market Incumbents: Extend teleaudiology platform licensing to independent clinics as a defensive moat against OTC channel substitution. Deepen backward integration into MEMS microphone supply to reduce foundry dependency. Prioritize FDA Class II certification investments that exclude self-fitting competitors from severe-to-profound loss segments. For New Entrants and Emerging Players: Retail pharmacy chains represent the most accessible channel partner type for OTC-compliant product launches. Target mild-to-moderate loss first-time adopters in United States coastal metropolitan markets where smartphone streaming compatibility drives upgrade willingness. Pursue white-label manufacturing arrangements with established DSP suppliers to compress time-to-market. For Investors and Strategic Acquirers: Distressed-cycle entries favor European audiology service consolidators with reimbursement-locked revenue streams. Long-term viability hinges on regulatory arbitrage between prescription and self-fitting pathways. Watch Medicare Advantage coverage expansion rates as the primary inflection indicator for prescription-grade volume recovery.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | Class II medical device clearance unlocks severe-to-profound loss segments excluded from OTC eligibility. |
| CE Marking Pathway | EU MDR compliance enables access to German statutory health insurance reimbursement pools. |
| Hospital System Partnership | Pediatric audiology protocols at children's hospitals secure congenital loss intervention volumes. |
| Software Companion Development | Real-time smartphone streaming apps differentiate premium Bluetooth-enabled instruments. |
| Reimbursement Strategy | Medicare Advantage contracting reduces patient out-of-pocket exposure in United States senior populations. |
Study Parameters
Multi-period observation of DSP foundry capacity utilization, audiology clinic transaction volumes, and FDA 510(k) clearance timelines anchored the trend analysis, supplemented by interviews with audiology clinic owners, hearing instrument dispensing audiologists, biomedical engineers at custom shell manufacturers, and procurement managers at retail pharmacy chains. Secondary validation drew from FDA 510(k) databases, CMS Medicare Advantage enrollment statistics, EU MDR notified body documentation, and customs records for medical-grade silicone imports. Bottom-up patient-flow modeling and top-down audiology channel revenue estimates were triangulated against manufacturer shipment disclosures.
Segment-weighting approaches applied differential growth assumptions across product architectures and distribution channels. The analytical framework modeled shell geometry, patient age cohort, wireless technology tier, and audiology channel type throughout the forecast period. CAGRs were derived from installed base replacement cycles and first-time adoption curves specific to aging demographics. Forecast inputs incorporated Bluetooth protocol certification timelines and teleaudiology reimbursement policy evolution.
Caveats apply where FDA enforcement discretion on OTC marketing claims or EU MDR notified body backlog could materially shift the outlook. Deviation in Medicare Advantage hearing benefit generosity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Audiology Devices Market
ENT
Acute Sinusitis Market
ENT
ENT Devices Market
ENT
Europe Speech Therapy Market
ENT
US Hearing Aids Market
ENT
Nasal Polyps Treatment Market
ENT
Europe Hearing Aids Market
ENT
ENT Laser Devices Market
ENT
Global Sinusitis Treatment Market
ENT
Global Pediatric Hearing Aids Market
ENT
North America Hearing Aid Market
ENT
Surgical ENT Devices Market
ENT
Global ENT Workstations Market
ENT
Global Acute Otitis Media Treatment Market
ENT
Denmark Hearing Aids Market
ENT
ENT Examination Chair Market