
 Head and Neck Squamous Cell Carcinoma Market | 2026-2036
Head and Neck Squamous Cell Carcinoma Market Size, Share, and Industry Trends Forecast 2026-2036
Head and Neck Squamous Cell Carcinoma Market Outlook
Market Context with Strategic Players
Oncology nursing specialization is unwinding capacity bottlenecks at infusion centers across major cancer networks. Merck & Co., Inc. leverages its PD-1 franchise to sustain leadership in first-line recurrent or metastatic disease settings. Bristol-Myers Squibb Company anchors its position through dual immunotherapy combinations, while AstraZeneca PLC differentiates via EGFR-directed strategies in the subset of human papillomavirus-negative tumors.
Technical Definition and Structural Segments
Head and neck squamous cell carcinoma encompasses malignant epithelial neoplasms arising from the mucosal surfaces of the upper aerodigestive tract, with pathological grading based on keratinization patterns and nuclear pleomorphism to guide therapeutic intensity. Its primary commercial purpose centers on prolonging overall survival and preserving organ function through multimodal therapy across oral cavity, pharynx, larynx, and nasopharynx anatomical subsites. Immunotherapy now leads revenue generation within product type segmentation, while targeted therapy occupies the fastest-expanding margin pool as biomarker-directed patient selection narrows eligible populations. Hospitals dominate end-user volume, though oncology clinics capture disproportionate value per patient episode through focused chemotherapy and immunotherapy administration.
Regulatory Frame and Forward-Looking Close
FDA oncology center of excellence, EMA committee for medicinal products for human use, and NMPA drug evaluation center each impose distinct evidentiary standards for progression-free survival endpoints and biomarker co-development requirements. These frameworks shape trial design priorities, label expansion feasibility, and market access timelines across jurisdictions. Stakeholders must monitor evolving surrogate endpoint acceptability and companion diagnostic co-approval requirements to anticipate which therapeutic modalities will secure priority review status.
Market Dynamics
FDA accelerated approval pathways for checkpoint inhibitors have compressed development timelines from five years to under eighteen months, forcing oncology networks to reconfigure infusion capacity and biomarker testing workflows before confirmatory data matures.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA oncology center of excellence grants priority review to PD-1/PD-L1 combinations, shrinking regulatory review windows and accelerating commercial access for eligible patient populations.
- Oncology Clinic Expansion:Infusion centers at tertiary care networks in the United States are adding dedicated immunotherapy suites to accommodate rising patient volumes for combination regimens.
- Biomarker Co-Development:Companion diagnostic platforms for PD-L1 expression and tumor mutational burden are integrating into standard pathology workflows, enabling precision patient selection at the point of diagnosis.
Market Restraints
- Platinum Supply Concentration:Cisplatin and carboplatin production concentrates among three API manufacturers in India and China, creating vulnerability to export restrictions and quality enforcement actions.
- Reimbursement Compression:Medicare's oncology care model and commercial payer prior authorization requirements impose documentation burdens that delay treatment initiation by two to four weeks.
- Immunotherapy Resistance Mechanisms:Primary and acquired resistance to checkpoint blockade limits durable response rates to thirty to forty percent in recurrent or metastatic settings, constraining addressable populations.
Strategic Opportunities
- HPV-Positive Subset Expansion:Human papillomavirus-associated oropharyngeal tumors demonstrate superior immunotherapy responsiveness, creating opportunity for de-escalation trials and reduced toxicity protocols.
- Neoadjuvant Immunotherapy:Preoperative checkpoint inhibitor administration prior to definitive surgery is generating pathologic complete response data that could reshape first-line locoregional disease management.
- Community Oncology Networks:Independent practice associations in the United States are acquiring infusion capacity and hiring oncology-certified nurses to capture patients migrating from academic medical centers.
Industry Challenges
- Oncology Nursing Shortage:Infusion center staffing gaps constrain patient throughput, with certified oncology nurses requiring eighteen to twenty-four months of specialized training that cannot be compressed.
- Cross-Trial Data Harmonization:Variability in PD-L1 assay platforms and scoring criteria across registrational studies complicates payer evidence synthesis and formulary positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Head and Neck Squamous Cell Carcinoma Market |
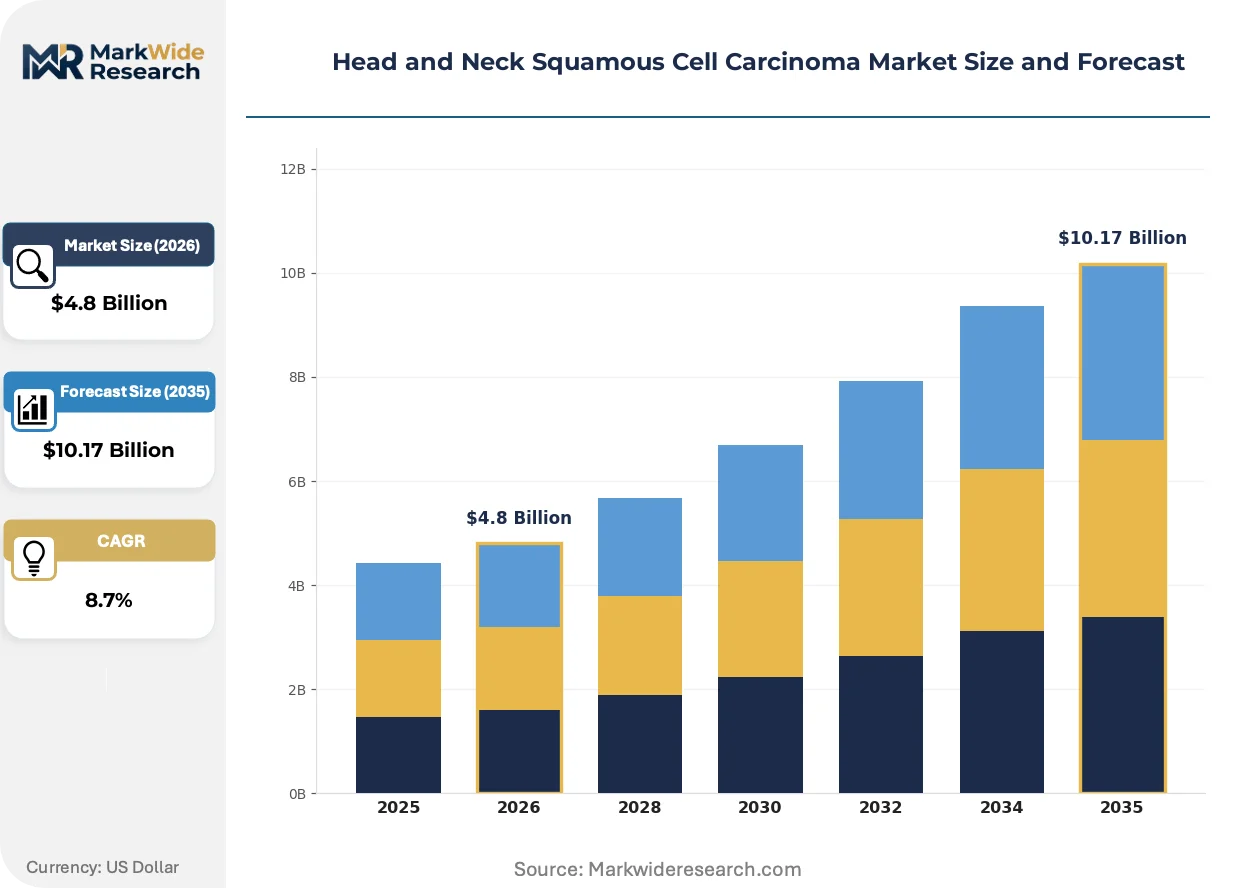
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Radiotherapy Application: Oral Cavity, Pharynx, Larynx, Nasopharynx End User: Hospitals, Oncology Clinics, Research Institutions, Homecare Settings Delivery Mode: Intravenous, Oral, Topical, Injectable |
| Companies Covered | Novartis AG, Amgen, Inc., Merck & Co., Inc., Merck KGaA, Boehringer Ingelheim GmbH, Bristol-Myers Squibb Company, AstraZeneca PLC, Eli Lilly and Company, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Head and Neck Squamous Cell Carcinoma Market Strategic Shifts
Next-generation sequencing is compressing diagnostic timelines from weeks to days, enabling real-time treatment decisions that bypass traditional pathology review hierarchies and accelerate therapeutic selection.
Artificial intelligence-powered digital pathology is fragmenting the diagnostic workflow by automating tumor-infiltrating lymphocyte quantification and PD-L1 scoring. Community pathology laboratories in the United States are adopting these platforms to reduce inter-observer variability and justify immunotherapy eligibility. The technology is fragmenting the historical monopoly of academic reference laboratories on complex biomarker interpretation.
The EMA committee for medicinal products for human use has tightened evidentiary standards for progression-free survival as a surrogate endpoint, requiring overall survival data or demonstration of preserved quality of life for full approval. This policy shift extends regulatory review timelines by twelve to eighteen months for agents relying on PFS primary endpoints. European sponsors are responding by enrolling larger cohorts earlier or pursuing conditional marketing authorization with post-approval commitments.
Patient advocacy organizations are demanding earlier access to investigational therapies through expanded access programs and right-to-try frameworks, pressuring manufacturers to establish compassionate use infrastructure before regulatory approval. This behavioral shift is most visible in the United States, where the Reagan-Udall Foundation and specific disease foundations are coordinating pre-approval access negotiations that bypass traditional clinical trial enrollment channels.
Head and Neck Squamous Cell Carcinoma Market Segmentation
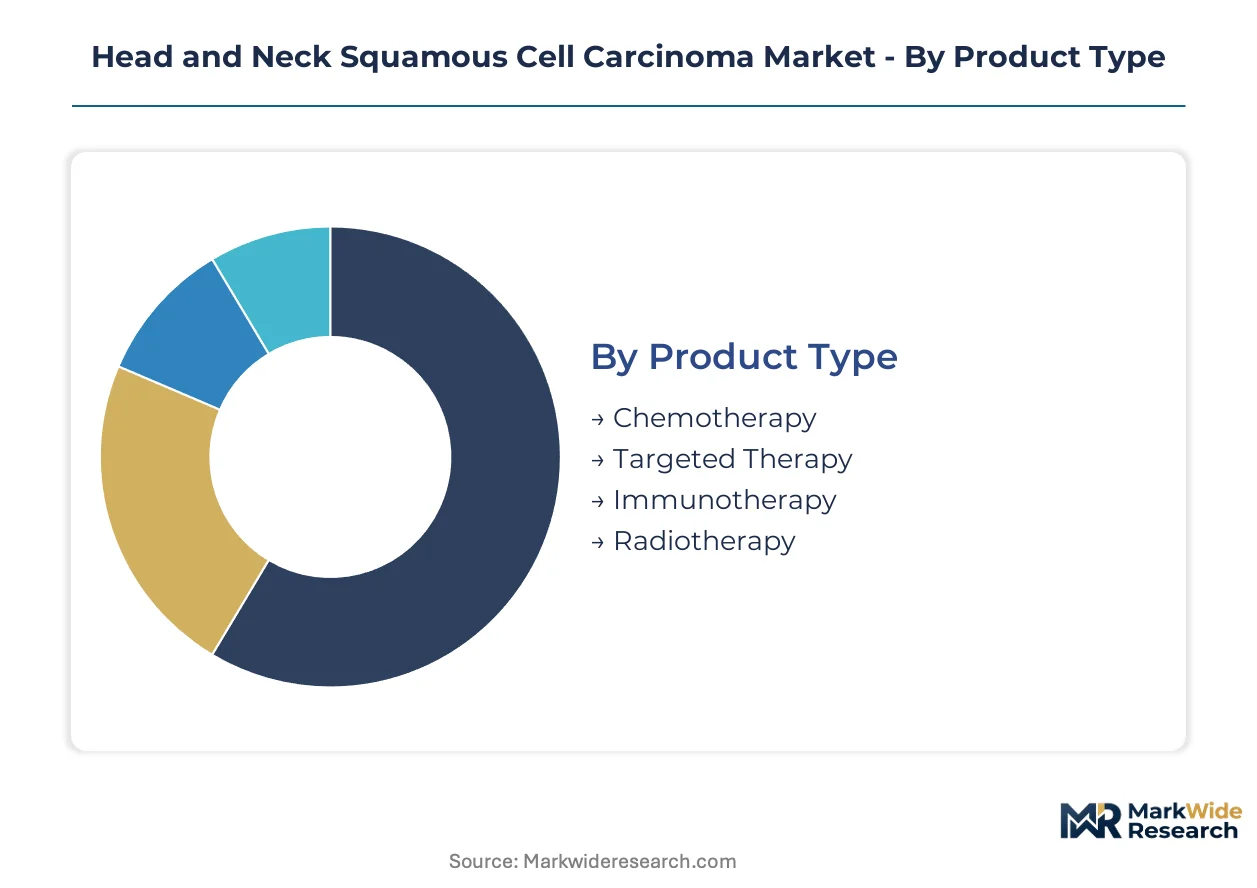
Segmentation in head and neck squamous cell carcinoma reflects divergent channel economics: infusion-based modalities concentrate value in tertiary care networks, while oral formulations and home administration are redistributing patient volume toward community settings. Understanding these flow patterns enables manufacturers to align capacity investments with where prescribing decisions actually occur.
Product Type:
Channel mix varies sharply across therapeutic modalities, with intravenous immunotherapy and chemotherapy anchoring hospital outpatient revenue while oral targeted agents enable clinic dispensing and pharmacy benefit management carve-outs.
- Immunotherapy:Checkpoint inhibitors dominate current prescribing in recurrent and metastatic settings, with PD-1 antibodies requiring specialized infusion infrastructure that concentrates administration at National Cancer Institute-designated centers. Demand clusters in the United States where prior authorization workflows for combination regimens have standardized around biomarker-driven patient selection.
- Targeted Therapy:EGFR inhibitors and emerging agents directed at specific molecular subsets enable oral administration pathways that bypass traditional infusion center bottlenecks. Prescribing concentrates among academic medical centers with integrated molecular tumor boards capable of interpreting next-generation sequencing reports within clinically actionable timeframes.
- Chemotherapy:Platinum-based regimens remain foundational for concurrent chemoradiation protocols, with cisplatin and carboplatin infusions generating predictable admission patterns at radiation oncology departments.
- Radiotherapy:External beam and brachytherapy modalities anchor locoregional disease management, with proton therapy capacity expanding at specialized centers seeking to reduce long-term toxicity in younger patient populations.
Immunotherapy dominates installed base. Targeted therapy is where expansion concentrates.
Application:
Cost tier stratification emerges across anatomical subsites, with oropharyngeal and nasopharyngeal presentations commanding premium diagnostic and therapeutic intensity due to proximity to critical structures and HPV-associated biology.
- Oral Cavity:Surgical resection with adjuvant radiation remains standard of care for resectable disease, generating demand for reconstructive surgery and dental oncology services that extend episode value beyond oncology drug spend.
- Pharynx:Oropharyngeal subsites demonstrate the strongest immunotherapy responsiveness among HPV-positive tumors, driving de-escalation trial enrollment and reduced toxicity protocol development at major cooperative groups.
- Larynx:Organ preservation protocols prioritize chemoradiation over total laryngectomy, with voice rehabilitation and swallowing therapy services creating ancillary revenue streams at multidisciplinary centers.
- Nasopharynx:Distinct epidemiology with EBV association and geographic clustering shapes trial design and regulatory strategy, with separate approval pathways emerging in Asian versus Western markets.
Oral cavity captures the largest procedural volume. Pharynx applications are climbing the fastest.
End User:
Customer type segmentation reveals a volume-value inversion: hospitals process the most patient encounters while oncology clinics extract superior margin per episode through focused chemotherapy and immunotherapy administration.
- Hospitals:Academic medical centers anchor complex case referral patterns, with emergency department presentation of airway-compromised patients driving unplanned admission volumes that subsidize elective oncology service lines.
- Oncology Clinics:Dedicated infusion centers are expanding immunotherapy suite capacity to capture patients migrating from hospital outpatient departments, with physician-owned models achieving faster prior authorization turnaround.
- Research Institutions:Phase I and II trial enrollment concentrates at sites with embedded phase I units capable of managing immune-related adverse events through dedicated inpatient beds.
- Homecare Settings:Oral oncolytic administration and supportive care medications are shifting patient days away from institutional settings, with specialty pharmacy networks managing adherence monitoring and toxicity triage.
Hospitals dominate installed base. Oncology clinics are where expansion concentrates.
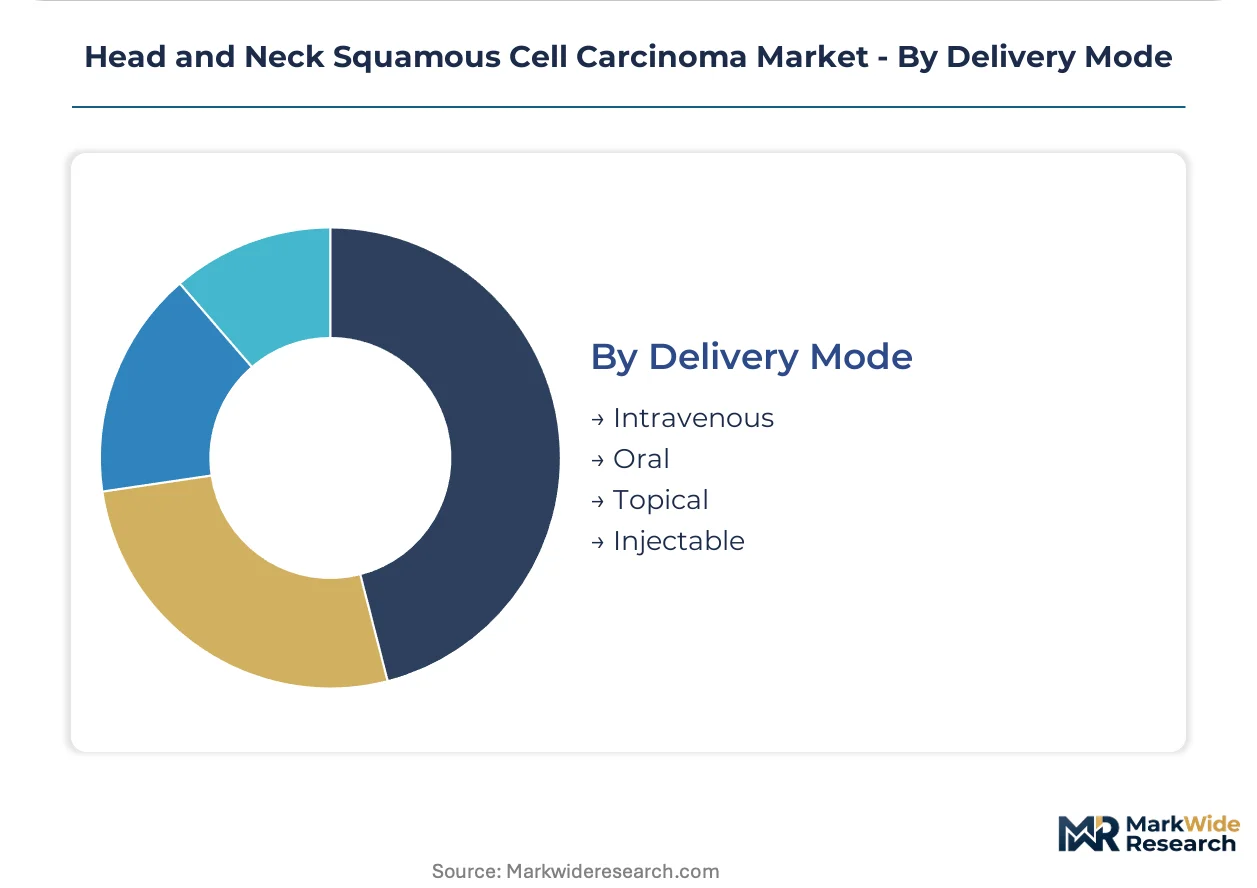
Delivery Mode:
Supply concentration characterizes parenteral manufacturing, with intravenous formulations dependent on contracted sterile compounding capacity while oral dosage forms enable broader distribution through specialty pharmacy networks.
- Intravenous:Infusion administration requires cold chain logistics and oncology-certified nursing staff that constrain throughput at individual sites, creating wait times that manufacturers address through patient assistance programs.
- Oral:Targeted agents and supportive care medications bypass infusion center capacity constraints, with adherence packaging and remote monitoring technologies enabling decentralized care models.
- Topical:Limited to pre-malignant lesions and palliative wound care, with compounding pharmacy relationships supporting customized formulation for mucosal application.
- Injectable:Subcutaneous immunotherapy formulations under development promise to shift administration from infusion centers to clinic injection rooms or home health nursing visits.
Intravenous dominates installed base. Oral delivery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor commercial activity in the United States, while EMA and NMPA frameworks shape parallel development tracks across Europe and China. Tertiary care networks concentrate immunotherapy administration capacity in specific metropolitan clusters.
United States
National Cancer Institute-designated centers drive combination regimen adoption through embedded phase I units and dedicated immunotherapy suites. Medicare's oncology care model and commercial payer prior authorization requirements impose documentation burdens that delay treatment initiation. The MD Anderson Cancer Center in Houston and Memorial Sloan Kettering in New York anchor referral patterns for complex oropharyngeal cases.
Germany
University hospitals in Munich and Heidelberg coordinate de-escalation trials for HPV-positive tumors through the German Cancer Consortium. EMA committee for medicinal products for human use standards for progression-free survival endpoints extend regulatory review timelines, prompting sponsors to enroll larger cohorts earlier. The National Center for Tumor Diseases in Heidelberg integrates companion diagnostic platforms into standard pathology workflows.
China
NMPA drug evaluation center requirements for biomarker co-development shape trial design priorities for nasopharyngeal carcinoma, which demonstrates distinct epidemiology with EBV association. Domestic API manufacturers concentrate platinum-based chemotherapy production, creating supply vulnerabilities to export restrictions. Sun Yat-sen University Cancer Center in Guangzhou anchors regional referral patterns for endemic nasopharyngeal presentations.
Japan
PMDA standards for overall survival data preservation influence conditional marketing authorization strategies for checkpoint inhibitors. Academic medical centers in Tokyo and Osaka maintain embedded phase I units capable of managing immune-related adverse events. The National Cancer Center Hospital in Tokyo coordinates multicenter trials for recurrent or metastatic disease settings.
United Kingdom
NICE technology appraisal processes determine reimbursement access for PD-1/PD-L1 combinations in recurrent or metastatic settings. The Royal Marsden NHS Foundation Trust in London and the Christie NHS Foundation Trust in Manchester anchor regional immunotherapy administration capacity. Cancer Research UK coordinates early-phase trial networks that compress patient enrollment timelines.
Head and Neck Squamous Cell Carcinoma Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the head and neck squamous cell carcinoma market. Large pharmaceutical companies with established oncology franchises control checkpoint inhibitor development and commercialization infrastructure. Mid-tier biopharmaceutical firms concentrate on targeted therapy modalities and biomarker-directed patient selection. Competitive moves center on portfolio diversification through immuno-oncology licensing and geographic expansion into Asia-Pacific markets with distinct regulatory pathways.
Within the integrated leader tier, Merck & Co., Inc. and Bristol-Myers Squibb Company occupy positions defined by PD-1 franchise scale and combination regimen development. AstraZeneca PLC represents the targeted therapy archetype through EGFR-directed strategies. Among European-based developers, Merck KGaA and Boehringer Ingelheim GmbH exemplify the mid-tier biopharmaceutical model focused on specialized oncology indications.
| Leading Market Players |
|---|
| Novartis AG |
| Amgen, Inc. |
| Merck & Co., Inc. |
| Merck KGaA |
| Boehringer Ingelheim GmbH |
| Bristol-Myers Squibb Company |
| AstraZeneca PLC |
| Eli Lilly and Company |
| Pfizer Inc. |
| Others |
Value Chain & Pricing Dynamics
FDA oncology center of excellence accelerated approval pathways gate both manufacturer qualification and price differentiation simultaneously, requiring companion diagnostic co-development investments that stratify market access costs across checkpoint inhibitor portfolios. This regulatory architecture concentrates pricing power among incumbents with integrated diagnostic capabilities while compressing margins for late entrants lacking biomarker platform partnerships.
Pricing Analysis
Long-term offtake agreements between tertiary care networks and immunotherapy manufacturers anchor pricing structures for PD-1/PD-L1 combinations, with value-based contracts tying reimbursement to progression-free survival benchmarks. Price differentiation separates academic medical centers with embedded phase I units from community oncology networks lacking immune-related adverse event management infrastructure. Pricing pressure stems from Medicare's oncology care model documentation requirements that extend prior authorization timelines. Community clinics demonstrate highest price sensitivity due to constrained infusion capacity and nursing shortage constraints.
Supply Chain Analysis
Port congestion at Mumbai and Shanghai gateways elevates inbound logistics costs for platinum-based API shipments from Indian and Chinese manufacturers to sterile compounding facilities in the United States. Active pharmaceutical ingredient production for cisplatin and carboplatin concentrates in India and China, with formulation and fill-finish capacity clustering in the United States and Germany. Raw material dependencies span platinum group metals, specialized excipients for liposomal formulations, and single-use bioreactor components. Single-source vulnerability characterizes the three-manufacturer concentration for platinum API supply. Distribution runs through contracted specialty pharmacy networks with cold chain integrity requirements for checkpoint inhibitor cold storage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in patient assistance programs and adherence monitoring platforms expand faster than core drug revenue, as manufacturers compete on prior authorization turnaround and nursing support rather than molecule differentiation alone.
For Market Incumbents: Shield market position by deepening backward integration into companion diagnostic manufacturing and securing exclusive pathology platform partnerships at NCI-designated centers. Counter emerging biosimilar threats through vertical integration into home infusion nursing networks that lock in patient episode capture. For New Entrants and Emerging Players: Anchor in HPV-positive oropharyngeal de-escalation trial networks where immunotherapy responsiveness enables reduced-toxicity protocol differentiation. Target community oncology associations acquiring independent infusion capacity as the most penetrable channel. Pursue go-to-market angles through specialty pharmacy adherence platform partnerships rather than direct hospital contracting. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across neoadjuvant immunotherapy development programs requiring larger cohort enrollment and longer follow-up periods. Long-term viability favors developers with integrated biomarker platforms and existing checkpoint inhibitor infrastructure. Watch for inflection signals in pathologic complete response rate thresholds that reshape first-line locoregional disease management standards.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA co-approval requirements for PD-L1 assays accelerate biomarker platform consolidation among reference laboratories. |
| Neoadjuvant Immunotherapy Trial Expansion | Pathologic complete response data from preoperative checkpoint inhibitor administration reshapes surgical oncology referral patterns. |
| Community Infusion Capacity Acquisition | Independent practice associations hiring oncology-certified nurses capture patient volume migrating from academic medical centers. |
| Subcutaneous Formulation Development | Shift from infusion centers to clinic injection rooms reduces nursing burden and expands addressable site networks. |
| HPV-Positive Subset Protocol De-escalation | Reduced toxicity trials for oropharyngeal tumors create differentiation in younger patient populations with superior immunotherapy response. |
Study Parameters
Desk research of FDA accelerated approval filings, EMA committee for medicinal products for human use assessment reports, and ClinicalTrials.gov protocol databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors at major payers, and oncology nursing directors at infusion centers. Secondary validation drew from hospital procurement databases, GPO contract repositories, and CMS Medicare claims data. Bottom-up patient volume estimates by treatment line and subsite triangulated against top-down manufacturer revenue disclosures.
Variance decomposition across product type, application subsite, end-user channel, and regional regulatory cluster informed the analytical framework over the projection horizon. Modeled segmentation dimensions spanned immunotherapy versus targeted therapy versus chemotherapy modality, oral cavity versus pharynx versus larynx versus nasopharynx anatomical presentation, hospital versus clinic versus homecare setting, and United States versus European Union versus China versus Japan regulatory jurisdiction. CAGRs derived from patient incidence projections, treatment penetration assumptions, and pricing trajectory synthesis. Forecast inputs incorporated biomarker testing adoption curves and infusion center capacity expansion plans.
Decision-makers should treat outputs as directional under assumptions of stable regulatory pathway timelines and continued checkpoint inhibitor efficacy profiles; material deviation in surrogate endpoint acceptability or immunotherapy resistance rates would warrant model refresh. Specific risk factors include platinum API export restrictions, oncology nursing shortage intensification, and payer prior authorization requirement expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Global Acute Otitis Media Treatment Market
ENT
Hearing Loss Disease Treatment Market
ENT
Acute Sinusitis Market
ENT
ENT Devices Market
ENT
Global Pediatric Hearing Aids Market
ENT
Surgical ENT Devices Market
ENT
Nasal Sampling Lines Market
ENT
Global Audiological Devices Market
ENT
Electrolarynx Market
ENT
ENT Laser Devices Market
ENT
Global Sinusitis Treatment Market
ENT
North America Hearing Aid Market
ENT
ENT Examination Chair Market
ENT
Global ENT Workstations Market
ENT
Hearing Amplifiers Market
ENT
Europe Speech Therapy Market