
 Nasal Polyps Treatment Market | 2026-2036
Nasal Polyps Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Nasal Polyps Treatment Market Outlook
Combination therapy bundling is realigning prescribing patterns across outpatient settings. Sanofi leverages its Dupixent positioning to anchor biologic-corticosteroid protocols in refractory cases. Regeneron Pharmaceuticals competes through co-development muscle and sustained R&D intensity in IL-4Rα pathway science. GlaxoSmithKline differentiates via Nucala's eosinophil-targeted mechanism and established respiratory commercial infrastructure.
Nasal polyps treatment encompasses pharmacological and interventional modalities targeting benign inflammatory outgrowths of the sinonasal mucosa, typically measured by endoscopic polyp score and computed tomography Lund-Mackay grading to assess severity and guide intervention. The primary purpose centers on restoring nasal airflow, olfaction, and quality of life while reducing polyp recurrence and surgical burden. Corticosteroids remain the volume backbone across topical and oral delivery modes, though biologics command disproportionate value concentration as payers grapple with premium pricing for dupilumab, omalizumab, and mepolizumab. Surgical intervention persists as a mature revenue stream with predictable reimbursement but faces margin compression from shifting medical management protocols and ambulatory migration.
FDA oversees biologics licensing through the Center for Drug Evaluation and Research, while EMA's Committee for Medicinal Products for Human Use shapes European access and pricing negotiations through centralized marketing authorization. The EU MDR and FDA 510(k) pathways respectively govern implantable sinus devices and drug-eluting stents, creating divergent compliance burdens for device-drug combination developers. Stakeholders must monitor payer evidence requirements for biologic step-therapy positioning and the evolving threshold for surgical versus medical-first protocols in health technology assessments.
Market Dynamics
The nasal polyps treatment market is being restructured by the migration from surgical-first protocols to biologic step-therapy algorithms, a shift reinforced by FDA accelerated approval pathways and EMA centralized marketing authorization timelines that compress development cycles and reshape prescriber decision trees.
Growth Catalysts
- IL-4Rα pathway biologics:Dupilumab and related monoclonal antibodies are expanding the addressable population of refractory chronic rhinosinusitis with nasal polyps patients who previously required repeat endoscopic sinus surgery.
- EMA centralized authorization:The Committee for Medicinal Products for Human Use streamlined European market entry for eosinophil-targeted therapies, reducing country-by-country reimbursement negotiation timelines.
- United States specialist rhinology networks:Dense clustering of academic ENT centers in Boston, Philadelphia, and Houston creates concentrated demand for advanced interventional and pharmacological protocols.
Market Restraints
- Biologic manufacturing concentration:Active pharmaceutical ingredient production for monoclonal antibodies clusters in Ireland and Singapore, exposing supply chains to single-site regulatory actions or geopolitical friction.
- Oral corticosteroid dependency:Generic prednisone and methylprednisolone remain the default escalation step before biologic authorization, compressing revenue capture for novel agents.
- EU MDR compliance burden:Drug-eluting sinus stents and implantable devices face extended conformity assessment timelines, delaying product refreshes and incremental innovation cycles.
Strategic Opportunities
- Japan's aging rhinology patient base:METI reimbursement reforms for biologic therapies in chronic inflammatory conditions create favorable access conditions for eosinophil-targeted mechanisms in an underpenetrated market.
- Real-world evidence platforms:Integration of electronic health record data from United States integrated delivery networks enables post-market outcome studies that support payer step-therapy removal.
- Tele-ENT channel development:Remote nasal endoscopy interpretation and virtual biologic injection training expand specialist reach into community hospital settings previously excluded from advanced therapy access.
Industry Challenges
- Rhinology fellowship pipeline constraints:United States academic medical centers graduate fewer than 60 advanced sinus surgeons annually, creating bottlenecks for interventional volume growth and biologic injection training.
- Biologic cold chain integrity:Temperature excursion management for subcutaneous dupilumab and mepolizumab requires specialized pharmacy infrastructure that community ENT clinics struggle to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasal Polyps Treatment Market |
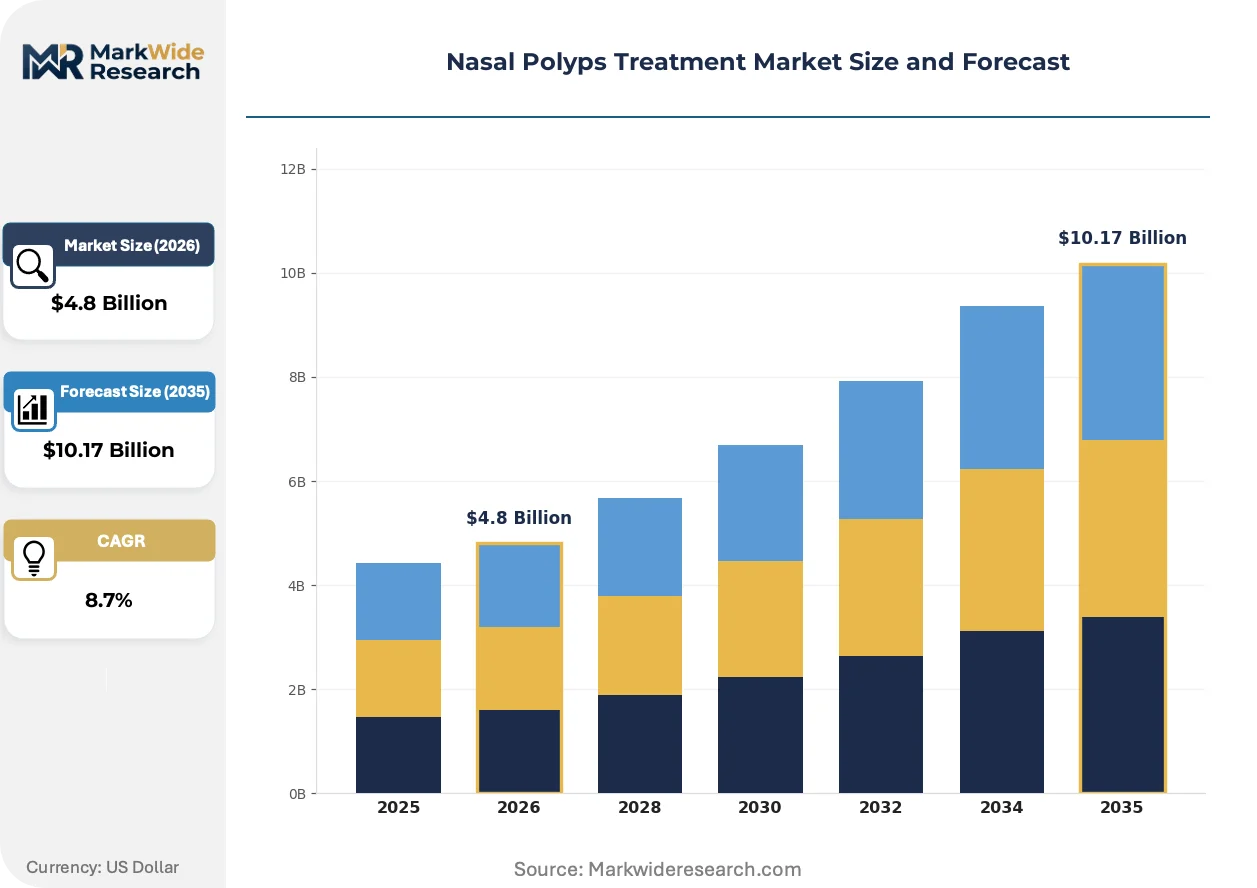
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Biologics, Antihistamines, Saline Nasal Sprays Delivery Mode: Topical, Injectable, Oral, Nasal End User: Hospitals, Clinics, Homecare, Ambulatory Surgical Centers Treatment Approach: Medical, Surgical, Combination, Supportive Care |
| Companies Covered | Sanofi, Regeneron Pharmaceuticals, GlaxoSmithKline, Novartis, AstraZeneca, Merck & Co., F. Hoffmann-La Roche, OptiNose, Intersect ENT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasal Polyps Treatment Market Strategic Shifts
Biologic mechanism diversification and digital diagnostic integration are compressing the interval between symptom onset and targeted therapy initiation, while regulatory harmonization efforts accelerate cross-border product availability.
Drug-eluting sinus implants are converging with sustained-release corticosteroid matrices to extend the functional window between endoscopic sinus surgery and biologic escalation. Academic rhinology departments in Germany and the United States are piloting these combination devices in high-recurrence patients. This convergence is compressing the surgical revision rate and shifting device manufacturers toward hybrid revenue models that bundle procedural hardware with pharmaceutical components.
EMA's expanded indication framework for IL-5 and IL-4Rα inhibitors is compressing the evidence threshold required for chronic rhinosinusitis with nasal polyps labeling beyond the original severe asthma anchor indication. German and French health technology assessment bodies are adapting their clinical benefit rating methodologies to accommodate biomarker-selected patient subsets. This regulatory evolution most directly affects eosinophil-targeted therapies seeking tiered reimbursement across European Union member states with divergent cost-effectiveness thresholds.
Patient-reported outcome measures are displacing physician-assigned polyp scores as the primary endpoint in United States payer contracts and United Kingdom National Health Service value-based purchasing agreements. ENT clinics in London, New York, and Los Angeles are deploying smartphone-based smell identification testing and nasal airflow symptom diaries to satisfy these data requirements. This behavioral shift is most visible in United States integrated delivery networks where pharmacy benefit managers are tying biologic prior authorization to documented quality-of-life trajectory data.
Nasal Polyps Treatment Market Segmentation
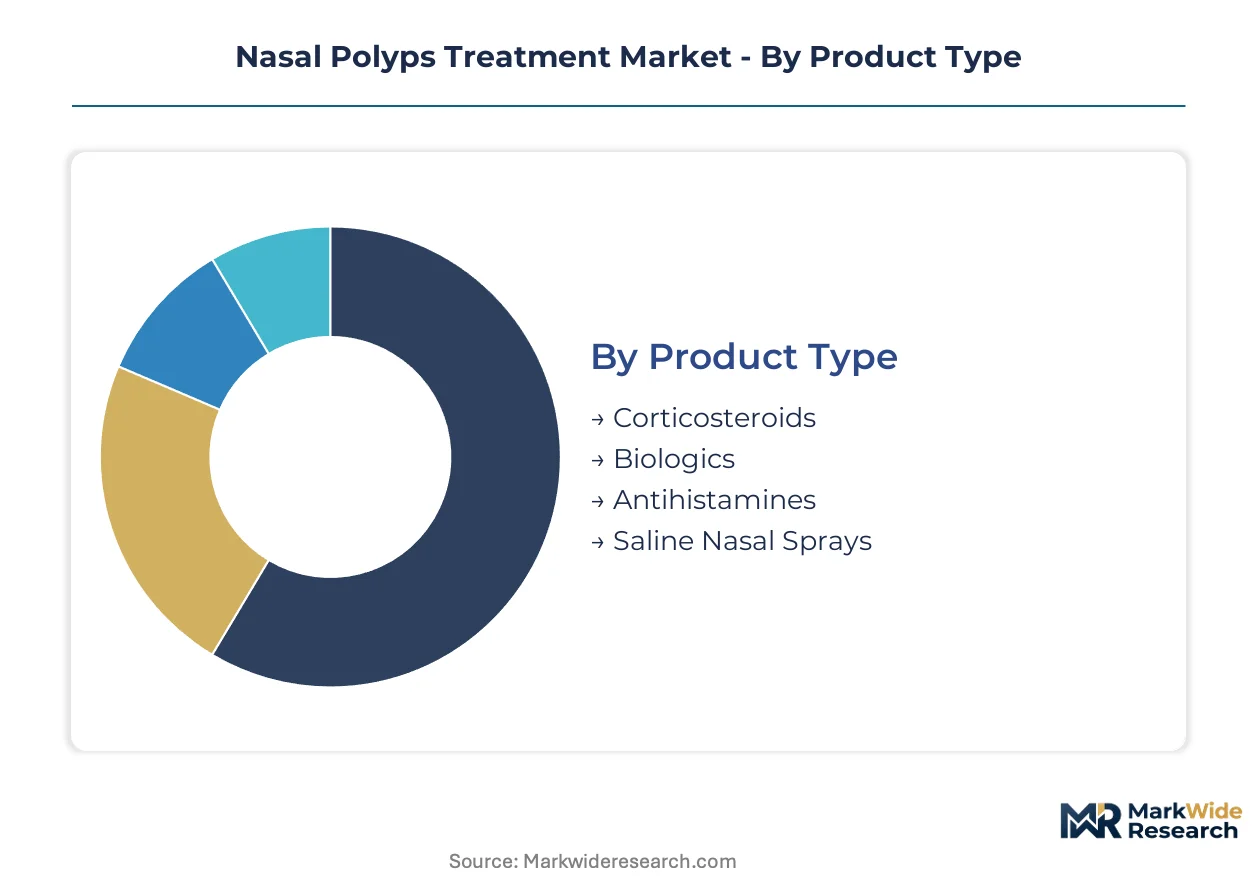
Segmentation in the nasal polyps treatment market reveals divergent capital requirements across pharmaceutical manufacturing, surgical infrastructure, and patient-administered delivery systems. Understanding these investment thresholds guides resource allocation for manufacturers, providers, and procurement stakeholders navigating the shift from procedural to biologic-first protocols.
Product Type:
Capital intensity peaks with biologics manufacturing, where monoclonal antibody production demands specialized fermentation capacity and cold-chain infrastructure. Corticosteroids require comparatively modest compounding investment.
- Corticosteroids:Synthetic glucocorticoid formulations dominate prescription volume through intranasal sprays, oral tablets, and implantable matrices. Demand concentrates in United States outpatient ENT clinics and German rhinology practices where generic prednisone and fluticasone propionate anchor step-therapy protocols before biologic escalation.
- Biologics:Monoclonal antibodies targeting IL-4Rα and IL-5 pathways command premium reimbursement but require substantial upstream investment in cell-line development, bioreactor capacity, and fill-finish infrastructure. United States academic medical centers and Japanese specialist hospitals drive adoption where prior authorization frameworks support eosinophil-guided patient selection.
- Antihistamines:Second-generation H1 antagonists serve adjunctive roles in allergic rhinitis overlap populations.
- Saline Nasal Sprays:Isotonic irrigation solutions represent minimal manufacturing barrier with commodity sourcing dynamics.
Most installed capacity flows through Corticosteroids. Expansion is steepest in Biologics.
Delivery Mode:
Volume distribution favors patient-administered routes, while value concentration tilts toward clinic-delivered injectables requiring trained personnel and specialized pharmacy infrastructure.
- Topical:Intranasal corticosteroid sprays and irrigations constitute the first-line intervention for mild-to-moderate disease, with patient self-administration reducing healthcare system burden. United States retail pharmacy networks and United Kingdom community health services distribute these formulations at scale.
- Injectable:Subcutaneous biologic delivery in dupilumab and mepolizumab requires cold-chain integrity and injection training, concentrating demand in hospital-based infusion centers and academic ENT clinics with pharmacy benefit manager contracts.
- Oral:Systemic corticosteroid bursts address acute exacerbations with burst-taper protocols.
- Nasal:Drug-eluting stents and sustained-release implants occupy procedural niches post-surgery.
Patient preference runs strongest for Topical self-administration. Injectable protocols gain share fastest in refractory populations.
End User:
Site-of-care economics reshape competitive dynamics, with ambulatory migration compressing hospital revenue per procedure while expanding addressable patient volume.
- Hospitals:Academic medical centers anchor complex surgical volume and biologic initiation protocols, with endoscopic sinus surgery and post-operative monitoring generating bundled reimbursement. German university hospitals and United States tertiary ENT centers concentrate interventional expertise and fellowship training programs.
- Clinics:Community otolaryngology practices manage maintenance biologic dosing and topical therapy titration, with United States integrated delivery networks deploying tele-ENT capabilities to extend specialist reach.
- Homecare:Self-administered topical regimens and patient-directed irrigation reduce clinical touchpoints.
- Ambulatory Surgical Centers:Office-based sinus procedures and stent placement capture migrating procedural volume.
Procedure volume concentrates in Hospitals. Patient touchpoint expansion is most rapid in Clinics.
Treatment Approach:
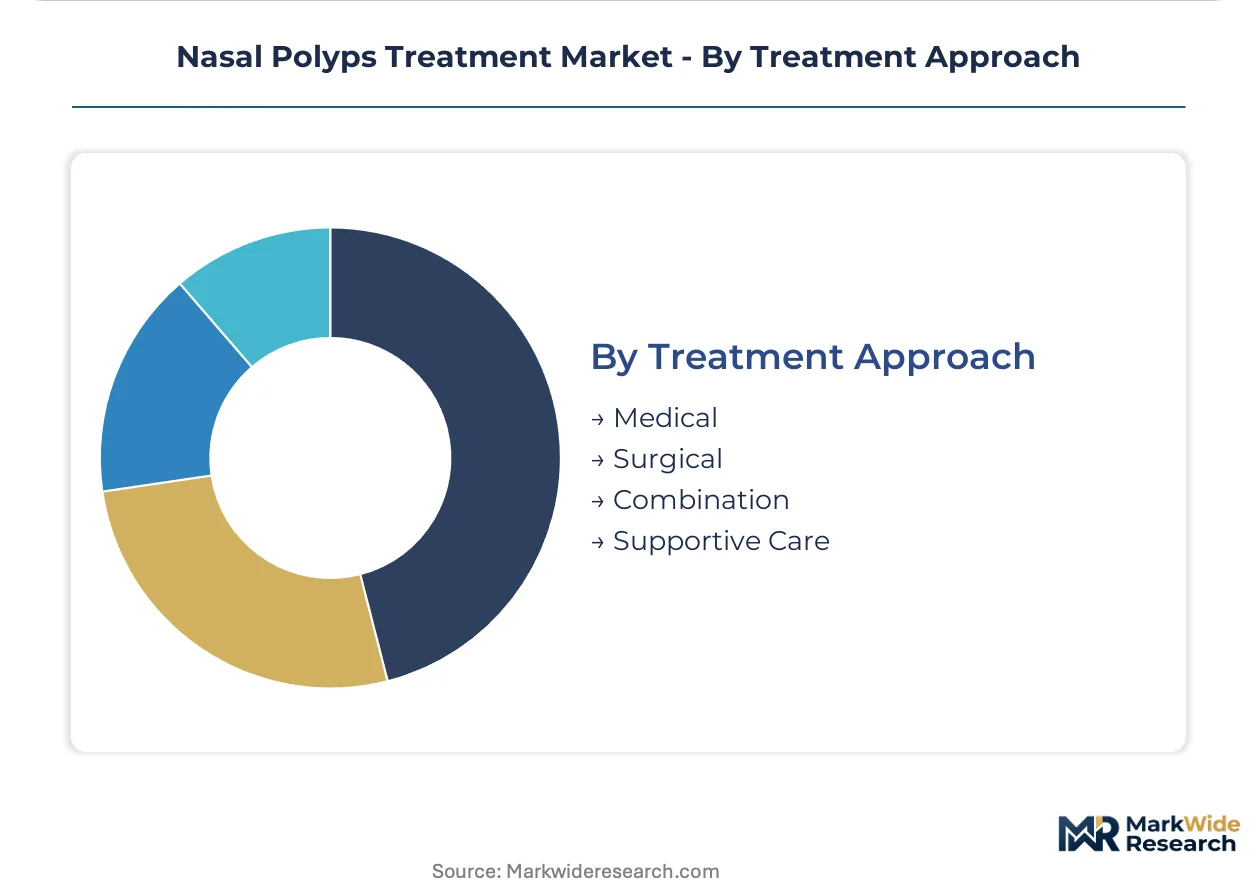
Protocol sequencing determines reimbursement capture, with medical-first algorithms delaying surgical intervention and biologic step-therapy restructuring provider economics.
- Medical:Pharmacological management through corticosteroids and biologics constitutes the dominant revenue stream, with FDA and EMA accelerated approval pathways compressing time-to-market for novel mechanisms. United States payer step-therapy requirements and German health technology assessment frameworks govern access sequencing.
- Surgical:Endoscopic sinus surgery retains indication for failed medical management, with Lund-Mackay CT grading and endoscopic polyp scores guiding intervention thresholds.
- Combination:Drug-eluting implant placement post-surgery bridges procedural and pharmaceutical revenue models.
- Supportive Care:Saline irrigation and environmental modification occupy preventive and maintenance niches.
Patient months flow predominantly through Medical protocols. Combination approaches are climbing fastest as device-drug convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Endoscopic sinus surgery techniques were pioneered and scaled in academic medical centers across the United States and Germany during the 1980s and 1990s, establishing the procedural foundation that biologic therapies now seek to displace.
United States
FDA accelerated approval pathways for IL-4Rα and IL-5 inhibitors have compressed development timelines for refractory chronic rhinosinusitis indications. Dense clustering of academic ENT centers in Boston, Philadelphia, and Houston concentrates specialist expertise and biologic injection training capacity. United States integrated delivery networks deploy pharmacy benefit manager contracts to govern step-therapy sequencing.
Germany
EMA centralized marketing authorization through the Committee for Medicinal Products for Human Use streamlines German market entry for eosinophil-targeted therapies. The Institute for Quality and Efficiency in Health Care adapts clinical benefit rating methodologies for biomarker-selected patient subsets. University hospitals in Munich and Heidelberg anchor interventional rhinology fellowship programs and device-drug combination trials.
Japan
METI reimbursement reforms for biologic therapies in chronic inflammatory conditions create favorable access conditions in an aging rhinology patient base. The Pharmaceuticals and Medical Devices Agency evaluates eosinophil-guided patient selection criteria for national health insurance listing. Specialist hospitals in Tokyo and Osaka concentrate maintenance biologic dosing infrastructure.
United Kingdom
National Institute for Health and Care Excellence technology appraisals govern National Health Service access to biologic step-therapy protocols. The Medicines and Healthcare products Regulatory Agency oversees post-market surveillance for drug-eluting sinus implants. ENT clinics in London deploy smartphone-based patient-reported outcome measures to satisfy value-based purchasing agreements.
France
ANSM marketing authorization timelines align with EMA centralized procedures for biologic indications in severe chronic rhinosinusitis. HAS clinical benefit ratings determine reimbursement tiers for monoclonal antibody therapies. Academic rhinology departments in Paris pilot real-world evidence platforms integrating electronic health record data for payer negotiations.
Nasal Polyps Treatment Market Competitive Environment
The competitive structure tilts toward biologic-focused pharmaceutical developers with respiratory commercial infrastructure. Two to three multinational conglomerates with established ENT specialist relationships anchor premium positioning, while mid-cap device manufacturers occupy procedural niches with implantable and drug-eluting technologies. Strategic moves concentrate on co-development partnerships for IL-4Rα pathway science and backward integration into active pharmaceutical ingredient production to secure cold-chain supply integrity.
Among biologic-centric developers, Sanofi, Regeneron Pharmaceuticals, and GlaxoSmithKline occupy positions defined by IL-4Rα and IL-5 mechanism differentiation. Sanofi represents the integrated pharmaceutical archetype with Dupixent positioning in corticosteroid-refractory populations. Regeneron Pharmaceuticals exemplifies the R&D-intensive biotech model through sustained pathway science investment. GlaxoSmithKline anchors the respiratory-specialist archetype via established commercial infrastructure and eosinophil-targeted mechanism deployment.
| Leading Market Players |
|---|
| Sanofi |
| Regeneron Pharmaceuticals |
| GlaxoSmithKline |
| Novartis |
| AstraZeneca |
| Merck & Co. |
| F. Hoffmann-La Roche |
| OptiNose |
| Intersect ENT |
| Others |
Value Chain & Pricing Dynamics
EMA centralized marketing authorization and FDA accelerated approval pathways for biologic therapies gate both qualified supply and premium-tier pricing access in the nasal polyps treatment market, concentrating manufacturing investment in facilities capable of cold-chain monoclonal antibody production while excluding commodity compounders from high-margin segments.
Pricing Analysis
Three-tier pricing structure across premium biologics, standard corticosteroids, and economy saline irrigations governs revenue capture in this market. Price differentiation rests on mechanism novelty and eosinophil biomarker stratification, with IL-4Rα pathway inhibitors commanding substantial premiums over generic fluticasone. Cost compression in oral corticosteroid tiers is intensifying because of prednisone commoditization and step-therapy mandates. Community ENT clinics exhibit highest price sensitivity due to prior authorization friction, while academic medical centers demonstrate lowest sensitivity given bundled reimbursement frameworks.
Supply Chain Analysis
Reverse-logistics networks for temperature-compromised biologics require specialized disposal protocols and cold-chain audit trails that extend operational complexity beyond standard pharmaceutical distribution. Active pharmaceutical ingredient production concentrates in Ireland, Singapore, and Switzerland, with fill-finish capacity clustering in Germany and the United States. Raw material dependencies include cell culture media, single-use bioreactor components, and pharmaceutical-grade excipients. Single-source vulnerability at API fermentation sites poses structural risk given regulatory inspection backlogs. Distribution runs through hospital-based specialty pharmacies and integrated delivery network formularies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nasal polyps treatment market functions as a stable compounder anchored by irreversible protocol migration from surgical-first to biologic step-therapy algorithms in refractory chronic rhinosinusitis populations.
For Market Incumbents: Anchor defensive positioning through backward integration into active pharmaceutical ingredient production to secure cold-chain supply integrity against single-site regulatory actions. Deepen entrenchment in United States academic medical centers by embedding injection training within rhinology fellowship curricula, countering emerging entrant challenges from tele-ENT platform developers seeking to disintermediate specialist access.
For New Entrants and Emerging Players: Enter via Japan's aging rhinology patient base where METI reimbursement reforms have created favorable access conditions for eosinophil-targeted mechanisms in an underpenetrated market. Target community hospital settings in the United States through remote nasal endoscopy interpretation partnerships, deploying virtual biologic injection training as the primary go-to-market angle to bypass established academic center relationships.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap device manufacturers with drug-eluting sinus implant portfolios because procedure volume migration to ambulatory settings creates consolidation opportunities for hybrid revenue models. Long-term viability centers on five-to-ten year positioning for combination device-drug convergence. Monitor EMA expanded indication framework decisions for IL-5 and IL-4Rα inhibitors as the primary inflection signal for biomarker-selected patient subset commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA biomarker-selected patient subset enrollment compresses health technology assessment timelines in Germany and France. |
| Manufacturing Scale-Up | Bioreactor capacity expansion in Ireland and Singapore secures monoclonal antibody supply against regulatory inspection bottlenecks. |
| Regulatory Approval Pathway | FDA accelerated approval for IL-4Rα indications reshapes prescriber decision trees in United States academic ENT centers. |
| Licensing Agreement | Co-development partnerships for IL-4Rα pathway science concentrate R&D investment among developers with respiratory commercial infrastructure. |
| Reimbursement Strategy | Patient-reported outcome measure integration satisfies United Kingdom National Health Service value-based purchasing contract requirements. |
Study Parameters
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers grounded qualitative insights, validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up and top-down triangulation reconciled manufacturer shipment data with payer utilization records across the analysis window.
Bottom-up modeling anchored volume projections to patient population epidemiology, treatment line progression rates, and biologic penetration curves by eosinophil status. Segmentation dimensions included treatment approach, delivery mode, product type, and regional regulatory cluster. CAGRs were derived from fitted adoption S-curves incorporating step-therapy removal timelines and health technology assessment influence coefficients.
Inputs from electronic health record platforms and integrated delivery network pharmacy benefit managers were available through the study window; gaps in real-world evidence completeness for community ENT clinic settings introduce uncertainty bands around biologic penetration forecasts. Practitioners should monitor FDA inspection classification outcomes at Irish and Singapore API facilities and EMA Committee for Medicinal Products for Human Use opinion timelines for expanded chronic rhinosinusitis indications as early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Over-The-Counter (OTC) Hearing Aids Market
ENT
ENT Laser Devices Market
ENT
Acute Sinusitis Market
ENT
Europe Speech Therapy Market
ENT
US Hearing Aids Market
ENT
Global Sinusitis Treatment Market
ENT
Denmark Hearing Aids Market
ENT
Nasal Sampling Lines Market
ENT
Custom Hearing Aids Market
ENT
Global ENT Workstations Market
ENT
ENT Disorder Treatment Market
ENT
Ear Health Market
ENT
Global Pediatric Hearing Aids Market
ENT
Laryngeal Papillomatosis Treatment Market
ENT
Europe Hearing Aids Market
ENT
Hearing Implants Market