
 Ear Health Market | 2026-2036
Ear Health Market Size, Share, and Industry Trends Forecast 2026-2036
Ear Health Market Foresight
Audiology centers is consolidating as the dominant end-use channel for advanced diagnostic and fitting services. Sonova Holding AG leverages its integrated retail-audiology network across multiple continents to sustain direct consumer access. Demant A/S anchors its position through R&D intensity in digital signal processing platforms. GN Store Nord A/S differentiates via wireless connectivity protocols that stream audio directly from consumer electronics.
Ear health encompasses the diagnosis, treatment, and management of hearing impairment, vestibular disorders, and otologic conditions through prosthetic, pharmaceutical, and protective interventions. Hearing aids incorporate digital signal processors with 16-24 bit resolution and adaptive noise reduction algorithms to restore speech intelligibility for sensorineural loss. Cochlear implants represent the fastest-growing product category as bilateral implantation expands pediatric candidacy criteria. The audiology centers end-user segment captures premium margin pools due to mandatory professional fitting and ongoing rehabilitation services.
The FDA oversees OTC hearing aid regulations under the 2022 final rule enabling direct-to-consumer sales for mild-to-moderate impairment, while the EMA's Medical Device Regulation classifies active implantable devices under stricter conformity assessment pathways. HIPAA privacy requirements govern patient audiological data flows in the United States, creating compliance costs for connected hearing instruments. Stakeholders must monitor how reimbursement policy divergence between public and private payers reshapes channel economics for device manufacturers and service providers.
Market Dynamics
The FDA's 2022 OTC Hearing Aid Act has bifurcated the ear health market into professional audiology services and direct-to-consumer channels, forcing manufacturers to reconfigure distribution strategies and pricing architectures simultaneously.
Growth Catalysts
- OTC Hearing Aid Act:FDA regulations enabling direct-to-consumer sales for mild-to-moderate impairment unlock pharmacy and e-commerce channels previously restricted to licensed dispensers.
- Pediatric bilateral candidacy expansion:Cochlear implant manufacturers benefit from relaxed age thresholds and expanded insurance coverage for simultaneous bilateral procedures in early intervention programs.
- Medicare Advantage hearing benefits:United States payers increasingly bundle hearing aid coverage into supplemental plans, driving utilization among beneficiaries aged sixty-five and older.
Market Restraints
- Semiconductor supply concentration:Digital signal processors and MEMS microphones depend on fabrication capacity concentrated in Taiwan and South Korea, exposing hearing instrument manufacturers to allocation delays.
- Professional fitting dependency:Cochlear implants and high-power hearing aids require surgical intervention and audiologist calibration, limiting addressable market expansion regardless of product innovation.
- Reimbursement fragmentation:Medicaid coverage for hearing services varies by state in the United States, creating patchwork access that suppresses demand in non-expansion jurisdictions.
Strategic Opportunities
- Remote programming platforms:Tele-audiology enables real-time device adjustment without clinic visits, appealing to rural populations and mobility-limited users in Australia and Canada.
- Consumer electronics convergence:Hearing aids incorporating Bluetooth Low Energy and Auracast broadcast audio directly from smartphones and public venue systems, differentiating premium tiers.
- Occupational hearing conservation mandates:OSHA regulations in the United States and EU directives under the Physical Agents Directive drive enterprise procurement of protective monitoring devices for industrial workforces.
Industry Challenges
- Audiologist workforce scarcity:Clinical training pipeline constraints in the United States and United Kingdom create bottlenecks for fitting capacity expansion even where device supply exists.
- Legacy system integration:Hospital ENT departments and audiology clinics face capital requirements to interconnect new connected hearing instruments with existing electronic health record architectures compliant with HIPAA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ear Health Market |
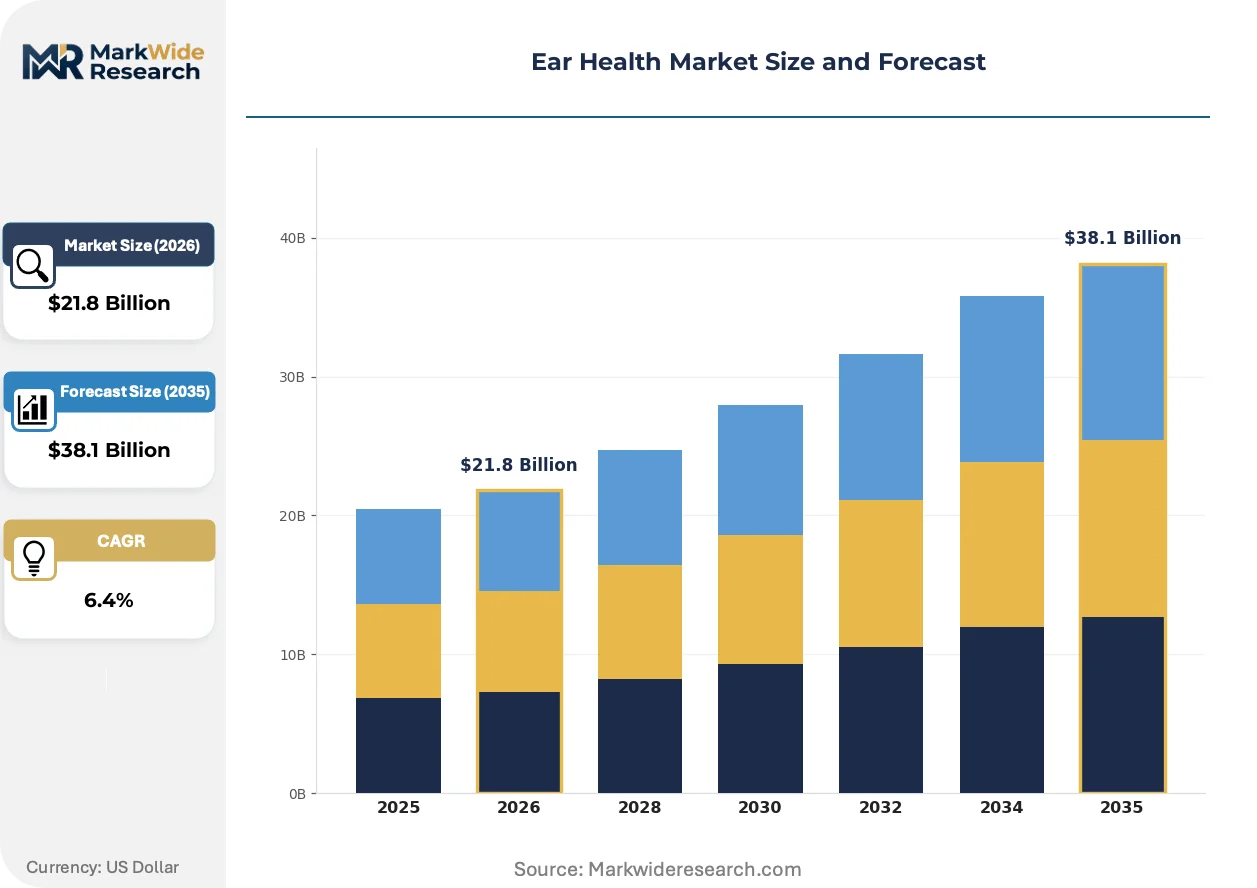
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $38.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hearing Aids, Ear Wax Removal, Cochlear Implants, Ear Plugs End User: Individuals, Hospitals, Clinics, Audiology Centers Distribution Channel: Online Stores, Pharmacies, Medical Supply Stores, Direct Sales Technology: Analog, Digital, Wireless, Adaptive |
| Companies Covered | Sonova Holding AG, Demant A/S, GN Store Nord A/S, WS Audiology, Cochlear Limited, Starkey Hearing Technologies, MED-EL, Widex A/S, Rion Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ear Health Market Shifts & Advancements
Deep learning architectures are migrating from cloud servers to edge processors within hearing instruments, enabling real-time acoustic scene classification without latency or privacy compromises.
On-device neural networks are absorbing environmental sound processing tasks previously executed through smartphone tethering. Audiology centers and direct-to-consumer brands alike deploy these chips to differentiate premium product tiers. The shift is compressing reliance on auxiliary hardware while extending battery life targets.
EMA's Medical Device Regulation imposes stricter conformity assessment pathways for active implantable devices including cochlear implants and bone-anchored systems. Manufacturers must maintain quality management systems and clinical evidence portfolios that exceed previous medical device directives. Pediatric implantable device categories face the steepest compliance cost escalation.
Pharmacy retailers and big-box electronics chains are capturing hearing aid transactions previously funneled through independent audiology practices. Consumers in the United States increasingly self-select OTC devices based on online diagnostic tools and return policies rather than professional recommendation. This channel rotation pressures incumbents to develop white-label supply relationships or direct-to-consumer sub-brands.
Ear Health Market Segmentation
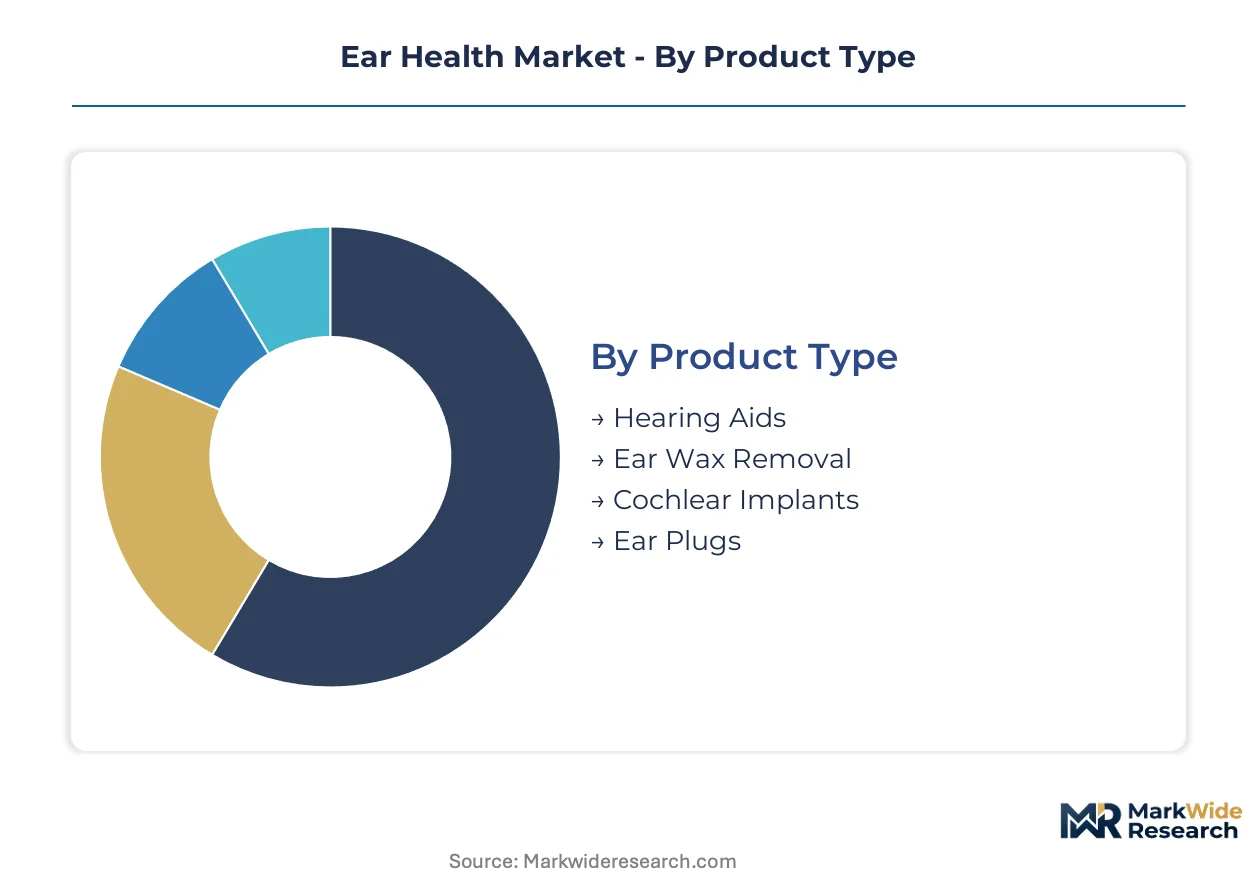
Ear health market segmentation reveals divergent margin structures across product categories and channel economics. Professional fitting requirements create premium capture opportunities in audiology centers while OTC pathways unlock volume expansion in pharmacy and digital retail.
Product Type:
Hearing aids dominate unit volume while cochlear implants command the steepest price premiums per procedure.
- Hearing Aids:Digital signal processors with 16-24 bit resolution and adaptive noise reduction algorithms restore speech intelligibility for sensorineural loss. Demand concentrates in the United States where Medicare Advantage plans increasingly bundle hearing benefits for beneficiaries aged sixty-five and older.
- Cochlear Implants:Active implantable devices requiring surgical intervention and audiologist calibration deliver direct neural stimulation for severe-to-profound hearing loss. Bilateral pediatric candidacy expansion in early intervention programs drives the steepest expansion trajectory among all product categories.
- Ear Wax Removal:Manual and irrigation-based systems address cerumen impaction in primary care and home settings.
- Ear Plugs:Passive and electronic attenuation devices serve occupational hearing conservation mandates under OSHA regulations.
Mature deployment sits with hearing aids. Newer deployment is concentrated in cochlear implants.
End User:
Channel selection determines pricing architecture and service bundling intensity.
- Audiology Centers:Professional fitting networks capture premium margin pools through mandatory calibration, ongoing rehabilitation services, and device maintenance contracts. United States audiology practices consolidate as dominant channels for advanced diagnostic and fitting services despite workforce scarcity constraints.
- Individuals:Direct-to-consumer purchases accelerate following FDA OTC Hearing Aid Act implementation, with pharmacy retailers and big-box electronics chains capturing transactions previously funneled through independent practices.
- Hospitals:ENT departments perform surgical implantation of cochlear and bone-anchored devices under hospital reimbursement frameworks.
- Clinics:Outpatient settings provide initial screening and referral pathways to specialized audiology services.
Volume concentration sits with individuals. Premium capture concentrates in audiology centers.
Distribution Channel:
Channel bifurcation intensifies as regulatory pathways diverge between professional and self-fit modalities.
- Pharmacies:OTC hearing aid distribution expands through national pharmacy chains and independent drugstores following FDA final rule implementation for mild-to-moderate impairment devices.
- Online Stores:E-commerce platforms enable direct-to-consumer sales with self-administered hearing assessments and return policies replacing professional recommendation.
- Medical Supply Stores:Durable medical equipment distributors serve institutional procurement and Medicare billing requirements.
- Direct Sales:Manufacturer-owned retail networks and audiology partnerships sustain premium brand positioning and service integration.
Legacy deployment sits with medical supply stores. Channel expansion concentrates in online stores.
Technology:
Signal processing architecture determines device functionality and battery performance trade-offs.
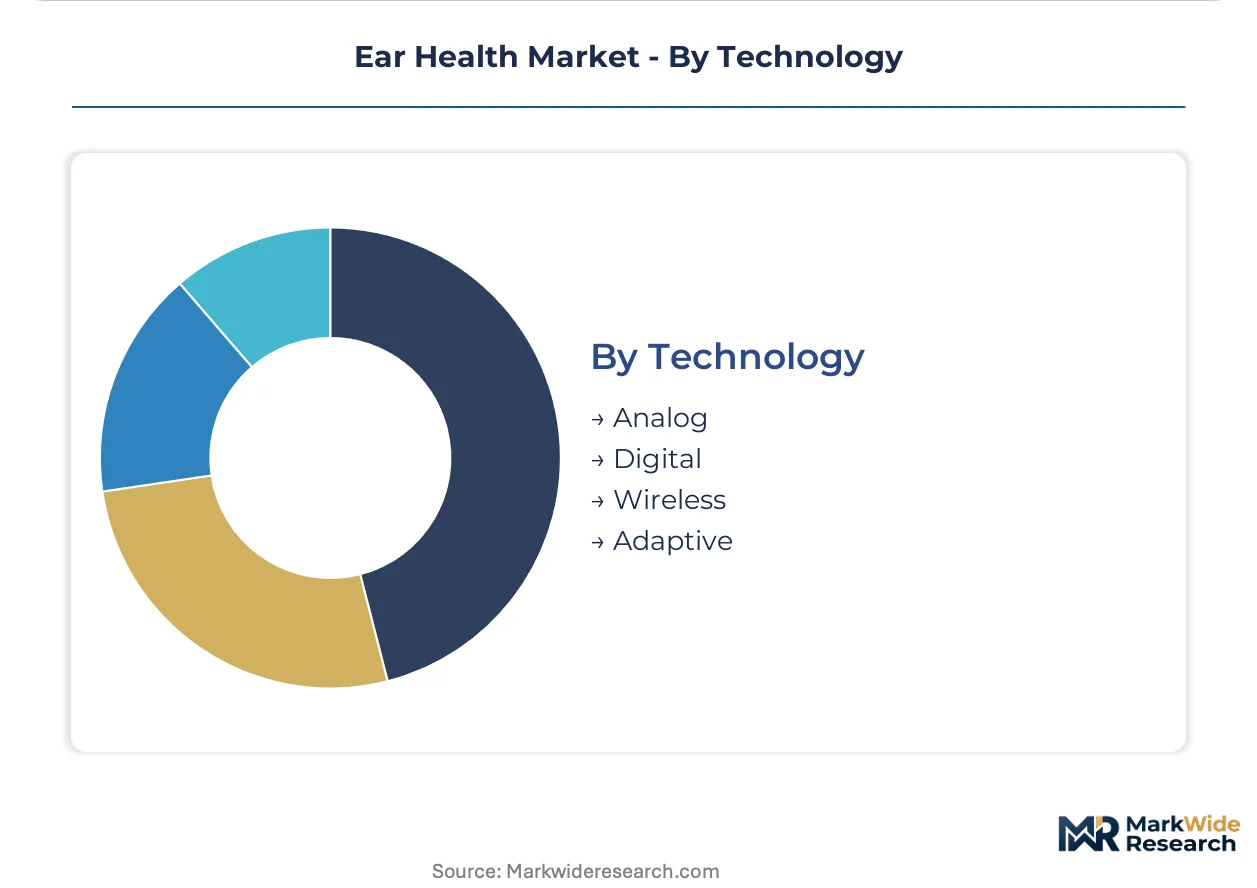
- Digital:DSP platforms with real-time acoustic scene classification enable adaptive noise reduction and directional microphone steering without latency.
- Wireless:Bluetooth Low Energy and Auracast broadcast protocols stream audio directly from smartphones and public venue systems, differentiating premium product tiers.
- Adaptive:On-device neural networks absorb environmental sound processing tasks previously executed through smartphone tethering, extending battery life targets.
- Analog:Basic amplification circuits persist in economy-tier devices and certain occupational hearing protection applications.
Legacy deployment sits with analog. Technology migration concentrates in adaptive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device fabrication concentrates in East Asian semiconductor clusters while consumption tilts toward aging populations in Western healthcare systems. Regulatory divergence between FDA pathways in the United States and EMA frameworks in Europe forces manufacturers to maintain parallel compliance architectures. Distribution economics vary sharply by reimbursement density and audiology workforce availability.
United States
Medicare Advantage plans bundle hearing benefits for beneficiaries aged sixty-five and older, driving utilization in Florida and Arizona retirement corridors. FDA OTC Hearing Aid Act implementation unlocks pharmacy and e-commerce channels for mild-to-moderate impairment devices. The Minneapolis-St. Paul corridor anchors domestic audiology service networks and hearing instrument R&D facilities.
Germany
Statutory health insurance mandates hearing aid coverage with fixed reimbursement schedules, compressing manufacturer margins while guaranteeing volume. EMA Medical Device Regulation imposes stricter conformity assessment for active implantable devices than previous directives. The Munich-Düsseldorf corridor concentrates ENT surgical centers and cochlear implant fitting capacity.
Japan
PMDA approval pathways for active implantable devices require domestic clinical trials, extending time-to-market for foreign manufacturers. METI promotes hearing healthcare access through municipal screening programs for school-age children. The Tokyo-Osaka corridor hosts the densest concentration of audiology clinics and cochlear implant rehabilitation centers in Asia.
Australia
Tele-audiology platforms expand service reach into rural Queensland and Western Australia where audologist density falls below urban benchmarks. TGA regulation aligns with EMA MDR frameworks for implantable device classifications. The Sydney-Melbourne corridor dominates cochlear implant surgical volume and pediatric early intervention program enrollment.
United Kingdom
NHS England procurement frameworks compress hearing aid pricing through centralized tendering while maintaining professional fitting requirements. MHRA post-Brexit regulatory autonomy permits divergence from EU MDR implementation timelines. The London-Manchester corridor concentrates private audiology chains competing with NHS services for middle-market consumers.
Ear Health Market Competitive Landscape
Top-tier vendors anchor premium implantable and advanced hearing instrument segments, while mid-tier specialists populate OTC self-fit and economy amplification tiers. The vendor base stratifies across integrated retail-audiology networks, component technology licensors, and pure-play manufacturers. Three archetypes dominate: vertically integrated hearing healthcare conglomerates, semiconductor-focused signal processing platform developers, and surgical implant specialists. Competitive dynamics center on audiology network acquisition and adaptive noise reduction algorithm licensing.
Among Swiss and Danish integrated healthcare groups, Sonova Holding AG and Demant A/S exemplify the retail-audiology network archetype, while GN Store Nord A/S occupies a position emphasizing wireless connectivity protocols. These three entities represent the tier-one competitive set, with Cochlear Limited and MED-EL anchoring the implantable device specialization vector. The competitive map rewards entities controlling both device manufacturing and professional fitting channel access.
| Leading Market Players |
|---|
| Sonova Holding AG |
| Demant A/S |
| GN Store Nord A/S |
| WS Audiology |
| Cochlear Limited |
| Starkey Hearing Technologies |
| MED-EL |
| Widex A/S |
| Rion Co., Ltd. |
| Others |
Supply & Pricing Matrix
Professional fitting mandates versus self-fit OTC pathways bifurcate pricing architectures and supply chain configurations across the ear health market. Audiology centers command premium capture through bundled calibration and rehabilitation services, while pharmacy and e-commerce channels compress margins through volume-driven OTC transactions.
Pricing Analysis
Short lead-time premiums attach to audiology center fittings with same-day DSP programming, while spot inventory in retail channels trades at discount. A three-tier pricing structure across premium, standard, and economy levels separates implantable surgical devices from programmable digital aids and basic analog amplifiers. Price differentiation rests on certification grade—FDA Class II versus OTC self-fit—and after-sales service bundling. Cost compression in the OTC tier intensifies because pharmacy chains negotiate national formulary placement. Individual consumers exhibit highest price sensitivity, whereas hospital ENT departments demonstrate lowest sensitivity due to reimbursement pass-through.
Supply Chain Analysis
Regional distribution centers in Minneapolis-St. Paul and Munich-Düsseldorf anchor hub-and-spoke patterns for audiology network replenishment. Fabrication concentrates in Taiwan and South Korea for DSP chips, with final assembly distributed across China, Vietnam, and Mexico. Raw material dependencies include rare earth magnets for cochlear implant electrodes, lithium polymer cells for rechargeable hearing aids, and medical-grade silicones for earmold production. Single-source vulnerability in MEMS microphone supply from Taiwanese foundries exposes manufacturers to allocation disruptions. Distribution runs through manufacturer-owned retail networks for premium tiers and pharmacy wholesalers for OTC devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Audiologist workforce scarcity props pricing for professional fitting services, constraining capacity expansion regardless of device supply availability. This supply-constrained dynamic favors incumbents controlling integrated service networks.
For Market Incumbents: Deploy audiology network acquisition as the primary lever to lock channel access against OTC disintermediation. Consolidate independent practices in Florida and Arizona retirement corridors to defend service revenue pools. Backward integration into DSP chip sourcing mitigates Taiwan foundry allocation risk. Certification investment in FDA de novo pathways for adaptive neural processing preserves premium tier positioning. For New Entrants and Emerging Players: Rural Medicare beneficiaries underserved by audiology density represent the most penetrable buyer archetype for tele-audiology platforms. White-label supply to pharmacy chains captures OTC volume without brand buildout costs. Occupational hearing conservation mandates under OSHA regulations open enterprise procurement channels bypassing consumer marketing spend. Direct-to-consumer sub-brand positioning with self-administered hearing assessments enables market entry without clinical infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated healthcare conglomerates seeking audiology network scale. Long-term viability favors entities with captive R&D in edge AI processing and bilateral implant surgical expertise. Acquisition target archetype: mid-cap cochlear implant specialists with pediatric candidacy expansion protocols. Watch FDA guidance on remote programming as the inflection signal for tele-audiology platform valuation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | De novo pathways for adaptive neural processing algorithms secure premium device classification. |
| CE Marking Pathway | EMA MDR conformity assessment enables European commercialization of active implantable systems. |
| Hospital System Partnership | ENT department alliances secure surgical implant volume through bundled reimbursement contracts. |
| Software Companion Development | Remote programming applications extend service reach into rural markets with audiologist scarcity. |
| Reimbursement Strategy | Medicare Advantage hearing benefit integration drives utilization among aged sixty-five-plus beneficiaries. |
Research Methodology
Multi-period observation of FDA 510(k) clearance volumes and Medicare Advantage hearing benefit adoption anchored the trend analysis, supplemented by interviews with audiology practice owners, biomedical engineers at implant manufacturers, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from FDA 510(k) premarket notification database, CMS Medicare Advantage plan benefit filings, hospital procurement databases, and SEC 10-K disclosures from listed device manufacturers. Bottom-up patient flow modeling and top-down reimbursement expenditure analysis provided triangulation.
Segment-weighting across product type, end user, distribution channel, and technology dimensions structured the analytical framework. CAGRs were derived from regression analysis of historical procedure volumes and reimbursement rate trajectories across the projection horizon. Modeled inputs included bilateral pediatric implant candidacy expansion rates, OTC hearing aid pharmacy channel penetration curves, and audiology workforce graduation pipeline data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA regulatory shifts, semiconductor supply allocation disruptions, and Medicare reimbursement policy revisions. Outputs reflect documented assumptions regarding audiology workforce growth and OTC self-fit adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
US Hearing Aids Market
ENT
Global ENT Workstations Market
ENT
ENT Devices Market
ENT
Electrolarynx Market
ENT
Nasal Sampling Lines Market
ENT
Laryngeal Papillomatosis Treatment Market
ENT
Head and Neck Squamous Cell Carcinoma Market
ENT
Interventional ENT Devices Market
ENT
Acute Sinusitis Market
ENT
Surgical ENT Devices Market
ENT
Global Acute Otitis Media Treatment Market
ENT
Europe Hearing Aids Market
ENT
Denmark Hearing Aids Market
ENT
Audiology Devices Market
ENT
Hearing Loss Disease Treatment Market
ENT
Europe Speech Therapy Market