
 Europe Hearing Aids Market | 2026-2036
Europe Hearing Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hearing Aids Market Foresight
Aftermarket service revenue is tilting toward software-enabled fitting adjustments and remote calibration platforms. GN Store Nord A/S leverages its ReSound brand strength across Nordic audiology channels. Sonova Holding AG anchors premium digital signal processing through its Phonak and Unitron divisions. WS Audiology competes aggressively on programmable technology tiers across mid-market European retail chains.
Hearing aids are electroacoustic wearable devices that amplify sound for individuals with sensorineural or conductive hearing loss, typically incorporating digital signal processors with 16-24 bit resolution, multiple compression channels, and directional microphone arrays to improve speech-in-noise performance. Receiver-in-Canal designs now lead volume shipments across European markets due to their acoustic advantages and cosmetic appeal. Behind-the-Ear configurations retain dominance in pediatric and severe-to-profound loss applications where power output and durability matter most. Digital technology platforms command the majority of value pools, while analog segments persist only in price-sensitive subsidy programs.
The EU Medical Device Regulation (MDR) and CE marking framework govern market access, with notified bodies now requiring expanded clinical evidence for active implantable devices. Germany's KBA-equivalent device regulator, the Federal Institute for Drugs and Medical Devices (BfArM), coordinates with EMA guidance on software-as-medical-device classifications for AI-powered hearing algorithms. France's ANSM enforces post-market surveillance protocols that influence warranty and service contract structures. Stakeholders must monitor how MDR transition timelines reshape competitive entry barriers for programmable and hybrid technology tiers.
Market Dynamics
The EU Medical Device Regulation is compressing certification timelines and forcing manufacturers to consolidate clinical evidence portfolios ahead of notified body capacity constraints.
Growth Catalysts
- Aging demographics:Germany, France, and Italy are expanding the senior end-user pool. Audiology clinics in these markets report rising appointment volumes for age-related sensorineural loss.
- MDR framework harmonization:The EU Medical Device Regulation is standardizing quality benchmarks across member states. Manufacturers benefit from single-market access rather than fragmented national approvals.
- Digital signal processing:16-24 bit resolution chips with multi-channel compression are improving speech-in-noise performance. This technical leap expands addressable loss severities.
Market Restraints
- Notified body bottlenecks:EU MDR transition has reduced active certification bodies by two-thirds. Extended audit queues are delaying product launches by 12-18 months.
- Semiconductor input volatility:MEMS microphone and DSP chip supply concentrates in East Asian foundries. European manufacturers face allocation risk for advanced audio components.
- Subsidy program fragmentation:Reimbursement rates vary across Germany's statutory health insurers, France's CPAM, and Italy's regional health systems. Price ceilings compress margin flexibility.
Strategic Opportunities
- Remote calibration platforms:Software-enabled fitting adjustments bypass clinic capacity constraints. Nordic markets with dispersed populations are piloting tele-audiology protocols.
- Pediatric segment expansion:Early intervention mandates in France and Germany are lowering fitting ages. Behind-the-Ear configurations for severe-to-profound pediatric loss command premium positioning.
- AI algorithm classification:Germany's BfArM is clarifying software-as-medical-device pathways for machine-learning hearing aids. First-movers gain regulatory precedent.
Industry Challenges
- Clinical evidence generation:EU MDR requires expanded patient follow-up data for active implantable devices. Manufacturers must fund multi-year post-market studies without guaranteed reimbursement.
- Legacy system integration:France's ANSM post-market surveillance protocols demand real-world performance tracking. Existing ERP systems require costly retrofitting for automated adverse event reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hearing Aids Market |
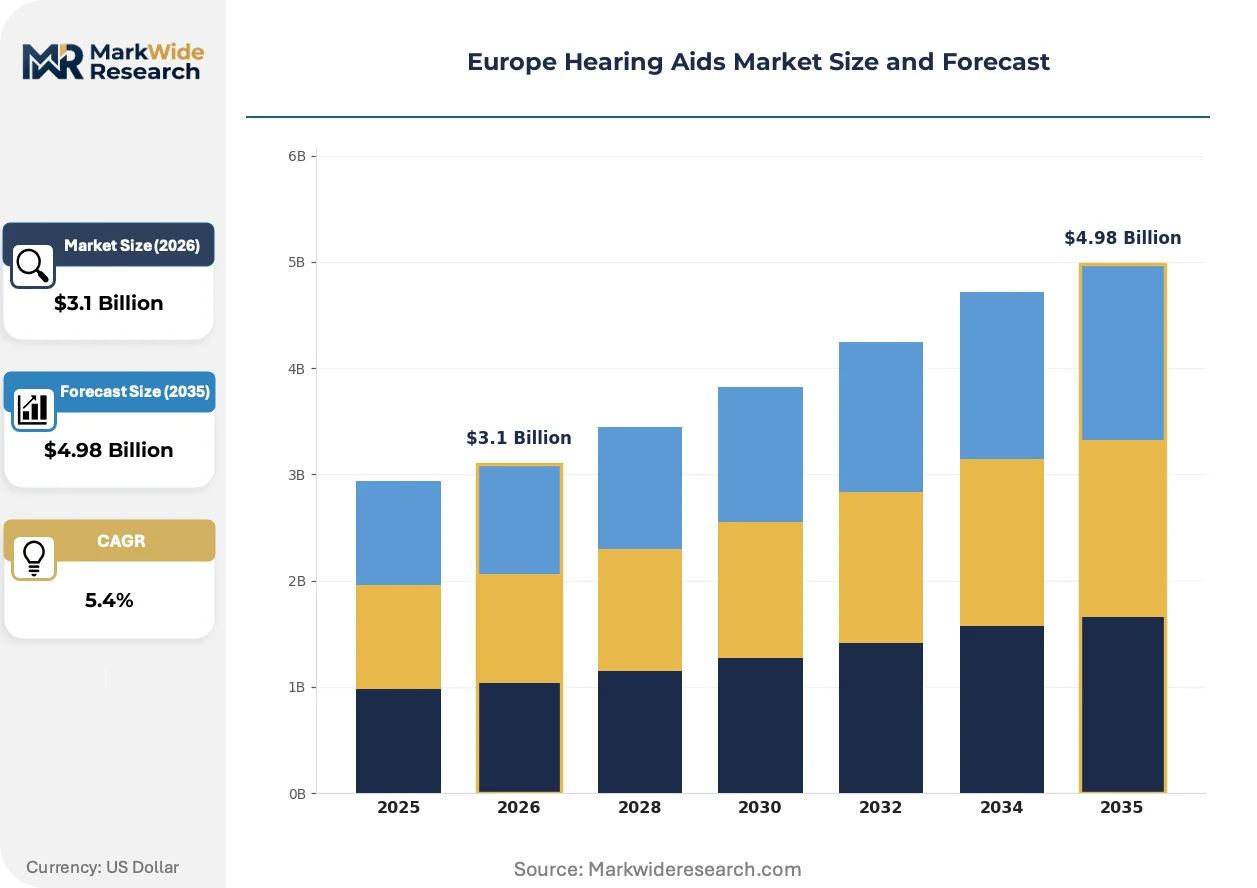
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Behind-the-Ear, In-the-Ear, Receiver-in-Canal, Completely-in-Canal Technology: Analog, Digital, Programmable, Hybrid End User: Adults, Seniors, Pediatric, Clinical Settings Distribution Channel: Retail Stores, Online Platforms, Audiology Clinics, Hospitals |
| Companies Covered | GN Store Nord A/S, Cochlear Limited, Sonova Holding AG, MED-EL, Amplifon S.p.A., Demant A/S, Starkey Hearing Technologies, Eargo, Inc., WS Audiology, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hearing Aids Market Shifts & Advancements
Signal processing architectures and distribution models are undergoing simultaneous transformation, with software-defined functionality displacing hardware-centric value capture.
Deep neural network noise suppression is migrating from research prototypes to commercial firmware releases. German audiology chains are adopting these algorithms for high-frequency hearing loss profiles. The technology is migrating from premium tier exclusivity toward mid-market standardization, compressing R&D amortization windows.
France's ANSM is tightening post-market surveillance protocols for AI-enabled hearing devices. Manufacturers must now submit algorithm update logs as part of periodic safety reports. Pediatric and severe-loss segments face the steepest compliance burden due to higher clinical risk classifications.
Subscription-based hearing care is displacing outright device ownership in Netherlands and Denmark. Retail chains bundle hardware, fitting services, and remote adjustments into monthly fees. This model concentrates most visibly in urban markets where clinic density supports rapid follow-up scheduling.
Europe Hearing Aids Market Segmentation
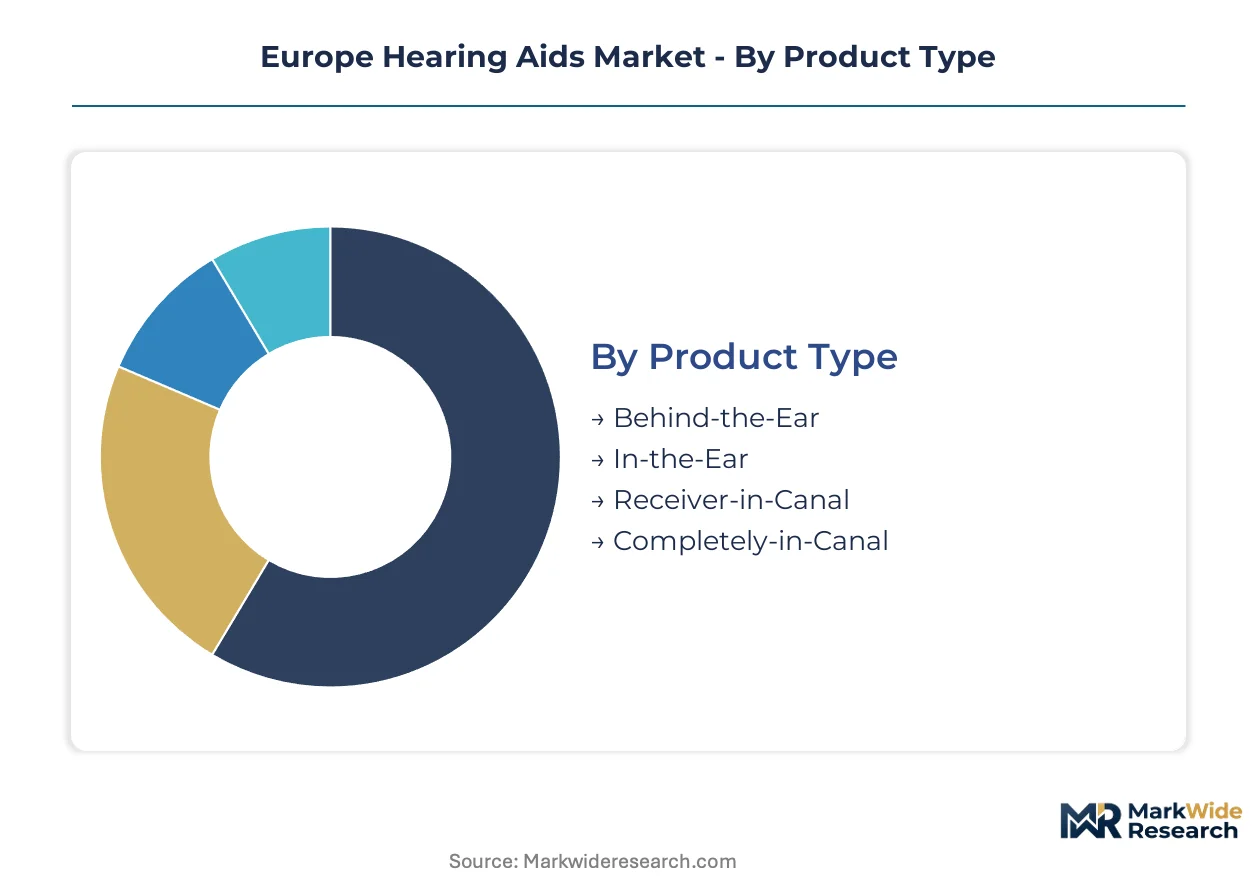
Hearing aid segmentation in Europe reflects divergent replacement cycles across device architectures. Premium digital platforms turn over every 4-5 years as firmware obsolescence accelerates, while basic analog units persist 7-10 years in subsidy-dependent patient pools.
Product Type:
Replacement velocity varies sharply by acoustic architecture and patient demographics, with cosmetic preference driving shorter cycles in invisible formats versus durability-focused pediatric applications.
- Receiver-in-Canal:Miniaturized receiver positioned directly in the ear canal connects via thin electrical wire to a behind-the-ear processor housing. German and Dutch audiology chains report this configuration dominating new fittings among working-age adults prioritizing discretion. The acoustic advantage of shorter sound path drives preference for moderate-to-severe sensorineural loss profiles.
- Behind-the-Ear:Traditional architecture houses all electronics in a crescent-shaped case resting behind the pinna, with sound delivered through custom earmold tubing. France's pediatric early intervention mandates and German severe-to-profound loss segments anchor demand where power output and physical durability outweigh cosmetic concerns.
- In-the-Ear:Custom shells fabricated from ear impressions contain all components within the concha bowl.
- Completely-in-Canal:Deep-fitted micro-devices sit nearly invisible within the ear canal aperture.
Behind-the-Ear anchors the volume base while Receiver-in-Canal gains share at the steepest rate.
Technology:
Cost tier stratification separates programmable AI-enabled platforms from fixed-function analog alternatives, with reimbursement ceilings determining accessible tiers in Italy's regional health systems versus Germany's statutory insurance.
- Digital:16-24 bit resolution signal processors with multi-channel compression and directional microphone arrays dominate commercial value pools. BfArM software-as-medical-device classifications for AI-powered algorithms are accelerating firmware update cycles in premium German retail channels.
- Programmable:Computer-adjustable parameters allow audiologists to fine-tune frequency response curves without hardware replacement. Nordic tele-audiology pilots favor this tier for remote calibration workflows serving dispersed rural populations.
- Analog:Fixed amplification circuits with basic volume control persist in price-sensitive subsidy programs.
- Hybrid:Mixed-signal architectures combine analog front-ends with digital processing backends.
Digital platforms command the installed base while Programmable climbs fastest as remote service models mature.
End User:
Patient lifecycle value concentrates in senior segments with age-related progressive loss, though pediatric mandates in France and Germany create captive long-term fitting relationships.
- Seniors:Age-related sensorineural degeneration in Germany, France, and Italy's expanding elderly populations drives appointment volume growth in independent audiology practices. Bilateral fitting norms and 4-5 year replacement cycles sustain recurring revenue streams.
- Pediatric:Early intervention mandates lower fitting ages for congenital and early-acquired losses, with Behind-the-Ear durability requirements dominating severe-to-profound cases. ANSM post-market surveillance protocols impose steepest compliance burdens on this highest-risk classification.
- Adults:Working-age patients with noise-induced or progressive genetic loss.
- Clinical Settings:Hospital-based fittings for acute-onset loss and post-surgical rehabilitation.
Seniors anchor volume economics while Pediatric delivers the longest patient-retention horizons.
Distribution Channel:
Channel margin structure reflects service intensity, with clinic-based professional fitting commanding premium positioning against self-fitting online alternatives facing MDR compliance uncertainty.
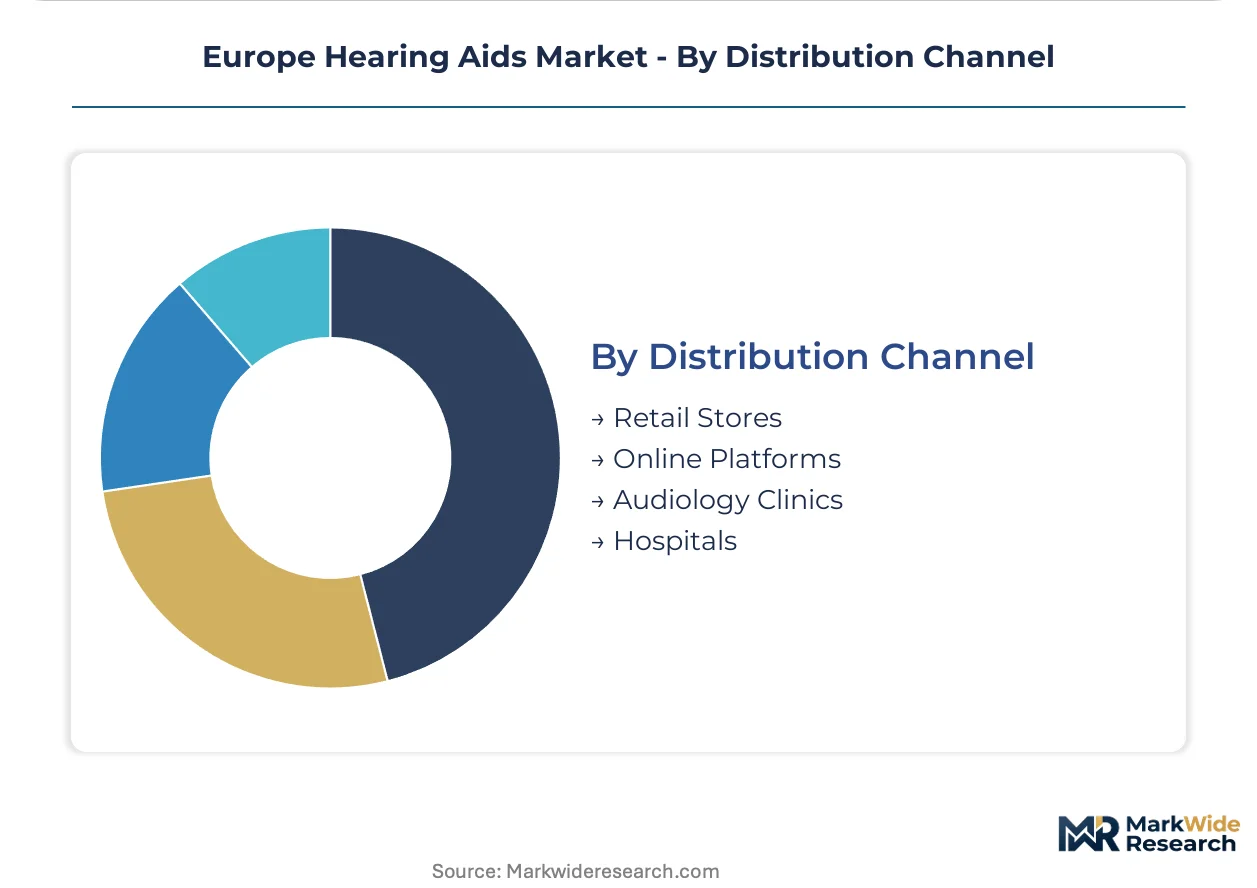
- Audiology Clinics:Professional diagnostic and fitting services bundled with device sales dominate Germany's reimbursement-integrated model. Independent practices and retail chains employ real-ear measurement verification and follow-up adjustments that sustain higher average selling prices.
- Retail Stores:Mid-market European chains compete aggressively on programmable technology tiers with standardized fitting protocols. Netherlands and Denmark subscription models concentrate in urban locations supporting rapid follow-up scheduling.
- Online Platforms:Direct-to-consumer remote screening and self-fitting applications face evolving CE marking requirements under MDR software-as-medical-device interpretations.
- Hospitals:Acute care and ENT specialist referral pathways for sudden hearing loss and surgical candidacy assessment.
Audiology Clinics defend the value core while Retail Stores expand most quickly through subscription bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across European hearing aid markets, with Scandinavian subsidy models minimizing out-of-pocket costs while Southern European regional health systems impose heavier patient contributions. Germany's statutory insurance integration creates the continent's most volume-elastic demand environment.
Germany
Bilateral fitting norms and 4-5 year replacement cycles sustain recurring revenue for independent audiology practices. BfArM coordinates with EMA guidance on software-as-medical-device classifications for AI-powered hearing algorithms. Bavaria's Munich-Stuttgart corridor hosts the densest concentration of premium retail chains deploying real-ear measurement verification.
France
Early intervention mandates lower fitting ages for congenital losses, expanding pediatric Behind-the-Ear demand. ANSM enforces post-market surveillance protocols that influence warranty and service contract structures. Paris and Lyon anchor hospital-based ENT referral pathways for sudden hearing loss assessment.
Italy
Regional health system fragmentation creates reimbursement rate disparities between Lombardy and Southern regions. CE marking requirements under MDR compress margin flexibility for manufacturers serving price-sensitive subsidy pools. Milan's audiology clinic network concentrates northern Italy's premium digital platform adoption.
Netherlands
Subscription-based hearing care models displace outright device ownership in urban markets with clinic density supporting rapid follow-up scheduling. EU MDR harmonization benefits Dutch manufacturers seeking single-market access across member states. Amsterdam-Rotterdam retail chains pilot tele-audiology protocols for dispersed rural populations.
Denmark
Nordic tele-audiology pilots favor programmable technology tiers for remote calibration workflows. GN Store Nord leverages ReSound brand strength across regional audiology channels. Copenhagen's hearing technology cluster anchors firmware development for deep neural network noise suppression algorithms.
Europe Hearing Aids Market Competitive Landscape
Vertically integrated hearing technology conglomerates and specialized audiology service chains split the market between hardware manufacturing and clinical distribution control. Consolidation concentrates around five dominant holding structures with full-stack capabilities from semiconductor sourcing to retail fitting. Two strategic archetypes predominate: integrated device-manufacturers with captive audiology networks, and independent retail chains competing on programmable technology tiers. Competitive moves center on M&A to secure notified body certification capacity and strategic partnerships for AI algorithm development.
Within the integrated-manufacturer tier, GN Store Nord A/S and Sonova Holding AG exemplify full-stack control from Danish and Swiss origins respectively. WS Audiology occupies a position bridging mid-market European retail penetration with programmable platform development. These three entities anchor the competitive structure through archetype representation rather than fragmented specialization.
| Leading Market Players |
|---|
| GN Store Nord A/S |
| Cochlear Limited |
| Sonova Holding AG |
| MED-EL |
| Amplifon S.p.A. |
| Demant A/S |
| Starkey Hearing Technologies |
| Eargo, Inc. |
| WS Audiology |
| Others |
Supply & Pricing Matrix
East Asian foundry concentration for MEMS microphones and DSP chips anchors cost structures for European manufacturers, pushing margin capture downstream toward software-enabled fitting services and remote calibration platforms that bypass hardware commoditization.
Pricing Analysis
After-sales revenue from software-enabled fitting adjustments and remote calibration platforms now drives lifetime patient value beyond the initial device transaction. Three-tier pricing structure across premium, standard, and economy levels separates AI-powered firmware-upgradable units from programmable mid-market tiers and fixed-function analog subsidy devices. Cost compression in economy tiers is intensifying because Italy's regional health systems impose divergent reimbursement ceilings. Subsidy-dependent patient pools exhibit highest price sensitivity, while working-age adults in German urban centers demonstrate lowest sensitivity due to cosmetic preference premiums.
Supply Chain Analysis
Tariff exposure between East Asian semiconductor foundries and European assembly facilities dominates supply chain risk planning for hearing aid manufacturers. Taiwan and South Korea anchor DSP chip and MEMS microphone sourcing, while Germany and Denmark concentrate final device assembly and firmware development. Raw material dependencies span rare-earth magnets for receiver transducers, medical-grade silicones for earmold fabrication, and lithium-polymer cells for rechargeable platforms. Single-source vulnerability in advanced audio component allocation threatens production continuity. Distribution runs through audiology clinic networks in Germany, retail chains in Netherlands and Denmark, and hospital ENT pathways in France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote calibration and subscription-based hearing care represent the fastest-expanding recurring-revenue layer, outpacing hardware turnover cycles as tele-audiology protocols mature in Nordic markets.
For Market Incumbents: Pre-empt regulatory capture by securing notified body certification capacity ahead of MDR transition bottlenecks that delay rival product launches 12-18 months. Consolidate clinical evidence portfolios for AI-powered algorithms before Germany's BfArM finalizes software-as-medical-device pathways. Backward integration into MEMS microphone sourcing mitigates East Asian foundry allocation risk. For New Entrants and Emerging Players: Mid-market programmable technology tiers in Southern European regional health systems represent the most penetrable entry point where reimbursement fragmentation compresses incumbent margin flexibility. Pediatric Behind-the-Ear configurations for severe-to-profound loss in France and Germany offer captive long-term fitting relationships under early intervention mandates. Partner with established audiology chains for white-label remote calibration deployment rather than building clinic networks organically. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed audiology service chains that lack captive manufacturing but control patient access in dense urban corridors. Five-to-ten year viability hinges on software-defined functionality displacing hardware-centric value capture. Monitor BfArM algorithm classification precedents as inflection indicator for which firmware-update platforms achieve regulatory moat.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance for AI-powered hearing algorithms unlocks single-market access across member states. |
| Software Companion Development | Remote calibration apps bypass clinic capacity constraints in Nordic dispersed populations. |
| Hospital System Partnership | ENT referral pathways in Paris and Lyon anchor acute-onset loss assessment volume. |
| Reimbursement Strategy | Integration with Germany's statutory health insurers sustains bilateral fitting norm economics. |
| Acquisition of Specialist Firm | Notified body certification capacity purchases compress rival product launch timelines. |
Research Methodology
Cross-validation between audiology clinic operating data and regulatory filing archives anchors the qualitative findings. Primary interviews with hearing aid manufacturing executives, independent audiologists, hospital ENT specialists, and statutory health insurance reimbursement officers combined with secondary validation from BfArM guidance documents, ANSM post-market surveillance protocols, EU MDR transition notices, and audiology chain financial disclosures. Bottom-up patient volume modeling and top-down device shipment triangulation ensure segmentation consistency.
Calibration against historical replacement cycle data and firmware obsolescence patterns shapes the analytical framework across the projection horizon. Segmentation dimensions span acoustic architecture, signal processing technology, patient age cohort, and distribution channel intensity. CAGRs derive from fitted trend extrapolation moderated by regulatory transition timeline uncertainty. Forecast inputs include notified body audit queue projections and tele-audiology protocol adoption curves in pilot markets.
Macroeconomic conditions sit as an overlay; deviation in statutory health insurance reimbursement rates or East Asian semiconductor foundry allocation priorities would shift the trajectory. Forecasts reflect documented assumptions about MDR transition completion and AI algorithm classification clarity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Global Sinusitis Treatment Market
ENT
Over-The-Counter (OTC) Hearing Aids Market
ENT
Audiology Devices Market
ENT
ENT Devices Market
ENT
Custom Hearing Aids Market
ENT
US Hearing Aids Market
ENT
Ear Health Market
ENT
Acute Sinusitis Market
ENT
ENT Laser Devices Market
ENT
Europe Speech Therapy Market
ENT
Global ENT Workstations Market
ENT
Global Pediatric Hearing Aids Market
ENT
Electrolarynx Market
ENT
Hearing Loss Disease Treatment Market
ENT
Global Audiological Devices Market
ENT
Nasal Sampling Lines Market