
 Dental CAM Milling Machine Market | 2026-2036
Dental CAM Milling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Dental CAM Milling Machine Market Analysis
The gap between premium five-axis titanium mills and entry-level zirconia units is expanding as laboratories face diverging capital budgets and case complexity. Dentsply Sirona leverages integrated software-to-hardware workflows that lock in recurring consumables revenue. VHF Dental Maschinen GmbH anchors German precision engineering reputation across European dental technician networks. Amann Girrbach differentiates through modular upgrade paths that protect laboratory capital investments.
Dental CAM milling machines are subtractive manufacturing systems that use computer-aided manufacturing to shape ceramic, metal, or composite blanks into final dental prostheses with spindle speeds typically exceeding 60,000 RPM for zirconia finishing. These systems automate crown, bridge, and implant abutment production with micron-level accuracy that eliminates manual waxing and casting steps. Wet milling machines retain dominant installed base share due to superior surface finishes on glass ceramics, though hybrid systems that switch between wet and dry modes capture fastest-growing interest from mid-size laboratories seeking single-unit flexibility. Crown fabrication applications generate the largest procedure volume, yet implantology applications command premium pricing because titanium milling requires rigid machine construction and specialized coolant systems that standard units lack.
FDA 510(k) premarket notification requirements govern dental milling machine clearance in the United States, while CE marking under the EU Medical Device Regulation mandates clinical evaluation and post-market surveillance across European Economic Area countries. ISO 13485 quality management certification has become a de facto procurement filter for hospital and large laboratory buyers evaluating vendor risk. Stakeholders must monitor evolving software validation requirements as artificial intelligence-driven toolpath optimization begins to blur the regulatory boundary between standalone hardware and regulated medical device software.
Market Dynamics
Chairside milling systems are compressing turnaround times from weeks to hours, forcing laboratories to reconfigure capital deployment toward same-day production workflows or risk case volume erosion to chairside competitors.
Growth Catalysts
- FDA 510(k) clearance streamlining:The FDA's premarket notification pathway for Class II medical devices accelerates product entry, reducing time-to-revenue for wet and dry hybrid milling systems targeting dental laboratories.
- Zirconia blank material advances:High-translucency zirconia formulations with enhanced flexural strength expand anterior crown indications, pulling demand from layered ceramics toward monolithic milled restorations.
- German precision manufacturing clusters:Concentrated supplier ecosystems around Bavaria and Baden-Württemberg deliver spindle and axis components with sub-micron repeatability that anchors European technician network loyalty.
Market Restraints
- Titanium bar stock cost volatility:Aerospace and medical device competition for aerospace-grade titanium creates input price instability that compresses margins on implant abutment production.
- Five-axis machine supply concentration:Premium simultaneous five-axis milling capability concentrates among Swiss and German machine tool builders, creating procurement bottlenecks for laboratories seeking titanium-grade rigidity.
- Wet milling infrastructure requirements:Coolant filtration, wastewater handling, and humidity control systems impose facility retrofit costs that delay adoption in leased laboratory spaces.
Strategic Opportunities
- India dental laboratory consolidation:Fragmented urban laboratory networks in Mumbai and Delhi present acquisition targets for integrated CAD/CAM workflow providers seeking scale in prosthodontics outsourcing.
- AI-driven toolpath optimization:Machine learning algorithms that predict tool wear and adjust feed rates in real-time converge with existing CAM software to reduce blank waste and spindle downtime.
- EU Medical Device Regulation post-market surveillance:MDR-mandated clinical evaluation and vigilance systems create competitive moats for manufacturers with established quality management infrastructure.
Industry Challenges
- CAD/CAM technician training deficits:Dental technology programs lag in five-axis programming and material science curricula, forcing laboratories to fund internal apprenticeship pipelines.
- ISO 13485 certification timelines:Quality management system audits and documentation requirements extend vendor qualification periods, delaying procurement decisions for hospital-affiliated laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental CAM Milling Machine Market |
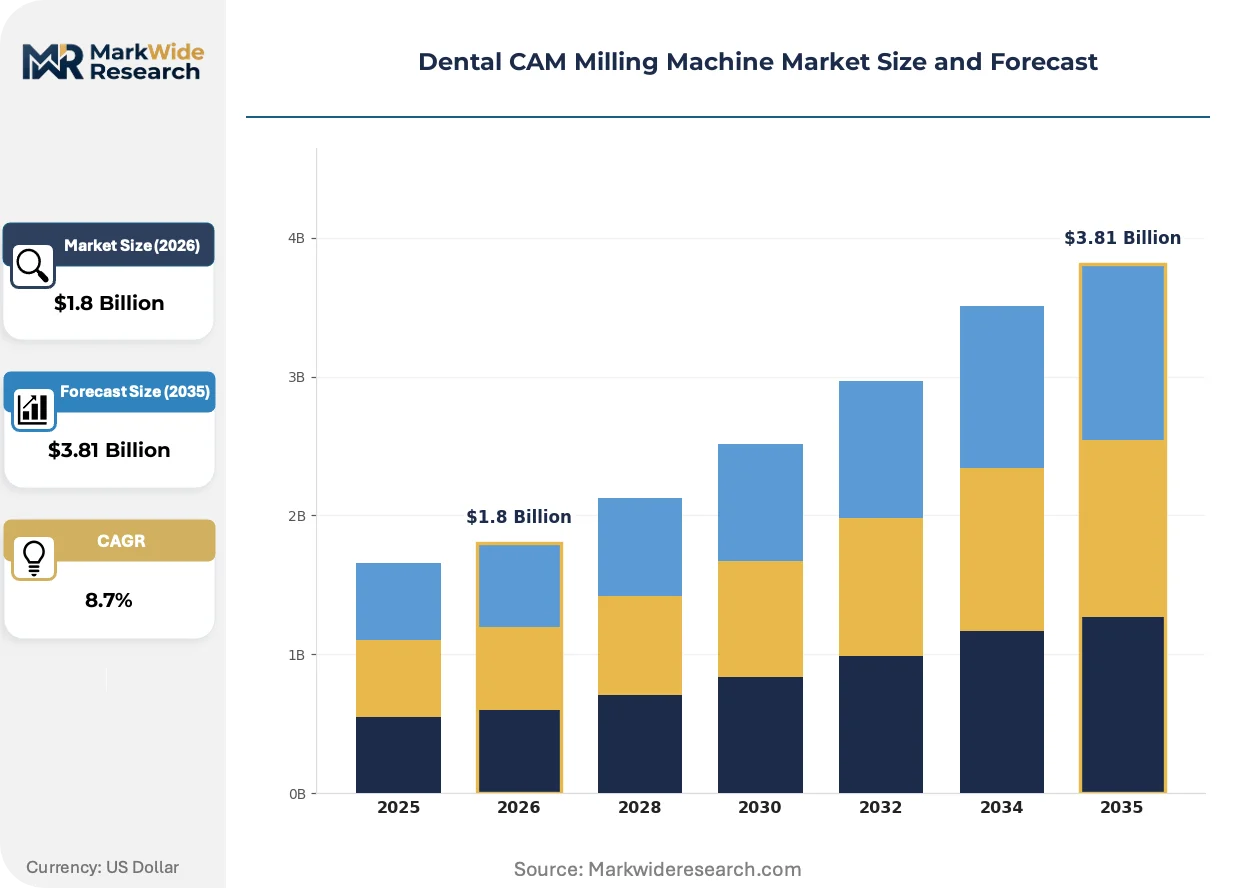
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Milling Machines, Dry Milling Machines, Hybrid Milling Machines, CAD/CAM Systems End User: Dental Laboratories, Dental Clinics, Hospitals, Research Institutions Technology: 3D Printing, CNC Machining, Laser Sintering, Subtractive Manufacturing Application: Crown Fabrication, Denture Production, Bridge Creation, Implantology |
| Companies Covered | Bien Air, VHF Dental Maschinen GmbH, Dentsply Sirona, Planmeca, Roland DGA Corporation, Renishaw, Amann Girrbach, Straumann Group, Zirkonzahn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental CAM Milling Machine Market Emerging Trajectories
Automation architectures are converging with artificial intelligence to compress the skilled labor dependency that has historically constrained laboratory throughput scaling.
Hybrid wet-dry milling systems are consolidating machine footprints in mid-size laboratories that previously maintained separate units for zirconia and titanium processing. German and Swiss equipment builders dominate this segment, with dental technician networks prioritizing single-platform flexibility over specialized performance. The technology is consolidating vendor relationships by embedding proprietary blank and tool libraries that raise switching costs.
EU Medical Device Regulation clinical evaluation requirements are tightening post-market surveillance obligations for milling machine manufacturers marketing within the European Economic Area. The regulation forces documentation of systematic literature reviews and clinical data trails that smaller vendors struggle to resource. Implantology-focused systems face the steepest compliance burden due to higher risk classification of titanium abutments.
Laboratory procurement patterns are fragmenting as group purchasing organizations lose leverage to direct manufacturer relationships. Large dental service organizations negotiate enterprise pricing with Dentsply Sirona and Amann Girrbach, bypassing traditional distribution markups. This disintermediation is most pronounced in Germany and the United States, where DSO consolidation has concentrated buyer power.
Dental CAM Milling Machine Market Segmentation
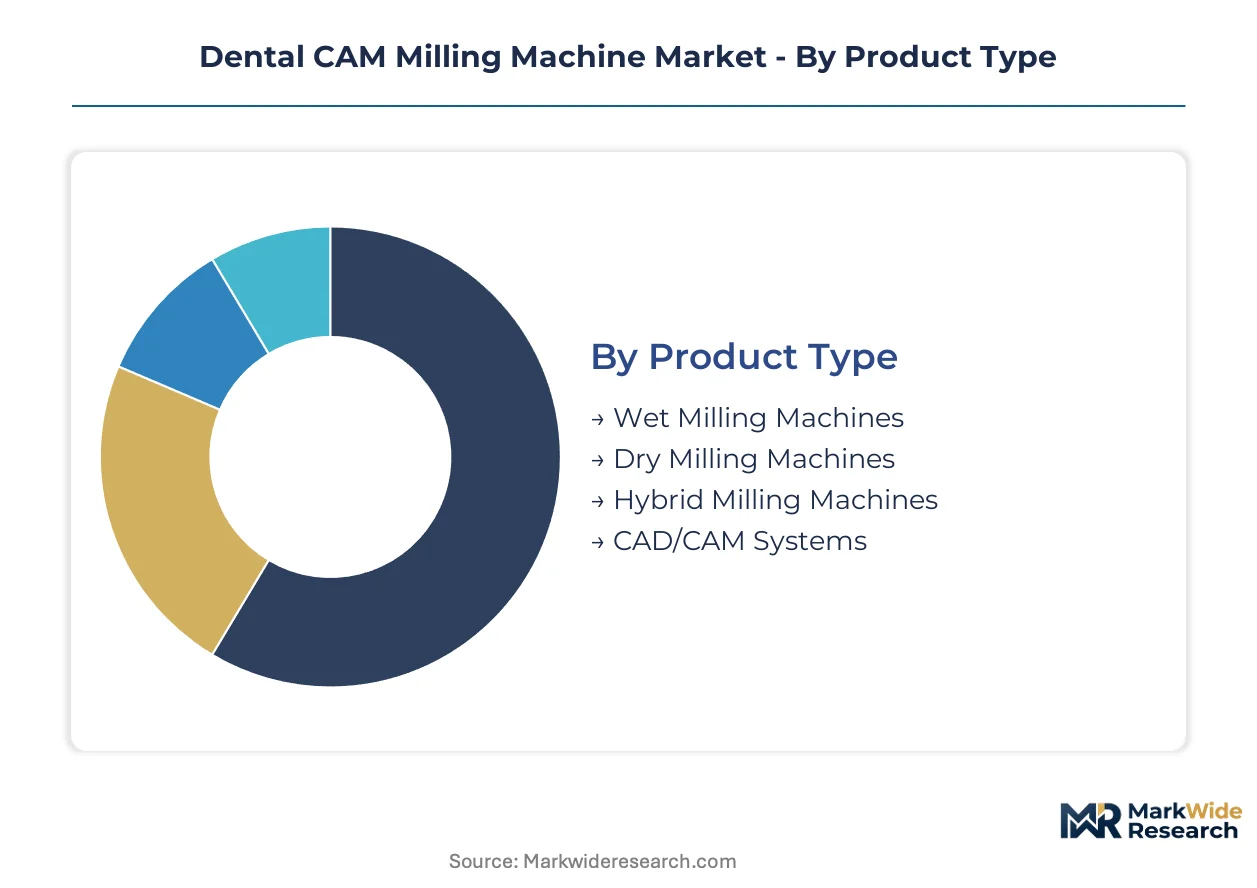
Segmentation in dental CAM milling machines reveals how capital deployment, workflow integration, and material processing requirements diverge across laboratory and clinical settings. Understanding these splits exposes where procurement budgets concentrate and which technology architectures capture upgrade cycles.
Product Type:
Spindle configuration and coolant architecture define the capital-intensity gradient across installation bases.
- Wet Milling Machines:These systems deploy liquid coolant circulation to manage thermal stress during glass ceramic and zirconia finishing, with spindle speeds exceeding 60,000 RPM. Demand clusters in German dental technician networks where surface finish specifications for anterior crowns remain stringent. Superior edge quality on lithium disilicate blocks sustains premium positioning despite higher facility infrastructure requirements.
- Hybrid Milling Machines:Dual-mode architecture switches between wet and dry processing without hardware reconfiguration, compressing machine footprints for mid-size laboratories. Italian and Spanish dental laboratories are accelerating adoption where leased facility constraints limit dedicated wet-line installations. Single-platform flexibility protects capital investments against shifting case mix between zirconia and titanium.
- Dry Milling Machines:Air-cooled spindles process zirconia and PMMA without coolant infrastructure, lowering entry barriers for small laboratories.
- CAD/CAM Systems:Integrated design-to-manufacture workflows bundle scanner, software, and mill in unified vendor ecosystems.
Mature deployment sits with wet milling machines. Newer deployment is concentrated in hybrid milling machines.
End User:
Procurement authority and case volume economics reshape vendor go-to-market strategies across the value chain.
- Dental Laboratories:High-throughput production facilities process 50-200 units daily across mixed material portfolios, driving demand for five-axis titanium capability. Bavarian and Baden-Württemberg laboratory networks anchor European precision manufacturing clusters. ISO 13485 certification requirements filter vendor selection for hospital-affiliated operations.
- Dental Clinics:Chairside systems compress crown turnaround from weeks to single-visit delivery, capturing patient preference for immediate restoration. US dental service organizations negotiate enterprise pricing that bypasses traditional distribution channels. Same-day workflow integration with intraoral scanners locks in consumables recurring revenue.
- Hospitals:Academic medical centers and maxillofacial surgery departments prioritize implantology applications with titanium-grade machine rigidity.
- Research Institutions:Universities and materials science laboratories validate next-generation ceramic formulations and toolpath algorithms.
Revenue concentration rests with dental laboratories. Steepest expansion trajectory is occurring in dental clinics.
Technology:
Fabrication methodology determines accuracy tolerances, material compatibility, and regulatory classification boundaries.
- CNC Machining:Computer-numerical control subtractive manufacturing achieves micron-level accuracy through multi-axis spindle movement, dominating crown and bridge production. Swiss and German machine tool builders control premium five-axis simultaneous capability for titanium implant components. Mature CAM software ecosystems embed proprietary tool libraries that elevate switching costs.
- 3D Printing:Additive resin and metal powder bed fusion enables complex lattice structures for temporary restorations and surgical guides, gaining traction in digital dentistry workflows. Japanese dental laboratories are piloting photopolymerization for denture baseplates where material costs challenge milling economics.
- Laser Sintering:Direct metal laser melting processes cobalt-chrome and titanium powders for implant frameworks with internal channel geometries impossible to mill.
- Subtractive Manufacturing:Broad category encompassing milling, grinding, and turning operations that remove material from solid blanks.
Installed base dominance belongs to CNC machining. Technology transition is accelerating toward 3D printing.
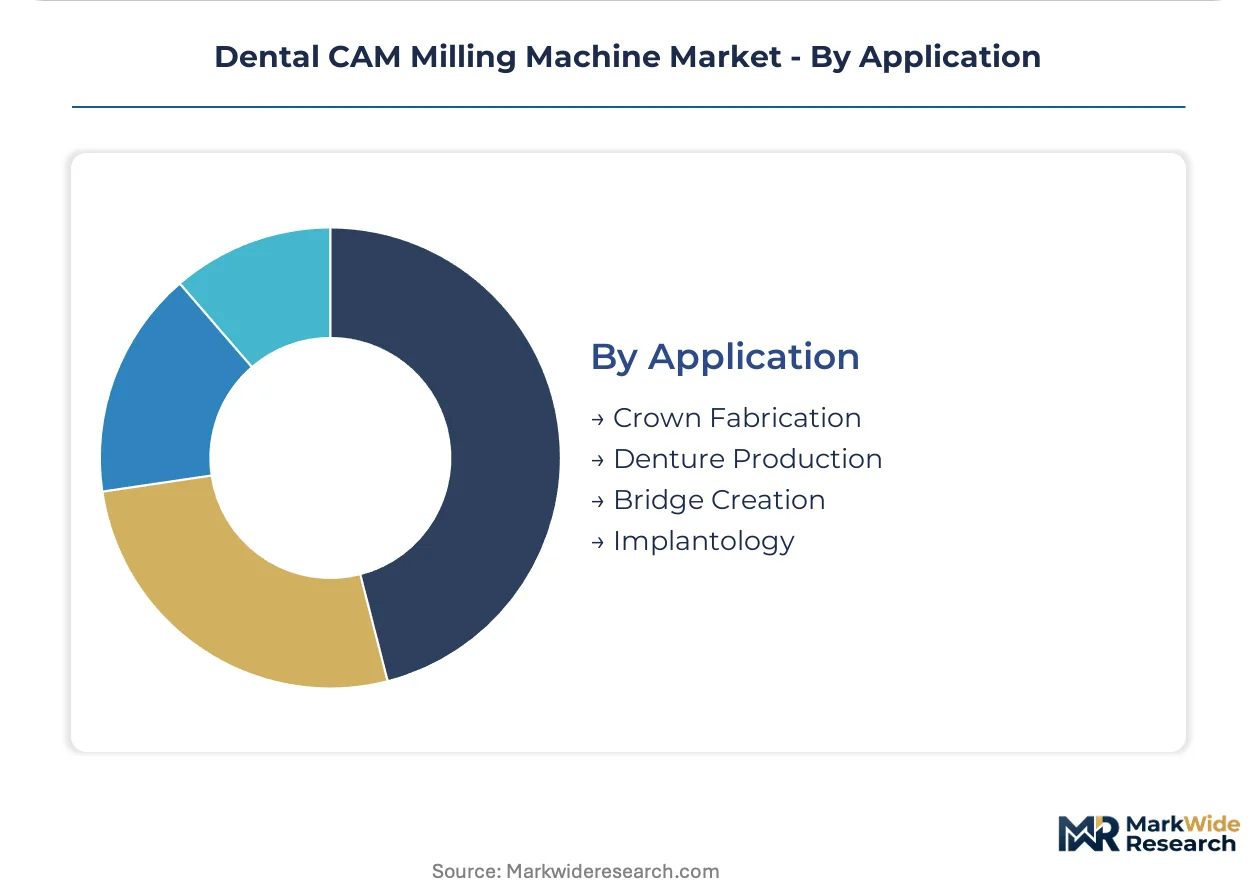
Application:
Clinical indication complexity dictates machine specification tiers and pricing architecture.
- Implantology:Titanium abutment and bar production demands rigid machine construction, specialized coolant systems, and tool wear monitoring that standard units lack. German implant manufacturers specify simultaneous five-axis capability for screw-retained restoration geometries. FDA 510(k) clearance pathways for Class II medical devices impose documentation burdens that concentrate supply among established vendors.
- Crown Fabrication:Single-unit restoration volume drives the largest procedure count across installed bases, with zirconia monolithic crowns displacing layered ceramics. Wet milling retention in anterior cases preserves surface finish advantages over dry alternatives.
- Bridge Creation:Multi-unit fixed prosthodontics require connector strength validation and occlusal adjustment workflows.
- Denture Production:PMMA and composite milling for removable prosthetics leverages larger blank formats and lower spindle speed requirements.
Procedure volume leadership sits with crown fabrication. Margin expansion is concentrating in implantology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's precision engineering corridor around Munich anchors European dental milling machine manufacturing, with Baden-Württemberg's Stuttgart region supplying sub-micron spindle components that technician networks specify for crown production.
United States
Dental service organizations in Texas and Florida negotiate enterprise pricing for chairside systems that compress restoration turnaround from weeks to hours. FDA 510(k) premarket notification pathways for Class II medical devices accelerate product entry timelines for wet-dry hybrid mills. The Pacific Northwest corridor hosts software developers integrating AI-driven toolpath optimization with existing CAM platforms.
Germany
Laboratory networks in Bavaria and Baden-Württemberg demand five-axis titanium capability for implant abutment production, specifying simultaneous machining that Swiss and German builders control. CE marking under the EU Medical Device Regulation mandates clinical evaluation documentation that concentrates supply among established quality management systems. VHF Dental Maschinen GmbH and Amann Girrbach anchor precision manufacturing clusters around Lake Constance.
China
Urban laboratory consolidation in Shanghai and Beijing drives demand for entry-level zirconia mills that displace manual waxing workflows. The National Medical Products Administration governs Class II medical device registration with documentation requirements that extend vendor qualification periods. Yangtze River Delta fabrication hubs supply spindle components to domestic equipment assemblers competing on capital cost.
Japan
Photopolymerization pilot programs in Tokyo and Osaka dental laboratories test additive alternatives to subtractive milling for denture baseplate production. The Ministry of Economy, Trade and Industry supports digital dentistry adoption through productivity-focused equipment subsidies. Nagoya's machine tool heritage supplies multi-axis controllers to regional dental equipment integrators.
India
Fragmented prosthodontics outsourcing networks in Mumbai and Delhi present acquisition targets for integrated CAD/CAM workflow providers seeking scale. The Central Drugs Standard Control Organization regulates medical device imports with quality management system requirements that filter vendor selection. Gujarat's industrial corridor hosts contract manufacturers assembling entry-level dry mills for price-sensitive laboratory segments.
Dental CAM Milling Machine Market Vendor Landscape
Premium-margin players sit above commodity-margin players across five-axis titanium capability versus entry-level zirconia processing. The vendor base stratifies between integrated CAD/CAM ecosystem providers and specialized hardware fabricators. Three archetypes dominate: German-Swiss precision engineering houses, Japanese electronics conglomerates with dental divisions, and Chinese cost-optimized assemblers. Competitive moves concentrate on M&A for software integration and capacity expansion in titanium-grade machine construction.
Among German precision engineering specialists, VHF Dental Maschinen GmbH and Amann Girrbach exemplify the modular-upgrade archetype that protects laboratory capital investments. Dentsply Sirona occupies a position representing integrated ecosystem providers that bundle scanner-to-mill workflows with consumables lock-in. These three companies anchor distinct competitive vectors: hardware modularity, vertical software integration, and enterprise-scale procurement relationships.
| Leading Market Players |
|---|
| Bien Air |
| VHF Dental Maschinen GmbH |
| Dentsply Sirona |
| Planmeca |
| Roland DGA Corporation |
| Renishaw |
| Amann Girrbach |
| Straumann Group |
| Zirkonzahn |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap precision engineering specialists in Bavaria and Baden-Württemberg anchor supply-side discipline through multi-generational capital stewardship that resists price erosion despite titanium bar stock volatility. Their anchored ownership structures translate into pricing power over dental technician networks that specify German spindle components for crown production quality assurance.
Pricing Analysis
Value-based pricing anchored to restoration throughput and machine uptime dominates vendor-laboratory contracting. Three-tier pricing structure across premium five-axis titanium systems, standard wet-milling zirconia units, and entry-level dry mills separates ISO 13485-certified installations from uncertified alternatives. Pricing pressure stems from Chinese equipment assemblers compressing capital costs for price-sensitive urban laboratory networks in Mumbai and Delhi. Small dental clinics exhibit highest price sensitivity, while hospital-affiliated laboratories prioritize certification tier over acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements from large dental service organizations mandate multi-supplier qualification for spindle and axis components that Swiss and German machine tool builders control. Manufacturing concentrates in Germany, Switzerland, and Japan, with Yangtze River Delta fabrication hubs supplying entry-level spindle assemblies to domestic Chinese assemblers. Aerospace-grade titanium bar stock, high-translucency zirconia blanks, and sub-micron ball screw drives constitute critical input dependencies. Single-source vulnerability concentrates in simultaneous five-axis motion controllers. Distribution runs through direct manufacturer relationships with dental service organizations that bypass traditional dental distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
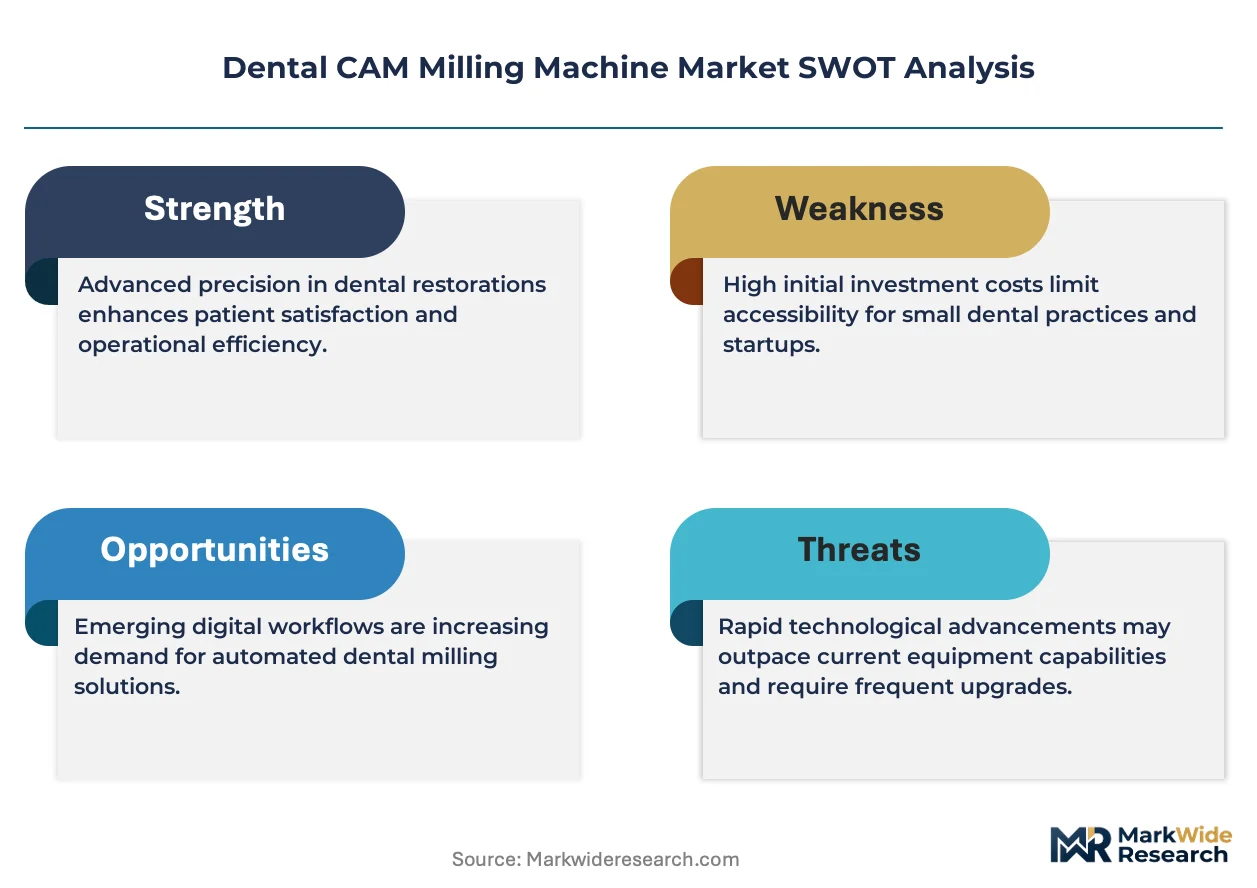
Five-axis titanium-grade machine construction capacity constraints among Swiss and German builders prop pricing discipline across the analysis window. Supply bottlenecks for rigid spindle platforms used in implant abutment production sustain premium positioning.
For Market Incumbents: Acquire AI-driven toolpath optimization software assets to lock in recurring consumables revenue against emerging CAD/CAM platform competitors. Dentsply Sirona's integrated scanner-to-mill workflow exemplifies ecosystem stickiness that protects against hardware commoditization. Backward integration into high-translucency zirconia blank manufacturing secures margin control as material science advances accelerate. For New Entrants and Emerging Players: Launch via dental service organization enterprise pricing contracts that disintermediate traditional distribution markups. White-space opportunity concentrates in India's fragmented Mumbai and Delhi laboratory networks where consolidation creates scale demand for entry-level hybrid wet-dry systems. Target mid-size Italian and Spanish laboratories constrained by leased facility infrastructure through single-platform flexibility messaging. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular-upgrade-path hardware specialists with established CE marking documentation under EU Medical Device Regulation post-market surveillance requirements. Long-term viability hinges on software-to-hardware workflow integration that elevates switching costs. Watch FDA 510(k) clearance timeline compression for Class II medical device submissions as inflection signal for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU Medical Device Regulation clinical evaluation documentation creates competitive moats for established quality systems. |
| AI Toolpath Integration | Machine learning algorithms that predict tool wear reduce blank waste and compress skilled labor dependency. |
| Hospital System Partnership | ISO 13485-certified vendors capture procurement from academic medical centers prioritizing implantology applications. |
| Software Companion Development | Proprietary blank and tool libraries embedded in CAM platforms elevate laboratory switching costs. |
| Reimbursement Strategy Alignment | Same-day crown delivery workflows align with dental service organization patient retention economics. |
Methodological Framework
Multi-period observation of spindle speed specifications, FDA 510(k) clearance timelines, and CE marking documentation requirements anchored the trend analysis, supplemented by interviews with dental laboratory owners, biomedical engineers at hospital-affiliated facilities, GPO contracts managers, and CAM software developers. Secondary validation drew from FDA 510(k) premarket notification database, EU Medical Device Regulation vigilance reports, German dental technician association procurement surveys, and customs records of zirconia blank imports. Bottom-up laboratory equipment installation tracking triangulated against top-down vendor revenue estimates.
Segment-weighting across product type, end user, technology, and application dimensions structured the analytical framework over the projection horizon. CNC machining, 3D printing, and laser sintering technology transitions were modeled against crown fabrication and implantology procedure volume splits. CAGRs were derived from installed base replacement cycles and capital expenditure patterns across dental laboratory consolidation waves. Titanium-grade machine rigidity requirements and wet-milling infrastructure retrofit costs informed industry-specific forecast inputs.
Titanium bar stock cost volatility, FDA software validation requirement evolution, and dental service organization procurement consolidation are the dominant revision risks to the outlook. Deviation in aerospace-grade titanium input pricing would shift margin compression timelines materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Dental Equipment and Consumables Market
Dental Equipment
Global Dental Light Curing Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Dental 3D Printing Scanner Market
Dental Equipment
Dental Engine Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market
Dental Equipment
Dental Elevator and Luxator Market
Dental Equipment
Ultrasonic Dental Scalers Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
North America Dental Equipment Market
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Japan Dental Equipment Market