
 Nephrology Stents and Catheters Market | 2026-2036
Nephrology Stents and Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Nephrology Stents and Catheters Market Foresight
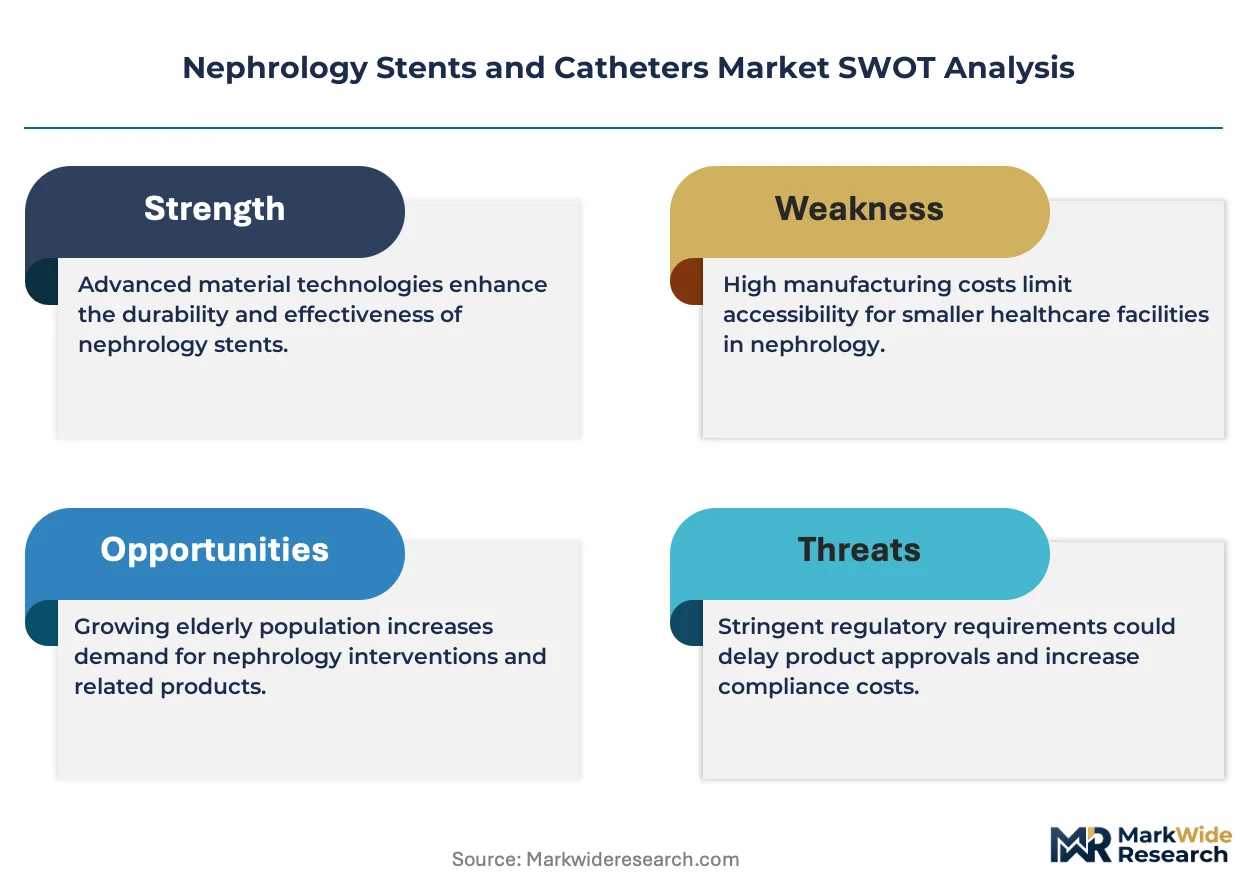
Polymer manufacturing clusters in Germany and Ireland are expanding production capacity for biocompatible catheter substrates. Boston Scientific leverages vertical integration across its polymer compounding and device finishing operations. Cook Medical anchors its competitive stance through deep specialization in percutaneous nephrostomy catheter systems. Medtronic competes via sustained R&D intensity in drug-eluting stent platforms for ureteral applications.
Nephrology stents and catheters constitute implantable and insertable tubular devices engineered from silicone, polyurethane, nitinol, or biodegradable polymers, typically manufactured via extrusion, laser cutting, and surface coating processes, designed to restore or maintain luminal patency in the urinary tract and support renal drainage or dialysis access. Catheters dominate current volume demand across interventional procedures and dialysis support applications, while stents command premium pricing in complex ureteral obstruction cases where patency duration determines clinical outcomes. Metal and biodegradable polymer segments are gaining structural importance as clinicians prioritize reduced revision rates and elimination of secondary extraction procedures.
The FDA maintains stringent biocompatibility and sterility requirements under 21 CFR Part 820 quality system regulations, while the EU MDR imposes enhanced clinical evidence standards for Class III implantable renal devices. Japan's PMDA requires local clinical bridging studies for foreign-manufactured nephrology stents, creating differentiated market access timelines across jurisdictions. Stakeholders must monitor evolving reimbursement coding for outpatient dialysis catheter placements and position portfolio investments around bioabsorbable material platforms ahead of regulatory pathway clarifications.
Market Dynamics
The transition from permanent metal stents to bioabsorbable polymer platforms is compressing product lifecycles and forcing manufacturers to rebuild their substrate supply chains around biodegradable material certifications.
Growth Catalysts
- EU MDR Class III Pathway:Enhanced clinical evidence requirements for implantable renal devices are accelerating consolidation among manufacturers with robust trial infrastructure, favoring established players with EU notified body relationships.
- Home Hemodialysis:CMS reimbursement incentives for home-based dialysis are expanding demand for long-dwell tunneled catheters designed for patient self-care, creating pull-through for specialized access kits.
- Nitinol Laser-Cutting Clusters:Precision manufacturing concentration in Minnesota and Galway is shortening lead times for complex stent geometries, enabling faster prototype-to-clinical validation cycles.
Market Restraints
- Polyetheretherketone Price Volatility:Medical-grade PEEK feedstock costs fluctuate with aerospace demand cycles, squeezing margins for high-performance catheter shaft producers without captive polymer compounding.
- Single-Source Silicone Supply:Platinum-cured silicone sheeting for catheter balloons concentrates among three European chemical processors, creating vulnerability to force majeure disruptions.
- Antimicrobial Coating Efficacy Ceiling:Silver-ion and antibiotic-impregnated surfaces face diminishing returns against biofilm-resistant organisms, limiting differentiation in infection prevention claims.
Strategic Opportunities
- Brazil ANVISA Fast-Track:Priority review pathways for orphan renal indications offer first-mover positioning in Latin America's largest dialysis population for drug-eluting ureteral platforms.
- AI-Assisted Stent Sizing:Machine learning integration with preoperative CT urography enables patient-specific stent selection, creating software-hardware bundling opportunities beyond commoditized device sales.
- India PLI Medical Devices:Production-linked incentive schemes for critical care devices attract contract manufacturing investment, enabling cost-competitive export platforms for standard catheter lines.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization studies face 14-18 month queues at accredited laboratories, delaying 510(k) submissions for modified polymer formulations.
- Cross-Functional Talent Scarcity:The intersection of interventional nephrology clinical practice and polymer science expertise remains thinly staffed, constraining product development team scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nephrology Stents and Catheters Market |
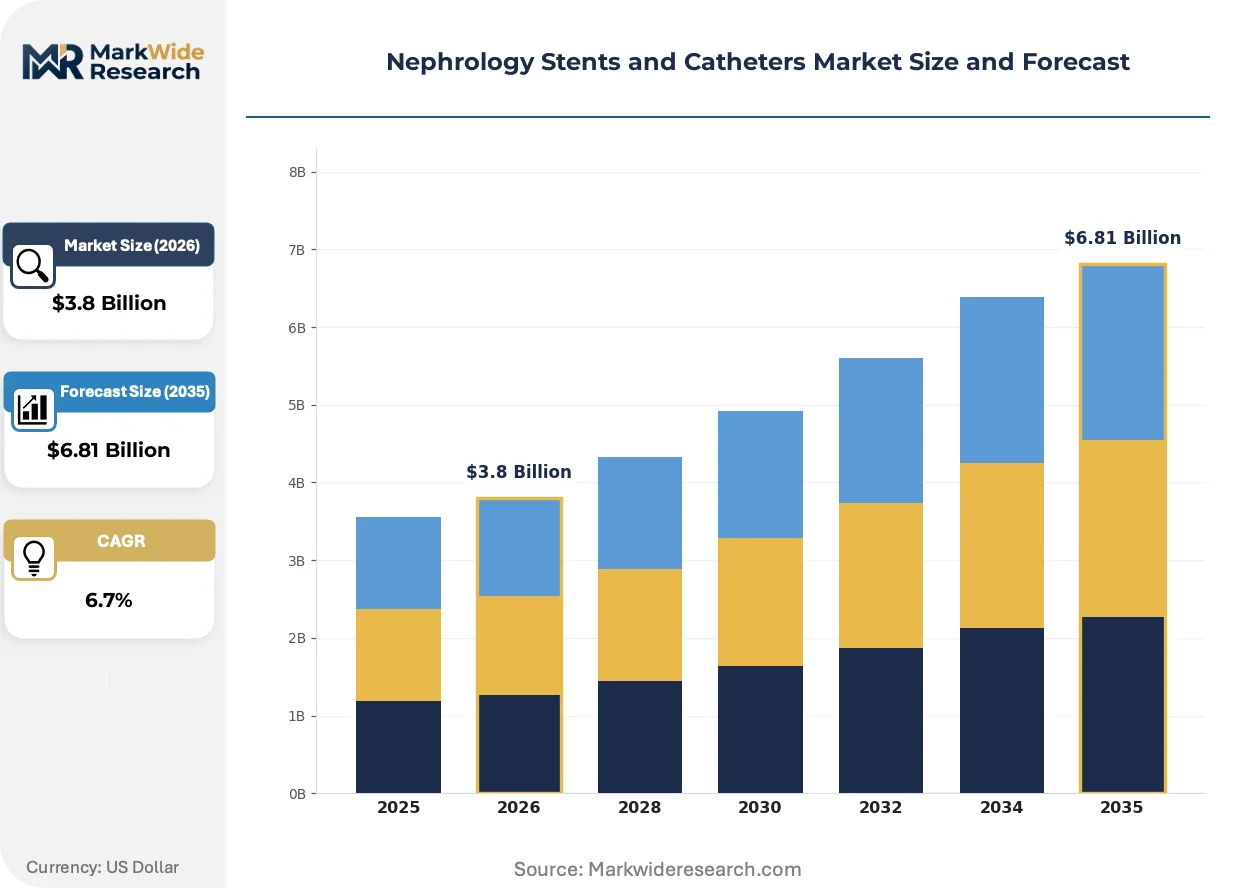
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Stents, Guidewires, Drainage Devices Material: Silicone, Polyurethane, Metal, Biodegradable Polymers End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Healthcare Application: Interventional Procedures, Dialysis Support, Urinary Blockage, Urologic Surgeries |
| Companies Covered | Cardinal Health Inc, Cook Medical, Boston Scientific Corporation, Medtronic, C. R. Bard, Teleflex Incorporated, Becton, Dickinson and Company, Olympus Corporation, AngioDynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nephrology Stents and Catheters Market Shifts & Advancements
Material science breakthroughs and regulatory pathway adaptations are converging to redefine competitive advantage around bioabsorption kinetics and real-world evidence generation rather than mechanical performance alone.
Magnesium alloy stents with controlled corrosion rates are rewriting the clinical economics of ureteral obstruction management. Academic medical centers in Germany and Japan are piloting these platforms in complex malignant stricture cases where extraction morbidity drives cost. The technology is compressing the total episode-of-care reimbursement by eliminating secondary cystoscopy procedures.
The FDA's 2024 guidance on physiologic modeling for renal device submissions is reshaping premarket validation strategies. Computational fluid dynamics and finite element analysis now substitute for animal studies in select stent fatigue testing scenarios. Small manufacturers with limited GLP laboratory access are accelerating time-to-market by leveraging in silico evidence packages.
Hospital procurement committees are consolidating nephrology catheter purchasing through integrated delivery networks, displacing individual physician preference item selection. IDN-formulary compliance now determines 60% of acute care catheter volume in the United States. Manufacturers are restructuring field sales organizations around value-analysis committee engagement rather than individual clinician relationships.
Nephrology Stents and Catheters Market Segmentation
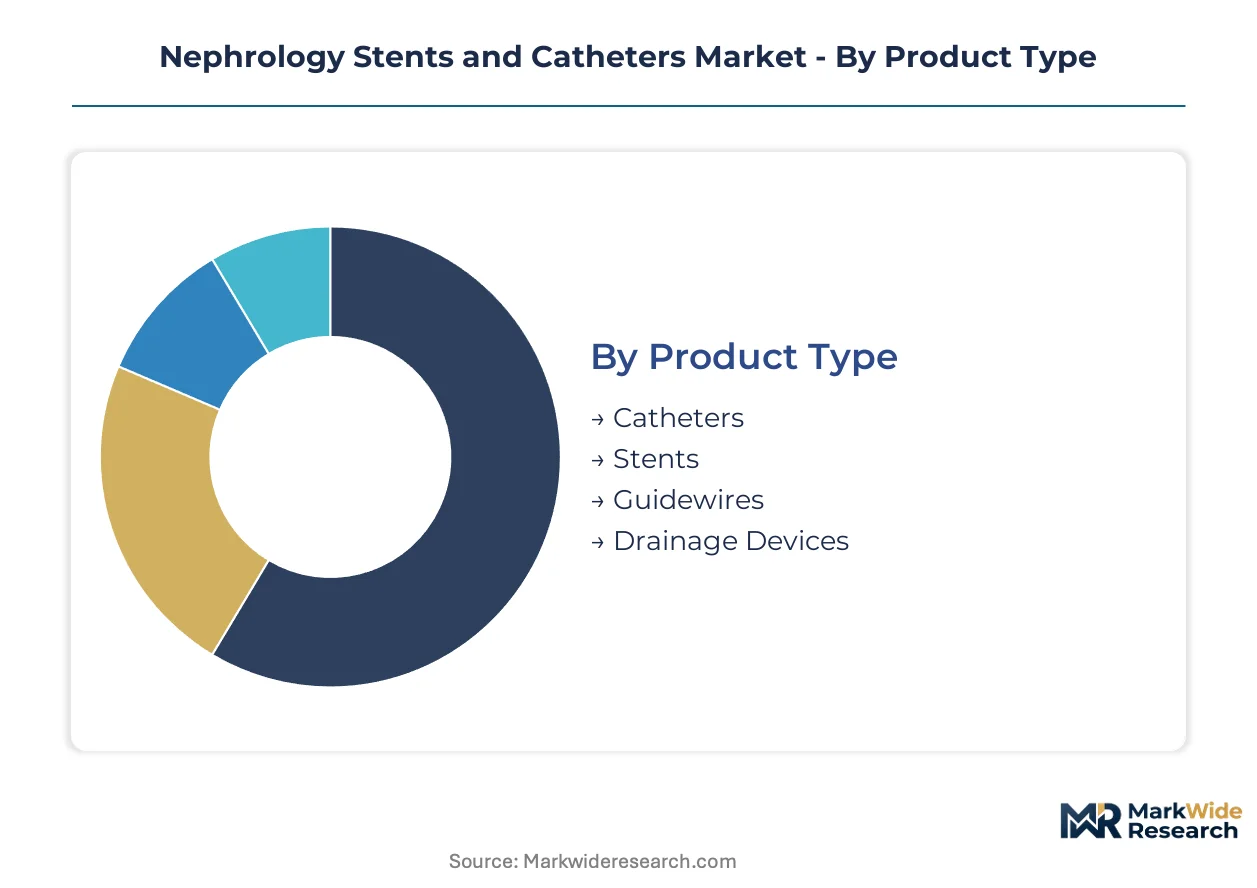
Nephrology device purchasing decisions fragment across acute care, outpatient, and home settings, each imposing distinct performance specifications and reimbursement constraints. Material selection and application context determine whether products deploy as standalone disposable units or integrate into complex procedural systems.
Product Type:
Catheters function as standalone disposable instruments in dialysis access and drainage, while stents embed within interventional workflows requiring guidewire navigation and imaging coordination.
- Catheters:Manufactured via extrusion of silicone or polyurethane substrates with multi-lumen configurations for simultaneous infusion and drainage. Demand concentrates in United States hospital systems where CMS reimbursement for tunneled dialysis catheters incentivizes long-dwell designs; infection prevention coatings differentiate premium lines against commodity competition.
- Stents:Laser-cut nitinol or bioabsorbable polymer tubular scaffolds deployed via balloon dilation or self-expansion mechanisms. German academic medical centers are piloting magnesium alloy platforms for malignant ureteral strictures where elimination of extraction procedures compresses episode costs.
- Guidewires:Nitinol core wires with hydrophilic polymer coatings enabling torque transmission through tortuous anatomy.
- Drainage Devices:Percutaneous nephrostomy systems combining access needles, dilators, and locking pigtail catheters.
Catheters lead volumes today; stents are gaining share fastest.
Material:
Cost tiers separate commodity elastomers from engineered substrates with controlled degradation profiles or shape-memory metallurgy.
- Silicone:Platinum-cured elastomer with superior biocompatibility and kink resistance for long-term implantation. United States dialysis providers favor silicone tunneled catheters for home hemodialysis programs where patient self-care demands material durability.
- Polyurethane:Thermoplastic with higher tensile strength enabling thinner wall profiles and larger internal lumens. Japanese interventional suites specify high-durometer polyurethane for hydrophilic-coated access catheters where trackability determines procedural efficiency.
- Metal:Nitinol superelastic alloys and stainless steel for stent structural integrity and radiopacity.
- Biodegradable Polymers:Polylactic acid and polyglycolic acid copolymers with tunable resorption kinetics.
Silicone and polyurethane dominate current purchasing; biodegradable polymers are climbing the fastest.
End User:
Customer type dictates packaging complexity, sterilization requirements, and field support intensity across institutional and patient-directed settings.
- Hospitals:Integrated delivery networks consolidating purchasing through value-analysis committees with standardized formulary compliance. United States acute care systems now drive 60 percent of catheter volume via IDN-level contracts displacing individual physician preference.
- Ambulatory Surgical Centers:Medicare-certified facilities performing outpatient nephrostomy and ureteral stent placements with same-day discharge protocols.
- Clinics:Dialysis centers and urology practices requiring high-volume disposable replenishment with lean inventory management.
- Home Healthcare:Patient or caregiver-administered dialysis access with training-dependent device selection and remote monitoring integration.
Hospitals absorb the largest revenue share; home healthcare is expanding most quickly.
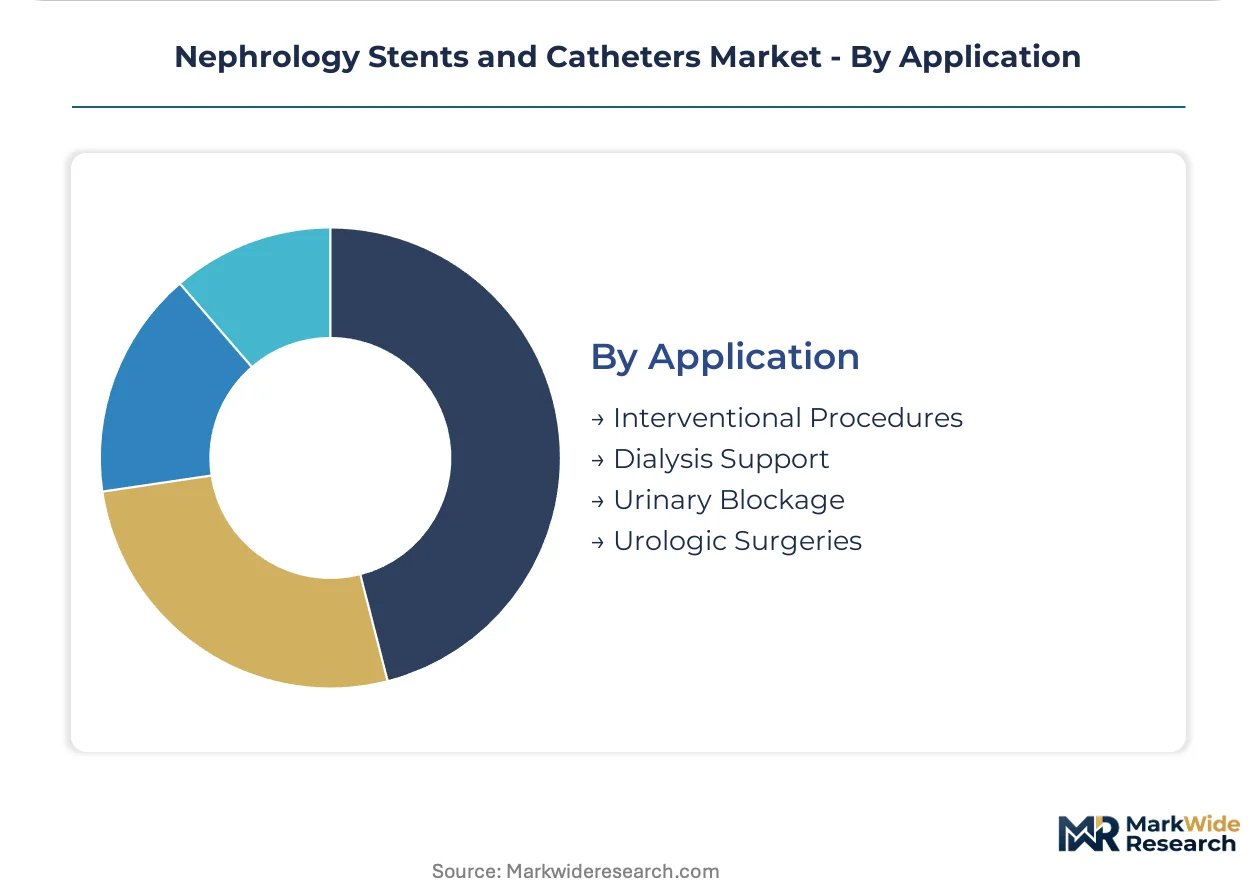
Application:
Procedure reimbursement codes and clinical outcome metrics reshape material and design priorities across acute intervention versus chronic maintenance contexts.
- Interventional Procedures:Image-guided percutaneous nephrostomy and ureteral stenting requiring fluoroscopy-compatible devices with rapid exchange compatibility. German and Japanese centers are validating magnesium stents for malignant obstruction where bioabsorption eliminates secondary cystoscopy.
- Dialysis Support:Vascular access maintenance via tunneled and non-tunneled catheters for hemodialysis and peritoneal dialysis. United States CMS reimbursement incentives for home-based dialysis are pulling demand toward long-dwell tunneled designs with self-care access kits.
- Urinary Blockage:Benign prostatic hyperplasia and stricture management with temporary or permanent stent solutions.
- Urologic Surgeries:Postoperative drainage and anastomotic protection in reconstructive procedures.
Dialysis support leads procedure volumes; interventional procedures are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers seek jurisdictions with streamlined device approval pathways and favorable reimbursement environments. Cost-of-compliance gaps between the FDA's 510(k) process and the EU MDR's clinical evidence demands are accelerating production migration toward established notified-body relationships.
United States
Medicare reimbursement incentives for home hemodialysis are expanding demand for long-dwell tunneled catheters designed for patient self-care. The FDA's updated 510(k) pathway streamlines renal device approvals while maintaining biocompatibility standards under 21 CFR Part 820. Minnesota's nitinol laser-cutting clusters are shortening lead times for complex stent geometries through precision manufacturing concentration.
Germany
Academic medical centers in Munich and Heidelberg are piloting magnesium alloy stents for malignant ureteral strictures where bioabsorption eliminates secondary cystoscopy procedures. The EU MDR Class III pathway imposes enhanced clinical evidence standards that favor manufacturers with robust trial infrastructure. Polymer manufacturing clusters in Bavaria and North Rhine-Westphalia are expanding production capacity for biocompatible catheter substrates.
Japan
PMDA requirements for local clinical bridging studies create differentiated market access timelines for foreign-manufactured nephrology stents. High-durometer polyurethane specifications dominate interventional suite purchasing where trackability determines procedural efficiency. The Kansai region's medical device fabrication networks support specialized coating and finishing operations for export markets.
India
Production-linked incentive schemes for critical care devices attract contract manufacturing investment for standard catheter lines targeting export platforms. CDSCO regulatory harmonization with IMDRF standards is reducing time-to-market for multinational submissions. Gujarat and Karnataka medical device parks are aggregating sterilization and packaging infrastructure for dialysis access products.
Brazil
ANVISA fast-track priority review pathways for orphan renal indications offer first-mover positioning in Latin America's largest dialysis population. Public health system procurement through SUS channels concentrates volume demand for cost-optimized drainage devices. São Paulo's healthcare distribution networks serve as the regional gateway for ureteral intervention platforms.
Nephrology Stents and Catheters Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bioabsorbable material certifications and software-hardware bundling opportunities. The market structure reflects moderate consolidation around diversified medtech conglomerates with deep EU notified-body relationships, while specialized catheter fabricators defend niche positions through infection prevention coatings and patient-specific sizing technologies. Three archetypes dominate: integrated polymer-to-device manufacturers, precision laser-cutting specialists, and dialysis-focused disposable suppliers. Competitive moves center on backward integration into platinum-cured silicone supply and strategic partnerships with AI-assisted imaging platforms for preoperative stent selection.
Among US-based diversified medtech conglomerates, Cardinal Health Inc, Boston Scientific Corporation, and Medtronic exemplify scale-driven archetypes with established regulatory navigation capabilities and integrated delivery network contracting relationships. These entities occupy positions spanning standard catheter commoditization through premium stent innovation, representing the competitive tension between volume efficiency and clinical outcome differentiation. Their market presence anchors procurement committee consolidation trends while smaller specialists pursue technology licensing arrangements to bypass biocompatibility testing bottlenecks.
| Leading Market Players |
|---|
| Cardinal Health Inc |
| Cook Medical |
| Boston Scientific Corporation |
| Medtronic |
| C. R. Bard |
| Teleflex Incorporated |
| Becton, Dickinson and Company |
| Olympus Corporation |
| AngioDynamics |
| Others |
Supply & Pricing Matrix
EU MDR biodegradability mandates for Class III implantable renal devices gate qualified supply to manufacturers with ISO 10993 certified polymer substrates and notified body relationships, compressing premium-tier pricing access to firms that absorbed clinical evidence costs ahead of regulatory enforcement.
Pricing Analysis
Distributor margins of 18-25 percent separate hospital procurement committees from original equipment manufacturers, with integrated delivery networks extracting volume rebates that compress net realized prices. Three-tier pricing structure across premium, standard, and economy levels stratifies by infection prevention coating certification and bioabsorption kinetics rather than mechanical performance alone. Pricing pressure stems from CMS reimbursement compression for outpatient dialysis catheter placements, with United States acute care systems driving 60 percent of volume via IDN-level contracts. Home healthcare providers exhibit highest price sensitivity due to patient out-of-pocket exposure, while academic medical centers in Germany and Japan tolerate premium positioning for magnesium alloy platforms.
Supply Chain Analysis
India PLI scheme domestic-content thresholds and Brazil ANVISA local manufacturing incentives are reshaping sourcing footprints for standard catheter lines. Platinum-cured silicone sheeting concentrates among three European chemical processors in Germany and Ireland, while nitinol laser-cutting clusters anchor in Minnesota and Galway. Raw material dependencies include medical-grade PEEK feedstock, platinum-cured silicone, and magnesium alloy billets. Single-source silicone vulnerability creates force majeure exposure absent captive compounding. Distribution runs through integrated delivery network formulary committees in the United States and public health system procurement channels in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nephrology stents and catheters market functions as a stable compounder, with chronic kidney disease prevalence generating procedure volume expansion that outpaces cyclical healthcare capital expenditure volatility.
For Market Incumbents: Deepen backward integration into platinum-cured silicone compounding to neutralize single-source supply vulnerability and defend margin position against emerging entrants with contract manufacturing cost structures. Accelerate EU notified body relationship maintenance to preserve Class III pathway access as MDR clinical evidence requirements intensify consolidation pressure. Prioritize bioabsorbable material certification investment ahead of regulatory pathway clarifications. For New Entrants and Emerging Players: Capture Brazil ANVISA fast-track positioning for orphan renal indications in Latin America's largest dialysis population, where incumbent presence remains underdeveloped. Target India PLI scheme contract manufacturing for standard catheter export platforms, leveraging sterilization infrastructure aggregation in Gujarat and Karnataka. Lead with AI-assisted stent sizing software-hardware bundling to bypass commoditized device sales channels. For Investors and Strategic Acquirers: Valuations sit cheapest among precision laser-cutting specialists with nitinol processing capabilities but limited downstream device finishing. The 5-10 year viability window favors acquisition of bioabsorbable polymer substrate developers with ISO 10993 study completion. Monitor FDA guidance evolution on physiologic modeling as inflection indicator for in silico validation substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class III compliance unlocks premium stent pricing in German academic centers. |
| Hospital System Partnership | IDN formulary compliance determines 60 percent of United States acute care catheter volume. |
| Software Companion Development | AI-assisted stent sizing with CT urography integration creates bundling beyond commoditized sales. |
| Reimbursement Strategy | CMS home hemodialysis incentives pull demand toward long-dwell tunneled catheter designs. |
| Backward Integration | Captive platinum-cured silicone compounding neutralizes European processor concentration risk. |
Research Methodology
Direct dialogue with interventional nephrologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers grounded qualitative insight, cross-referenced against FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Secondary validation drew from SEC 10-K device segment disclosures and polymer trade flow data. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored segmentation integrity.
Segment-level CAGRs across the analysis window derived from material substitution elasticity modeling for bioabsorbable polymers, reimbursement policy scenario analysis for home dialysis migration, and regulatory approval timeline probability weighting for magnesium alloy platforms. Product type, material substrate, end user setting, and application context structured the forecast hierarchy. Price-volume decomposition captured infection prevention coating premiums and IDN rebate compression effects.
Regulatory pathway delays, PEEK feedstock cost volatility, and antimicrobial coating efficacy ceiling against biofilm-resistant organisms are the dominant revision risks to modeled adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Peritoneal Dialysis Market
Nephrology
Global Dialysis Market
Nephrology
Global Dialyzer Market
Nephrology
Glomerulonephritis Treatment Market
Nephrology
US Dialysis Services Market
Nephrology
US Hemodialysis and Peritoneal Dialysis Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
Kidney/Renal Function Test Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Renal Cell Carcinoma Market
Nephrology
Renal Artery Stenosis Treatment Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
Global Nephroblastoma Treatment Market
Nephrology
Hemodialyzer Market
Nephrology
Ketoanalogue for Kidney Disease Market