
 Venous Skin Ulcer Treatment Market | 2026-2036
Venous Skin Ulcer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Venous Skin Ulcer Treatment Market Analysis
Market Context
CE marking under the EU Medical Device Regulation is hardening compliance thresholds for wound care manufacturers seeking European market access. Medtronic leverages its diversified medical technology portfolio to sustain competitive positioning across advanced wound management categories. Mölnlycke Health Care AB anchors its presence through specialized silicone foam dressings and established hospital supply chains. Smith & Nephew plc differentiates via bioactive wound healing technologies and strong ambulatory surgery center relationships.
Technical Definition and Segment Structure
Venous skin ulcer treatment encompasses clinical interventions for lower extremity wounds arising from chronic venous insufficiency, typically involving compression bandaging systems delivering 30-40 mmHg pressure, moisture-retentive dressings, and biological skin substitutes to restore dermal integrity. Compression therapy dominates product type revenue due to established clinical guidelines and reimbursement familiarity, while biological agents represent the fastest-expanding segment as platelet-rich plasma and living cell therapies gain procedural traction. Among end users, home care settings capture disproportionate growth as remote patient monitoring and portable negative pressure devices reduce hospital dependency.
Regulatory Framework and Outlook
The FDA oversees device clearance and biologic licensing for wound care innovations in the United States, while the EMA coordinates centralized assessments for advanced therapy medicinal products across European member states. Japan's PMDA maintains distinct quality management system requirements that shape market entry timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement codes for outpatient wound care and anticipate convergence between digital health regulations and traditional device pathways.
Market Dynamics
Compression therapy manufacturers face intensifying margin pressure as home care settings absorb hospital discharge volumes and reimbursement codes tighten outpatient payment windows. The shift from institutional to ambulatory wound management is compressing traditional supply chain markups.
Growth Catalysts
- Chronic Venous Insufficiency Prevalence:Aging demographics in Germany, Japan, and the United States sustain clinical caseloads for debridement and grafting procedures. Hospital systems prioritize same-day discharge protocols that expand portable negative pressure device utilization.
- EU Medical Device Regulation:CE marking under MDR is accelerating consolidation among wound care manufacturers unable to absorb quality management system upgrade costs. Surviving suppliers capture shelf space from exiting competitors.
- Silicone Foam Technology:Advanced moisture-retentive dressings reduce dressing change frequency and nursing labor hours. Home health agencies specify these materials in procurement contracts to control per-episode costs.
Market Restraints
- Biological Input Volatility:Platelet-rich plasma and living cell therapies depend on human-derived materials with unpredictable donor supply chains. Collection center capacity constraints limit manufacturing scale-up.
- Reimbursement Compression:Medicare's hospital outpatient prospective payment system reduces wound care procedure compensation annually. Ambulatory surgery centers defer advanced dressing adoption when margins erode below operational thresholds.
- Technical Limitation:Compression bandaging systems require trained application to achieve therapeutic pressure gradients. Patient non-adherence in unsupervised home settings undermines clinical efficacy and drives recurrence.
Strategic Opportunities
- Remote Patient Monitoring:Smartphone-connected wound imaging and biometric sensors enable asynchronous clinical oversight. Japan's PMDA digital health guidance creates regulatory clarity for device developers seeking home care market entry.
- Bioactive Convergence:Antimicrobial silver integration with alginate matrices addresses infection risk in diabetic foot complications. Wound clinics specify combination products that reduce pharmacy coordination burden.
- Underpenetrated Rural Networks:Telemedicine-linked compression therapy programs reach patients beyond specialist clinic catchment areas. Federally qualified health centers in the United States pilot hub-and-spoke models for ulcer management.
Industry Challenges
- Specialized Wound Care Nursing Shortage:Certification requirements for negative pressure wound therapy operation exceed available training program throughput. Home health agencies compete for licensed practitioners across overlapping service territories.
- Legacy Electronic Health Record Integration:Proprietary wound measurement tools fail to synchronize with dominant hospital information systems. Documentation friction delays reimbursement claims and extends accounts receivable cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venous Skin Ulcer Treatment Market |
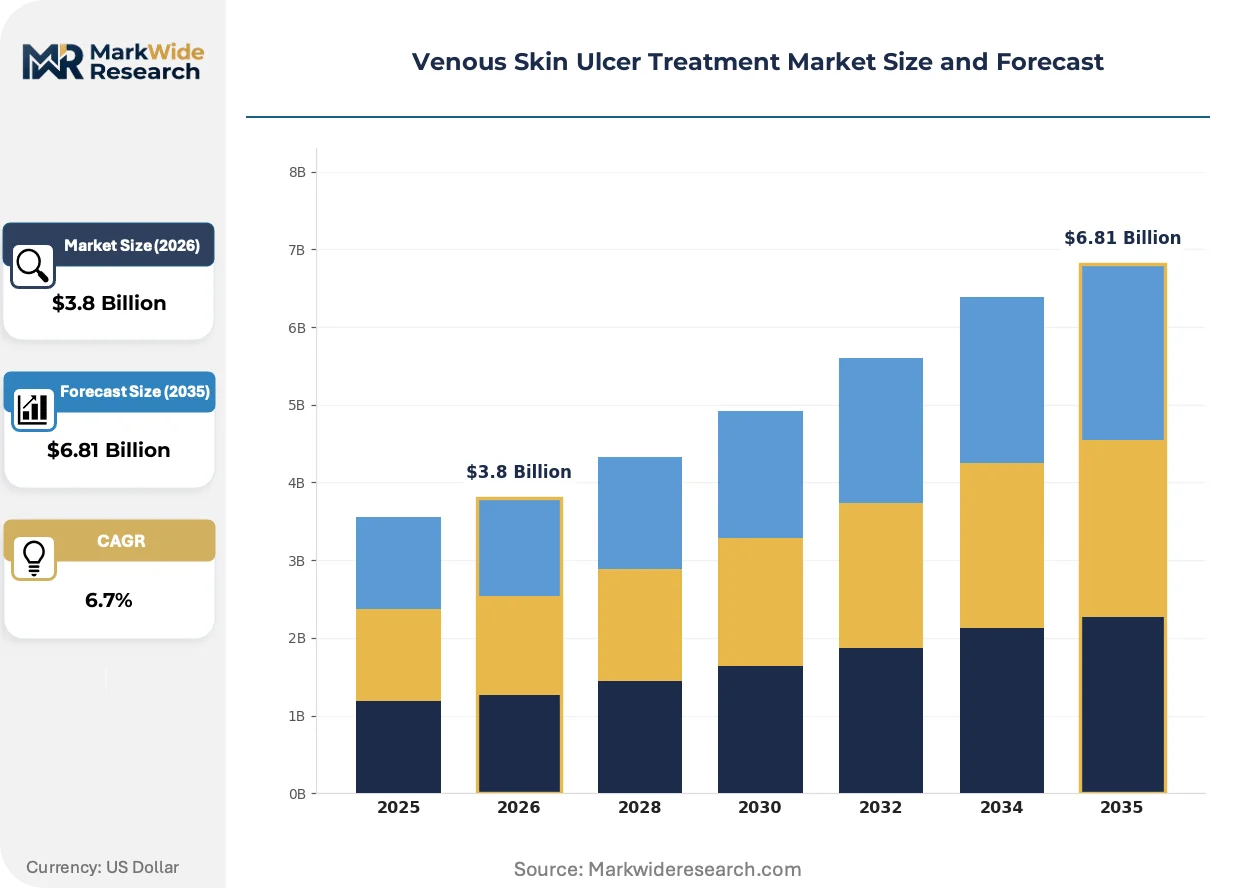
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Topical Treatments, Compression Therapy, Biological Agents End User: Hospitals, Home Care Settings, Clinics, Long-term Care Facilities Technology: Electrotherapy, Negative Pressure Wound Therapy, Hydrotherapy, Laser Therapy Application: Wound Management, Pain Relief, Infection Control, Skin Regeneration |
| Companies Covered | Medtronic, Mölnlycke Health Care AB, Smith & Nephew plc., Cardinal Health, SIGVARIS, Integra LifeSciences Corporation, Coloplast Corp., URGO Medical, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venous Skin Ulcer Treatment Market Emerging Trajectories
Wound care technology is pivoting from passive coverage to active biological intervention, with sensor integration and regenerative materials converging in product development pipelines. Regulatory pathways are fragmenting as digital therapeutics claim distinct classification categories.
Electrical stimulation devices for venous ulcer healing are electrifying clinical practice by delivering microcurrent therapy that accelerates granulation tissue formation. Wound care centers in the United States are integrating these systems into standard-of-care protocols for recalcitrant ulcers. The technology is electrifying competitive dynamics as device manufacturers compete for exclusive supply agreements with multi-site clinic networks.
Japan's PMDA revised its quality management system requirements for software-as-a-medical-device in wound monitoring applications. Foreign manufacturers must now demonstrate local post-market surveillance infrastructure before market authorization. Digital health developers with existing cardiovascular remote monitoring platforms are adapting submissions to capture wound care eligibility.
Hospital procurement departments are unbundling advanced dressing contracts from device and service agreements. Purchasing managers negotiate separate SKUs for foam, hydrocolloid, and antimicrobial categories rather than accepting bundled portfolios. This pattern concentrates in German hospital networks seeking granular cost-accounting for diagnosis-related group reimbursement optimization.
Venous Skin Ulcer Treatment Market Segmentation
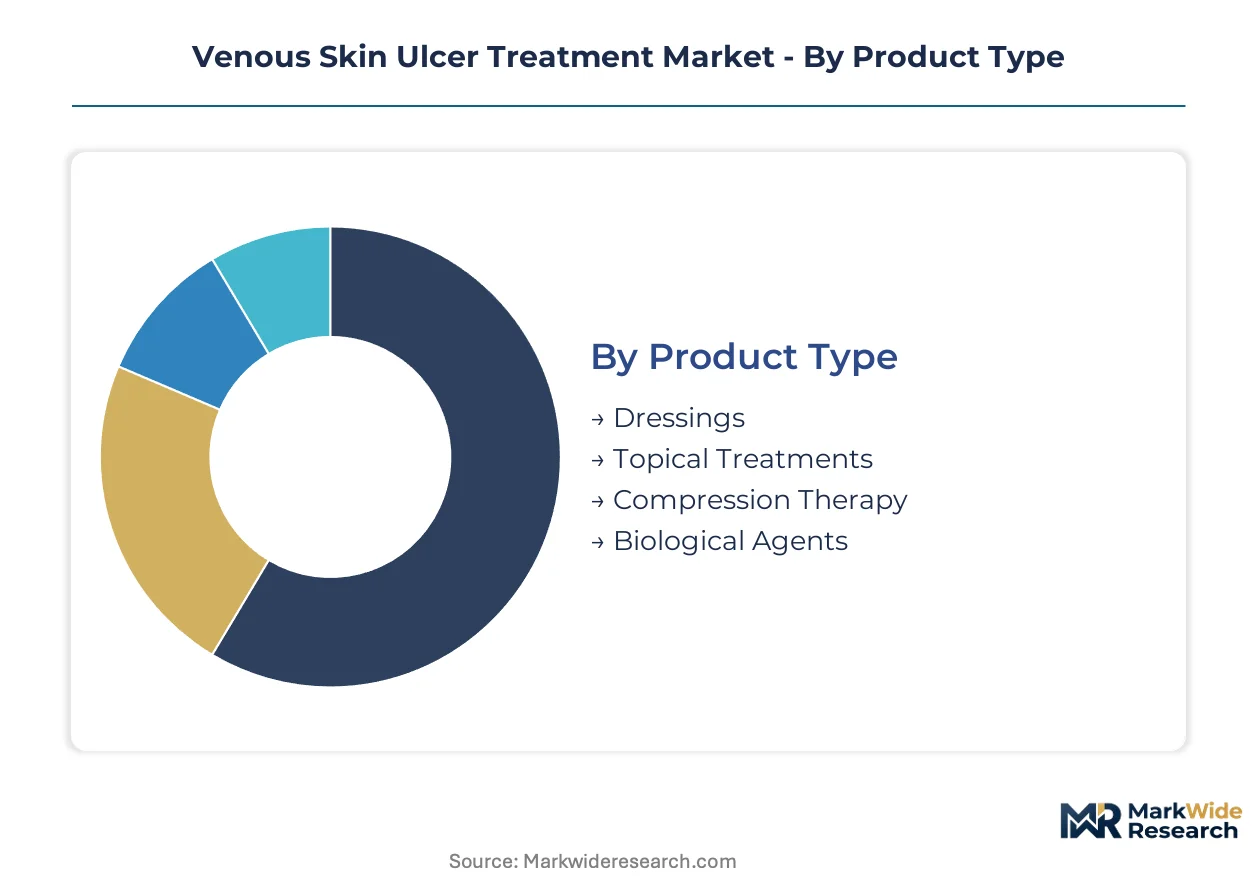
Venous skin ulcer treatment segmentation reveals divergent capital requirements across modalities, with biological manufacturing demanding specialized cleanroom infrastructure while compression systems leverage textile automation. Procurement patterns in Germany and Japan show hospitals prioritizing bundled device-service contracts, whereas United States home health agencies favor disposable-heavy SKUs for episode-based reimbursement.
Product Type:
Capital intensity varies dramatically across this category, with biological agents requiring GMP-certified bioreactor facilities and cryogenic logistics networks that compression manufacturers avoid entirely.
- Compression Therapy:Multi-layer bandaging systems and pneumatic pumps deliver calibrated pressure gradients through textile-wrapped bladders or elasticized fabrics. Demand concentrates in United States home care settings where Medicare's outpatient prospective payment system rewards same-day discharge protocols. Manufacturers face margin compression as procurement departments unbundle contracts into separate SKU negotiations.
- Biological Agents:Living cell therapies, platelet-rich plasma preparations, and bioengineered skin substitutes regenerate dermal architecture through active cellular intervention. German hospital networks absorb the highest volumes as diagnosis-related group reimbursement covers advanced interventions for refractory ulcers. Donor supply chain volatility constrains manufacturing scale-up.
- Dressings:Silicone foam, hydrocolloid, and alginate matrices manage exudate and moisture balance.
- Topical Treatments:Antimicrobial creams, growth factor gels, and enzymatic debriding agents address localized wound bed preparation.
Most installed capacity flows through Compression Therapy. Expansion is steepest in Biological Agents.
End User:
Customer type determines purchasing authority structure, with hospital procurement departments wielding volume leverage while home health agencies optimize per-episode labor efficiency.
- Home Care Settings:Patients receive portable negative pressure devices, compression bandaging supplies, and remote monitoring support in residential environments. Japan's aging demographic sustains clinical caseloads as METI promotes community-based care models. Smartphone-connected wound imaging reduces specialist clinic dependency.
- Hospitals:Acute care facilities perform debridement, grafting, and initial compression therapy application before discharge. United States hospital systems prioritize length-of-stay reduction, driving same-day procedure protocols. Operating room block scheduling limits wound care procedure access.
- Clinics:Outpatient wound centers provide specialized debridement and ongoing assessment.
- Long-term Care Facilities:Nursing homes manage chronic ulcer maintenance and prevention protocols.
Volume concentrates in Hospitals. Share gains are fastest in Home Care Settings.
Technology:
Technology selection reflects reimbursement coding sophistication, with negative pressure therapy enjoying established payment categories while electrotherapy navigates emerging code development.
- Negative Pressure Wound Therapy:Vacuum-assisted closure systems apply sub-atmospheric pressure to accelerate granulation tissue formation through macrostrain and microstrain mechanisms. German ambulatory surgery centers deploy portable units for post-discharge continuity. Device manufacturers compete for exclusive multi-site clinic network agreements.
- Electrotherapy:Microcurrent and pulsed electromagnetic field devices stimulate cellular migration and angiogenesis through bioelectrical intervention. United States wound care centers integrate these systems for recalcitrant ulcers resistant to standard protocols. FDA 510(k) clearance pathways shape competitive entry timelines.
- Hydrotherapy:Whirlpool and pulsatile lavage systems mechanically debride wound beds.
- Laser Therapy:Low-level light applications reduce bioburden and stimulate collagen synthesis.
Installed base dominates in Negative Pressure Wound Therapy. Adoption velocity peaks in Electrotherapy.
Application:
Application focus determines regulatory pathway selection, with infection control claims triggering antimicrobial registration requirements that wound management indications avoid.
- Wound Management:Comprehensive protocols encompassing debridement, moisture balance, and epithelial edge advancement. United States home health agencies specify advanced dressings in procurement contracts to control per-episode nursing labor costs. Documentation requirements for reimbursement claims create administrative friction.
- Infection Control:Antimicrobial silver, iodine, and PHMB-integrated dressings suppress bacterial bioburden in colonized ulcers. German hospital networks prioritize combination products that reduce pharmacy coordination burden. EMA quality management system requirements under MDR harden compliance thresholds.
- Pain Relief:Analgesic-impregnated dressings and cooling hydrogels address procedural and chronic discomfort.
- Skin Regeneration:Growth factor delivery and cellular matrix applications restore dermal integrity.
Clinical volume flows predominantly through Wound Management. Investment intensity is highest in Skin Regeneration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wound care specialists concentrate in Germany's industrial corridors, Japan's metropolitan hospital networks, and United States ambulatory surgery clusters. These talent pools anchor regional market development and shape procurement sophistication.
United States
Medicare's hospital outpatient prospective payment system drives same-day discharge protocols for venous ulcer procedures. FDA digital health guidance for software-as-a-medical-device creates regulatory clarity for remote wound monitoring developers. Wound care centers in Florida and Arizona absorb disproportionate clinical volumes from snowbird populations with chronic venous insufficiency.
Germany
Diagnosis-related group reimbursement covers advanced biological interventions for refractory ulcers in hospital networks. EMA centralized assessments under the Medical Device Regulation harden compliance thresholds for CE marking renewal. Medical technology clusters in North Rhine-Westphalia and Bavaria host concentrated manufacturing capacity for compression bandaging systems.
Japan
METI community-based care models shift ulcer management from acute facilities to residential settings. PMDA quality management system requirements for wound monitoring software demand local post-market surveillance infrastructure. Tokyo and Osaka metropolitan areas concentrate specialist wound clinics serving the country's most aged demographic cohorts.
United Kingdom
NHS England's wound care transformation program prioritizes community nursing capacity for leg ulcer management. MHRA post-Brexit regulatory autonomy diverges from EU MDR implementation timelines for device manufacturers. London and Manchester hospital trusts pilot hub-and-spoke telemedicine models linking specialist centers to peripheral clinics.
France
Regional health agencies coordinate chronic wound care pathways through territorial hospital group networks. ANSM vigilance reporting requirements shape post-market surveillance obligations for biological dressing manufacturers. Lyon and Marseille medical device clusters support specialized logistics for temperature-sensitive regenerative materials.
Venous Skin Ulcer Treatment Market Vendor Landscape
The competitive structure tilts toward diversified medical technology conglomerates with wound care as a portfolio segment. Tiered specialization separates integrated device-service providers from component-focused material suppliers. Three archetypes dominate: diversified conglomerates leveraging cross-category procurement relationships, specialized wound care pure-plays with silicone foam expertise, and regional compression therapy manufacturers with textile automation advantages. Consolidation accelerates through M&A among mid-scale players unable to absorb regulatory compliance upgrade costs, while exclusive supply agreements lock up multi-site clinic network access.
Among diversified medical technology conglomerates, Medtronic and Smith & Nephew plc exemplify the integrated portfolio approach. Mölnlycke Health Care AB occupies a specialized position within the advanced dressing segment. These three anchors represent distinct strategic postures: conglomerate breadth, wound-specific depth, and regional manufacturing scale respectively.
| Leading Market Players |
|---|
| Medtronic |
| Mölnlycke Health Care AB |
| Smith & Nephew plc. |
| Cardinal Health |
| SIGVARIS |
| Integra LifeSciences Corporation |
| Coloplast Corp. |
| URGO Medical |
| 3M |
| Others |
Supply Flow & Price Mechanics
Human-derived biological materials flow through cryogenic logistics networks from collection centers to GMP-certified bioreactor facilities, with donor supply volatility compressing margins on regenerative therapies while textile-automated compression systems maintain steadier cost structures across premium, standard, and economy tiers.
Pricing Analysis
Bundled device-service contracts dominate hospital procurement in Germany and Japan, while unbundled SKU negotiations prevail among United States home health agencies optimizing per-episode reimbursement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EU MDR and FDA pathways, with premium tiers commanding advantage from bioactive convergence features. Cost compression in biological agents is intensifying because donor supply chain constraints limit manufacturing scale-up. Home care settings exhibit highest price sensitivity due to episode-based reimbursement ceilings, whereas hospital networks absorb premium pricing for refractory ulcer interventions covered under diagnosis-related group codes.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital procurement departments and German hospital networks mandate multi-supplier qualification for compression textiles and silicone foam substrates, reducing single-source vulnerability. Manufacturing concentrates in Germany for compression bandaging systems, the United States for negative pressure wound therapy devices, and Japan for wound monitoring software. Raw material flows draw from medical-grade elastomer suppliers, antimicrobial silver compound producers, and human tissue collection centers. Tariff exposure on Chinese-sourced alginate matrices and textile components elevates landed cost volatility. Distribution runs through specialized medical device distributors and group purchasing organizations with exclusive multi-site clinic network agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through silicone foam technology adoption that reduces dressing change frequency and nursing labor hours, while biological manufacturing scale-up creates premium-tier pricing power for regenerative therapies.
For Market Incumbents: Anchor market position through backward integration into textile automation for compression systems and captive supply of GMP-certified bioreactor capacity for biological agents. Defend against emerging digital health entrants by securing exclusive supply agreements with multi-site wound clinic networks and investing in FDA 510(k) pathways for smartphone-connected monitoring devices. For New Entrants and Emerging Players: Enter via remote patient monitoring platforms adapted from cardiovascular applications, targeting Japan's PMDA digital health guidance clarity for software-as-a-medical-device authorization. White-space concentrates in underpenetrated rural United States networks through telemedicine-linked compression therapy hub-and-spoke models, with go-to-market leverage through federally qualified health center pilot programs. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance upgrade costs under EU MDR exceed mid-scale wound care manufacturer balance sheet capacity. Long-term viability favors diversified conglomerates with cross-category procurement relationships and specialized pure-plays with silicone foam expertise. Acquisition target archetype: regional compression therapy manufacturers with textile automation advantages seeking CE marking renewal capital. Signal to watch: hospital procurement department unbundling velocity accelerating SKU-level negotiation granularity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance investment captures shelf space from exiting competitors in German hospital networks. |
| Hospital System Partnership | Exclusive supply agreements with multi-site clinic networks lock up ambulatory surgery center volumes. |
| Software Companion Development | Smartphone-connected wound imaging reduces specialist clinic dependency for Japan's METI community care models. |
| Reimbursement Strategy | Medicare outpatient prospective payment system alignment drives same-day discharge protocol adoption. |
| FDA Submission | 510(k) clearance for electrical stimulation devices secures standard-of-care protocol integration in United States wound centers. |
Methodological Framework
Bottom-up home care setting modeling reconciled against top-down compression therapy manufacturer tracking forms the analytical core of this study. Primary interviews with wound care clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA centralized assessment databases, CMS Medicare reimbursement codes, and hospital procurement contract registries. Triangulation between demand-side episode data and supply-side production capacity estimates ensures cross-verification of volume assumptions.
Historical trendline analysis of compression therapy adoption rates and biological agent procedural volumes established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, end user category, technology modality, and application focus with regional regulatory cluster differentiation. CAGRs derive from curve-fitting observed adoption velocities against demographic-driven prevalence projections for chronic venous insufficiency. Forecast inputs incorporate PMDA digital health guidance evolution and Medicare outpatient payment system revision trajectories.
Inputs from EMA MDR implementation timelines and FDA software-as-a-medical-device guidance documents were available through the study window; gaps in real-time donor supply chain capacity data introduce uncertainty bands around biological agent manufacturing scale-up assumptions. Deviation in Japan's METI community-based care funding allocation or Medicare's hospital outpatient prospective payment system wound care procedure compensation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Global Negative Pressure Wound Therapy (NPWT) Devices Market
Wound Care
Bioadhesive Wound Care Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Bioactive Wound Dressing Market
Wound Care
Wound Closure Strips Market
Wound Care
France Wound Care Market
Wound Care
Vascular Ulcer Treatment Market
Wound Care
Next Generation Wound Closure Device Market
Wound Care
Surgical Dressing Market
Wound Care
Burn Care Centers Market
Wound Care
Global Active Wound Care Market
Wound Care
Advanced Wound Management Market
Wound Care
United States Negative Pressure Wound Therapy Market
Wound Care
Europe Compression Bandages Market
Wound Care
Middle East and Africa Advanced Wound Care Market