
 Kidney Stone Extraction Balloon Market | 2026-2036
Kidney Stone Extraction Balloon Market Size, Share, and Industry Trends Forecast 2026-2036
Kidney Stone Extraction Balloon Market Foresight
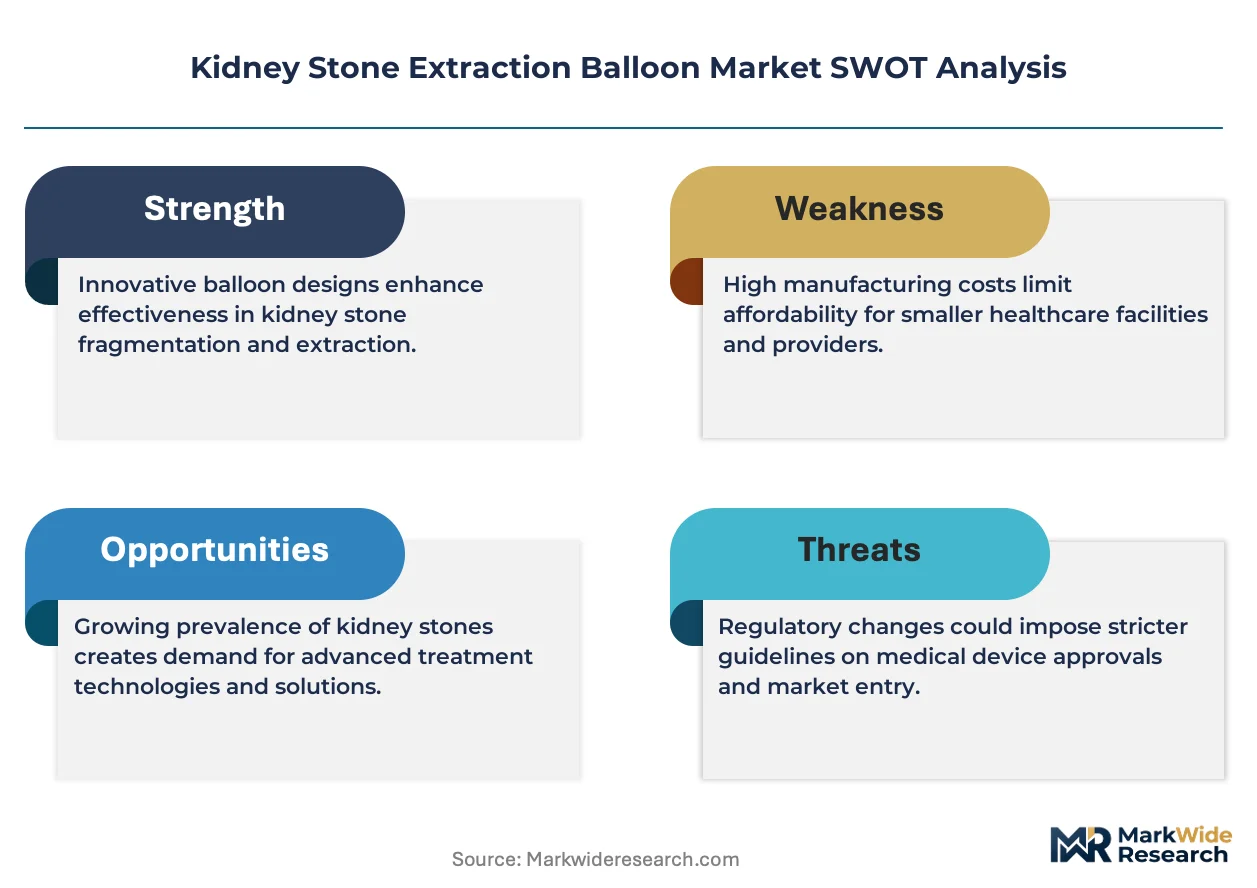
Aftermarket service revenue for lithotripsy systems is fragmenting as hospitals extend equipment lifecycles and seek disposable-centric procurement models. Boston Scientific Corporation leverages its integrated urology portfolio to sustain recurring revenue through balloon catheter replenishment programs. Cook Medical anchors its position via specialized manufacturing scale in minimally invasive extraction devices. Coloplast differentiates through channel control across European hospital networks.
A kidney stone extraction balloon is a compliant elastomeric catheter device, typically constructed from latex or silicone with inflation diameters ranging from 12 Fr to 18 Fr, designed to capture and remove renal calculi through ureteroscopic or percutaneous access. Its primary commercial purpose is to provide atraumatic stone entrapment and retrieval during endourological procedures. Single-use balloons dominate procurement budgets due to infection control mandates, while expandable balloons represent the fastest-growing product category as physicians demand adaptive sizing for complex calyceal anatomy. Robotic-assisted delivery systems command premium positioning as hospitals integrate surgical automation platforms.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product validation timelines and clinical evidence thresholds for market entry. ISO 13485 quality management certification functions as a baseline qualifier for supplier qualification by major hospital purchasing consortia. Stakeholders must monitor reimbursement coding revisions for ureteroscopic stone management procedures as these directly influence hospital capital allocation for extraction device inventories.
Market Dynamics
The transition from reusable to single-use extraction balloons is compressing hospital sterilization infrastructure requirements while amplifying disposable procurement volumes. Manufacturers now compete on balloon compliance characteristics and catheter trackability rather than capital equipment service contracts.
Growth Catalysts
- FDA 510(k) clearance streamlining:Expedited review pathways for predicate device submissions accelerate product iterations and reduce time-to-revenue for balloon design modifications targeting specific calyceal anatomies.
- Endourology suite expansion:Ambulatory surgical centers in the United States are adding dedicated stone management capabilities, creating new point-of-care demand for compact extraction balloon inventories.
- Silicone elastomer substitution:Latex-free material transitions address allergy protocols in European hospital networks while improving balloon wall thickness consistency for precise inflation control.
Market Restraints
- EU MDR technical documentation burdens:Clinical evidence requirements for Class IIa devices extend validation timelines and inflate regulatory affairs staffing costs for manufacturers below 500 employees.
- Natural rubber latex price volatility:Malaysian plantation output fluctuations transmit directly to input cost instability for manufacturers maintaining dual material platforms.
- Single-source catheter shaft suppliers:Japanese precision extrusion houses control high-torque tubing specifications, creating concentration risk for European device assemblers.
Strategic Opportunities
- India's CDSCO device registration acceleration:Streamlined import licensing for predicate-approved urology devices opens private hospital procurement channels in Mumbai and Delhi NCR corridors.
- Robotic ureteroscope integration:Balloon catheter compatibility with Intuitive Surgical's da Vinci single-port platforms commands premium positioning in academic medical center tenders.
- Japan's aging urologist workforce:Prefecture-level training subsidies for minimally invasive stone procedures expand addressable procedural volume in secondary cities.
Industry Challenges
- ISO 13485 auditor availability:Notified body capacity constraints delay quality management recertification for mid-tier manufacturers, freezing new product submissions.
- Legacy lithotripsy system interfacing:Balloon retrieval compatibility with fifteen-year-old Storz and Olympus endoscope channels requires maintained engineering support for obsolete connector geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kidney Stone Extraction Balloon Market |
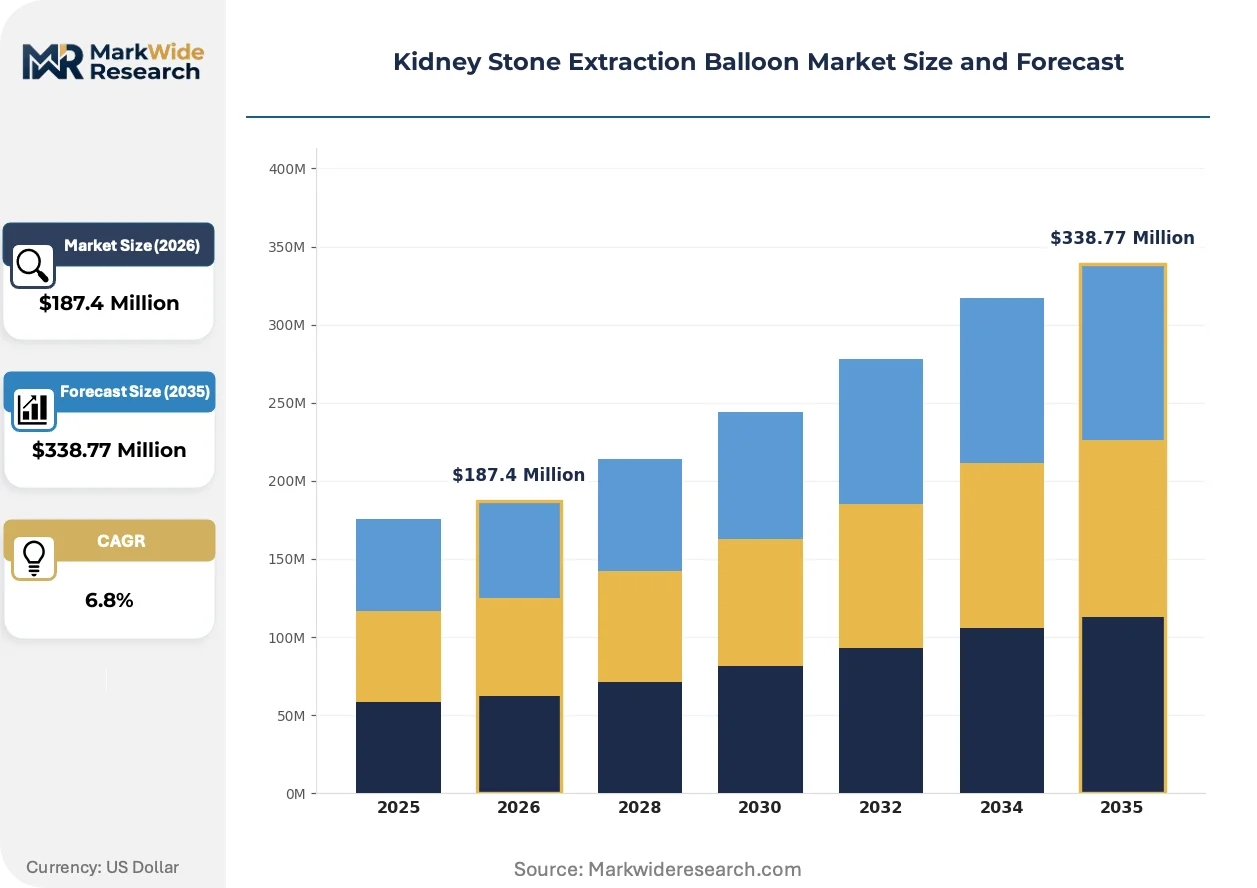
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use Balloons, Reusable Balloons, Expandable Balloons, Standard Balloons End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Delivery Mode: Manual Delivery, Automated Delivery, Robotic-Assisted Delivery, Local Anesthesia Technology: Hydraulic Systems, Pneumatic Systems, Electromechanical Systems, Laser-assisted Systems |
| Companies Covered | Boston Scientific Corporation, Cook Medical, Inc., Coloplast Ltd., Teleflex Incorporated, iVascular SLU, Med Pro Medical B.V., NuAngle, BD, OLYMPUS CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kidney Stone Extraction Balloon Market Shifts & Advancements
Digital integration of procedural workflows is reshaping how extraction balloons are specified, tracked, and replenished across hospital supply chains. Three developments merit particular attention.
Compliant balloon inflation pressure sensing is digitizing real-time tactile feedback during stone entrapment. Urology departments in German university hospitals are piloting sensor-integrated catheters that transmit inflation dynamics to console displays, reducing fluoroscopy exposure and enabling standardized force application across resident training cohorts. This capability is compressing the learning curve for complex lower pole calyceal access.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up for legacy balloon designs previously grandfathered under the Medical Devices Directive. Manufacturers must now maintain active implant registries or procedural outcome databases, which is elevating documentation costs most acutely for product lines with decade-plus commercial histories. French and Italian notified bodies are enforcing this most stringently.
Hospital purchasing consortia are consolidating balloon catheter specifications around standardized French sizes and connector interfaces. Group purchasing organizations in the United States are displacing individual hospital preference cards with formulary compliance mandates, compressing supplier count per metropolitan market. This concentration is most visible in Texas and Florida health systems where IDN consolidation has proceeded fastest.
Kidney Stone Extraction Balloon Market Segmentation
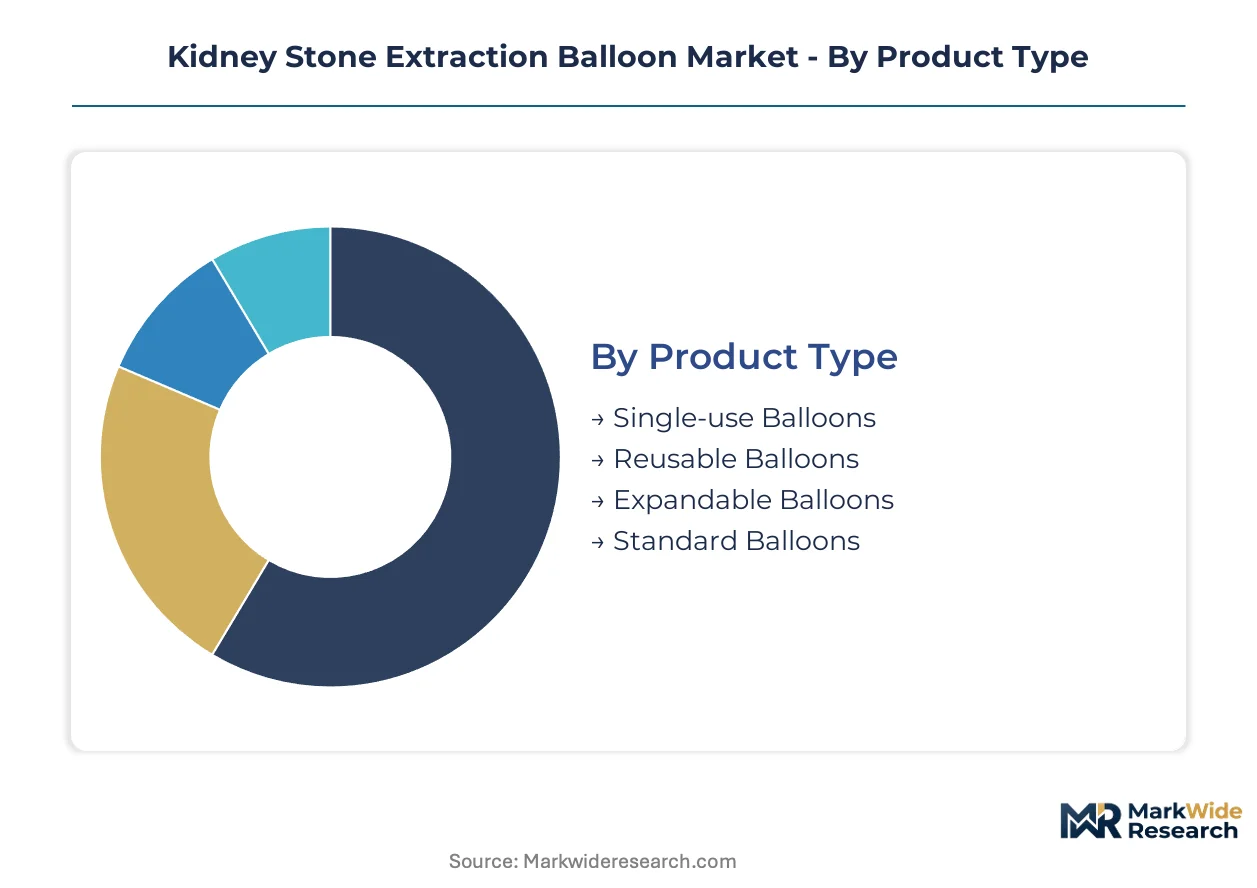
Segmentation in the kidney stone extraction balloon market reflects divergent procurement priorities across infection control mandates, capital equipment strategies, and surgical workflow integration. Hospital purchasing committees evaluate balloons through lenses of procedural volume, sterilization infrastructure, and compatibility with existing endoscope inventories.
Product Type:
The use-case spectrum spans emergency departments requiring immediate availability through academic centers optimizing for complex calyceal anatomy.
- Single-use Balloons:Constructed from medical-grade silicone or latex with pre-sterilized packaging, these devices eliminate cross-contamination risk in high-throughput stone management programs. Demand concentrates in United States ambulatory surgical centers where Joint Commission infection protocols and limited sterilization staffing create preference for disposable workflows.
- Expandable Balloons:Adaptive diameter inflation mechanisms accommodate variable ureteral and renal pelvis geometries during single-procedure stone retrieval. Adoption is accelerating fastest in German university hospitals where complex lower pole calyceal access cases require precise balloon sizing without catheter exchange.
- Reusable Balloons:Elastomeric devices designed for 50-100 cycle sterilization, primarily serving cost-constrained hospital systems in India with established central sterile processing departments.
- Standard Balloons:Fixed-diameter configurations for routine ureteroscopic stone extraction, dominating procurement volumes in Japan's prefecture hospitals with standardized procedural protocols.
Established volume favors Single-use Balloons; emerging adoption favors Expandable Balloons.
End User:
Customer type determines packaging specifications, inventory minimums, and clinical training support requirements.
- Hospitals:Integrated urology departments with 24/7 stone management capabilities, driving bulk procurement contracts and dedicated storage for multiple French sizes. United States health systems with over 500 beds maintain highest per-facility inventory levels.
- Ambulatory Surgical Centers:Same-day discharge facilities with space-constrained supply rooms, prioritizing compact packaging and just-in-time replenishment through distributor partnerships.
- Specialty Clinics:Urology-focused outpatient settings with selective stone management services, typically stocking 12 Fr and 15 Fr sizes exclusively.
- Research Institutions:Academic medical centers with IRB-approved device evaluation protocols, sourcing prototype configurations and sensor-integrated variants for clinical validation studies.
Procurement concentration sits with Hospitals; volume growth is climbing the fastest in Ambulatory Surgical Centers.
Delivery Mode:
Margin profiles diverge sharply between manual catheter advancement and capital-intensive robotic platform integration.
- Manual Delivery:Physician-controlled catheter advancement through rigid or flexible ureteroscopes, requiring tactile skill but minimizing capital expenditure. Dominates Japanese procedural volumes where experienced urologist cohorts resist automation.
- Robotic-Assisted Delivery:Integration with surgical automation platforms enabling tremor-filtered catheter positioning and standardized force application. Premium positioning in United States academic medical centers with da Vinci single-port system deployments.
- Automated Delivery:Motorized catheter advancement with programmable insertion depth limits, gaining evaluation in German hospitals for resident training standardization.
- Local Anesthesia:Conscious sedation protocols with patient-controlled analgesia, expanding addressable procedures in European day-surgery units without anesthesiologist coverage.
Manual Delivery retains installed base dominance; Robotic-Assisted Delivery commands the steepest expansion trajectory.
Technology:
Maturity gradients separate decades-proven hydraulic mechanisms from electromechanical innovations seeking clinical validation.
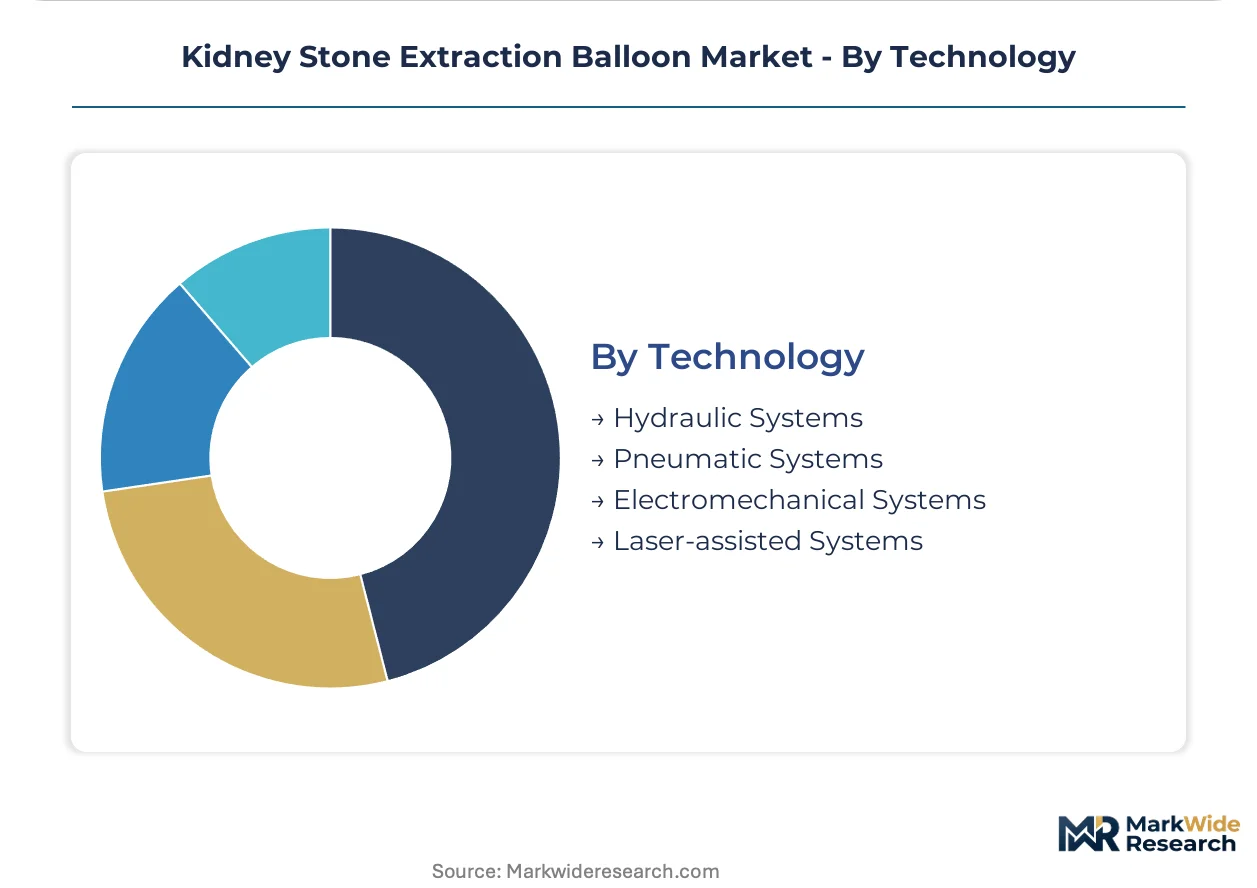
- Hydraulic Systems:Saline-filled inflation lumens with manual syringe control, offering predictable compliance characteristics and minimal failure modes. Sustains majority share in European hospital networks with conservative technology adoption profiles.
- Pneumatic Systems:Compressed gas inflation with rapid deflation capability for stone release optimization, preferred in high-volume Japanese centers prioritizing procedural throughput.
- Electromechanical Systems:Motor-driven inflation with pressure feedback displays, piloting in German university hospitals for fluoroscopy reduction and resident training.
- Laser-assisted Systems:Integrated lithotripsy-balloon combinations for simultaneous fragmentation and retrieval, confined to research protocols pending regulatory clearance.
Hydraulic Systems anchor current procurement; Electromechanical Systems are gaining share fastest among technology-forward institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across procurement environments. United States health systems absorb premium pricing for robotic-compatible balloons, while Indian hospitals prioritize cost-per-procedure metrics that favor reusable configurations.
United States
Ambulatory surgical centers in Texas and Florida are expanding dedicated stone management suites, driving compact inventory requirements. FDA 510(k) clearance pathways enable rapid product iteration for predicate device submissions. Academic medical centers in Boston and Houston are piloting sensor-integrated catheters for fluoroscopy reduction.
Germany
University hospitals in Bavaria and Baden-Württemberg prioritize adaptive sizing technologies for complex lower pole calyceal access. EU MDR technical documentation requirements extend validation timelines for Class IIa devices. The Munich-Stuttgart corridor concentrates electromechanical balloon development programs.
Japan
Prefecture-level training subsidies for minimally invasive stone procedures expand procedural volume in secondary cities beyond Tokyo and Osaka. PMDA consultation procedures shape clinical evidence requirements for novel balloon designs. The Nagoya medical device cluster supports precision extrusion capabilities for high-torque catheter shafts.
India
Private hospital procurement channels in Mumbai and Delhi NCR corridors are opening under streamlined CDSCO import licensing for predicate-approved devices. Cost constraints sustain demand for reusable balloons in central sterile processing departments. The Bangalore-Chennai corridor hosts contract manufacturing for European device assemblers.
United Kingdom
NHS supply chain consolidation around standardized French sizes is compressing supplier counts per metropolitan market. MHRA post-market surveillance alignment with EU MDR elevates documentation obligations for legacy designs. The Oxford-Cambridge arc generates clinical validation data for sensor-integrated prototypes.
Kidney Stone Extraction Balloon Market Competitive Landscape
Capability concentration sits with specialized elastomeric device manufacturers; scale advantage sits with diversified urology portfolio holders. The market structures around three tiers: integrated multinationals with recurring revenue programs, mid-tier specialists with regional manufacturing scale, and emerging entrants targeting regulatory arbitrage in accelerated approval jurisdictions. Dominant competitive moves include portfolio diversification into complementary stone management devices and backward integration into catheter shaft extrusion capabilities.
Among integrated urology portfolio holders, Boston Scientific Corporation exemplifies recurring revenue architecture through replenishment program design. Cook Medical, Inc. occupies a position within specialized manufacturing scale archetypes for minimally invasive extraction devices. Coloplast Ltd. anchors channel control strategies across European hospital procurement networks.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Cook Medical, Inc. |
| Coloplast Ltd. |
| Teleflex Incorporated |
| iVascular SLU |
| Med Pro Medical B.V. |
| NuAngle |
| BD |
| OLYMPUS CORPORATION |
| Others |
Supply & Pricing Matrix
Single-source catheter shaft dependency on Japanese precision extrusion houses compresses pricing tier spreads while forcing European device assemblers into premium positioning for balloon catheter replenishment programs. This concentration risk simultaneously elevates input cost volatility and shapes three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Aftermarket replenishment revenue for balloon catheter inventories drives lifetime value capture for integrated urology portfolio holders. Pricing stratifies across premium, standard, and economy tiers based on silicone elastomer wall thickness consistency and FDA 510(k) predicate tier certification. Cost compression in standard-tier configurations is intensifying because Malaysian natural rubber latex price volatility transmits directly to dual-material platform manufacturers. Ambulatory surgical centers in United States metropolitan markets exhibit highest price sensitivity, while academic medical centers with robotic platform integration absorb premium positioning.
Supply Chain Analysis
Tariff exposure between Malaysia and European device assemblers dominates input cost instability for latex-dependent balloon production. Manufacturing gravity centers on Japan for high-torque catheter shaft extrusion, Germany for electromechanical system assembly, and India for contract manufacturing serving European device assemblers. Raw material sourcing draws from Malaysian plantation rubber, medical-grade silicone from German chemical suppliers, and precision extrusion alloys from Japanese metallurgical houses. Single-source vulnerability in Japanese precision extrusion creates concentration risk for European device assemblers lacking backward integration into catheter shaft capabilities. Distribution runs through group purchasing organizations in United States health systems and specialized urology distributors in European hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where robotic ureteroscope interoperability standards are displacing standalone balloon catheter specifications with integrated surgical automation workflows.
For Market Incumbents: Build switching-cost moats through catheter shaft extrusion backward integration that captive-supplies high-torque tubing specifications currently controlled by Japanese precision houses. Threat from emerging entrants with CDSCO-accelerated predicate approvals in Indian private hospital corridors demands defensive capacity positioning in Mumbai and Delhi NCR distribution nodes. Priority lever rests on ISO 13485 quality management recertification investment to freeze mid-tier competitor product submissions during notified body capacity constraints. For New Entrants and Emerging Players: Pursue regulatory arbitrage through India's streamlined CDSCO import licensing for predicate-approved urology devices, targeting private hospital procurement channels in Mumbai and Delhi NCR corridors with cost-per-procedure metrics favoring reusable balloon configurations. Most penetrable segment sits with India's central sterile processing departments sustaining demand for 50-100 cycle sterilization devices. Go-to-market angle leverages European contract manufacturing relationships through Bangalore-Chennai corridor assembly partnerships. For Investors and Strategic Acquirers: Specialized elastomeric device manufacturers with regional manufacturing scale and EU MDR technical documentation capabilities represent the acquisition target archetype with defensible positioning. Long-term viability frames around robotic platform compatibility standardization and sensor-integrated catheter validation over the next decade. Signal to watch is Intuitive Surgical da Vinci single-port system deployment velocity in United States academic medical center tenders as inflection indicator for premium balloon catheter demand.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Expedited predicate device pathways compress time-to-revenue for balloon design modifications targeting specific calyceal anatomies. |
| EU MDR Technical Documentation Investment | Class IIa device validation capabilities elevate barriers for manufacturers below 500 employees in European hospital networks. |
| Hospital System Partnership | GPO formulary compliance mandates in Texas and Florida health systems displace individual hospital preference cards with standardized specifications. |
| Software Companion Development | Sensor-integrated inflation pressure displays enable fluoroscopy reduction and resident training standardization in German university hospitals. |
| Reimbursement Strategy | Coding revisions for ureteroscopic stone management procedures directly influence hospital capital allocation for extraction device inventories. |
Research Methodology
A standing panel of urology department heads, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against operating reality throughout the analysis window. Primary interview intelligence combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement coding revisions. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market size estimation.
Scenario-bracketing around regulatory approval velocity, robotic platform adoption curves, and sterilization infrastructure investment cycles framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, end user facility category, delivery mode, and technology platform, with regional regulatory cluster effects incorporated throughout the forecast period. CAGRs derived from procedure volume elasticity against reimbursement rate trajectories and capital equipment replacement cycles, with electromechanical system penetration and sensor-integrated catheter adoption as industry-specific forecast inputs.
Sensitivities concentrate around EU MDR notified body capacity constraints, Malaysian natural rubber latex price volatility, and Intuitive Surgical platform interoperability standard revisions. Forecasts reflect documented assumptions regarding ambulatory surgical center expansion velocity and Japan's prefecture-level training subsidy continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Glomerulonephritis Treatment Market
Nephrology
Global Diabetic Nephropathy Market
Nephrology
Renal Anemia Treatment Market
Nephrology
Renal Artery Stenosis Treatment Market
Nephrology
US Dialysis Centers Market
Nephrology
Kidney Transplant Market
Nephrology
Hemodialysis Services Market
Nephrology
Global Dialysis Market
Nephrology
South Africa Hemodialysis and Peritoneal Dialysis Market
Nephrology
Global Hemodialysis Market
Nephrology
Kidney Transplant Medicine Market
Nephrology
Hollow Fiber Dialyzers Market
Nephrology
Renal Denervation Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
US Dialysis Services Market
Nephrology
Kidney/Renal Function Test Market