
 Proteinuria Treatment Market | 2026-2036
Proteinuria Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Proteinuria Treatment Market Analytics
Combination therapy bundling is pivoting how payers and clinicians evaluate proteinuria protocols. Pfizer leverages its cardiovascular portfolio to anchor bundled ACE inhibitor and ARB offerings. AstraZeneca competes through SGLT2 adjacency programs that extend into renal protective indications. Bristol-Myers Squibb differentiates via immunology pipelines addressing proteinuria secondary to lupus nephritis.
Proteinuria treatment encompasses pharmacological and non-pharmacological interventions targeting abnormal urinary protein excretion exceeding 150 mg per day, with albumin-to-creatinine ratio serving as the primary diagnostic threshold. ACE Inhibitors and ARBs retain the largest share of pharmacological prescribing due to established renoprotective evidence, while SGLT2 inhibitors are displacing earlier lines in diabetic kidney disease protocols. Injectable delivery modes represent the fastest-expanding segment as biologic agents for refractory glomerular disease advance through clinical development. Combination Therapy approaches command premium positioning where polypharmacy reduces progression to end-stage renal disease.
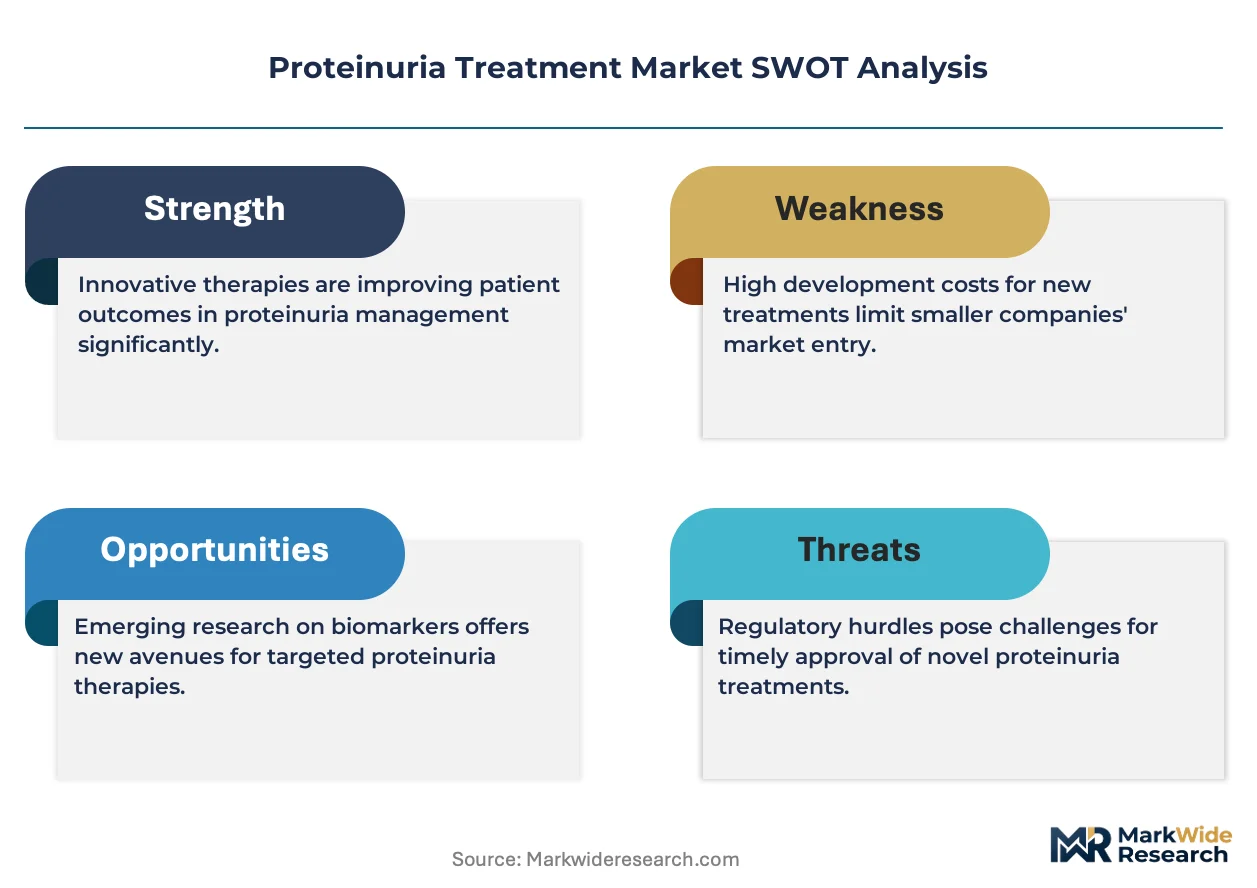
The FDA maintains stringent renal outcome trial requirements that shape Phase III design and payer evidence standards. EMA's MDR and pharmacovigilance frameworks govern post-market surveillance for nephrotoxicity signals across European markets. Stakeholders must monitor evolving surrogate endpoint acceptance criteria that could compress development timelines or expand label indications without hard renal outcome data.
Market Dynamics
The FDA's accelerated approval pathways for chronic kidney disease therapeutics are compressing development timelines while simultaneously elevating evidence standards for surrogate endpoints, forcing manufacturers to front-load investment in biomarker validation.
Growth Catalysts
- Surrogate Endpoint Acceptance:The FDA's evolving framework for albuminuria as a valid surrogate endpoint in renal outcome trials is shortening Phase III durations for novel agents. This regulatory flexibility accelerates patient access to proteinuria-modifying therapies.
- Integrated Care Networks:Hospital systems in the United States are consolidating nephrology services into dedicated renal centers of excellence. These networks create standardized protocols that drive formulary adoption of combination ACE inhibitor and ARB regimens.
- SGLT2 Inhibitor Class Expansion:Cardiorenal protective indications for sodium-glucose cotransporter-2 inhibitors are displacing earlier-line diabetic kidney disease protocols. This mechanism shift expands addressable patient populations beyond traditional proteinuria thresholds.
Market Restraints
- Specialized Manufacturing Concentration:Active pharmaceutical ingredient production for renin-angiotensin system modulators concentrates among contract manufacturers in India and China. Geopolitical friction or supply chain disruptions at these nodes create vulnerability for formulated product availability.
- Biologic Cold Chain Requirements:Investigational monoclonal antibodies for refractory glomerular disease require temperature-controlled distribution infrastructure that remains underdeveloped in rural healthcare markets. Last-mile logistics constraints limit trial enrollment and commercial reach.
- Reimbursement Compression:Medicare's Inflation Reduction Act price negotiation provisions are applying downward pressure on established small-molecule proteinuria agents. Margin erosion threatens R&D reinvestment capacity for incremental innovation.
Strategic Opportunities
- Home-Based Monitoring Integration:Albumin-to-creatinine ratio testing via smartphone-connected dipstick readers is enabling remote disease management. This channel innovation opens direct-to-patient engagement models outside traditional clinic-based specialty pharmacy.
- Immunology-Renal Convergence:Biologic pipelines targeting lupus nephritis and IgA nephropathy are creating adjacency opportunities for proteinuria specialists. Technology convergence between immunology and nephrology departments is dissolving traditional therapeutic area boundaries.
- European Orphan Designation Pathways:The EMA's incentives for rare renal disease indications are attracting development investment in primary glomerular disorders. This regulatory tailwind supports premium pricing for ultra-orphan proteinuria segments.
Industry Challenges
- Biomarker Standardization Delays:Variability in albuminuria measurement methodologies across clinical laboratories complicates multi-site trial data harmonization. ISO 15189 accreditation gaps at regional reference centers create protocol deviations.
- Nephrotoxicity Signal Detection:Post-market pharmacovigilance requirements under the EU MDR mandate real-world safety surveillance that strains safety database infrastructure. Smaller developers lack pharmacovigilance system master file capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proteinuria Treatment Market |
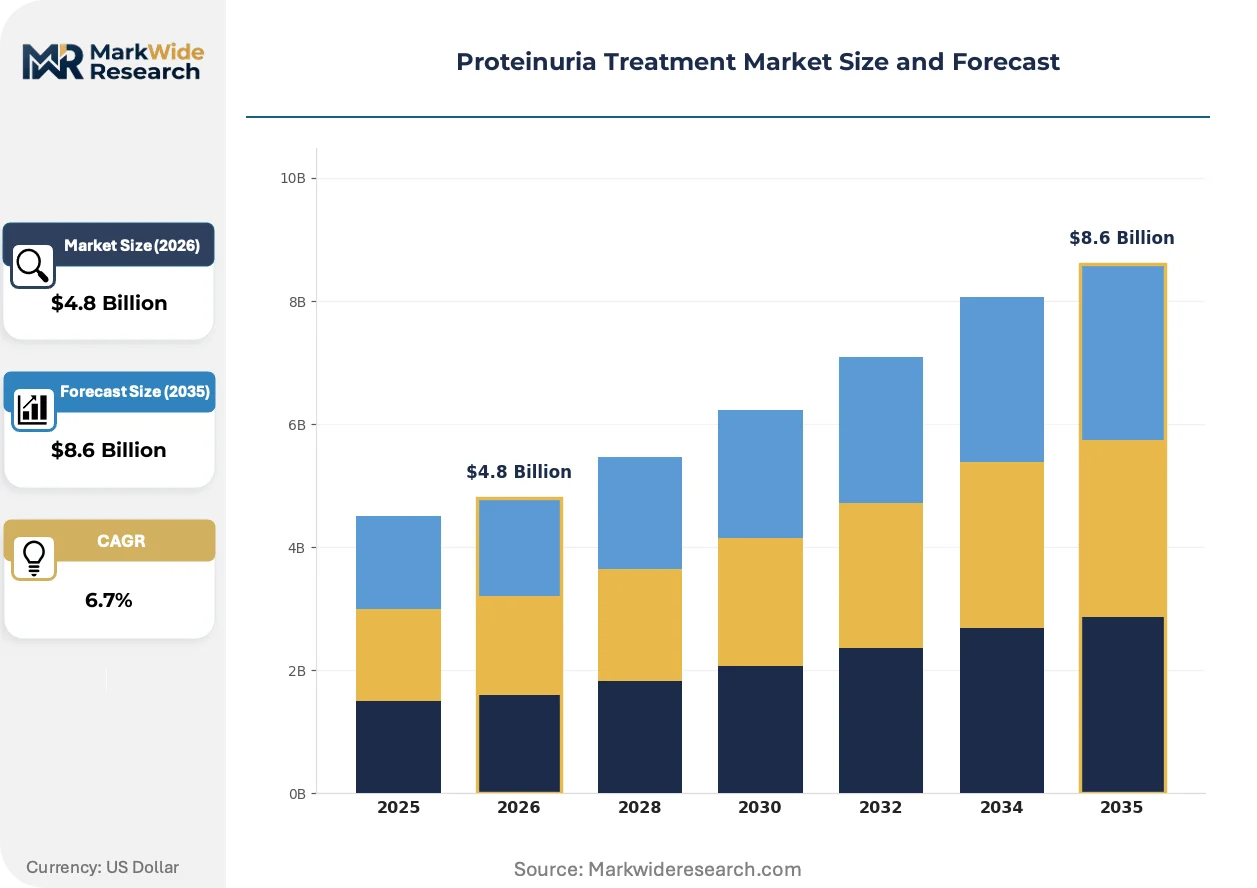
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ACE Inhibitors, ARBs, Diuretics, Calcium Channel Blockers Delivery Mode: Oral, Injectable, Intravenous, Transdermal End User: Hospitals, Outpatient Clinics, Homecare, Specialty Clinics Treatment Approach: Pharmacological, Dietary Management, Lifestyle Changes, Combination Therapy |
| Companies Covered | Merck & Co., Pfizer, AstraZeneca, Bristol-Myers Squibb, Novartis, Eli Lilly and Company, Sanofi, AbbVie, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proteinuria Treatment Market Evolving Landscape
Proteinuria management is undergoing mechanistic diversification as SGLT2 inhibitors and non-steroidal mineralocorticoid receptor antagonists challenge the historical dominance of renin-angiotensin blockade. This therapeutic pluralism is reshaping clinical trial design and payer evaluation frameworks simultaneously.
Artificial intelligence-enabled histopathology analysis is unifying diagnostic workflows across nephrology departments. Academic medical centers in Germany and Japan are deploying convolutional neural networks to standardize glomerular lesion scoring. This technology is compressing inter-rater variability in kidney biopsy interpretation and accelerating patient stratification for targeted proteinuria protocols.
The EMA's MDR pharmacovigilance frameworks are mandating enhanced post-authorization safety studies for nephrotoxicity signals. Manufacturers must now maintain active surveillance systems that detect rare renal adverse events in real-world use. European markets are responding by consolidating safety data management through specialized contract research organizations with EudraVigilance integration expertise.
Specialty pharmacy consolidation is altering how proteinuria therapies reach patients. Large integrated delivery networks in the United States are internalizing dispensing for oral proteinuria agents previously routed through retail channels. This vertical channel capture is most visible in Medicare Advantage populations where network-owned pharmacies capture adherence data for risk-adjustment optimization.
Proteinuria Treatment Market Segmentation
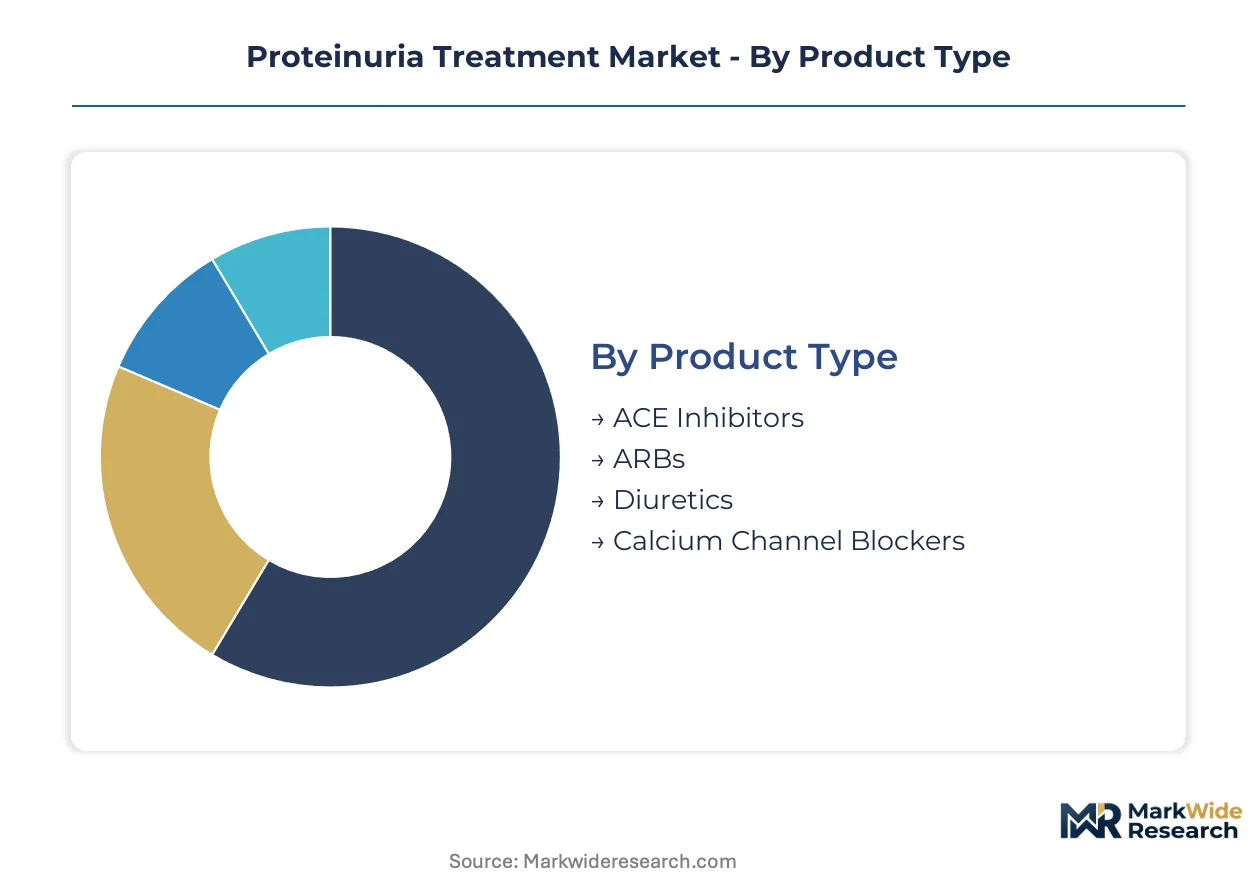
Proteinuria treatment protocols stratify across therapeutic mechanisms, administration routes, and care settings. Each segmentation dimension reveals distinct reimbursement patterns and patient access constraints that shape commercial strategy.
Product Type:
Standalone renin-angiotensin modulators anchor first-line protocols, while combination regimens embed into progressive disease management pathways.
- ACE Inhibitors:These agents suppress angiotensin-converting enzyme activity, reducing intraglomerular pressure and protein filtration. Demand concentrates in United States integrated care networks where Medicare Advantage formularies favor generic lisinopril and enalapril for cost containment.
- ARBs:Angiotensin II receptor blockers provide alternative renoprotection for ACE inhibitor-intolerant patients. Japanese nephrology departments prescribe losartan and valsartan extensively following PMDA guidance on diabetic kidney disease progression.
- Diuretics:Loop and thiazide diuretics manage volume overload in nephrotic-range proteinuria.
- Calcium Channel Blockers:Dihydropyridine agents serve as adjunctive antihypertensives when renin-angiotensin blockade proves insufficient.
ACE Inhibitors lead volumes today; ARBs are gaining share fastest among ACE-intolerant populations.
Delivery Mode:
Cost tiers separate mass-market oral formulations from premium-priced biologic injectables requiring cold chain infrastructure.
- Oral:Small-molecule tablets and capsules dominate prescription volumes due to pharmacy dispensing convenience and patient adherence advantages. United States retail channels and specialty pharmacies handle the majority of ACE inhibitor and ARB distribution.
- Injectable:Subcutaneous biologics for refractory glomerular disease command premium reimbursement. German academic medical centers and Japanese university hospitals pilot monoclonal antibody protocols requiring temperature-controlled logistics.
- Intravenous:Hospital-administered infusions serve acute proteinuria exacerbations and inpatient nephrology consultations.
- Transdermal:Patch-based delivery remains investigational for antihypertensive components of combination regimens.
Oral delivery leads volumes today; injectable modes are expanding most quickly through biologic pipeline advancement.
End User:
Patient acuity and reimbursement sophistication determine whether care concentrates in institutional settings or disperses toward home-based management.
- Hospitals:Inpatient nephrology services manage acute kidney injury with proteinuria and initiate intensive immunosuppression. United States hospital systems in Texas and Florida are consolidating renal centers of excellence to capture bundled payment contracts.
- Outpatient Clinics:Community nephrology practices handle stable chronic kidney disease monitoring and medication titration.
- Homecare:Remote albumin-to-creatinine ratio monitoring via smartphone-connected devices enables direct-to-patient engagement outside traditional clinic visits.
- Specialty Clinics:Lupus nephritis and IgA nephropathy referral centers concentrate biologic eligibility screening and infusion administration.
Hospitals lead volumes today; homecare channels are climbing the fastest through remote monitoring adoption.
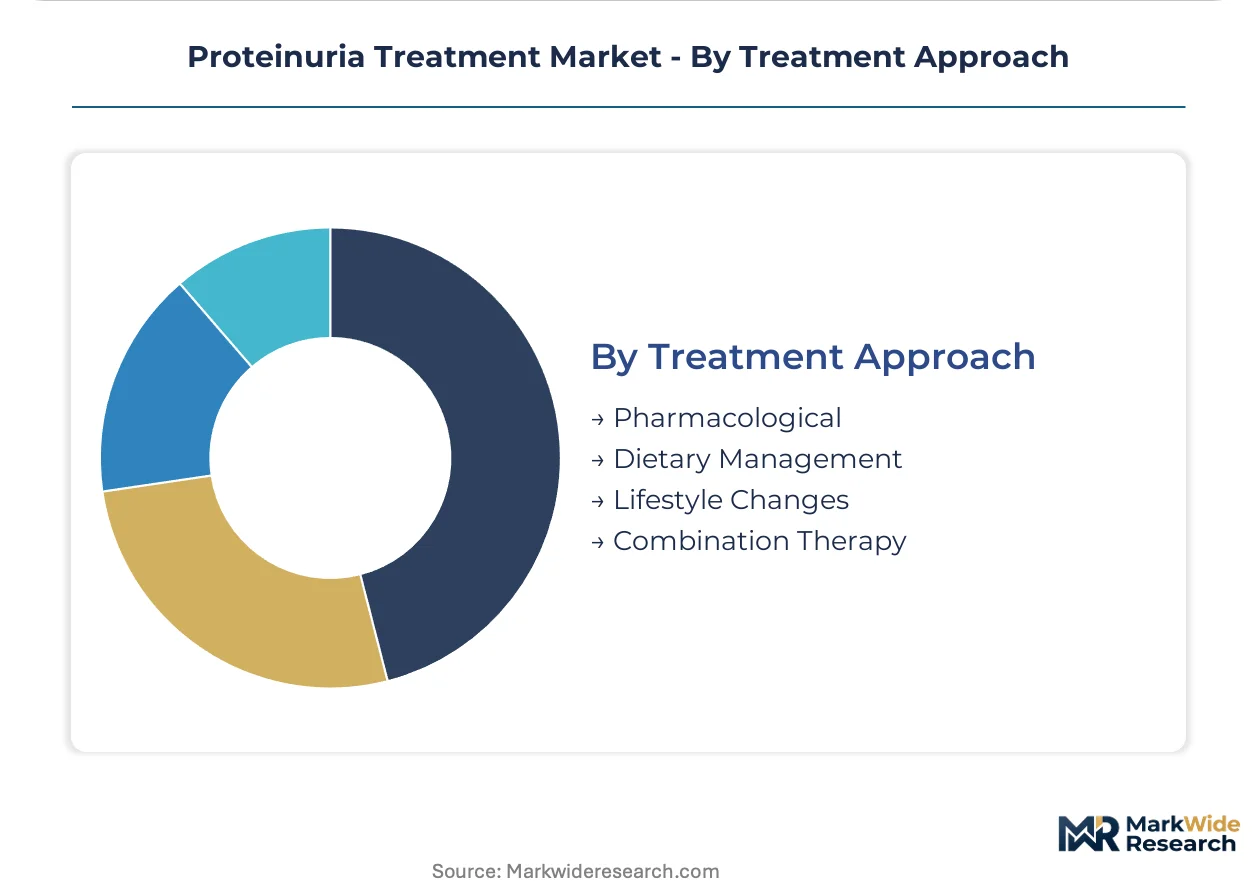
Treatment Approach:
Maturity curves separate decades-old pharmacological standards from emerging lifestyle and combination protocols gaining payer acceptance.
- Pharmacological:Drug-based interventions remain the foundation of proteinuria modification. EMA pharmacovigilance frameworks under the MDR mandate enhanced post-authorization safety studies for nephrotoxicity across European markets.
- Dietary Management:Sodium restriction and protein intake modification support pharmacological efficacy in progressive disease.
- Lifestyle Changes:Weight reduction and smoking cessation protocols address modifiable cardiovascular risk factors.
- Combination Therapy:Dual renin-angiotensin blockade or SGLT2 inhibitor add-on commands premium positioning where polypharmacy demonstrates renal outcome benefits.
Pharmacological approaches lead volumes today; combination therapy is gaining share fastest through outcome-based contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Renin-angiotensin blockade therapy for proteinuria achieved clinical standardization through United States academic medical centers during the 1990s, with subsequent protocol diffusion into German nephrology departments and Japanese university hospitals establishing the current geographic concentration of expertise.
United States
Medicare Advantage integrated care networks in Texas and Florida are consolidating renal centers of excellence to capture bundled payment contracts for chronic kidney disease management. The FDA's accelerated approval pathways for albuminuria surrogate endpoints are compressing Phase III trial timelines for novel proteinuria-modifying agents. Hospital systems in the Southeast are internalizing specialty pharmacy dispensing for oral ACE inhibitors and ARBs previously routed through retail channels.
Germany
Academic medical centers in Berlin and Munich deploy artificial intelligence-enabled histopathology analysis to standardize glomerular lesion scoring and accelerate patient stratification for targeted biologic protocols. The EMA's MDR pharmacovigilance frameworks mandate enhanced post-authorization safety studies for nephrotoxicity signals across European markets. Bavarian university hospitals pilot monoclonal antibody infusion protocols requiring temperature-controlled logistics infrastructure.
Japan
PMDA guidance on diabetic kidney disease progression drives extensive losartan and valsartan prescribing in Tokyo and Osaka nephrology departments. The country's national pharmaceutical regulator maintains stringent renal outcome trial requirements that shape evidence standards for SGLT2 inhibitor label expansions. Kansai region medical centers concentrate IgA nephropathy referral volumes and biologic eligibility screening.
India
Contract manufacturers in Hyderabad and Ahmedabad produce active pharmaceutical ingredients for renin-angiotensin system modulators serving global formulated product supply. CDSCO regulatory pathways for biosimilar monoclonal antibodies are attracting development investment in refractory glomerular disease segments. Maharashtra-based specialty hospitals are expanding dedicated proteinuria management protocols for diabetic kidney disease populations.
United Kingdom
NHS England's integrated care systems in London and the Midlands are standardizing combination ACE inhibitor and ARB regimens through renal center consolidation. The country's national pharmaceutical regulator aligns with EMA surrogate endpoint acceptance criteria that could expand label indications without hard renal outcome data. Scottish academic medical centers participate in multi-site European trials for lupus nephritis biologics.
Proteinuria Treatment Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with cardiovascular and immunology portfolio adjacencies. Large-cap developers anchor market presence through established renin-angiotensin blockade franchises and expanding SGLT2 inhibitor renal indications. Mid-tier specialists concentrate on biologic pipelines for refractory glomerular disease. Dominant competitive moves include strategic partnerships combining small-molecule and biologic capabilities, plus geographic expansion through regional licensing arrangements for cold chain-dependent injectables.
Among diversified pharmaceutical conglomerates, Pfizer leverages its cardiovascular portfolio breadth to anchor bundled ACE inhibitor and ARB offerings across United States integrated care networks. AstraZeneca exemplifies the SGLT2 adjacency strategy, extending cardiorenal protective indications into diabetic kidney disease protocols that displace earlier-line proteinuria thresholds. Bristol-Myers Squibb occupies a position within the immunology-renal convergence archetype, targeting proteinuria secondary to lupus nephritis through biologic pipeline development.
| Leading Market Players |
|---|
| Merck & Co. |
| Pfizer |
| AstraZeneca |
| Bristol-Myers Squibb |
| Novartis |
| Eli Lilly and Company |
| Sanofi |
| AbbVie |
| Bayer |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialty pharmacy networks in the United States have consolidated dispensing control over oral ACE inhibitors and ARBs, tightening pricing discipline through formulary tier management and rebate aggregation while simultaneously extracting upstream volume commitments from API manufacturers in India and China.
Pricing Analysis
Three-tier pricing structure across premium biologic injectables, standard branded small molecules, and economy generic oral agents governs proteinuria therapeutics. Price differentiation rests on cold chain certification requirements for monoclonal antibodies versus pharmacy dispensing convenience for tablets. Cost compression in the generic oral tier is intensifying because Medicare's Inflation Reduction Act price negotiation provisions apply downward pressure on established renin-angiotensin blockers. Medicare Advantage populations demonstrate highest price sensitivity; specialty clinics managing lupus nephritis biologics show lowest sensitivity due to limited therapeutic alternatives.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-controlled biologics remains underdeveloped in rural United States markets, forcing manufacturers to absorb spoilage costs or restrict distribution to academic medical centers with validated cold chain capabilities. Active pharmaceutical ingredient production draws from contract manufacturers in Hyderabad and Ahmedabad, India, plus chemical synthesis clusters in Zhejiang Province, China. Supply chain risk centers on single-source vulnerability for injectable monoclonal antibody fill-finish capacity. Distribution runs through integrated delivery network-owned specialty pharmacies capturing adherence data for risk-adjustment optimization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The proteinuria treatment market functions as a stable compounder anchored by irreversible chronic kidney disease prevalence expansion and protocol-driven polypharmacy adoption that resists cyclical demand fluctuation.
For Market Incumbents: Deploy backward integration into API manufacturing to offset geopolitical friction at Indian and Chinese contract manufacturing nodes. Incumbent pharmaceutical conglomerates should secure captive renin-angiotensin system modulator supply through minority stakes in Hyderabad-based producers, while simultaneously expanding SGLT2 inhibitor renal indication labeling to defend against biologic displacement in diabetic kidney disease protocols. For New Entrants and Emerging Players: Launch via direct-to-patient home monitoring channels that bypass entrenched specialty pharmacy gatekeepers. New entrants should target underpenetrated rural United States markets with smartphone-connected albumin-to-creatinine ratio testing platforms, while pursuing European orphan designation pathways for primary glomerular disorders to access premium pricing in ultra-orphan proteinuria segments. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier biologic developers with refractory glomerular disease pipelines lacking Phase III renal outcome data. Long-term viability in this market hinges on surrogate endpoint acceptance criteria that could compress development timelines without hard renal outcome requirements. Investors should monitor FDA guidance document releases on albuminuria validation as the critical inflection signal for pipeline value realization.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III renal outcome trials with albuminuria surrogate endpoints accelerate FDA approval timelines for novel agents. |
| Manufacturing Scale-Up | Cold chain capacity expansion in German Bavarian university hospitals enables monoclonal antibody protocol piloting. |
| Regulatory Approval Pathway | EMA orphan designation for IgA nephropathy indications unlocks premium pricing in European ultra-orphan segments. |
| Pipeline Diversification | Immunology-renal convergence programs at Bristol-Myers Squibb target lupus nephritis proteinuria secondary indications. |
| Licensing Agreement | Regional licensing for temperature-controlled injectables penetrates Japanese Kansai region biologic eligibility screening centers. |
Research Methodology
Bottom-up nephrology department prescribing modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare formulary databases. Cross-referencing manufacturer shipment data against payer rebate disclosures enables volume triangulation.
The input-output matrix maps treatment mechanism adoption curves against patient population progression rates, with segmentation across pharmacological class, delivery mode, care setting, and regional regulatory cluster. CAGRs derive from modeled prescription volume trajectories and pricing elasticity assumptions across the projection horizon. Forecast inputs incorporate SGLT2 inhibitor protocol displacement rates and biologic pipeline advancement timelines through Phase III renal outcome trials.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA surrogate endpoint rejection scenarios or acute geopolitical disruption at Indian API manufacturing nodes. Practitioners should monitor regulatory guidance releases, CDSCO biosimilar approval velocity, and Medicare Advantage formulary tier adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Renal Denervation Market
Nephrology
Renal Artery Stenosis Treatment Market
Nephrology
Kidney Dialysis Equipment Market
Nephrology
Peritoneal Dialysis Market
Nephrology
Global Dialysis Market
Nephrology
Nephrology Stents and Catheters Market
Nephrology
Kidney Stone Extraction Balloon Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Plasmapheresis Market
Nephrology
Kidney/Renal Function Test Market
Nephrology
US Hemodialysis and Peritoneal Dialysis Market
Nephrology
US Continuous Renal Replacement Therapy Market
Nephrology
Hemodialyzer Market
Nephrology
US Dialysis Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market