
 Nephrotic Syndrome Market | 2026-2036
Nephrotic Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Nephrotic Syndrome Market Outlook
Capital-intensity divergence between large-cap diversified pharma and mid-cap nephrology specialists is rotating competitive dynamics across the treatment landscape. Novartis leverages its established immunology infrastructure to sustain commercial reach in corticosteroid and immunosuppressant categories. Travere Therapeutics specializes in orphan nephrology indications, occupying a differentiated position against broader-portfolio rivals. Mallinckrodt anchors its presence through manufacturing scale in corticosteroid supply, competing on cost reliability rather than novel mechanism innovation.
Nephrotic syndrome constitutes a glomerular disorder characterized by heavy proteinuria exceeding 3.5 grams per 24 hours, hypoalbuminemia, edema, and hyperlipidemia, with podocyte injury representing the central pathophysiological mechanism driving filtration barrier dysfunction. The condition's primary commercial purpose centers on chronic disease management requiring sustained pharmacological intervention to prevent end-stage renal disease progression. Corticosteroids retain the largest share of the treatment type segment as first-line induction therapy, though immunosuppressants are gaining fastest traction among steroid-resistant patient populations where calcineurin inhibitors and mycophenolate mofetil demonstrate superior remission durability. Hospitals dominate the end user segment due to requirements for kidney biopsy capabilities and nephrology specialist oversight, while homecare settings are emerging as a structural growth pocket as oral maintenance regimens reduce inpatient dependency.
The FDA's orphan drug designation framework and EMA's pediatric investigation plan requirements shape development incentives and trial design standards for nephrotic syndrome therapeutics, directly influencing which indications receive prioritized investment. NMPA's evolving rare disease catalog inclusion criteria in China and CDSCO's accelerated approval pathways in India are expanding market access parameters beyond traditional Western regulatory benchmarks. Stakeholders must monitor how real-world evidence requirements from these regulators reshape post-approval commitment burdens and pricing negotiation leverage across markets.
Market Dynamics
The FDA's accelerated approval pathways for rare disease therapeutics are compressing development timelines and redirecting R&D capital toward nephrology pipeline assets, fundamentally altering how sponsors prioritize steroid-resistant indications against broader immunology portfolios.
Growth Catalysts
- EMA Pediatric Investigation Plans:Mandatory pediatric study requirements create development incentives that expand addressable patient populations beyond adult cohorts. Sponsors gain protocol design clarity that de-risks trial execution.
- Homecare Administration:Oral calcineurin inhibitor maintenance protocols enable treatment migration from infusion centers to patient residences. This channel expansion reduces healthcare system capacity constraints.
- Podocyte Biology Advances:Molecular characterization of slit diaphragm proteins is identifying novel druggable targets. Biopharma investment follows mechanistic validation in steroid-resistant disease models.
Market Restraints
- Corticosteroid API Concentration:Active pharmaceutical ingredient manufacturing for prednisone and methylprednisolone concentrates among three contract manufacturers in India. Supply disruption risk elevates procurement costs.
- Biopsy Infrastructure Gaps:Kidney biopsy capabilities require specialized pathologist networks that remain underdeveloped in secondary care settings. Diagnostic confirmation bottlenecks delay treatment initiation.
- Calcineurin Inhibitor Nephrotoxicity:Long-term tacrolimus and cyclosporine exposure produces secondary renal damage that limits chronic dosing. This toxicity ceiling constrains maintenance therapy durability.
Strategic Opportunities
- Real-World Evidence Pathways:FDA's expanded acceptance of post-market surveillance data for label extensions creates regulatory tailwinds. Sponsors can pursue indication broadening without prospective randomized trials.
- Point-of-Care Proteinuria Testing:Dipstick-to-smartphone diagnostic platforms enable home monitoring of disease activity. This technology convergence supports decentralized care models.
- Steroid-Sparing Regimens:Mycophenolate mofetil and rituximab combinations demonstrate durable remission in pediatric populations. Underpenetrated use in adult idiopathic membranous nephropathy represents expansion potential.
Industry Challenges
- Pediatric Nephrology Workforce:Fellowship-trained specialists concentrate in academic medical centers. Community hospital coverage gaps force patient travel burdens that compromise adherence.
- Biomarker Qualification Timelines:FDA and EMA validation requirements for proteinuria surrogates extend development programs. Sponsors face capital lock-up during evidentiary package assembly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nephrotic Syndrome Market |
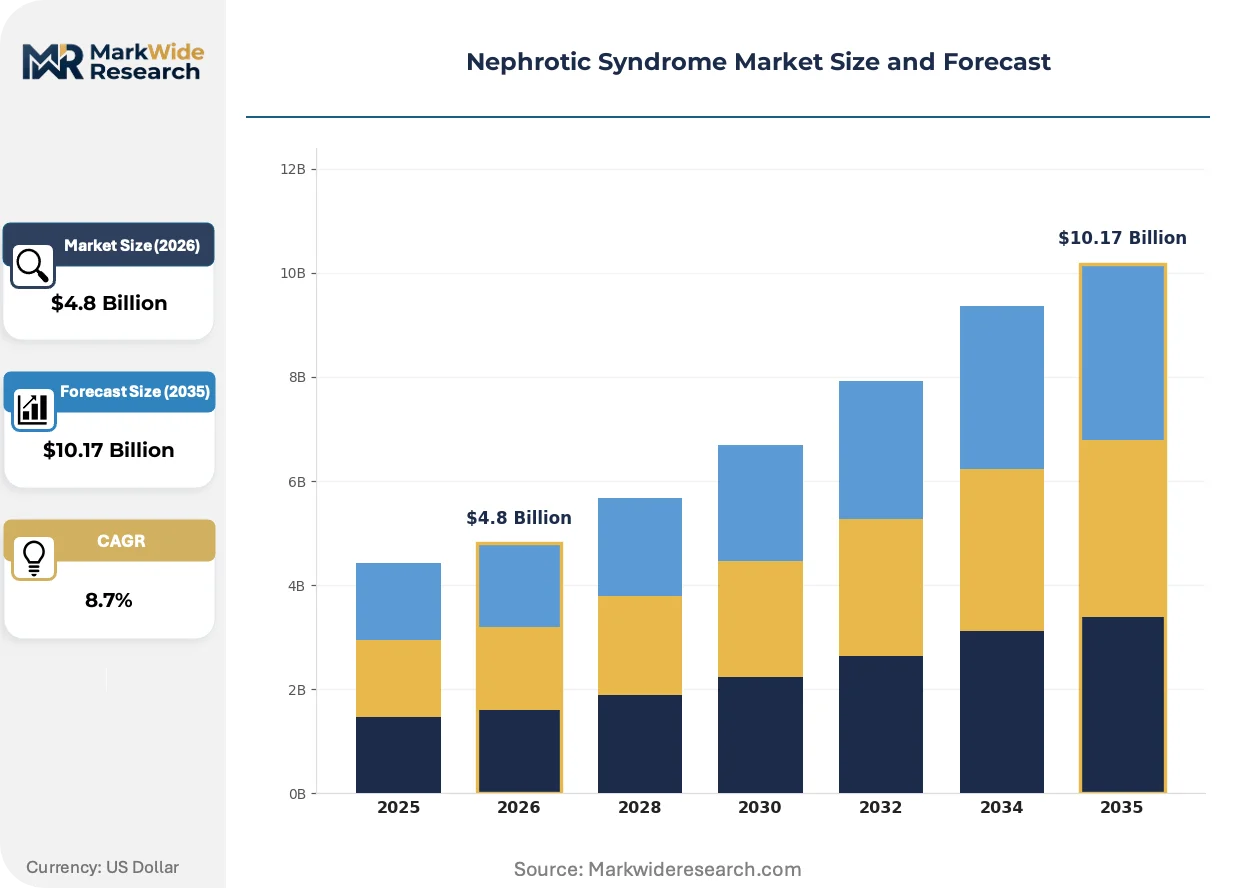
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Corticosteroids, Immunosuppressants, ACE Inhibitors, Diuretics End User: Hospitals, Clinics, Homecare Settings, Dialysis Centers Diagnosis Method: Urinalysis, Blood Tests, Kidney Biopsy, Imaging Techniques Stage of Disease: Initial Phase, Progressive Stage, Remission Phase, Recurrence Stage |
| Companies Covered | Novartis AG, Mallinckrodt Company, Travere Therapeutics, Inc., Aurinia Pharmaceuticals Inc., Bristol-Myers Squibb Company, Abbott, Pfizer Inc., GlaxoSmithKline, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nephrotic Syndrome Market Strategic Shifts
Biomarker-driven patient stratification is displacing empirical treatment selection across the nephrotic syndrome landscape, with molecular profiling enabling precision matching of immunosuppressive mechanisms to underlying podocyte pathology.
Targeted complement inhibition is fragmenting the steroid-resistant treatment paradigm. Ravulizumab and eculizumab variants demonstrate efficacy in C3 glomerulopathy-associated nephrotic presentations. Academic medical centers in the United States and Germany are adopting these agents ahead of formal guideline updates. This mechanism-based approach compresses reliance on empirical alkylating agents.
REACH registration requirements in Europe are mandating disclosure of immunosuppressive metabolite environmental persistence. Manufacturers must now submit fate-and-transport studies for mycophenolic acid derivatives. Contract manufacturing organizations serving EU markets are retrofitting waste handling infrastructure to comply with substance evaluation timelines.
Site-of-care economics are driving consolidation in infusion administration. Payers in the United States are bundling calcineurin inhibitor monitoring with nephrology specialist visits. Hospital outpatient departments capture volume as independent physician associations face reimbursement compression. This channel shift concentrates purchasing leverage among integrated delivery networks.
Nephrotic Syndrome Market Segmentation
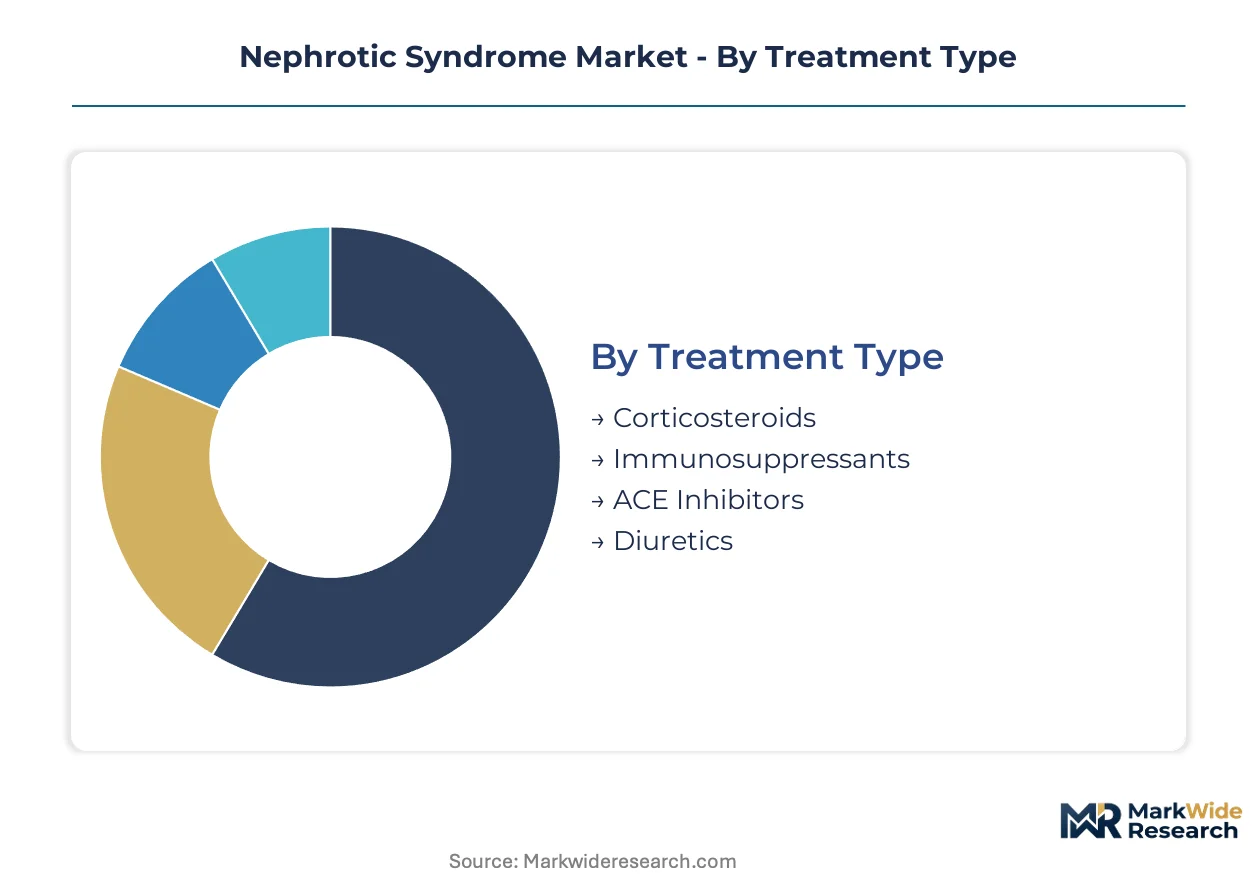
Segmentation in nephrotic syndrome therapeutics reveals how treatment selection varies by care setting, disease severity, and diagnostic capability. Substitution dynamics between pharmacological classes and care delivery channels directly shape competitive positioning and margin structures across the value chain.
Treatment Type:
Substitution pressure from novel immunomodulatory mechanisms is compressing market share for legacy corticosteroid regimens, particularly in steroid-resistant patient populations where calcineurin inhibitors and biologics demonstrate superior durability.
- Corticosteroids:Prednisone and methylprednisolone function as first-line induction therapy through anti-inflammatory and immunosuppressive action on T-cell activation. Demand concentrates in United States Medicare populations and European tertiary hospitals where cost containment protocols prioritize generic prescribing. Procurement contracts with Indian API manufacturers anchor supply reliability.
- Immunosuppressants:Calcineurin inhibitors (tacrolimus, cyclosporine) and antiproliferative agents (mycophenolate mofetil) target steroid-resistant disease through podocyte cytoskeleton stabilization. Germany's academic medical centers and Japan's pediatric nephrology networks drive adoption of tacrolimus-based maintenance protocols. EMA pediatric investigation plans accelerate development timelines for this class.
- ACE Inhibitors:Ramipril and lisinopril reduce proteinuria through glomerular hemodynamic modulation.
- Diuretics:Furosemide and spironolactone manage edema through sodium excretion enhancement.
Corticosteroids anchor the volume base while immunosuppressants gain share at the steepest rate.
End User:
Cost tier stratification across care settings is fragmenting purchasing authority, with integrated delivery networks capturing infusion volume while homecare channels erode hospital outpatient margins through oral maintenance migration.
- Hospitals:Tertiary academic centers manage acute presentations, kidney biopsy procedures, and intravenous induction protocols. United States hospital outpatient departments bundle calcineurin inhibitor monitoring with specialist visits. Biopsy infrastructure requirements concentrate volume in centers with dedicated renal pathology services.
- Homecare Settings:Oral calcineurin inhibitor maintenance and smartphone-linked proteinuria monitoring enable decentralized disease management. Germany's statutory health insurance reimbursement for home nursing supports channel expansion. REACH registration requirements for immunosuppressive metabolite disposal create compliance overhead for this segment.
- Clinics:Community nephrology practices handle stable maintenance patients and referral coordination.
- Dialysis Centers:End-stage renal disease transition facilities manage nephrotic syndrome complications in advanced cases.
Hospitals retain the highest patient acuity while homecare settings expand most quickly.
Diagnosis Method:
Application-specific accuracy requirements are concentrating investment in non-invasive alternatives, with molecular biomarker platforms threatening traditional histopathology's diagnostic monopoly in steroid-resistant phenotyping.
- Kidney Biopsy:Percutaneous tissue sampling remains the gold standard for histopathological classification of minimal change disease, focal segmental glomerulosclerosis, and membranous nephropathy. United States academic medical centers and French nephrology reference networks maintain specialized pathologist density. Workforce concentration in urban centers creates access barriers.
- Urinalysis:Dipstick and quantitative protein-to-creatinine ratio testing provide initial screening and disease activity monitoring. Point-of-care smartphone integration platforms from South Korean and Israeli developers are penetrating home monitoring applications. India's diagnostic laboratory chains scale cost-efficient screening.
- Blood Tests:Serum albumin, lipid panel, and creatinine assessments support metabolic complication monitoring.
- Imaging Techniques:Renal ultrasound evaluates structural abnormalities and guides biopsy procedures.
Urinalysis captures the highest test volume while kidney biopsy commands the premium diagnostic tier.
Stage of Disease:
Customer type differentiation across disease trajectories is reshaping clinical trial recruitment and commercial messaging, with sponsors prioritizing progressive-stage populations for novel mechanism demonstration.
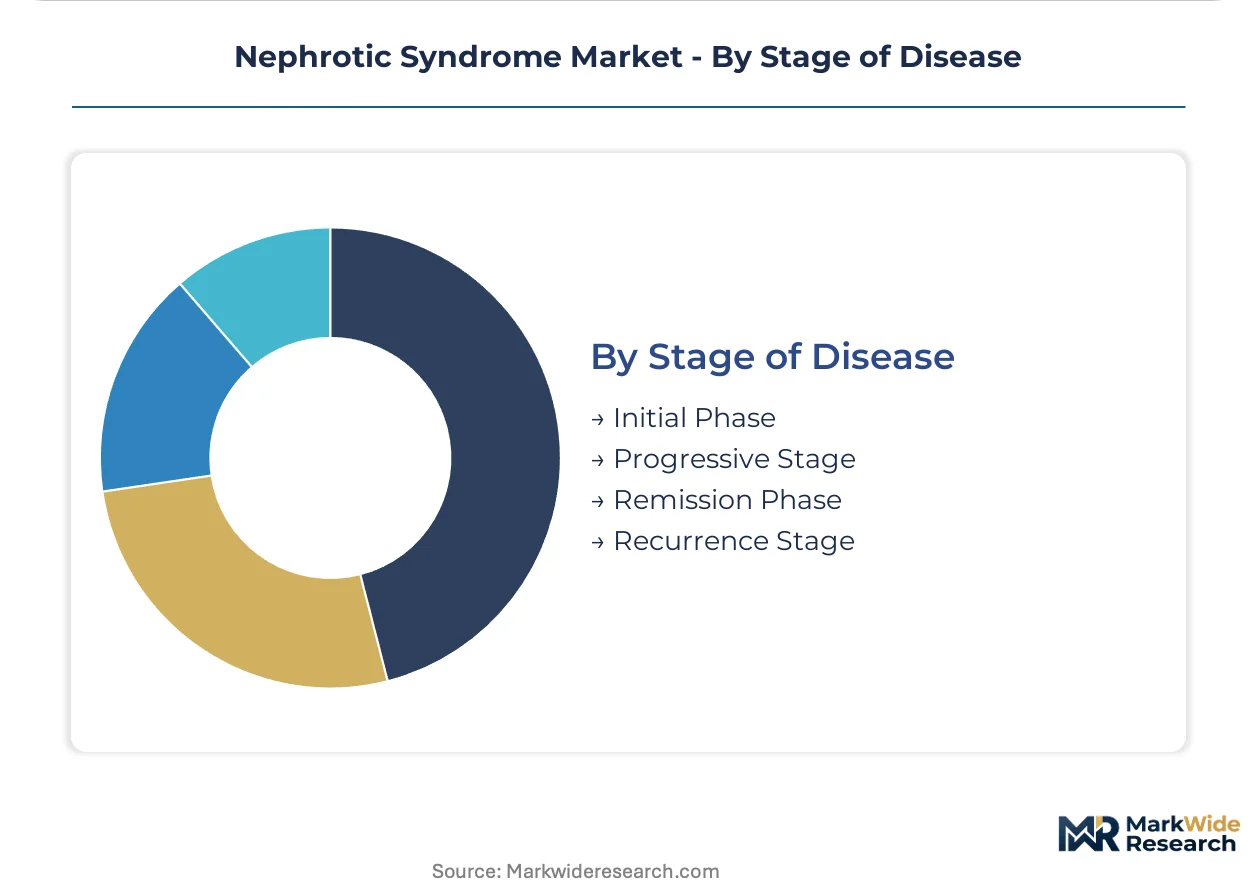
- Initial Phase:First presentation with heavy proteinuria and edema requires rapid corticosteroid initiation and diagnostic workup. Pediatric populations in United States children's hospitals and United Kingdom specialist centers dominate this segment. EMA pediatric investigation plan mandates shape development program design.
- Progressive Stage:Steroid resistance or frequent relapse triggers immunosuppressant escalation and consideration of rituximab or complement inhibitors. Germany's glomerular disease registries and Japan's rare disease research networks concentrate this refractory population. FDA accelerated approval pathways target this unmet need.
- Remission Phase:Sustained proteinuria resolution requires maintenance immunosuppression tapering protocols.
- Recurrence Stage:Relapse after prior remission demands re-induction strategy modification.
Initial phase patients represent the largest addressable cohort while progressive stage populations drive pipeline prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States Medicare reimbursement corridors while procurement leverage clusters in German statutory health insurance networks. This asymmetry fragments commercial strategy across the Atlantic basin. Regional regulatory divergence shapes where sponsors prioritize launch sequencing and evidence generation.
United States
Medicare Part B reimbursement for calcineurin inhibitor monitoring bundles specialist visits with drug administration. FDA accelerated approval pathways for rare disease therapeutics compress development timelines for steroid-resistant indications. Boston and New York academic medical centers anchor glomerular disease registry participation and real-world evidence collection.
Germany
Statutory health insurance funds drive volume through centralized tendering for oral immunosuppressant maintenance protocols. EMA pediatric investigation plan mandates shape trial design for pediatric nephrology networks. Heidelberg and Berlin tertiary hospitals concentrate biopsy infrastructure and specialized renal pathology services.
Japan
PMDA orphan drug designation provides tax incentives and priority review for complement inhibitor development in C3 glomerulopathy. Pediatric nephrology specialists cluster in Tokyo and Osaka academic medical centers. The Ministry of Health, Labour and Welfare's rare disease research network accelerates patient identification for refractory cohorts.
China
NMPA's evolving rare disease catalog inclusion criteria expand market access for imported immunosuppressants beyond traditional Western benchmarks. Domestic corticosteroid API manufacturing concentrates in Zhejiang and Jiangsu provinces. Beijing and Shanghai tertiary hospitals lead adoption of molecular biomarker platforms for patient stratification.
India
CDSCO accelerated approval pathways enable earlier access to novel mechanisms in steroid-resistant populations. Cost-containment pressures favor generic corticosteroid prescribing in Delhi and Mumbai public hospital networks. The country's contract manufacturing base supplies prednisone API to European and North American formulation facilities.
Nephrotic Syndrome Market Competitive Environment
Concentration sits with diversified pharmaceutical conglomerates possessing established immunology infrastructure. Three to five mid-cap specialists occupy differentiated positions in orphan nephrology indications. Large-cap players compete on manufacturing scale and distribution reach. Mid-tier firms pursue mechanism-based differentiation through biologic and small-molecule innovation. Competitive moves center on portfolio diversification into rare disease assets and strategic partnerships for biomarker-driven patient selection.
Within the diversified pharmaceutical tier, Novartis AG and Pfizer Inc. represent scale-driven positions anchored by broad immunology portfolios. Travere Therapeutics, Inc. exemplifies the orphan nephrology specialist archetype with concentrated focus on glomerular disease mechanisms. Mallinckrodt Company occupies a manufacturing-centric position competing on corticosteroid supply reliability rather than novel therapeutic innovation.
| Leading Market Players |
|---|
| Novartis AG |
| Mallinckrodt Company |
| Travere Therapeutics, Inc. |
| Aurinia Pharmaceuticals Inc. |
| Bristol-Myers Squibb Company |
| Abbott |
| Pfizer Inc. |
| GlaxoSmithKline |
| Asahi Kasei Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-day API inventory buffers at Indian contract manufacturers determine corticosteroid spot price volatility and immunosuppressant contract renewal leverage across European hospital networks. This lead-time exposure concentrates pricing power among formulation facilities with captive tacrolimus supply, while generic prednisone procurement faces cost compression from concentrated API sourcing.
Pricing Analysis
The customization-premium spread between standard-of-care corticosteroid protocols and configured-to-order biologic regimens spans three distinct tiers. Pricing stratifies across premium complement inhibitors, standard calcineurin inhibitor maintenance, and economy generic corticosteroid induction. Price differentiation rests on FDA orphan designation status and pediatric indication breadth. Cost compression in the corticosteroid tier intensifies because Indian API manufacturers compete on volume scale. Pediatric nephrology networks demonstrate highest price sensitivity, while academic medical centers in Germany and the United States show lowest sensitivity for novel mechanisms.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for corticosteroid and calcineurin inhibitor manufacturing. Tacrolimus fermentation draws from Chinese intermediate suppliers and Indian finished-dose formulation. Single-source vulnerability concentrates in mycophenolate mofetil precursor synthesis, where two Zhejiang province facilities supply global demand. Distribution runs through hospital outpatient departments and specialty pharmacy channels, with integrated delivery networks capturing infusion volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nephrotic syndrome therapeutic landscape rewards sponsors possessing rare disease regulatory expertise and pediatric trial execution infrastructure. Fellowship-trained nephrologist density in academic medical centers creates bottlenecks that constrain patient recruitment velocity and commercial reach.
For Market Incumbents: Shield market position by deepening backward integration into corticosteroid API supply and accelerating biomarker-driven patient stratification capabilities. Novartis-type diversified portfolios face substitution pressure from Travere Therapeutics' orphan-focused positioning. Vertical integration into Indian API manufacturing secures cost reliability against supply disruption. For New Entrants and Emerging Players: Differentiate on complement inhibition mechanisms in C3 glomerulopathy-associated presentations, where FDA accelerated approval pathways compress development timelines. Adult idiopathic membranous nephropathy represents the most penetrable segment for steroid-sparing regimens. Go-to-market execution should target German statutory health insurance tendering cycles for oral maintenance protocols. For Investors and Strategic Acquirers: Long-term, this sits as a rare disease consolidation play because EMA pediatric investigation plan mandates and FDA orphan incentives create durable moats around approved mechanisms. Acquisition targets should display biomarker qualification progress and real-world evidence infrastructure. The signal to watch is NMPA rare disease catalog inclusion for imported immunosuppressants.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Pediatric investigation plan execution de-risks FDA submission timelines for steroid-resistant indications. |
| Regulatory Approval Pathway | Orphan drug designation secures priority review and tax incentives across United States and Japan markets. |
| Manufacturing Scale-Up | API capacity expansion in Indian facilities reduces procurement cost exposure for generic corticosteroid supply. |
| Pipeline Diversification | Complement inhibitor development fragments dependence on calcineurin inhibitor maintenance paradigms. |
| Strategic Partnership | Biomarker platform alliances enable precision patient selection for mechanism-matched therapy assignment. |
Study Parameters
Desk research of FDA orphan drug designations, EMA pediatric investigation plans, and ClinicalTrials.gov protocols preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from CMS Medicare reimbursement data, hospital procurement databases, and glomerular disease registry publications. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation anchored market sizing.
Variance decomposition across treatment type, end user, diagnosis method, and disease stage segmentation dimensions shaped the analytical framework. CAGRs were derived from patient population epidemiology and therapy penetration curves across the projection horizon. Forecast inputs incorporated corticosteroid resistance rates, calcineurin inhibitor maintenance duration, and complement inhibitor adoption velocity in academic medical centers.
The analysis sits within stated boundaries; outcomes outside FDA accelerated approval pathway utilization or EMA pediatric mandate compliance would require recalibration. Forecasts reflect assumptions regarding reimbursement stability and biopsy infrastructure expansion. Recalibration cycles align with material shifts in NMPA rare disease catalog criteria and CDSCO accelerated approval utilization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Global Hemodialysis Market
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Ketoanalogue for Kidney Disease Market
Nephrology
Renal Insufficiency Treatment Market
Nephrology
Dialysis Service Market
Nephrology
Radiation Nephropathy Treatment and Management Market
Nephrology
Renal Artery Embolization Market
Nephrology
US Dialysis Centers Market
Nephrology
End Stage Renal Disease Market
Nephrology
Hemodialysis Services Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
Plasmapheresis Market
Nephrology
Hemodialysis Vascular Graft Market
Nephrology
Nephrology Stents and Catheters Market
Nephrology
Global Dialyzer Market
Nephrology
Global Dialysis Market