
 US Cath Labs Market | 2026-2036
US Cath Labs Market Size, Share, and Industry Trends Forecast 2026-2036
US Cath Labs Market Intelligence
Buyer concentration among hospital networks is rebalancing as independent cardiology practices merge into larger health systems. Siemens Healthineers leverages its imaging hardware leadership to anchor integrated cath lab suites. Boston Scientific Corporation competes through specialized interventional devices that pair with third-party imaging platforms. Medtronic controls electrophysiology ablation technologies that differentiate its cath lab ecosystem offerings.
A cardiac catheterization laboratory is a specialized procedural suite equipped with fluoroscopic X-ray imaging, hemodynamic monitoring systems, and sterile catheter handling infrastructure designed for minimally invasive cardiovascular diagnosis and intervention. Imaging systems typically operate at 15-30 frames per second with flat-panel detector technology to enable real-time coronary visualization during percutaneous procedures. Catheter systems represent the largest product category by installed base, though optical coherence tomography technology is expanding fastest as physicians demand intravascular imaging with ten-micron resolution for stent optimization. Coronary intervention remains the dominant treatment type by procedure volume, while electrophysiology labs command premium capital allocation due to complex ablation mapping requirements.
The FDA regulates cath lab devices under Class II and III medical device pathways, while CMS reimbursement determinations directly shape hospital capital expenditure cycles for new suite construction. Joint Commission accreditation standards mandate specific room sizing, radiation shielding, and emergency resuscitation capabilities that constrain facility design flexibility. State-level certificate-of-need programs in New York and Illinois limit cath lab expansion in oversaturated markets. Stakeholders must monitor whether CMS extends site-neutral payment policies that would compress margins at hospital-based outpatient cath labs relative to freestanding centers.
Market Dynamics
Hospital capital expenditure cycles for cath lab construction are compressing as CMS site-neutral payment policies force outpatient facilities to demonstrate procedural volume thresholds before reimbursement authorization.
Growth Catalysts
- Outpatient procedure migration:Medicare's expansion of ambulatory surgical center coverage for diagnostic catheterization is redirecting patient volume from inpatient settings. Hospital networks in Texas and Florida are building freestanding cath labs to capture this shift.
- Optical coherence tomography integration:Ten-micron resolution imaging for stent optimization is becoming standard-of-care in interventional cardiology. Physicians demand intravascular imaging capabilities that justify premium capital equipment investments.
- Aging demographic concentration:Cardiovascular disease prevalence in retirement corridors across Arizona and coastal Carolinas is driving cath lab construction to serve Medicare-eligible populations.
Market Restraints
- Certificate-of-need saturation:New York and Illinois regulators block new cath lab approvals in markets where existing capacity exceeds utilization benchmarks. CON programs constrain geographic expansion for health systems.
- Specialized technician scarcity:Radiologic technologists with cardiac catheterization certification command wage premiums that elevate fixed operating costs. Training pipelines produce fewer qualified candidates than replacement demand requires.
- Fluoroscopy equipment lead times:Flat-panel detector manufacturing concentrates among Asian component suppliers. Extended delivery schedules for imaging hardware delay suite commissioning and revenue recognition.
Strategic Opportunities
- Rural hospital hub-and-spoke models:Critical access hospitals in Montana and North Dakota are partnering with tertiary centers for teleproctoring-supported diagnostic procedures. Remote interpretation contracts expand service footprints without full capital deployment.
- Electrophysiology lab hybridization:Complex ablation mapping requirements command premium capital allocation. Facilities combining diagnostic catheterization with EP capabilities capture higher reimbursement per square foot.
- Joint Commission accreditation differentiation:Emergency resuscitation capability mandates create compliance barriers. Hospitals exceeding minimum standards market their cath labs as regional STEMI receiving centers.
Industry Challenges
- Legacy hemodynamic system integration:Proprietary data formats from installed monitoring platforms resist interoperability with newer imaging archives. IT infrastructure upgrades require parallel capital commitments.
- Radiation safety officer certification bottlenecks:State licensing boards impose continuing education requirements that limit staff scheduling flexibility. Compliance documentation consumes administrative bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cath Labs Market |
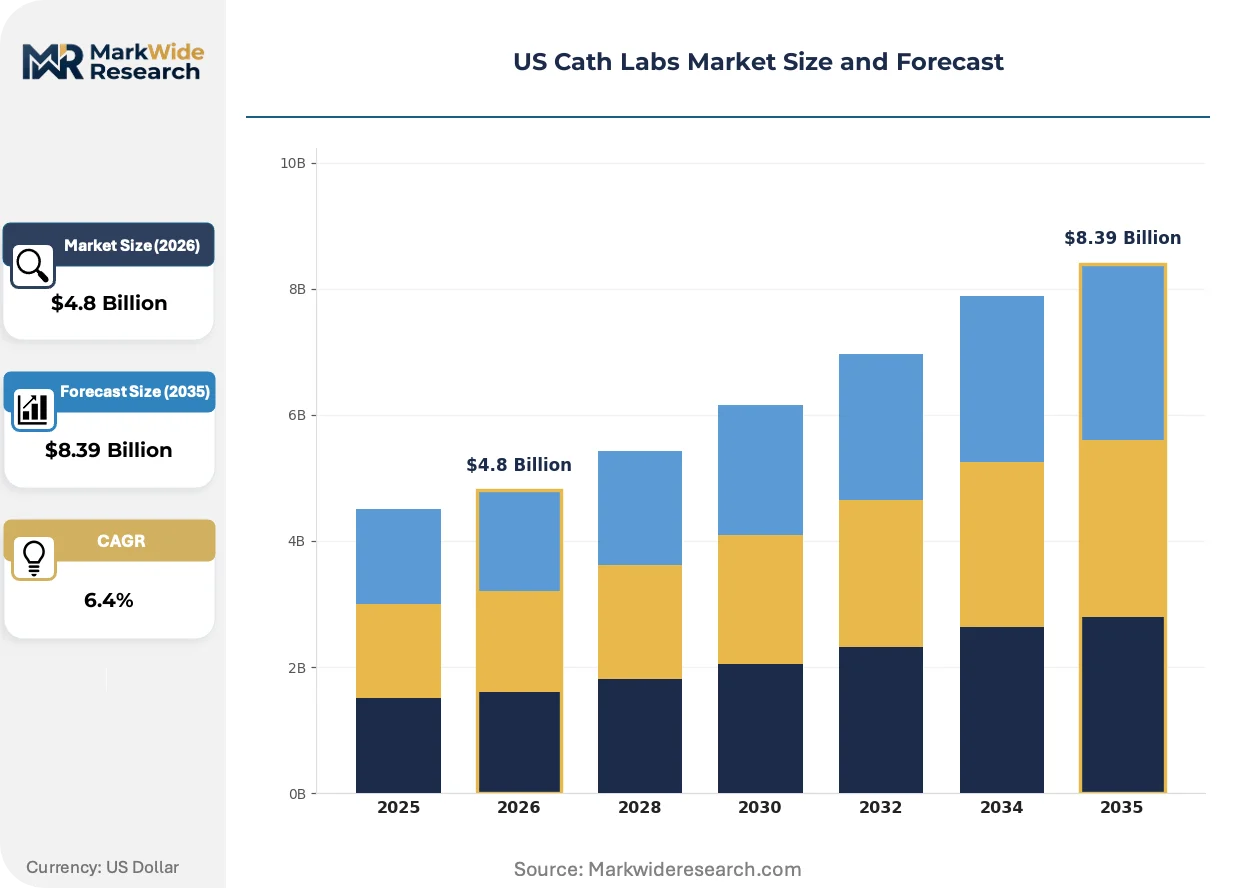
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheter Systems, Imaging Systems, Accessories, Equipment End User: Hospitals, Cardiology Clinics, Outpatient Centers, Research Laboratories Technology: X-ray Imaging, MRI Systems, Ultrasound, Optical Coherence Tomography Treatment Type: Coronary Intervention, Peripheral Vascular Intervention, Electrophysiology, Valve Repair |
| Companies Covered | Boston Scientific Corporation, Johnson & Johnson, Koninklijke Philips N.V., Shimadzu Corporation, Siemens Healthineers, GE Healthcare, Abbott Laboratories, B. Braun Melsungen AG, Medtronic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cath Labs Market Strategic Shifts & Innovations
Artificial intelligence-assisted image interpretation is compressing procedure times while radiation dose monitoring systems respond to occupational safety litigation. These forces are reshaping capital allocation priorities across cath lab construction and retrofit cycles.
Intravascular ultrasound guidance systems are converging with robotic catheter navigation platforms. Academic medical centers in California and Massachusetts are piloting autonomous lesion crossing protocols. This convergence is compressing the learning curve for complex percutaneous coronary intervention while raising questions about liability frameworks for physician-supervised automation.
FDA Class III device pathway modifications for breakthrough designation are accelerating optical coherence tomography catheter approvals. The industrial consequence is compressed time-to-market for imaging accessories that command premium pricing. Interventional cardiology practices in Florida are prioritizing suite configurations that accommodate rapid technology turnover.
Health system procurement committees are consolidating vendor relationships through enterprise imaging contracts. Independent cardiology practices merging into hospital networks lose negotiating leverage for best-of-breed device selection. This concentration is most visible in Texas, where HCA and Tenet facility standardization programs limit cath lab equipment heterogeneity across metropolitan markets.
US Cath Labs Market Segmentation
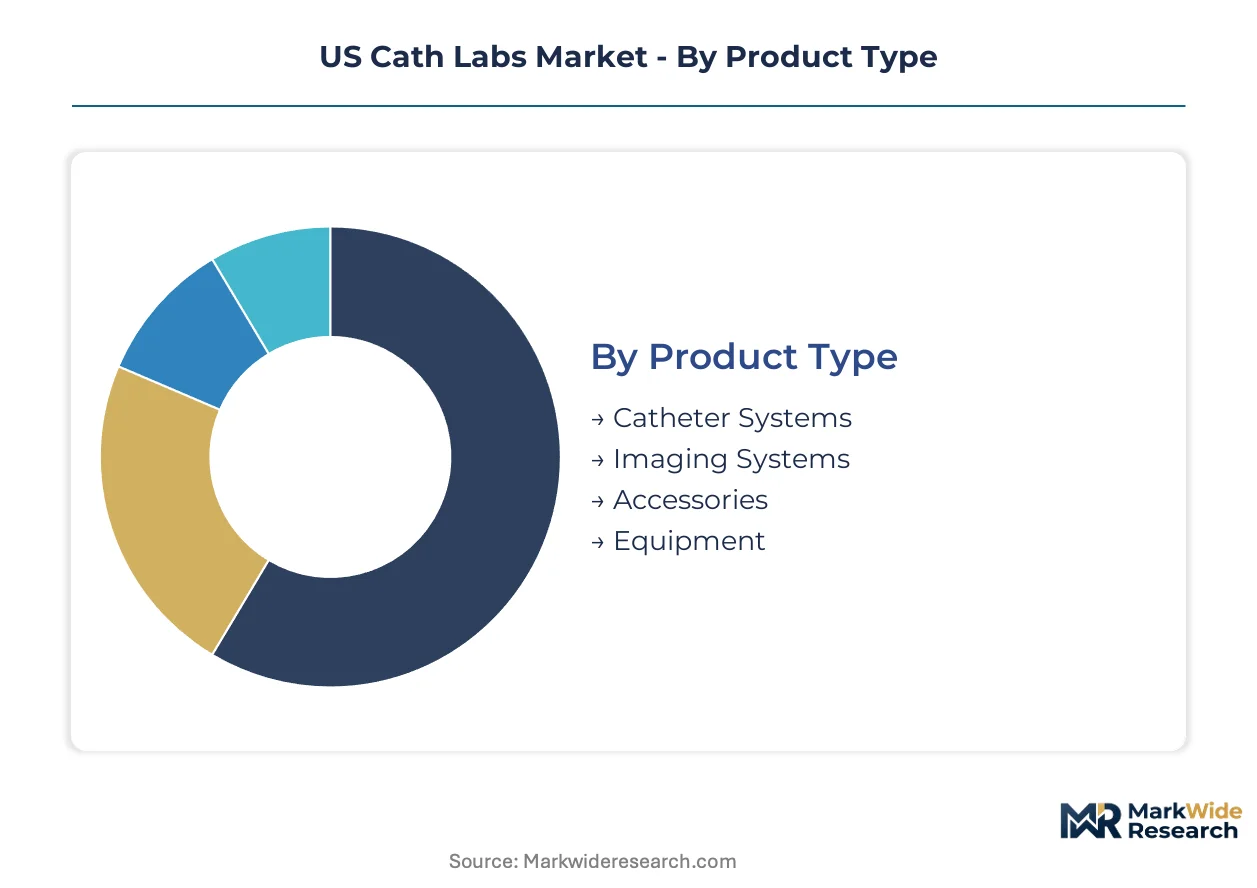
US cath lab procurement committees segment capital allocation across four dimensions that determine suite configuration and vendor selection. Product type and technology choices anchor equipment specifications, while end user and treatment type segmentation governs reimbursement pathways and facility design requirements.
Product Type:
Standalone capital equipment dominates integrated suite configurations, while disposable accessories embed into per-procedure supply chains.
- Catheter Systems:Guiding catheters, diagnostic catheters, and interventional delivery systems constitute the largest installed base by unit volume. Texas hospital networks negotiate enterprise contracts for coronary guiding catheters as they expand interventional cardiology service lines.
- Imaging Systems:Flat-panel fluoroscopy units with 15-30 frames per second capability anchor procedural visualization. Florida cath lab construction projects prioritize biplane angiography systems to capture outpatient migration from inpatient settings.
- Accessories:Introducer sheaths, manifold kits, and pressure transducers represent high-velocity consumables. Arizona retirement corridor facilities stockpile these disposables to maintain procedural throughput.
- Equipment:Hemodynamic monitoring consoles and boom-mounted radiation shields complete the sterile field infrastructure. Coastal Carolina health systems specify integrated boom configurations during new construction.
Volume placements concentrate in Catheter Systems; the faster expansion belongs to Imaging Systems.
End User:
Reimbursement authorization thresholds vary sharply across facility types, compressing capital cycles at outpatient sites while extending them at academic centers.
- Hospitals:Inpatient and hospital-based outpatient departments command the majority of procedural volume. Texas medical centers leverage CMS site-neutral payment policy delays to defend outpatient cath lab margins.
- Cardiology Clinics:Physician-owned or hospital-affiliated diagnostic facilities focus on elective catheterization. Florida certificate-of-need exemptions enable clinic-based lab construction in underserved counties.
- Outpatient Centers:Freestanding ambulatory surgical centers capture Medicare's expanded diagnostic coverage. HCA and Tenet standardization programs limit equipment heterogeneity across these facilities.
- Research Laboratories:Academic medical centers in California and Massachusetts pilot robotic catheter navigation protocols. These sites absorb extended equipment validation timelines.
Procedure volume clusters at Hospitals; Outpatient Centers are climbing the fastest.
Technology:
Capital intensity stratifies sharply between legacy X-ray platforms and premium intravascular imaging modalities.
- X-ray Imaging:Conventional fluoroscopy with digital subtraction angiography remains the workhorse visualization platform. Every US cath lab maintains at least one biplane angiography suite.
- MRI Systems:Magnetic resonance imaging integration supports structural heart planning and complex congenital cases. Select tertiary centers deploy MRI-guided electrophysiology mapping.
- Ultrasound:Intravascular ultrasound guidance systems enable lesion characterization and stent sizing. Interventional cardiologists demand IVUS capability for left main interventions.
- Optical Coherence Tomography:Ten-micron resolution intravascular imaging commands premium pricing for stent optimization. FDA breakthrough designations accelerate catheter approvals for this modality.
Installed base dominance rests with X-ray Imaging; steepest expansion trajectory belongs to Optical Coherence Tomography.
Treatment Type:
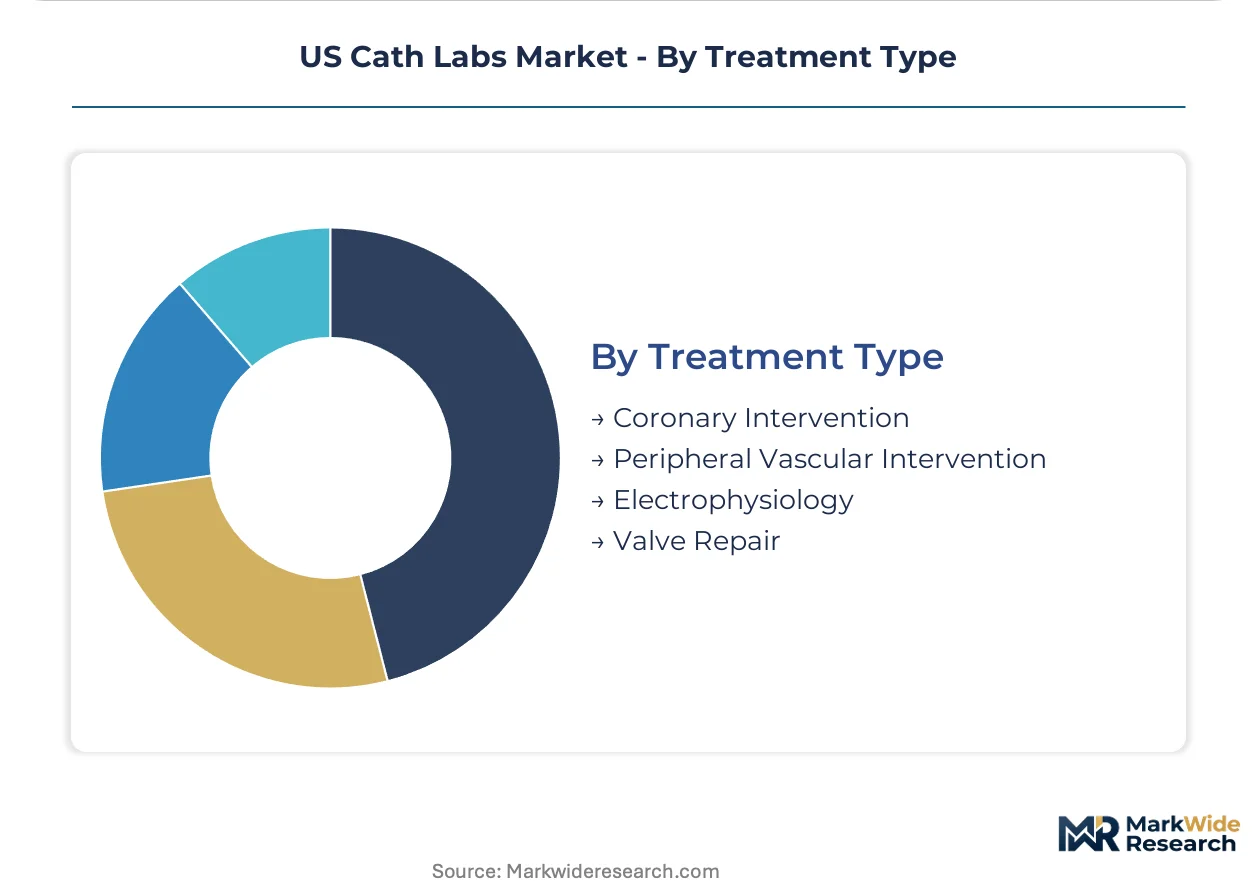
Procedure complexity and reimbursement rates determine capital allocation per square foot across diagnostic and therapeutic service lines.
- Coronary Intervention:Percutaneous coronary intervention constitutes the dominant procedure category by volume. Arizona and coastal Carolina cath labs size suites around anticipated PCI throughput.
- Peripheral Vascular Intervention:Lower extremity and renal artery interventions leverage existing coronary catheter platforms. Florida outpatient centers add peripheral capabilities to maximize equipment utilization.
- Electrophysiology:Complex ablation mapping for atrial fibrillation commands premium capital allocation. Three-dimensional electroanatomical mapping systems differentiate EP lab configurations.
- Valve Repair:Transcatheter aortic valve replacement and mitral clip procedures require hybrid operating room infrastructure. Academic medical centers combine surgical backup with interventional suites.
Procedure volume concentrates in Coronary Intervention; premium capital allocation flows to Electrophysiology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for catheterization laboratory infrastructure concentrates in retirement corridors and cardiovascular disease hotspots across the United States. State-level regulatory frameworks and Medicare reimbursement policies create sharp geographic variation in construction activity. Hospital networks prioritize expansion in markets with aging demographics and favorable certificate-of-need environments.
Texas
Houston and Dallas medical centers drive interventional cardiology capacity expansion as HCA and Tenet deploy standardized suite configurations. The Texas Department of State Health Services maintains certificate-of-need exemptions for underserved counties that accelerate rural cath lab construction. Freestanding outpatient facilities in Austin and San Antonio capture Medicare's expanded ambulatory surgical center coverage for diagnostic catheterization.
Florida
Retirement migration along the Gulf Coast and Atlantic shoreline elevates cardiovascular procedure volumes in Tampa, Orlando, and Miami metropolitan areas. Florida's Agency for Health Care Administration grants CON exemptions for cardiac services in designated rural counties, enabling clinic-based lab development. Biplane angiography systems dominate new construction in Jacksonville and Fort Lauderdale as outpatient migration accelerates.
Arizona
Phoenix and Tucson health systems size cath lab suites around anticipated percutaneous coronary intervention throughput from Medicare-eligible populations. The Arizona Department of Health Services regulates radiation safety officer certification requirements that constrain staffing flexibility. Sun City and Mesa retirement communities drive demand for intravascular imaging capabilities in new facilities.
Coastal Carolinas
Charleston, Myrtle Beach, and Wilmington hospital networks expand interventional cardiology service lines to serve seasonal and year-round retiree populations. North Carolina's certificate-of-need program limits new cardiac catheterization approvals in saturated urban markets. Duke and Atrium Health systems standardize optical coherence tomography integration across coastal facility upgrades.
California
Academic medical centers in Los Angeles, San Francisco, and San Diego pilot robotic catheter navigation protocols that extend procedural validation timelines. The California Department of Public Health enforces radiation shielding mandates that elevate construction costs for new suite commissioning. Cedars-Sinai and Stanford Medicine facilities absorb extended equipment lead times for breakthrough-designation imaging accessories.
US Cath Labs Market Key Industry Players
German and Dutch imaging hardware producers anchor one tier; American interventional device specialists hold differentiated positions in catheter and monitoring ecosystems. The vendor structure organizes around integrated suite providers, component specialists, and disposable supply chains. Three archetypes dominate: diversified health technology conglomerates, focused cardiovascular device manufacturers, and regional imaging equipment fabricators. Consolidation proceeds through health system enterprise contracting and vendor relationship standardization rather than horizontal acquisition.
Within the integrated suite tier, Siemens Healthineers and Koninklijke Philips N.V. occupy positions that exemplify hardware-led ecosystem strategies. Boston Scientific Corporation and Abbott Laboratories represent the interventional device archetype, anchoring catheter and monitoring platform supply. Medtronic sits within the electrophysiology specialization vector, differentiating through ablation mapping technologies. GE Healthcare and Shimadzu Corporation exemplify the diversified medical technology position, spanning imaging modalities beyond cardiovascular applications.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Johnson & Johnson |
| Koninklijke Philips N.V. |
| Shimadzu Corporation |
| Siemens Healthineers |
| GE Healthcare |
| Abbott Laboratories |
| B. Braun Melsungen AG |
| Medtronic |
| Others |
Cost & Logistics Intelligence
Hospital network consolidation into private-equity-backed health systems concentrates procurement leverage and compresses vendor margins across imaging hardware and disposable catheter contracts. This ownership pattern feeds supply chain standardization mandates that override best-of-breed preferences while locking in multi-year pricing agreements.
Pricing Analysis
High-volume coronary catheter contracts trade margin for shelf space while premium electrophysiology mapping systems retain pricing power through proprietary ecosystem lock-in. Three-tier pricing structure across premium OCT-guided suites, standard biplane configurations, and economy diagnostic-only labs reflects certification complexity and after-sales service bundling. Cost compression in consumables intensifies because GPO aggregation concentrates buyer power. Independent cardiology practices merging into hospital networks exhibit highest price sensitivity; academic medical centers piloting robotic navigation show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Asian flat-panel detector manufacturers that feed fluoroscopy assembly lines in Germany and the Netherlands. Component sourcing draws from Japan for precision sensors, South Korea for semiconductor substrates, and China for rare-earth phosphors. Raw material dependencies include cesium iodide scintillators, amorphous silicon photodiodes, and tungsten radiation shielding. Tariff exposure on Chinese electronic subassemblies elevates landed costs for imaging hardware. Distribution runs through manufacturer-direct sales teams for capital equipment and medical-surgical distributors for disposable accessories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US cath lab market sits in a technology-transition phase where optical coherence tomography and robotic catheter navigation displace conventional fluoroscopy-guided intervention. This displacement compresses legacy equipment replacement cycles while opening premium pricing windows for integrated imaging-robotics platforms.
For Market Incumbents: Lock in enterprise imaging contracts with HCA and Tenet before standardization programs harden. Defend catheter market share through backward integration into introducer sheath manufacturing. Prioritize FDA breakthrough designation pathways for OCT catheters to accelerate time-to-market against emerging robotics competitors. For New Entrants and Emerging Players: AI-assisted image interpretation platforms offer a technology-first wedge into crowded procedural documentation software. Rural hospital hub-and-spoke teleproctoring contracts in Montana and North Dakota present the most penetrable white-space target. Lead with remote interpretation service bundles rather than capital equipment sales to bypass certificate-of-need barriers. For Investors and Strategic Acquirers: CMS site-neutral payment policy finalization is the leading indicator that outpatient center valuations will compress relative to hospital-based labs. Long-term viability favors electrophysiology hybridization capabilities and AI-integrated imaging platforms over standalone diagnostic catheterization. Target acquisition archetype: mid-cap robotics specialists with FDA investigational device exemption status and hospital pilot contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Enterprise imaging contracts with HCA and Tenet lock out competing vendors across metropolitan markets. |
| FDA Submission | Breakthrough designation for OCT catheters accelerates approval timelines and commands premium pricing. |
| Software Companion Development | AI-assisted image interpretation integrates with existing Siemens and Philips platforms to capture retrofit demand. |
| Reimbursement Strategy | Site-neutral payment policy navigation determines outpatient center construction authorization and capital allocation. |
| CE Marking Pathway | European regulatory clearance validates safety profiles for subsequent FDA submissions and academic center pilots. |
Research Approach
Multi-period observation of cath lab construction permits, CMS reimbursement determinations, and vendor contract awards anchored the trend analysis, supplemented by interviews with interventional cardiologists, hospital purchasing committee directors, biomedical equipment planners, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, CMS Medicare cost reports, hospital procurement databases, and Joint Commission accreditation records. Bottom-up equipment shipment tracking and top-down health system capital expenditure disclosures were triangulated to reconcile volume estimates.
Segment-weighting across product type, end user facility category, imaging technology tier, and treatment procedure complexity structured the analytical framework. CAGRs were derived from installed base replacement cycles, procedure volume elasticity to reimbursement changes, and technology adoption S-curves across the analysis window. Forecast inputs included certificate-of-need approval timelines, radiation safety officer certification pipeline constraints, and flat-panel detector manufacturing capacity.
Several conditions sit outside the modeled scope, including unannounced FDA regulatory pathway modifications, state-level CON program eliminations, and macroeconomic shocks to hospital capital budgets. Forecasts reflect documented assumptions about CMS policy continuity and technology adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Automated Blood Processing Equipment Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Global Laboratory Equipment and Disposables Market
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
UK Pipette Tips Market
Laboratory Equipment
Laboratory Vacuum Drying Oven Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Micropipette Puller Market
Laboratory Equipment
Laboratory Supplies Market
Laboratory Equipment
Portable Hemoglobin Analyzer Market
Laboratory Equipment
Muffle Laboratory Furnaces Market
Laboratory Equipment
Scalable Clinical Chemistry Analyzers Market
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Electrophoresis Equipment and Supplies Market
Laboratory Equipment
ASEAN Laboratory Equipment Market