
 Micropipette Puller Market | 2026-2036
Micropipette Puller Market Size, Share, and Industry Trends Forecast 2026-2036
Micropipette Puller Market Foresight
Contract research organizations are bifurcating demand away from academic buyers in the micropipette puller landscape. Sutter Instrument dominates North American supply through its vertical integration into filament and heating element production. Harvard Bioscience sustains diversified exposure across life science tools, while Narishige International Limited anchors demand in Asia-Pacific patch-clamp installations.
A micropipette puller is a precision thermal or laser-based instrument that heats and draws glass capillary tubes into fine-tipped microelectrodes with tip diameters ranging below one micrometer, serving electrophysiology, microinjection, and micromanipulation protocols. Automatic pullers command the largest installed base due to reproducibility requirements in high-throughput screening, while laser technology segments expand fastest as researchers demand programmable tip geometries for single-cell recording. Digital pullers concentrate margin pools in pharmaceutical quality-control environments where protocol traceability is mandatory.
FDA device classification rules and ISO 13485 quality management standards shape product development pathways for manufacturers targeting clinical diagnostic applications. EPA hazardous material disclosures affect filament composition choices and regional supply qualification. Stakeholders must monitor evolving CE marking requirements under the EU Medical Device Regulation as European neuroscience funding agencies tighten equipment procurement specifications.
Market Dynamics
Laser-based pulling technology is compressing thermal filament margins while contract research organizations displace academic buyers as the dominant procurement segment, fundamentally restructuring vendor-customer relationships across the precision instrumentation landscape.
Growth Catalysts
- Patch-clamp electrophysiology expansion:Pharmaceutical companies are scaling precision puller procurement for ion-channel screening workflows, with demand concentrating in neuroscience-focused contract labs.
- EU Medical Device Regulation alignment:CE marking requirements under MDR are compelling manufacturers to upgrade quality systems, creating replacement cycles for installed base equipment.
- Programmable tip geometry demand:Single-cell recording protocols require laser-based systems capable of sub-micrometer precision control, accelerating technology substitution in advanced research facilities.
Market Restraints
- Platinum-iridium filament cost volatility:Precious metal input prices fluctuate with mining supply constraints, compressing gross margins for thermal puller manufacturers.
- Supply concentration in precision optics:Laser system component sourcing clusters in German and Japanese specialty glass suppliers, creating single-source vulnerability.
- ISO 13485 certification timeline friction:Clinical diagnostic pathway approvals extend product development cycles by 18-24 months versus research-use-only instruments.
Strategic Opportunities
- India pharmaceutical QC expansion:CDSCO-mandated quality control upgrades in generic drug manufacturing are creating first-time demand for traceable digital pullers.
- Microinjection automation convergence:Integration of robotic positioning systems with laser pullers enables unattended fabrication workflows for high-throughput facilities.
- Green filament chemistry transition:EPA hazardous material disclosure pressures are opening market share for tungsten-based alternatives with simplified environmental compliance.
Industry Challenges
- Electrophysiology technician scarcity:Specialized glass-pulling expertise retirement rates exceed training pipeline output in North American and European academic centers.
- Legacy thermal puller integration complexity:Retrofitting programmable controllers onto existing filament-based systems requires custom engineering that strains service organization capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micropipette Puller Market |
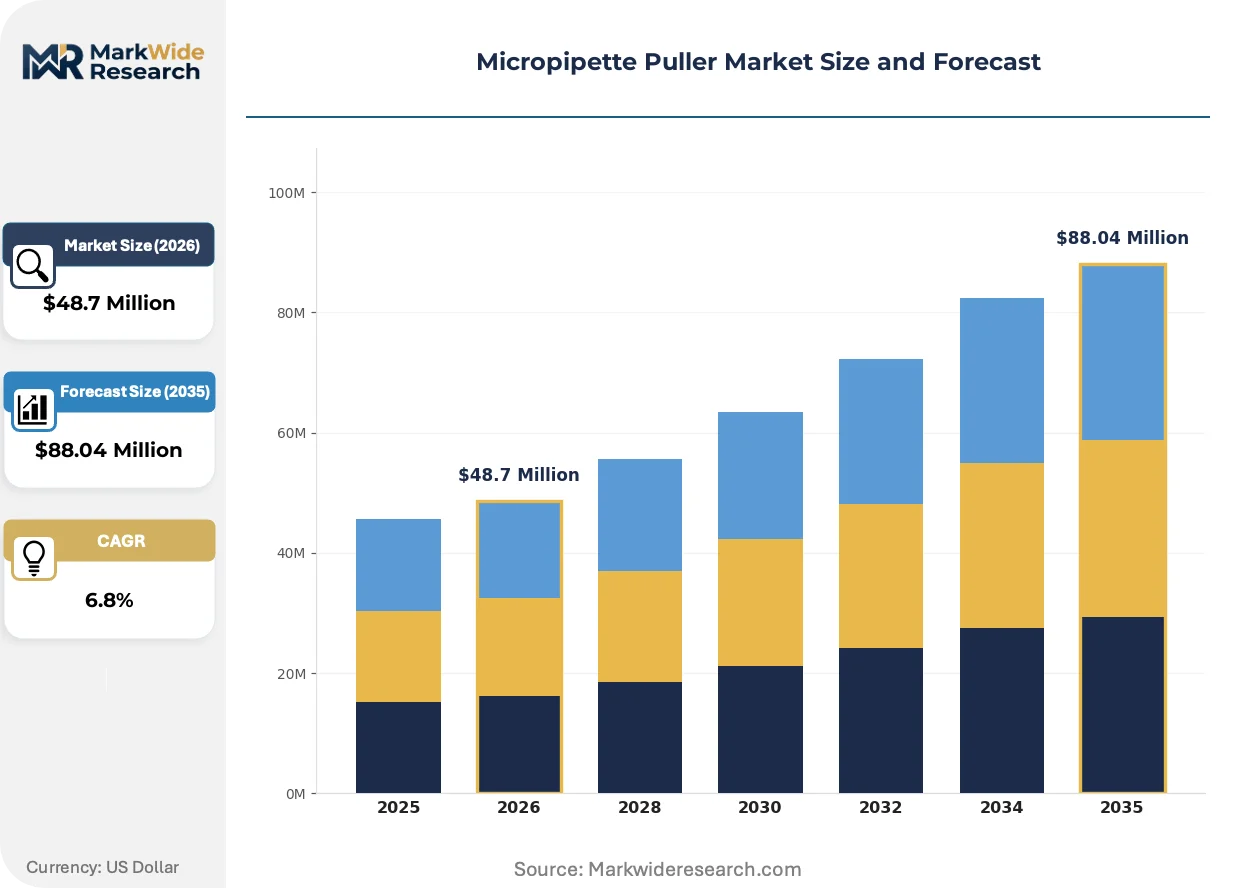
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Pullers, Automatic Pullers, Digital Pullers, Semi-Automatic Pullers End User: Research Laboratories, Educational Institutions, Pharmaceutical Companies, Biotechnology Firms Technology: Thermal Control, Laser Technology, Ultrasonic Technology, Pneumatic Mechanism Application: Molecular Biology, Cell Culture, Drug Development, Genetic Engineering |
| Companies Covered | Sutter Instrument, Tritech Research, Harvard Bioscience, Narishige International Limited, Scientifica, World Precision Instruments, MicroData Instrument, Advance Scientific Company, RWD Life Science, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micropipette Puller Market Shifts & Advancements
Digital control architectures and environmental compliance mandates are simultaneously elevating performance specifications and reshaping supplier qualification criteria across the micropipette puller value chain.
Femtosecond laser machining is miniaturizing tip fabrication tolerances below 0.1 micrometers for patch-clamp applications. Max Planck Institute network facilities are adopting these systems at replacement rates exceeding thermal equipment by three-to-one. The technology is miniaturizing the addressable market for conventional gravity-based pullers to entry-level educational settings.
REACH substance restrictions on heavy metals in heating elements are forcing filament composition redesigns across European supply chains. Manufacturers must reformulate alloys or source exempted materials, adding 12-18 months to product recertification timelines. Digital puller categories face the steepest compliance burden due to integrated heating element traceability requirements.
Consolidated procurement through centralized life science equipment consortia is displacing individual laboratory purchasing authority in German and French public research institutions. National funding agency tender specifications now mandate ISO 17025 calibration traceability and multi-year service bundling. This behavior concentrates vendor selection power with procurement departments rather than principal investigators.
Micropipette Puller Market Segmentation
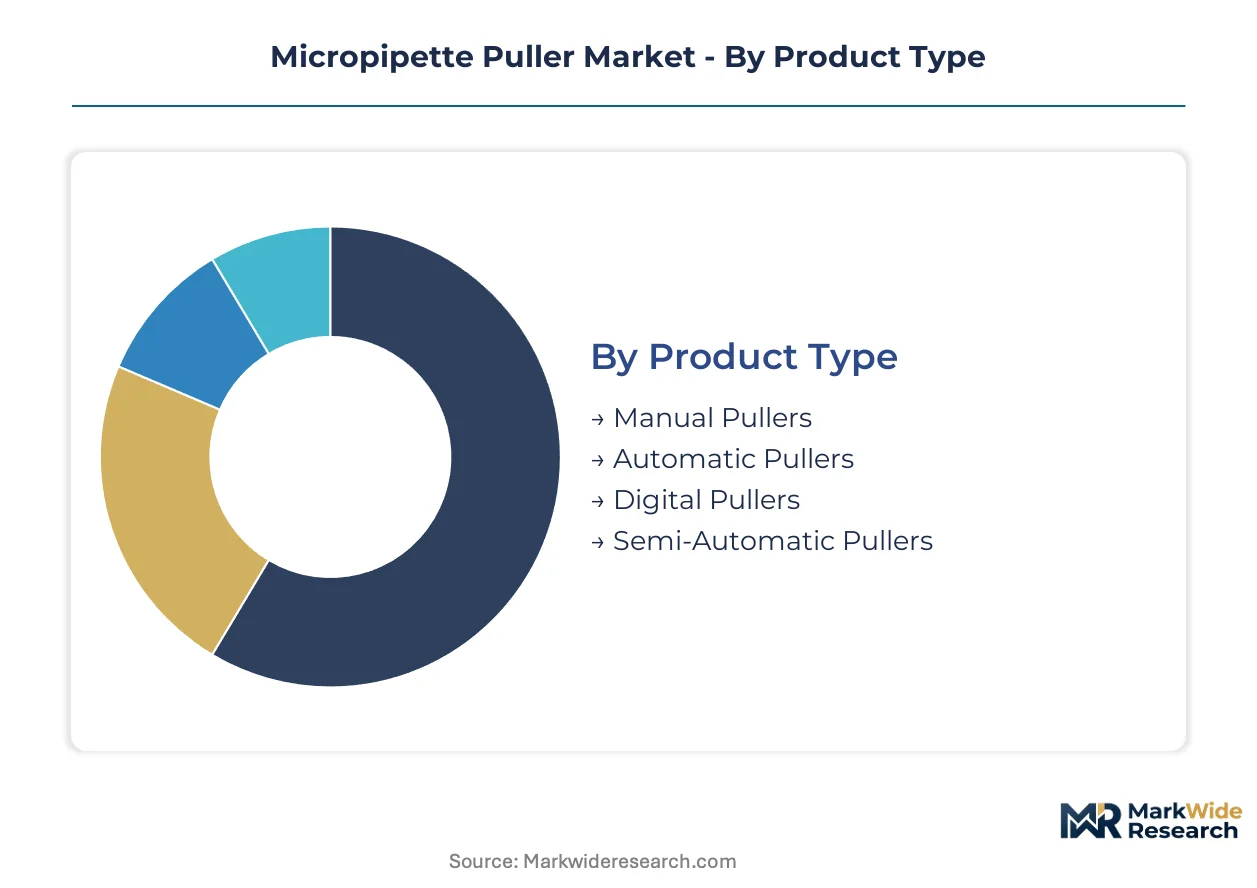
Micropipette puller procurement splits sharply across regulatory environments. FDA device classification rules and ISO 13485 mandates create distinct product development pathways that segment vendor offerings by certification tier and end-use compliance burden.
Product Type:
FDA 510(k) clearance requirements and ISO 13485 quality system audits differentiate installed base economics across automation levels.
- Automatic Pullers:Programmable heating profiles with reproducible tip geometries dominate high-throughput screening workflows. Pharmaceutical quality-control laboratories in Germany and the United States specify these systems for protocol traceability under FDA 21 CFR Part 11 and EU GMP Annex 11.
- Digital Pullers:Integrated data logging and calibration certificate generation command premium positioning in contract research organizations facing CDSCO, FDA, and EMA inspection readiness requirements. India's pharmaceutical QC expansion drives first-time procurement of traceable digital systems.
- Manual Pullers:Gravity-based mechanical systems retain installed base in entry-level educational settings with minimal regulatory exposure.
- Semi-Automatic Pullers:Hybrid designs bridge cost-performance gaps for mid-tier research laboratories in Asia-Pacific academic centers.
Established volume favors Automatic Pullers; emerging adoption favors Digital Pullers.
End User:
Procurement authority concentration reshapes demand patterns across institutional types.
- Pharmaceutical Companies:Ion-channel screening workflows and patch-clamp electrophysiology expansion scale precision puller procurement. Centralized equipment consortia in German public research institutions now mandate ISO 17025 calibration traceability and multi-year service bundling.
- Research Laboratories:Max Planck Institute network facilities and affiliated commercial labs concentrate laser-based system demand. Femtosecond laser machining adoption exceeds thermal equipment replacement rates by substantial margins in these settings.
- Biotechnology Firms:Venture-backed cell therapy developers prioritize programmable tip geometry for single-cell recording protocols.
- Educational Institutions:Budget constraints and minimal regulatory exposure sustain legacy thermal puller installed base.
Procurement centralization favors Pharmaceutical Companies; technology substitution favors Research Laboratories.
Technology:
Component sourcing geography and environmental compliance burden stratify competitive positioning.
- Laser Technology:Femtosecond machining achieves sub-0.1 micrometer fabrication tolerances for advanced patch-clamp applications. German and Japanese specialty glass suppliers concentrate precision optics sourcing, creating single-source vulnerability.
- Thermal Control:Platinum-iridium filament systems face REACH substance restrictions and EPA hazardous material disclosure pressures. Precious metal input cost volatility compresses gross margins for manufacturers.
- Ultrasonic Technology:Niche positioning in microinjection automation convergence with robotic positioning systems.
- Pneumatic Mechanism:Limited adoption in gravity-assisted educational equipment with minimal regulatory compliance requirements.
Performance specifications favor Laser Technology; cost accessibility favors Thermal Control.
Application:
Workflow integration complexity and regulatory submission requirements segment demand by therapeutic area.
- Drug Development:FDA IND-enabling studies and EMA clinical trial applications mandate equipment qualification documentation. Contract research organizations displace academic buyers as dominant procurement segment in this application.
- Molecular Biology:CRISPR microinjection and single-cell analysis protocols drive laser-based system specification. Patch-clamp electrophysiology expansion concentrates demand in neuroscience-focused contract laboratories.
- Cell Culture:Stem cell and organoid workflows require reproducible tip geometries for micromanipulation.
- Genetic Engineering:Transgenic animal production sustains steady thermal puller demand in agricultural biotechnology settings.
Regulatory intensity favors Drug Development; technology refresh cycles favor Molecular Biology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics suppliers export laser components to neuroscience facilities in the United States and Japan, establishing the primary trade-flow corridor for advanced micropipette puller technology.
United States
FDA 510(k) clearance requirements and patch-clamp electrophysiology expansion drive pharmaceutical procurement in Massachusetts and California clusters. EPA hazardous material disclosure rules affect filament composition choices for domestic manufacturers. Boston-Cambridge neuroscience facilities displace academic buyers with contract research organization procurement concentration.
Germany
Max Planck Institute network facilities anchor laser-based system demand with replacement rates exceeding thermal equipment substantially. EU Medical Device Regulation CE marking mandates compel manufacturers to upgrade quality systems for clinical diagnostic pathways. Baden-Württemberg precision optics suppliers concentrate component sourcing for femtosecond machining systems.
Japan
PMDA quality system audits and single-cell recording protocol adoption accelerate programmable tip geometry specifications. METI technology standards influence laser system certification timelines for research-use instruments. Kansai region academic centers maintain thermal puller installed base while Tokyo-area facilities transition to laser technology.
India
CDSCO-mandated quality control upgrades in generic drug manufacturing create first-time demand for traceable digital pullers. Central Drugs Standard Control Organization inspection readiness requirements concentrate procurement in Maharashtra and Gujarat pharmaceutical corridors. Hyderabad and Mumbai contract research organizations displace individual laboratory purchasing authority with centralized equipment consortia.
United Kingdom
ISO 17025 calibration traceability mandates from research funding agencies reshape vendor selection criteria in Cambridge and Oxford clusters. MHRA device registration requirements extend product development cycles for clinical diagnostic applications. London-based life science equipment consortia consolidate procurement power with principal investigators.
Micropipette Puller Market Competitive Landscape
Listed leaders compete with private specialists across automation tiers and geographic coverage, producing a bifurcated structure where scale-driven public companies face niche-focused family-owned enterprises. The vendor base stratifies into three tiers: premium laser-system specialists, mid-market automatic puller providers, and entry-level thermal equipment fabricators. Two dominant competitive moves define current positioning: backward integration into captive filament and heating element production, and strategic partnerships with centralized university procurement consortia.
Among United States-based instrument manufacturers, Sutter Instrument Co. and Harvard Bioscience Inc. occupy positions in the premium automation tier, while Narishige International Limited exemplifies the Asia-Pacific specialist archetype with concentrated exposure to patch-clamp installation workflows. These three entities represent contrasting strategic postures: one emphasizes in-house production of precision components, another sustains diversified life science tools exposure, and the third anchors regional demand through specialized electrophysiology expertise.
| Leading Market Players |
|---|
| Sutter Instrument |
| Tritech Research |
| Harvard Bioscience |
| Narishige International Limited |
| Scientifica |
| World Precision Instruments |
| MicroData Instrument |
| Advance Scientific Company |
| RWD Life Science |
| Others |
Supply & Pricing Matrix
Capacity utilization at German precision optics suppliers sets price floors for femtosecond laser systems while compressing margins for thermal filament manufacturers facing precious metal volatility. Scale concentration in Baden-Württemberg component fabrication and Japanese specialty glass production creates asymmetric pricing power that ripples through downstream equipment tiers.
Pricing Analysis
Current-generation laser pullers command substantial premiums over prior-generation thermal systems and entry-level gravity-based equipment, with next-generation femtosecond platforms entering at the apex. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified clinical systems from research-use automatic pullers and educational manual units. Cost compression in thermal equipment is intensifying because platinum-iridium filament price volatility erodes manufacturer margins. Contract research organizations demonstrate lowest price sensitivity due to bundled service requirements, while educational institutions in Asia-Pacific academic centers exhibit highest elasticity.
Supply Chain Analysis
Extended lead times for precision optics from German and Japanese suppliers constrain production scheduling for laser system manufacturers. Component sourcing clusters in Germany, Japan, and the United States for femtosecond machining hardware, platinum-iridium alloys, and programmable controller assemblies. Single-source vulnerability in specialty glass feedstock creates systemic exposure to regional disruption. Distribution runs through centralized life science equipment consortia in German public research institutions and pharmaceutical procurement clusters in Massachusetts and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by EU Medical Device Regulation recertification waves that compelled replacement purchasing across European neuroscience facilities.
For Market Incumbents: Fortify captive supply of heating elements and precision optics to offset single-source vulnerability in German and Japanese component markets. Deepen backward integration into filament alloy production to mitigate platinum-iridium cost volatility threatening thermal equipment margins. Prioritize ISO 17025 calibration service bundling to defend against centralized procurement consortia extracting price concessions.
For New Entrants and Emerging Players: CDSCO fast-track certification for digital pullers unlocks first-mover positioning in India's pharmaceutical quality-control expansion. Target Maharashtra and Gujarat generic drug manufacturing corridors where traceable equipment procurement is nascent. Pursue white-label partnerships with established distribution networks rather than direct sales infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among laser-system specialists with multi-year service contracts and consumables lock-in. Five-to-ten year viability favors vendors with clinical diagnostic pathway approvals and backward integration into precision component production. Monitor femtosecond adoption rates at Max Planck Institute network facilities as inflection signal for technology substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Laser Technology Platform Migration | Femtosecond systems displace thermal equipment at Max Planck Institute facilities three-to-one. |
| ISO 13485 Quality System Upgrade | CE marking under EU MDR compels replacement cycles for installed base equipment. |
| Backward Integration into Filament Production | Sutter Instrument's captive heating element supply insulates margins from precious metal volatility. |
| Centralized Procurement Consortium Partnership | German national funding agency tenders mandate multi-year service bundling and calibration traceability. |
| CDSCO Certification Fast-Track | India's pharmaceutical QC expansion creates first-time demand for traceable digital pullers. |
Research Methodology
The analysis maps laser-based, thermal control, ultrasonic, and pneumatic micropipette puller sub-sectors, each validated through electrophysiology technicians, pharmaceutical procurement managers, biomedical engineers, and laboratory equipment distributors. Primary interviews with patch-clamp specialists and contract research organization purchasing committees combined with secondary validation against FDA 510(k) filings, EMA device registrations, EU funding agency tender specifications, and ISO certification databases. Bottom-up equipment shipment tracking and top-down neuroscience research funding allocation triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models automation level, technology generation, end-user institution type, application workflow, and regional regulatory cluster segmentation. CAGRs derive from equipment replacement cycle analysis and funding flow projections. Forecast inputs incorporate femtosecond laser adoption curves and REACH substance restriction compliance timelines.
Decision-makers should treat outputs as directional under assumptions of sustained pharmaceutical R&D expenditure and stable precious metal supply; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Microplate Washer Market
Laboratory Equipment
Laboratory Furnaces Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Electronic Multichannel Pipettes Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Laboratory Vacuum Drying Oven Market
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Latin America Laboratory Equipment and Disposables Market
Laboratory Equipment
Global Blood Gas Analyzers Market
Laboratory Equipment
Benchtop Centrifuges Market
Laboratory Equipment
Orbital Shakers Market
Laboratory Equipment
Laboratory Furniture Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Laboratory Pulverizer Market