
 Surgical Dressings and Disposables Market | 2026-2036
Surgical Dressings and Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Dressings and Disposables Market Outlook
East Asian non-woven fabric producers is consolidating output for medical-grade spunbond and meltblown layers used in advanced wound care. Medline Industries, LP leverages vertically integrated U.S. distribution to sustain hospital contract renewals. Smith & Nephew plc anchors its position through silicone foam technology leadership in post-operative segments. B. Braun SE competes via sterile kit bundling that reduces operating room preparation time.
Surgical dressings and disposables encompass sterile barrier products, absorbent pads, and tissue-contact materials engineered to maintain moisture balance, prevent infection, and support hemostasis during and after operative procedures; most advanced variants incorporate antimicrobial agents such as silver or iodine within hydrocolloid or alginate matrices. The primary commercial purpose centers on reducing surgical site complications while enabling faster patient mobilization and shorter hospital stays. Cotton and non-woven fabric materials dominate volume production due to cost scalability, though biodegradable materials represent the fastest-growing margin pool as EU Green Deal procurement criteria tighten. Film dressings and hydrocolloid dressings capture premium pricing in outpatient settings where wear time and cosmetic outcomes matter most.
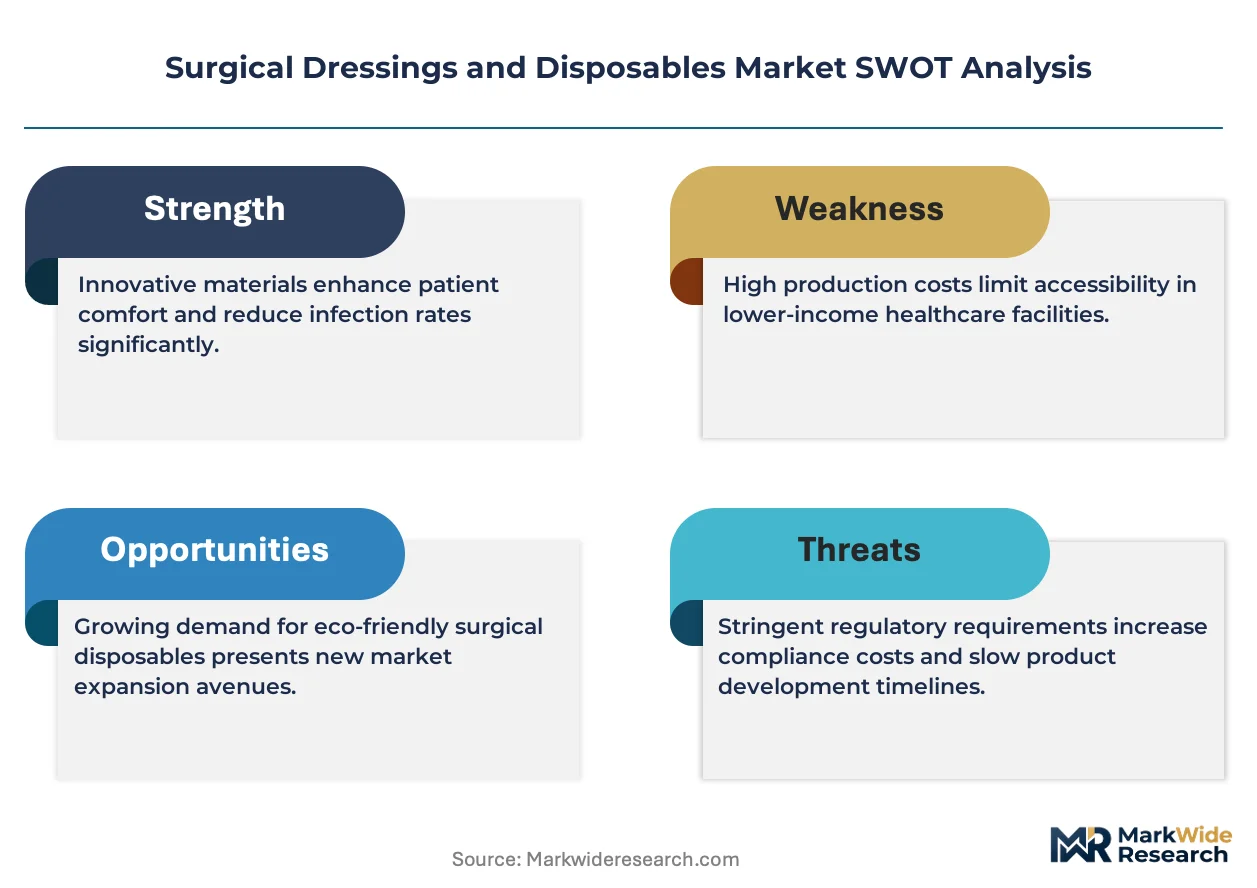
FDA 510(k) premarket notification requirements and EU MDR technical documentation standards elevate barrier costs for new entrants while accelerating consolidation among established manufacturers. ISO 13485 quality management certification now functions as a baseline qualification rather than a differentiator for hospital purchasing committees. Stakeholders must monitor how CMS reimbursement shifts toward bundled payment models reshape product selection criteria away from unit cost toward total episode-of-care outcomes.
Market Dynamics
EU MDR technical documentation requirements and FDA 510(k) clearance pathways are compressing product development timelines while elevating capital requirements for sterile barrier and antimicrobial dressing manufacturers. These regulatory pressures favor established players with dedicated regulatory affairs infrastructure.
Growth Catalysts
- Chronic wound prevalence:Aging populations in the United States, Germany, and Japan expand demand for advanced moisture-retentive dressings in home care and outpatient settings.
- EU Green Deal procurement criteria:Biodegradable material mandates in European public tenders accelerate substitution of petroleum-based non-wovens with plant-derived alternatives.
- Silver-ion antimicrobial integration:Hospital-acquired infection protocols now specify ionic silver or iodine matrices for post-operative dressings, pulling premium product adoption.
Market Restraints
- Medical-grade polymer input volatility:Polypropylene and polyurethane price swings squeeze margins on spunbond and meltblown fabric production.
- East Asian non-woven supply concentration:Spunbond and meltblown layer production clusters in China and South Korea create single-source vulnerability for Western converters.
- EU MDR transition friction:Extended technical documentation review timelines delay product launches and freeze R&D budgets for mid-tier manufacturers.
Strategic Opportunities
- Underpenetrated Indian outpatient surgery:Ambulatory surgical center expansion under Ayushman Bharat creates first-mover positioning for sterile kit bundlers.
- Brazilian ANVISA fast-track pathway:Expedited registration for antimicrobial dressings accelerates market entry timelines versus standard review cycles.
- Smart dressing convergence:pH-responsive hydrogels combined with wireless temperature monitoring enable remote wound assessment in telehealth programs.
Industry Challenges
- ISO 13485 auditor capacity constraints:Certification body backlogs extend quality management system renewal timelines, freezing supplier qualification for hospital contracts.
- Legacy ERP integration with UDI compliance:Unique Device Identification serialization requirements force expensive middleware upgrades for mid-size manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Dressings and Disposables Market |
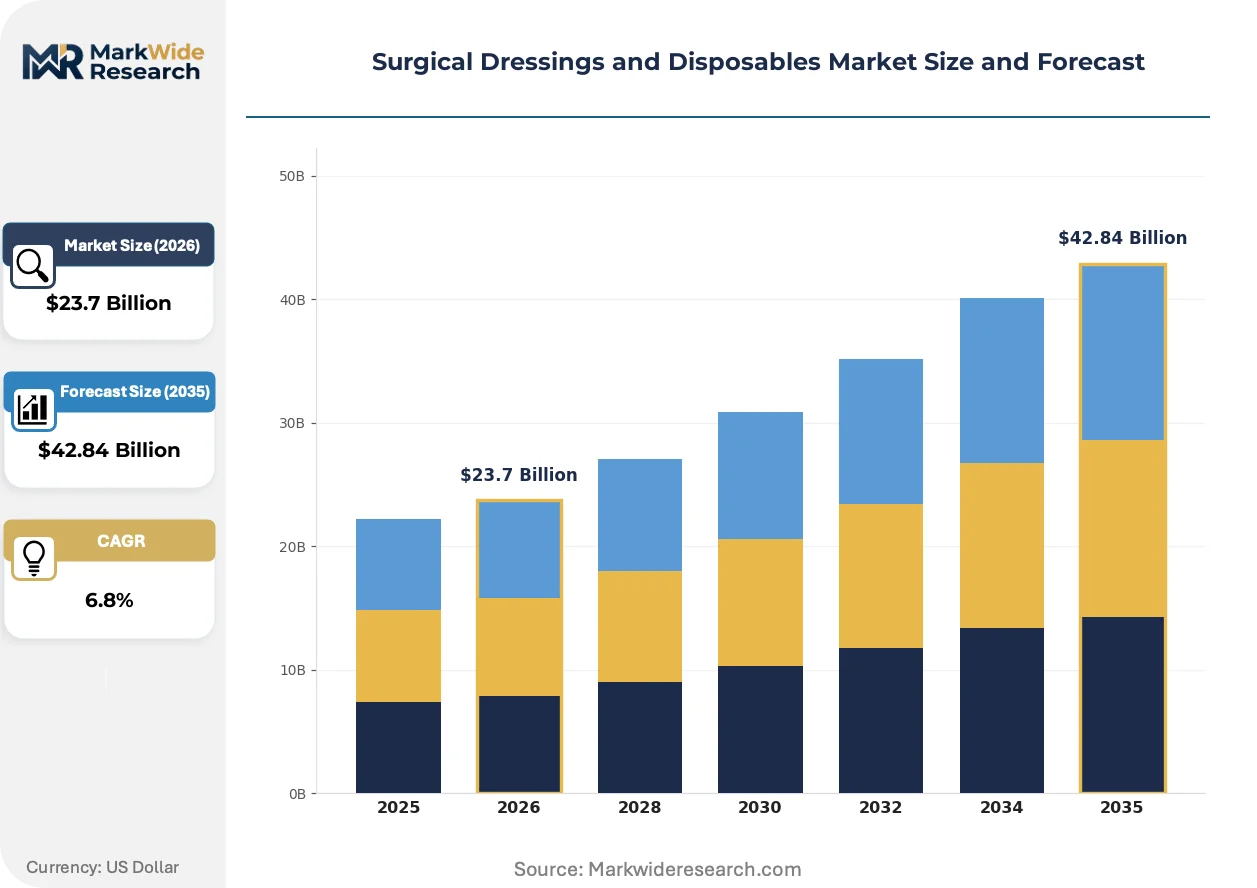
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Bandages, Gauze, Film Dressings, Hydrocolloid Dressings Material: Cotton, Foam, Non-woven Fabrics, Biodegradable Materials End User: Hospitals, Surgical Centers, Home Care, Clinics Packaging Type: Sterile Packs, Bulk Packs, Individual Packs, Cartons |
| Companies Covered | 3M Company, Medline Industries, LP, Smith & Nephew plc, B. Braun SE, Cardinal Health Inc., Mölnlycke Health Care AB, Coloplast, Johnson & Johnson, ConvaTec Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Dressings and Disposables Market Strategic Shifts
Active materials science and regulatory data requirements are converging to redefine product architecture in wound care, with moisture management and infection prevention functions merging into single-layer systems.
Silicone foam technology is consolidating post-operative dressing standards by enabling atraumatic removal and extended wear time. Ambulatory surgical centers in the United States and Western Europe are standardizing on silicone-adherent variants for outpatient procedures. This material transition is compressing demand for traditional adhesive non-woven alternatives while expanding average selling prices in premium segments.
EU MDR post-market surveillance requirements now mandate systematic clinical follow-up data for antimicrobial claims. Manufacturers must maintain vigilance systems tracking device performance across distributed hospital networks. Class III dressing categories face the steepest documentation burdens, driving portfolio rationalization toward lower-risk classifications.
Hospital purchasing committees now weight total episode-of-care outcomes over unit cost in vendor selection. Bundled payment models from CMS and private payers in the United States reward reduced surgical site infection rates rather than material savings. This behavioral shift elevates antimicrobial and advanced moisture-retentive dressings in procurement scoring algorithms.
Surgical Dressings and Disposables Market Segmentation
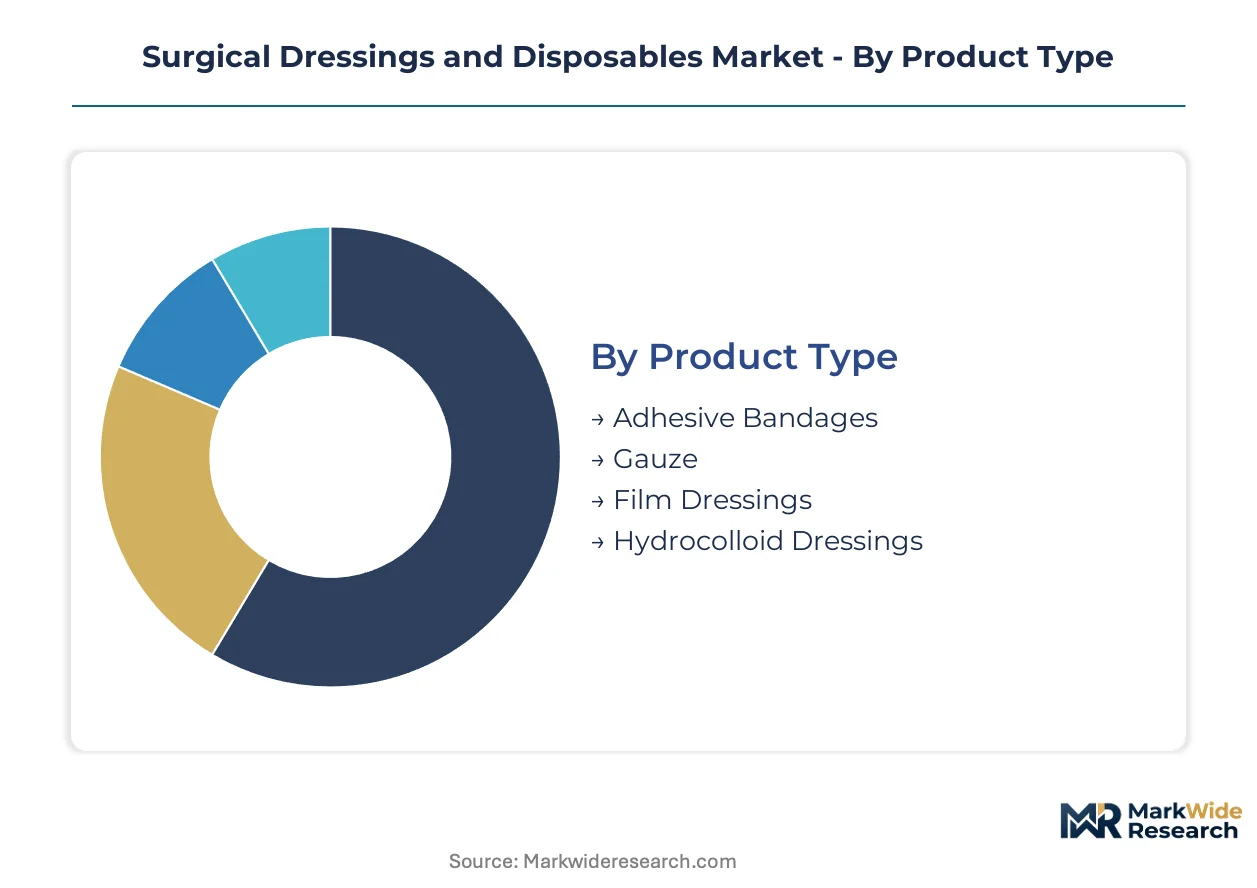
Surgical dressing procurement diverges sharply across care settings, with material specifications and packaging formats calibrated to infection risk profiles and reimbursement structures. Product type selection now tracks directly to ambulatory expansion and home care discharge protocols.
Product Type:
Replacement cycles in post-operative care are compressing as silicone-adherent technologies displace traditional adhesives in outpatient settings.
- Hydrocolloid Dressings:Gel-forming matrices composed of carboxymethylcellulose and gelatin manage exudate while maintaining moist wound environments. Demand concentrates in German and Japanese home care segments where aging populations require extended wear time for chronic wounds.
- Film Dressings:Semi-permeable polyurethane membranes permit moisture vapor transmission while blocking liquid and bacterial ingress. United States ambulatory surgical centers specify transparent variants for cosmetic-sensitive procedures and remote visual monitoring.
- Adhesive Bandages:Woven or plastic strip constructions with absorbent non-adherent pads serve low-exudate traumatic injuries and minor surgical closures.
- Gauze:Woven cotton or synthetic mesh fabrics provide primary or secondary dressing layers for heavily exuding wounds and intraoperative packing.
Volume placements concentrate in gauze and adhesive bandages; the faster expansion belongs to hydrocolloid variants.
Material:
Cost tiers separate commodity inputs from certified medical-grade substrates with validated biocompatibility documentation.
- Non-woven Fabrics:Spunbond and meltblown polypropylene layers engineered for barrier protection and controlled permeability. East Asian producers in China and South Korea supply Western converters facing EU Green Deal substitution pressures.
- Biodegradable Materials:Polylactic acid and cellulose-derived substrates decompose under industrial composting conditions. European public tenders under EU Green Deal procurement criteria accelerate hospital adoption despite 15-30% price premiums.
- Cotton:Bleached and carded natural fibers remain the reference standard for absorbency in traditional gauze and padding applications.
- Foam:Hydrophilic polyurethane structures manage moderate-to-heavy exudate with thermal insulation and cushioning properties.
Non-woven fabrics dominate hospital purchase orders; biodegradable alternatives are climbing the fastest as regulatory deadlines approach.
End User:
Application intensity varies by procedure volume and reimbursement methodology across institutional settings.
- Surgical Centers:High-throughput ambulatory facilities in the United States standardize on pre-sterilized kit configurations to minimize room turnover time. Bundled payment models from CMS reward reduced surgical site infection rates over material cost minimization.
- Home Care:Post-acute discharge protocols in Germany and Japan extend dressing change responsibilities to patients and informal caregivers. Moisture-retentive technologies with extended wear intervals reduce nursing visit frequency.
- Hospitals:Inpatient surgical departments maintain diverse inventory for complex wound presentations and intensive care requirements.
- Clinics:Primary care and specialty outpatient facilities manage lower-acuity wound presentations with constrained storage capacity.
Surgical centers capture the steepest placement growth; home care represents the fastest-expanding value pool as length-of-stay contracts.
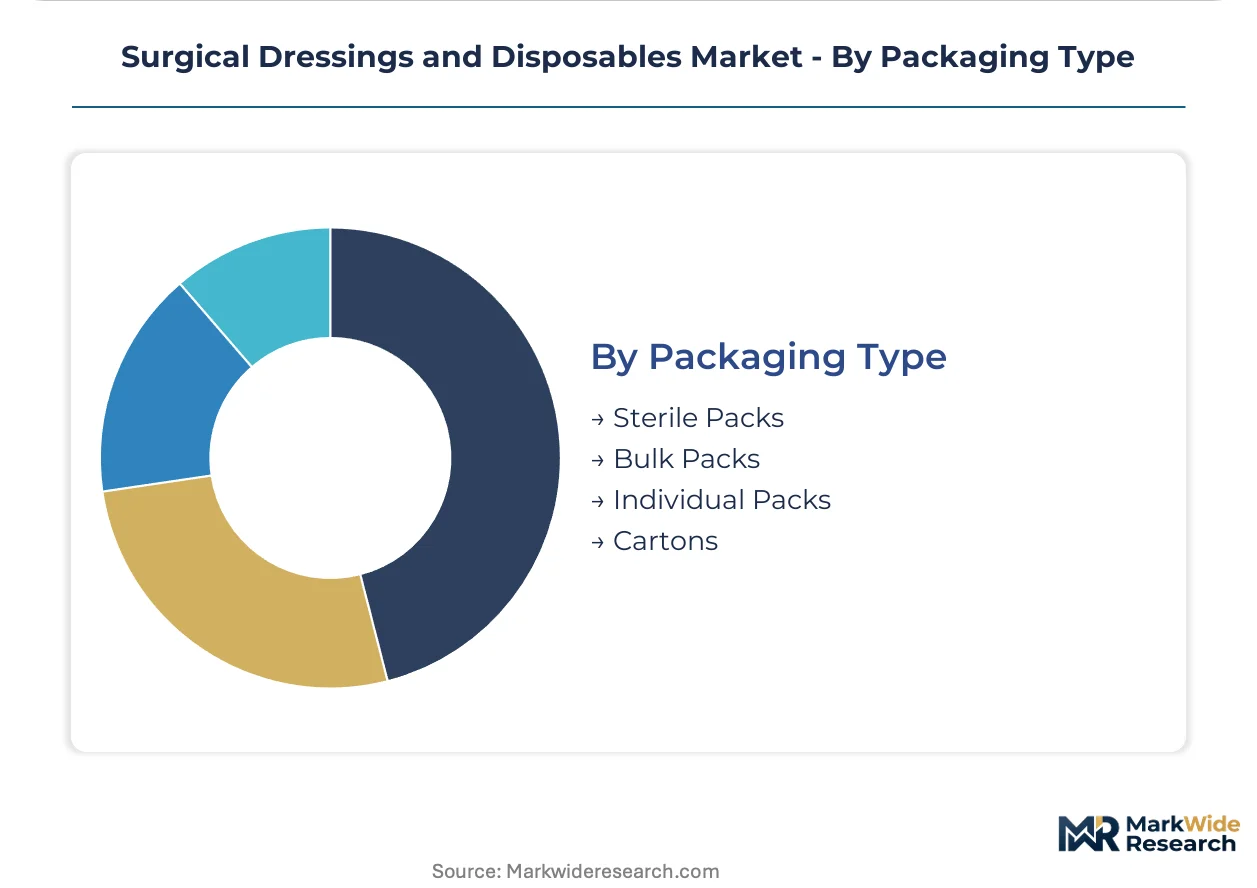
Packaging Type:
Supply concentration in sterile barrier manufacturing shapes availability and qualification timelines for format selection.
- Sterile Packs:Individually sealed units terminally sterilized via ethylene oxide or gamma irradiation maintain aseptic integrity through point-of-use. FDA 510(k) clearance pathways and EU MDR technical documentation requirements elevate barrier costs for new entrants.
- Individual Packs:Single-unit non-sterile or clean packaging for low-risk applications and patient self-administration.
- Bulk Packs:Multi-unit configurations reduce per-piece handling costs for high-consumption hospital departments with in-house sterilization capability.
- Cartons:Secondary packaging aggregating multiple primary units for logistics efficiency and inventory management.
Sterile packs command premium positioning in surgical workflows; individual packs are gaining share fastest in direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene feedstock availability in the US Gulf Coast anchors sterile barrier manufacturing for North American wound care supply chains. German chemical clusters supply medical-grade polyurethane precursors to European dressing converters. East Asian spunbond production concentrates in Zhejiang Province and Gyeonggi-do.
United States
FDA 510(k) clearance pathways and CMS bundled payment models drive demand for antimicrobial dressings in ambulatory surgical centers. The IRA's domestic manufacturing incentives support reshoring of meltblown fabric production. Houston-area petrochemical complexes supply propylene monomer to medical non-woven converters along the Gulf Coast.
Germany
EU MDR technical documentation requirements and aging population demographics expand home care dressing demand. The EU Green Deal procurement criteria accelerate biodegradable material substitution in public hospital tenders. North Rhine-Westphalia's chemical industry corridor supplies polyurethane precursors to dressing manufacturers in the Ruhr region.
Japan
PMDA regulatory harmonization with IMDRF standards streamlines antimicrobial dressing approvals for elderly care applications. METI's healthcare technology roadmaps prioritize smart wound monitoring integration. Osaka-based chemical producers supply hydrocolloid gel precursors to Kansai region medical device fabricators.
China
NMPA medical device classification reforms and domestic hospital procurement centralization reshape competitive access. MIIT's medical materials industrial policy targets import substitution in high-end wound care. Zhejiang Province's non-woven textile clusters in Shaoxing and Jiaxing export spunbond layers to Western converters.
India
Ayushman Bharat ambulatory surgical center expansion and CDSCO streamlined licensing create first-mover opportunities for sterile kit bundlers. BIS certification requirements for medical textiles elevate quality barriers for local producers. Gujarat's chemical manufacturing belt in Vadodara and Ahmedabad supplies pharmaceutical-grade cotton processing.
Surgical Dressings and Disposables Market Competitive Environment
Global majors compete with regional champions across regulatory compliance infrastructure and sterile barrier manufacturing scale. The vendor base stratifies into three tiers: integrated multinationals with captive polymer supply, mid-cap specialists with regional regulatory depth, and commodity converters competing on unit economics. Dominant competitive moves include backward integration into meltblown fabric production and strategic partnerships with ambulatory surgical center chains.
Within the integrated multinational tier, 3M Company and Medline Industries, LP exemplify players with vertically controlled supply chains spanning polymer feedstock to hospital distribution. Smith & Nephew plc occupies a position representing European regulatory specialization in advanced wound care segments. These anchors demonstrate how regulatory affairs infrastructure and sterile manufacturing certification function as primary competitive moats rather than product differentiation alone.
| Leading Market Players |
|---|
| 3M Company |
| Medline Industries, LP |
| Smith & Nephew plc |
| B. Braun SE |
| Cardinal Health Inc. |
| Mölnlycke Health Care AB |
| Coloplast |
| Johnson & Johnson |
| ConvaTec Group plc |
| Others |
Value Chain & Pricing Dynamics
Hospital purchasing committees and ambulatory surgical center GPOs now dominate procurement volume, anchoring contract-based long-term offtake pricing that compresses spot-market exposure for converters. This buyer concentration elevates antimicrobial and silicone-foam premiums while squeezing commodity gauze margins through consolidated tender awards.
Pricing Analysis
Service bundling separates sterile kit configurations with operating room preparation support from unbundled commodity gauze sold on unit economics. Three-tier pricing structure across premium antimicrobial, standard moisture-retentive, and economy cotton gauze levels tracks certification grade and FDA 510(k) clearance status. Pricing pressure stems from polypropylene feedstock volatility in Gulf Coast petrochemical corridors. Ambulatory surgical centers exhibit lowest price sensitivity due to CMS bundled payment incentives rewarding infection reduction over material savings.
Supply Chain Analysis
Workforce availability constraints in Zhejiang Province and Gyeonggi-do limit expansion of medical-grade spunbond and meltblown capacity despite surging Western demand. Supply concentrates in China, South Korea, and the US Gulf Coast for polypropylene resin and non-woven fabric conversion. Raw material dependencies include propylene monomer, medical-grade polyurethane precursors from North Rhine-Westphalia, and hydrocolloid gel inputs from Osaka chemical producers. Single-source vulnerability in East Asian meltblown production creates chokepoint exposure. Distribution runs through vertically integrated hospital distributors and GPO contracts in North America, regional medical wholesalers in Europe, and centralized procurement platforms in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU MDR compliance costs and ISO 13485 auditor backlogs force mid-tier manufacturers toward exit or acquisition.
For Market Incumbents: To counter regulatory documentation burdens freezing R&D budgets, deepen backward integration into meltblown fabric production in US Gulf Coast corridors and secure dedicated ISO 13485 auditor relationships through certification body partnerships. These moves defend sterile barrier manufacturing scale against emerging Asian competitors. For New Entrants and Emerging Players: Enter via Brazilian ANVISA fast-track antimicrobial dressing registrations and Indian Ayushman Bharat ambulatory surgical center sterile kit bundling. Target underpenetrated outpatient surgery segments where regulatory friction remains lower than EU MDR jurisdictions. Pursue hospital system partnership go-to-market angles rather than direct GPO competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with regional regulatory depth in Germany and Japan facing EU MDR transition friction. Long-term viability over a multi-year horizon rests on captive sterile manufacturing certification and hospital contract renewal rates. Watch CMS reimbursement shifts toward total episode-of-care outcomes as the inflection signal elevating antimicrobial dressing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates US market entry for antimicrobial dressing variants against standard review timelines. |
| EU MDR Technical Documentation | Elevates barrier costs for new entrants while consolidating established manufacturer positions. |
| Hospital System Partnership | Secures GPO contract renewals through operating room preparation time reduction guarantees. |
| Backward Integration into Meltblown | Captures polypropylene feedstock margin and insulates against East Asian supply concentration. |
| Reimbursement Strategy | Aligns antimicrobial claims with CMS bundled payment incentives rewarding infection reduction. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and customs trade data, complemented by interviews with regulatory affairs directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary fieldwork across North American, European, and East Asian markets was validated against secondary sources including SEC filings, CMS reimbursement data, and chemical industry production reports. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to produce volume and value outputs.
Cross-referencing historical pricing trajectories against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, material substrate, end-user setting, and packaging format. CAGRs were derived from demand elasticity coefficients calibrated to ambulatory surgical center expansion rates and chronic wound prevalence demographics. Industry-specific forecast inputs incorporated polypropylene feedstock price indices and EU Green Deal procurement timeline assumptions.
Revisions become necessary when EU MDR transition timelines extend, ISO 13485 auditor capacity constraints deepen, or CMS reimbursement models shift materially. Forecasts reflect documented assumptions about regulatory compliance costs and hospital purchasing behavior. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Pressure Monitoring Extension Tubing Sets Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
Medical Gas Market
Medical Supplies
Alcohol Prep Pads Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Europe Surgical Glue Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Transfusion Bottles Market
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market
Medical Supplies
Global Povidone Iodine Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Global Medical Waste Containers Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Global IV Flush Syringe Market
Medical Supplies
Medical Liners Market