
 Lab Accessories Market | 2026-2036
Lab Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Lab Accessories Market Intelligence
Modular automation platforms are reshaping how laboratories configure their accessory ecosystems, enabling plug-and-play integration between pipetting systems and sample prep workflows. Thermo Fisher Scientific leverages its vertical integration across consumables and instrumentation to sustain pricing power in high-throughput environments. Danaher Corporation anchors its position through stringent quality certifications that dominate pharmaceutical QC workflows. Eppendorf AG specializes in precision liquid handling accessories that command premium positioning in academic research markets.
Lab accessories encompass consumable and reusable implements—including polypropylene centrifuge tubes rated for 15,000×g, borosilicate glass petri dishes, and graduated micropipette tips calibrated to ISO 8655 tolerances—designed to ensure reproducibility, contamination control, and operator safety across analytical and preparative workflows. Micropipettes and centrifuge tubes occupy the largest revenue pools due to their universal deployment across biotechnology and pharmaceutical research applications, while cryovials represent the fastest-expanding category as biobanking infrastructure scales for cell and gene therapy supply chains. Diagnostic centers and quality control labs concentrate margin capture through high-frequency reorder patterns and stringent vendor qualification requirements that lock in multi-year supply agreements.
FDA 21 CFR Part 11 compliance requirements shape electronic record-keeping for accessories used in GMP environments, while ISO 13485 certification gates market access for products supporting in-vitro diagnostic workflows. REACH substance restrictions and EU MDR traceability mandates in Europe compel manufacturers to reformulate plastics and implement lot-level digital tracking. Stakeholders must monitor evolving dual-use export controls on precision liquid handling technologies and assess whether regional biomanufacturing subsidies will redirect procurement toward domestic supply bases.
Market Dynamics
ISO 17025 quality mandates are compressing vendor qualification timelines while Fraunhofer institutes and Max Planck facilities in Germany's Baden-Württemberg corridor drive high-volume procurement of certified labware with full lot-level traceability.
Growth Catalysts
- Cell therapy workflow scale-up:Biotechnology firms are expanding precision liquid handling tool procurement to support commercial manufacturing transitions. Academic medical centers in the United States are following this procurement pattern.
- ISO 17025 tightening:Quality mandates across North America and Europe now require full digital traceability for consumables used in analytical workflows. Diagnostic laboratories are upgrading vendor qualification protocols.
- Biobanking infrastructure build-out:Cryogenic storage systems for cell and gene therapy supply chains are driving demand for certified cryovials. Germany's research corridor anchors this procurement surge.
Market Restraints
- Specialty polymer supply concentration:Medical-grade polypropylene resin production clusters in the US Gulf Coast and northwestern Europe. Any disruption to these feedstock sources propagates through centrifuge tube and pipette tip manufacturing.
- REACH substance restrictions:ECHA mandates on phthalate plasticizers and bisphenol alternatives are forcing reformulation of legacy labware. Manufacturers face 18-24 month requalification cycles.
- Glass-to-plastic substitution ceiling:Borosilicate glass petri dishes retain irreplaceable thermal and optical properties for specific cell culture applications. This limits full polymer conversion in high-precision workflows.
Strategic Opportunities
- Modular automation integration:Plug-and-play accessory ecosystems that bridge pipetting systems with sample prep workflows are capturing premium positioning. Contract research organizations in Switzerland are early adopters.
- Domestic biomanufacturing subsidies:US IRA provisions and EU pharmaceutical sovereignty initiatives are redirecting procurement toward regional supply bases. Manufacturers with captive polymer conversion capacity gain qualification advantages.
- Digital lot tracking convergence:Integration of RFID-enabled consumables with laboratory information management systems is creating new service revenue streams. ISO 13485-certified suppliers are bundling these capabilities.
Industry Challenges
- ISO 8655 calibration technician scarcity:Micropipette recertification requires specialized metrology skills that outpace vocational training output. Service networks in secondary markets face 6-8 week backlogs.
- FDA 21 CFR Part 11 validation timelines:Electronic record-keeping compliance for GMP accessories demands 12-18 month software-hardware integration projects. Smaller diagnostic labs defer upgrades.
- Multi-site standardization complexity:Pharmaceutical quality control networks struggle to harmonize consumable specifications across manufacturing sites in different regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab Accessories Market |
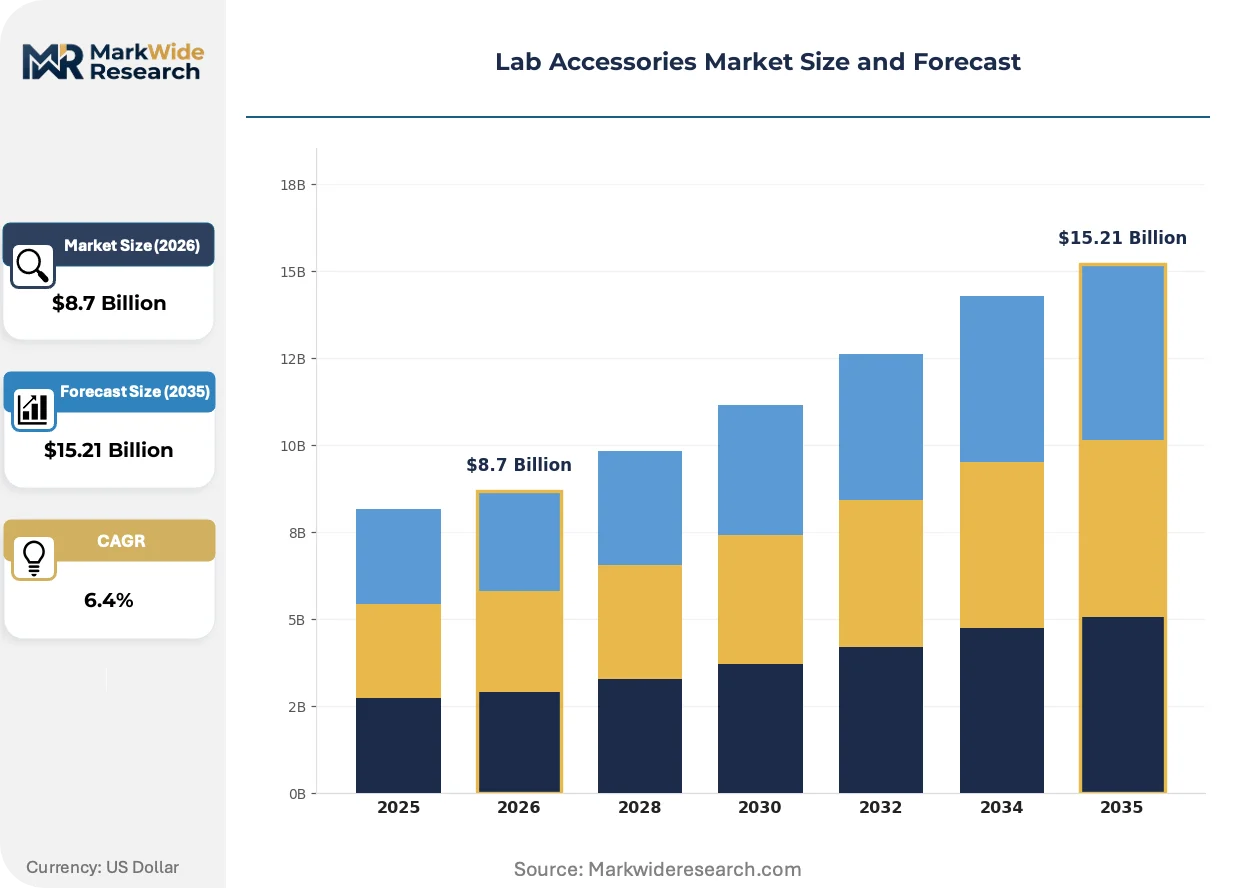
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micropipettes, Centrifuge Tubes, Petri Dishes, Cryovials, Lab Stirrers Application: Biotechnology, Pharmaceutical Research, Academic Research, Food Testing, Environmental Analysis End User: Research Institutions, Diagnostic Centers, Quality Control Labs, Forensic Labs, Agricultural Testing Facilities Distribution Channel: Direct Sales, Online Retailers, Distributors, Lab Equipment Suppliers, Specialty Stores |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, Agilent Technologies, Inc., Bio-Rad Laboratories, Inc., PerkinElmer Inc., Sartorius AG, Eppendorf AG, Merck KGaA, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab Accessories Market Strategic Shifts & Innovations
Precision liquid handling technologies are converging with automated sample prep platforms, while regulatory digitization mandates and procurement consolidation are reshaping vendor-buyer relationships across research and diagnostic segments.
Smart consumables embedded with near-field communication chips are rendering obsolete manual lot-tracking systems that rely on paper certificates of analysis. Pharmaceutical quality control labs in Germany and Switzerland are adopting these traceable accessories at accelerated rates. The technology is compressing audit preparation timelines while enabling real-time supply chain visibility from manufacturer to end-user.
EU MDR traceability mandates now require unique device identification on in-vitro diagnostic accessories, extending beyond finished instruments to include pipette tips and collection vessels. Manufacturers serving European diagnostic markets are retrofitting production lines with laser marking and serialization equipment. High-throughput clinical laboratories in France and the Netherlands are prioritizing MDR-compliant suppliers in vendor scorecards.
Consolidated procurement frameworks are displacing decentralized purchasing across multi-site research institutions. University medical center networks in the United States are centralizing labware contracts under single-source agreements with performance guarantees. This behavioral shift concentrates volume with ISO 13485-certified manufacturers capable of serving distributed sites under unified quality agreements.
Lab Accessories Market Segmentation
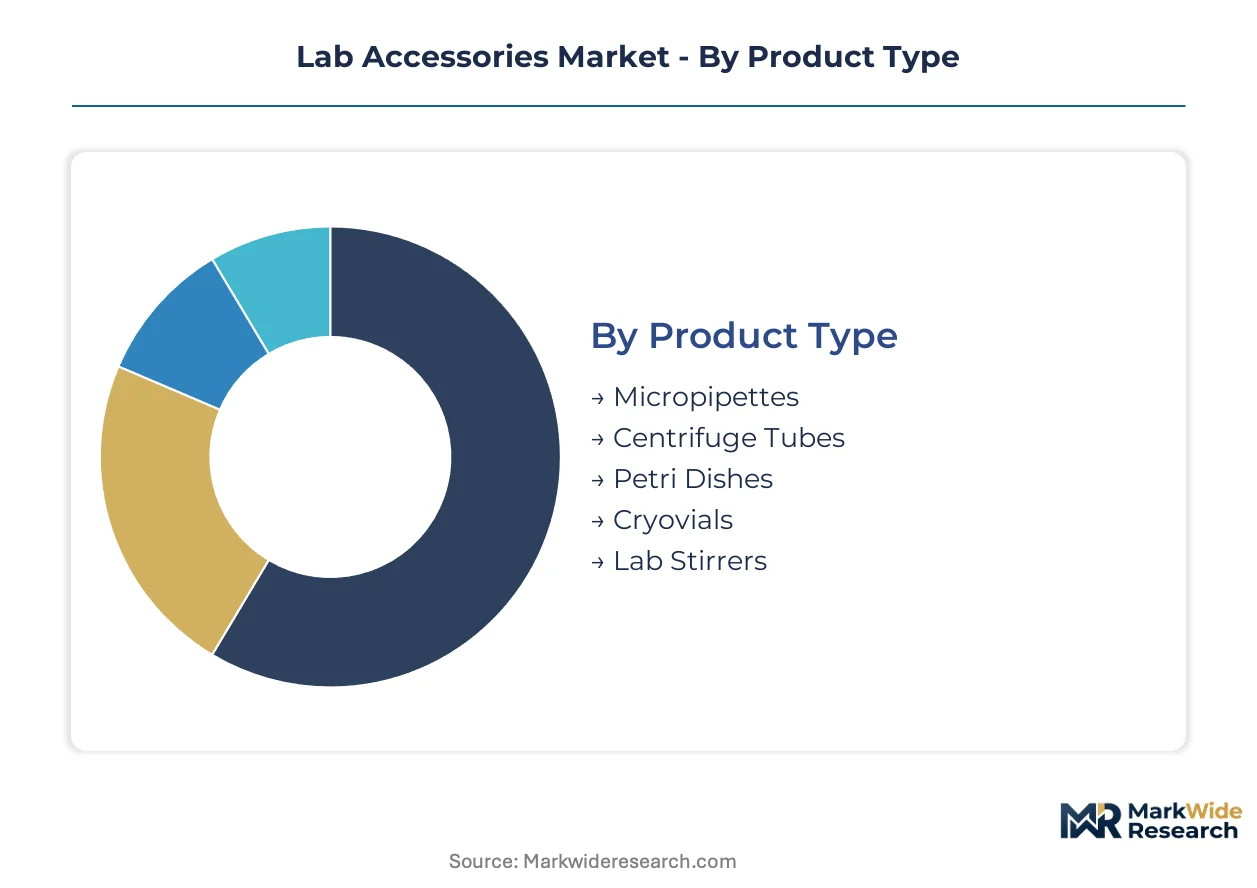
Segmentation in lab accessories reveals how procurement priorities diverge across precision requirements, regulatory exposure, and workflow integration needs. Understanding these fault lines exposes where margin concentrates and where volume expansion accelerates.
Product Type:
Cost tier differentiation separates commodity consumables from precision-calibrated instruments that command sustained pricing power through recertification dependencies.
- Micropipettes:ISO 8655-calibrated instruments with piston-driven air displacement mechanisms achieve accuracy within 0.6% at maximum volume. Pharmaceutical QC labs in Germany's Baden-Württemberg corridor drive replacement cycles tied to annual metrology audits.
- Centrifuge Tubes:Medical-grade polypropylene vessels rated for 15,000×g rotational stress dominate high-throughput bioprocessing. Biotechnology firms scaling cell therapy manufacturing anchor procurement volumes in the United States and Germany.
- Petri Dishes:Borosilicate glass variants retain thermal stability for adherent cell culture protocols requiring microscopic observation.
- Cryovials:Internally threaded polypropylene tubes with silicone gaskets enable vapor-phase liquid nitrogen storage. Biobanking infrastructure build-out for gene therapy supply chains propels demand fastest.
- Lab Stirrers:Magnetic and overhead mixing systems support dissolution and suspension workflows in pharmaceutical formulation development.
Micropipettes and centrifuge tubes command the established base. The steepest expansion runs through cryovials.
Application:
Application scope determines regulatory stringency tiers, with GMP environments imposing vendor qualification barriers that lock out uncertified suppliers.
- Biotechnology:Cell and gene therapy workflows demand sterile, pyrogen-free consumables with documented supply chain traceability. FDA 21 CFR Part 11 compliance requirements shape electronic record-keeping for accessories used in commercial manufacturing environments.
- Pharmaceutical Research:Quality control networks require ISO 13485-certified consumables with lot-level digital tracking. Multi-site standardization complexity across manufacturing sites in different regulatory jurisdictions strains procurement harmonization efforts.
- Academic Research:Budget-constrained institutions prioritize three-tier pricing stratification across premium, standard, and economy performance levels.
- Food Testing:ISO 17025-accredited laboratories drive demand for certified reference materials and validated consumable lots.
- Environmental Analysis:Trace metal analysis protocols specify acid-washed vessels to eliminate contamination risk in low-concentration detection.
Pharmaceutical research anchors the revenue base. Biotechnology applications are climbing the fastest.
End User:
Customer type dictates reorder frequency and contract structure, with diagnostic networks capturing volume through multi-year supply agreements.
- Research Institutions:University medical center networks in the United States are consolidating labware contracts under single-source frameworks with performance guarantees.
- Diagnostic Centers:High-throughput clinical laboratories prioritize MDR-compliant suppliers in vendor scorecards. EU MDR traceability mandates now require unique device identification on in-vitro diagnostic accessories.
- Quality Control Labs:Pharmaceutical manufacturing sites demand ISO 13485 certification and full digital lot traceability.
- Forensic Labs:Chain-of-custody protocols necessitate tamper-evident packaging and documented sterilization certificates.
- Agricultural Testing Facilities:Seasonal sample surges drive bulk procurement patterns with price-sensitive specifications.
Diagnostic centers concentrate margin through locked-in supply agreements. Research institutions are gaining share fastest through procurement consolidation.
Distribution Channel:
Channel selection reflects buyer scale and technical support requirements, with direct relationships dominating qualified vendor programs.
- Direct Sales:Manufacturers with captive polymer conversion capacity serve pharmaceutical clients under unified quality agreements spanning distributed sites.
- Online Retailers:E-commerce platforms capture standard-grade consumable orders from small academic labs with decentralized purchasing authority.
- Distributors:Regional warehouse networks provide same-day fulfillment for diagnostic laboratories with inventory minimization mandates.
- Lab Equipment Suppliers:Bundled instrumentation-consumable contracts reduce vendor management overhead for new facility build-outs.
- Specialty Stores:Niche suppliers serve forensic and environmental segments with application-specific product curation.
Direct sales channels command the established base. Online retailers are expanding most quickly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export certified labware to biotechnology clusters in the United States and Switzerland, while polymer feedstock flows from US Gulf Coast refineries shape regional production economics.
United States
Academic medical centers in Greater Boston and the Research Triangle Park anchor procurement of precision liquid handling tools for cell therapy scale-up. FDA 21 CFR Part 11 compliance requirements shape electronic record-keeping for consumables used in GMP environments. The San Francisco Bay Area concentrates demand from venture-backed biotechnology firms building commercial manufacturing infrastructure.
Germany
Fraunhofer institutes and Max Planck facilities in Baden-Württemberg drive high-volume orders for ISO 17025-certified consumables with full lot-level traceability. ECHA REACH substance restrictions on phthalate plasticizers compel manufacturers to reformulate legacy labware. The Munich-Stuttgart research corridor anchors pharmaceutical quality control procurement for European export markets.
Switzerland
Contract research organizations in Basel and Zurich adopt modular automation platforms that bridge pipetting systems with sample prep workflows. Swissmedic regulations govern in-vitro diagnostic accessories used in clinical laboratory settings. The country's precision manufacturing heritage supports premium positioning for metrology-calibrated instruments.
China
Domestic biomanufacturing subsidies redirect procurement toward regional supply bases for cell and gene therapy applications. NMPA quality mandates tighten traceability requirements for consumables used in diagnostic workflows. The Yangtze River Delta cluster concentrates polymer conversion capacity for centrifuge tube and pipette tip production.
Japan
Pharmaceutical quality control networks in Kanto and Kansai regions demand ISO 13485-certified consumables with documented sterilization certificates. PMDA regulations shape vendor qualification protocols for in-vitro diagnostic accessories. METI industrial policy supports domestic production of medical-grade polypropylene resin.
Lab Accessories Market Key Industry Players
On the supply side, the industry is consolidating around vertically integrated conglomerates with captive polymer conversion capacity and specialized precision instrument manufacturers with metrology expertise. Three strategic archetypes dominate: diversified life science conglomerates with consumables-instrumentation bundling power, mid-cap specialists with ISO 13485 certification dominance in pharmaceutical QC, and regional polymer processors serving price-sensitive academic markets. Competitive moves concentrate on M&A to secure calibration service networks and capacity expansion in medical-grade resin compounding.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the vertical integration archetype, while Eppendorf AG occupies a specialist position in precision liquid handling. These three entities represent contrasting approaches to market positioning: the conglomerate model leverages unified quality agreements across distributed pharmaceutical sites, while the specialist model commands premium positioning through ISO 8655 calibration dependencies and academic research channel penetration.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Agilent Technologies, Inc. |
| Bio-Rad Laboratories, Inc. |
| PerkinElmer Inc. |
| Sartorius AG |
| Eppendorf AG |
| Merck KGaA |
| Shimadzu Corporation |
| Others |
Cost & Logistics Intelligence
The Rotterdam-Antwerp petrochemical corridor shapes cost dynamics for medical-grade polypropylene resin, concentrating feedstock pricing power among northwestern European suppliers while downstream price differentiation separates ISO 13485-certified consumables from standard-grade alternatives in pharmaceutical procurement.
Pricing Analysis
Next-generation RFID-enabled consumables command 15-25% premiums over current-generation manually tracked labware, while prior-generation non-certified products face accelerating price erosion in academic channels. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified cryovials from research-grade alternatives and bulk-packaged economy tiers. Pricing pressure stems from consolidated procurement frameworks at US university medical centers negotiating volume-based discounts. Academic research institutions exhibit highest price sensitivity, while pharmaceutical QC labs demonstrate lowest sensitivity due to vendor qualification lock-in.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for pharmaceutical clients, with supply-chain finance facilities increasingly bridging working capital gaps for mid-tier manufacturers. Medical-grade polypropylene resin production concentrates in Germany, Belgium, and the US Gulf Coast, while precision molding equipment sources primarily from Switzerland and Japan. Raw material dependencies include petroleum-derived propylene monomer, medical-grade colorants, and silicone gasket formulations. Single-source vulnerability runs through specialized ISO 8655 calibration service networks. Distribution runs through direct manufacturer relationships for qualified vendor programs, with regional distributors serving diagnostic laboratories requiring rapid replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 8655-calibrated metrology capabilities represent the scarcest technical asset in this market, with technician training pipelines failing to match demand from expanding biomanufacturing capacity.
For Market Incumbents: Insulate calibration service networks through exclusive technician training partnerships with vocational institutes in Germany and Switzerland. Acquire regional polymer compounding facilities to secure captive medical-grade resin supply against REACH-driven reformulation cycles. The priority defensive lever rests on backward integration into specialty polymer production. For New Entrants and Emerging Players: Mid-market diagnostic laboratories in India's western states represent the most penetrable entry point, underserved by ISO 13485-certified suppliers with localized technical support. Secondary opportunities cluster in Southeast Asian biomanufacturing hubs receiving government subsidy support. A digital lot-tracking bundling strategy with RFID-enabled consumables offers differentiation against established commodity suppliers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming labware divisions lacking pharmaceutical certification depth. Long-term viability favors specialists with dual ISO 13485 and ISO 17025 accreditation spanning diagnostic and analytical workflows. Watch for NMPA regulatory alignment signals in China as inflection indicators for regional supply base redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Acquisition | Addresses ISO 8655 technician scarcity compressing vendor qualification timelines in secondary markets. |
| Medical-Grade Polymer Compounding Capacity | Secures captive supply against REACH substance restrictions and ECHA reformulation mandates. |
| RFID-Enabled Consumables Platform Launch | Captures EU MDR traceability compliance premiums from high-throughput diagnostic laboratories. |
| Modular Automation Integration Partnership | Positions accessories within plug-and-play sample prep workflows adopted by Swiss CROs. |
| Domestic Biomanufacturing Subsidy Alignment | Qualifies suppliers for US IRA and EU pharmaceutical sovereignty procurement preferences. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with laboratory procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs specialists; and secondary validation against FDA 510(k) filings, ECHA REACH substance restriction updates, hospital procurement databases, and ISO certification registries. Bottom-up demand modeling triangulated against top-down market sizing from trade flow analysis.
Forecast inputs incorporated product type segmentation by precision tier, application segmentation by regulatory exposure, end-user segmentation by reorder frequency, and regional segmentation by biomanufacturing subsidy eligibility. CAGRs derived from volume trajectory analysis across the projection horizon, with inputs including cell therapy manufacturing capacity expansion, biobanking infrastructure build-out rates, and ISO 17025 accreditation growth curves.
Practitioners should monitor REACH substance restriction expansion, dual-use export control tightening, and regional biomanufacturing subsidy redirection for early signals of supply base reconfiguration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Laboratory Supplies Market
Laboratory Equipment
Vacuum Tissue Processors Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Global Slide Stainer Market
Laboratory Equipment
Global Laboratory Plasticware Market
Laboratory Equipment
US Cath Labs Market
Laboratory Equipment
Global Microplate System Market
Laboratory Equipment
UK Pipette Tips Market
Laboratory Equipment
Micropipette Puller Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Portable Hemoglobin Analyzer Market
Laboratory Equipment
Laboratory Refrigerators and Ovens Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Human Milk Analyzers Market
Laboratory Equipment
Laboratory Fume Hoods Market