
 UK Pipette Tips Market | 2026-2036
UK Pipette Tips Market Size, Share, and Industry Trends Forecast 2026-2036
UK Pipette Tips Market Insights
Contract research organizations are reorganizing purchasing patterns across the UK pipette tips landscape, shifting from spot-buying to multi-year supply agreements that lock in volume and specification. Thermo Fisher Scientific Inc. leverages its integrated distribution network to anchor hospital and university contracts nationwide. Eppendorf SE differentiates through precision-manufactured low-retention geometries that command premium positioning in pharmaceutical quality control labs. Sartorius AG competes by extending its bioscience consumables portfolio into single-use workflow bundles that reduce customer switching.
UK pipette tips are precision-molded polypropylene consumables designed to deliver microliter-to-milliliter liquid volumes with calibrated accuracy, typically manufactured via high-speed injection molding with flash-free cavity design to prevent aerosol contamination and sample carryover. Filtered tips now lead product type demand as PCR and cell culture protocols mandate barrier protection against cross-contamination, while low-retention tips represent the fastest-expanding material segment as protein and nucleic acid workflows require minimized sample adhesion. Molecular biology applications occupy the largest application share, though clinical diagnostics is accelerating as NHS pathology consolidation drives standardization toward racked, sterile, filtered formats.
The Medicines and Healthcare products Regulatory Agency enforces ISO 8655 compliance for volumetric accuracy in diagnostic settings, while the Health and Safety Executive mandates COSHH-aligned aerosol containment that elevates filtered tip specifications in clinical laboratories. BSI Kitemark certification and EU MDR-aligned quality system requirements shape market access for manufacturers supplying NHS supply chains. Stakeholders must monitor how post-Brexit UKCA marking divergence from CE standards reshapes import compliance costs for continental European suppliers.
Market Dynamics
Contract research organizations are reorganizing purchasing patterns across the UK pipette tips landscape, shifting from spot-buying to multi-year supply agreements that lock in volume and specification. Thermo Fisher Scientific Inc. leverages its integrated distribution network to anchor hospital and university contracts nationwide. Eppendorf SE differentiates through precision-manufactured low-retention geometries that command premium positioning in pharmaceutical quality control labs. Sartorius AG competes by extending its bioscience consumables portfolio into single-use workflow bundles that reduce customer switching.
Growth Catalysts
- MHRA Quality Standards:The UK Medicines and Healthcare products Regulatory Agency's tightened quality standards for laboratory consumables are pushing tip manufacturers toward higher-grade polypropylene resins, elevating overall market value per unit.
- Biotech Clustering:Demand concentrates in the Greater London-Oxford-Cambridge life sciences corridor, where biotech clustering drives repeat bulk purchasing from established R&D facilities.
- Outsourced Drug Discovery:Contract research organizations are expanding procurement volumes as outsourced drug discovery accelerates, creating sustained pull for sterile, filtered tip formats.
Market Restraints
- Polypropylene Resin Volatility:Feedstock cost fluctuations for medical-grade polypropylene create margin compression for manufacturers locked into fixed-price NHS contracts.
- Post-Brexit Compliance Friction:UKCA marking divergence from CE standards reshapes import compliance costs for continental European suppliers, raising landed costs for cross-channel distributors.
- Reusable Pipetting Systems:Electronic pipettes with fixed-tip designs present substitution risk in high-throughput screening applications where plastic waste reduction is prioritized.
Strategic Opportunities
- North England Biotech Expansion:Manchester and Leeds biotech incubators remain underpenetrated relative to the Golden Triangle, offering first-mover advantage for localized distribution partnerships.
- Cell and Gene Therapy Workflows:Advanced therapy medicinal product manufacturing requires ultra-low retention and certified nuclease-free tips, opening premium product tiers.
- NHS Pathology Consolidation:Standardization toward racked, sterile, filtered formats across consolidated NHS pathology networks creates volume aggregation opportunities for compliant suppliers.
Industry Challenges
- ISO 8655 Calibration Expertise:Volumetric accuracy certification requires specialized metrology talent that remains scarce in UK consumables manufacturing.
- Injection Molding Retrofit Costs:Transitioning existing high-speed lines to flash-free cavity designs for aerosol containment demands significant capital reinvestment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Pipette Tips Market |
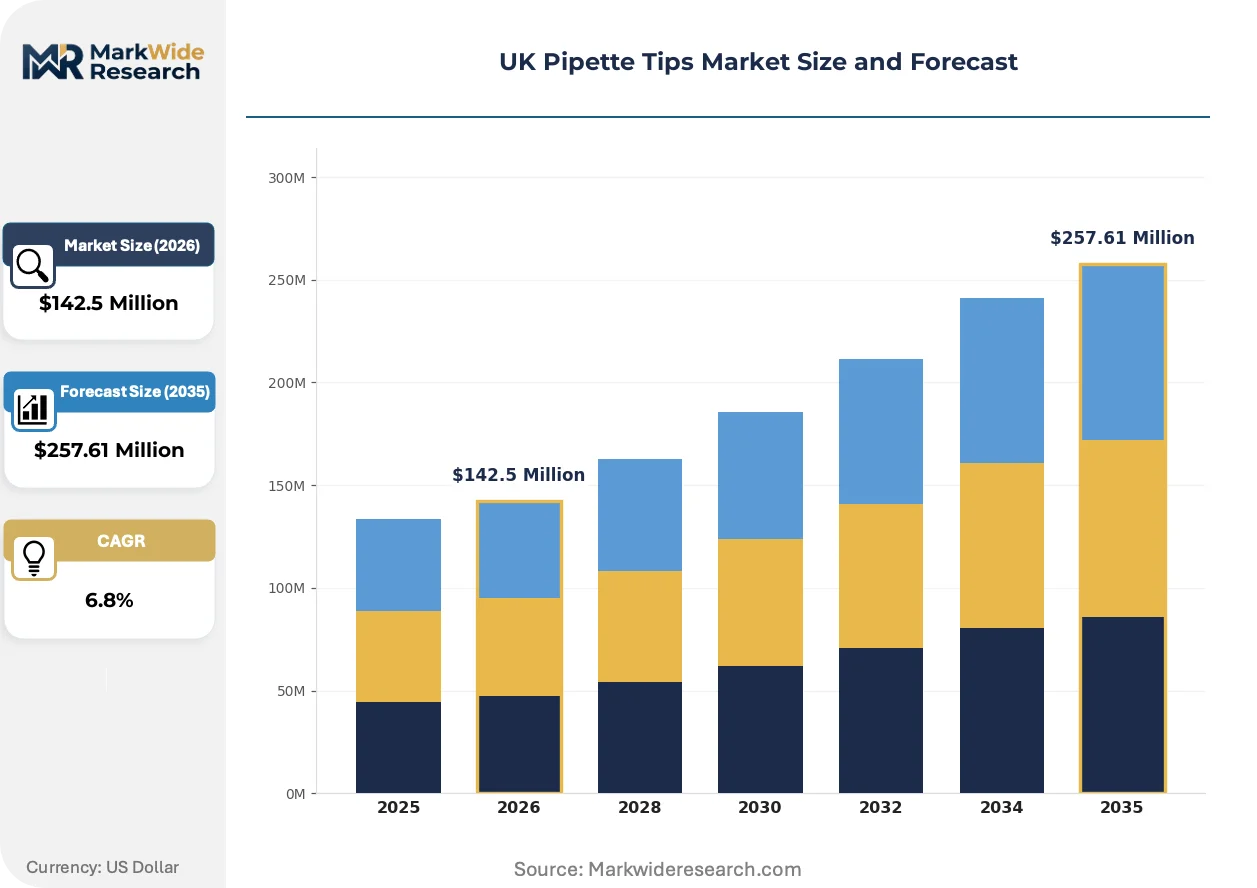
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filtered Tips, Non-filtered Tips, Low-retention Tips, Sterile Tips, Universal Tips Material: Polypropylene, Polycarbonate, Polystyrene, High-density Polyethylene, Biodegradable Polymers Application: Molecular Biology, Clinical Diagnostics, Pharmaceutical Research, Forensic Testing, Environmental Monitoring End User: Biotechnology Firms, Diagnostic Laboratories, Academic Research Centers, Pharmaceutical Companies, Contract Research Organizations |
| Companies Covered | Corning Incorporated, Gilson Incorporated, Thermo Fisher Scientific Inc., Greiner Bio-One International GmbH, INTEGRA Biosciences AG, Eppendorf SE, Mettler Toledo, Starlab International GmbH, Sartorius AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Pipette Tips Market Trends and Innovations
Active reshaping of the UK pipette tips market centers on material science advances, regulatory alignment pressures, and procurement rationalization across consolidated healthcare networks. These forces are compressing legacy supply relationships while elevating specification-driven competition.
Low-retention polypropylene formulations with proprietary hydrophobic surface treatments are supplanting standard-grade tips in protein and nucleic acid workflows. Pharmaceutical quality control labs and CROs are adopting these geometries at accelerated rates to minimize sample adhesion. This material transition is compressing margins on commodity tip categories while rewarding manufacturers with captive resin formulation capabilities.
BSI Kitemark certification and EU MDR-aligned quality system requirements are reshaping market access protocols for manufacturers supplying NHS supply chains. The Health and Safety Executive's COSHH-aligned aerosol containment mandates elevate filtered tip specifications in clinical laboratories. Diagnostic settings now require ISO 8655 compliance for volumetric accuracy, forcing suppliers to maintain dual certification tracks for UK and continental European markets.
Multi-year framework agreements are displacing spot purchasing across NHS pathology networks and university procurement consortia. Aggregated buying through regional collaborative procurement hubs concentrates volume with fewer suppliers. This consolidation is most visible in Greater London and the South East, where teaching hospital networks have standardized on racked, sterile, filtered formats through single-source contracts.
UK Pipette Tips Market Segmentation
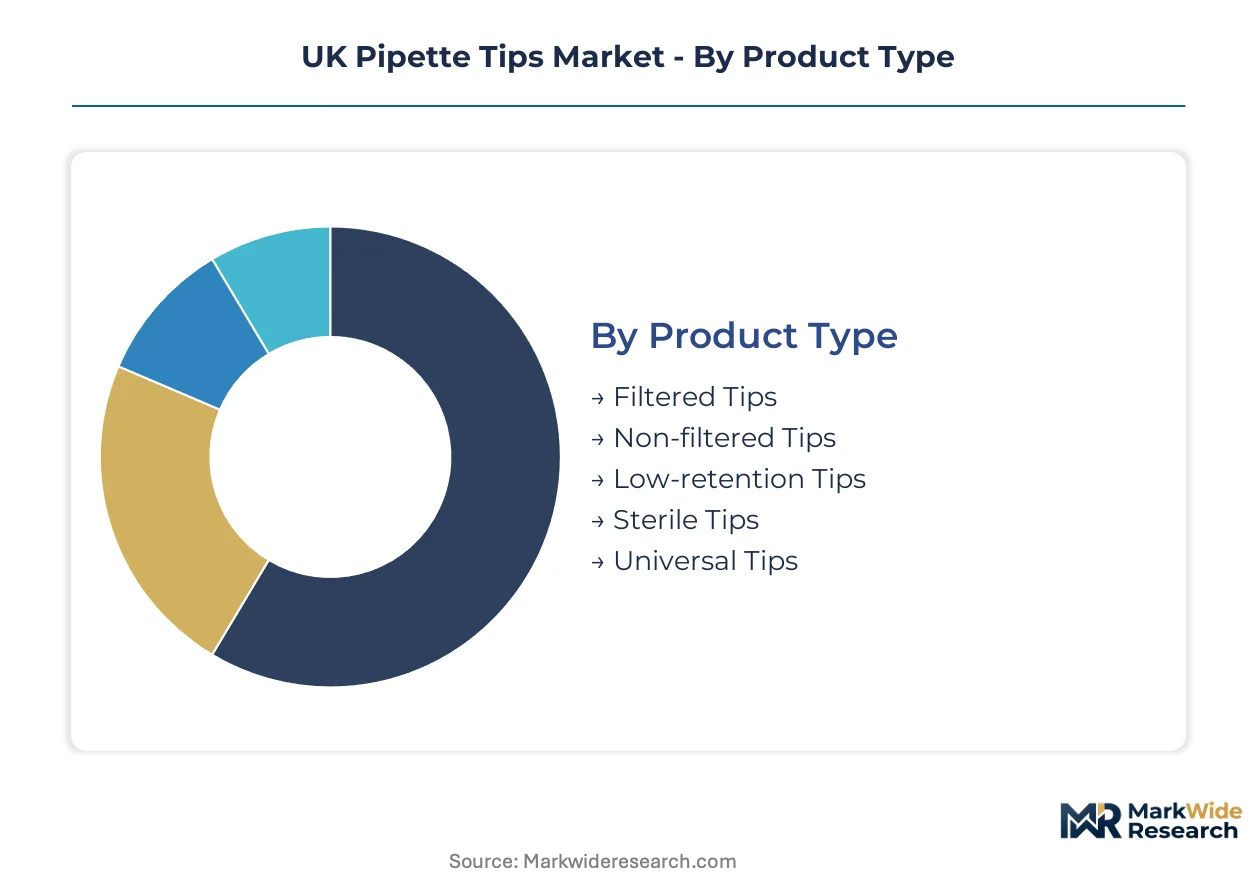
Pipette tip segmentation in the UK reflects divergent pressure from regulatory mandates, workflow automation, and sustainability imperatives. Each dimension carries distinct substitution risks and margin structures that reshape supplier positioning.
Product Type:
Filtered tips face the most acute substitution pressure from reusable pipetting systems in high-throughput screening environments where plastic waste reduction drives procurement decisions.
- Filtered Tips:Hydrophobic barrier membranes prevent aerosol cross-contamination between samples. NHS pathology networks in Greater London and the South East mandate these formats for PCR workflows under COSHH-aligned containment rules.
- Low-retention Tips:Proprietary hydrophobic surface treatments minimize sample adhesion for protein and nucleic acid protocols. Pharmaceutical quality control labs across the Golden Triangle adopt these geometries at premium price points to reduce reagent loss.
- Non-filtered Tips:Standard-grade polypropylene consumables serve basic liquid handling where contamination risk remains minimal.
- Sterile Tips:Gamma-irradiated or ethylene oxide-sterilized formats for cell culture applications.
- Universal Tips:Cross-manufacturer compatibility designs for mixed-instrument laboratories.
Filtered tips retain volume leadership across NHS and CRO procurement; low-retention tips hold the steepest expansion curve as biologics workflows proliferate.
Material:
Cost tier stratification separates medical-grade polypropylene from emerging alternatives, with resin grade directly determining MHRA compliance eligibility.
- Polypropylene:Dominant medical-grade resin offering chemical resistance and low extractables. MHRA tightened quality standards now require higher-grade specifications that elevate per-unit value.
- Biodegradable Polymers:PLA and PHA formulations address plastic waste reduction mandates from the UK Health and Safety Executive. Manchester and Leeds biotech incubators pilot these materials as sustainability procurement criteria harden.
- Polycarbonate:Rigid clarity for visual confirmation applications in forensic and diagnostic settings.
- Polystyrene:Lower-cost option for non-critical liquid handling with limited chemical compatibility.
- High-density Polyethylene:Alternative for specific solvent resistance requirements in environmental monitoring.
Polypropylene maintains installed-base dominance; biodegradable polymers are expanding most quickly as NHS supply chains embed circular procurement targets.
Application:
Volume concentration in molecular biology creates margin compression, while clinical diagnostics offers aggregation opportunities through NHS consolidation.
- Molecular Biology:PCR, qPCR, and nucleic acid purification workflows dominate current consumption. The Greater London-Oxford-Cambridge corridor drives repeat bulk purchasing from established R&D facilities.
- Clinical Diagnostics:NHS pathology consolidation standardizes procurement toward racked, sterile, filtered formats. ISO 8655 compliance for volumetric accuracy is mandatory in diagnostic settings.
- Pharmaceutical Research:Quality control and formulation development requiring certified accuracy.
- Forensic Testing:Contamination-sensitive protocols for DNA evidence processing.
- Environmental Monitoring:Water and soil analysis with trace-level detection requirements.
Molecular biology commands the largest application share; clinical diagnostics is accelerating fastest as regional NHS hubs aggregate purchasing volume.
End User:
Customer type determines contract structure, with CROs shifting from spot-buying to multi-year agreements that lock specification and volume.
- Contract Research Organizations:Outsourced drug discovery acceleration expands procurement volumes. CROs now favor multi-year framework agreements over transactional purchasing to secure supply continuity.
- Biotechnology Firms:Cell and gene therapy developers require ultra-low retention and certified nuclease-free tips for advanced therapy medicinal product manufacturing.
- Diagnostic Laboratories:NHS and private pathology services with standardized format requirements.
- Academic Research Centers:University procurement consortia with aggregated buying power.
- Pharmaceutical Companies:Internal R&D and quality control operations with premium specification demands.
Contract research organizations anchor volume demand; biotechnology firms are gaining share fastest as cell and gene therapy manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and contract research organizations concentrate purchasing power across distinct UK sub-regions, with procurement patterns diverging between consolidated NHS networks and fragmented biotech clusters.
London and the South East
Imperial College London and the Francis Crick Institute anchor demand for low-retention and filtered tip formats in CRISPR and cell therapy workflows. The Medicines and Healthcare products Regulatory Agency's ISO 8655 enforcement raises compliance costs for suppliers serving Guy's and St Thomas' NHS Foundation Trust. The Golden Triangle corridor stretching to Oxford and Cambridge drives repeat bulk purchasing from established R&D facilities.
East of England
Cambridge's biotech density, including the Babraham Research Campus, sustains premium tip consumption for nucleic acid protocols. NHS East of England pathology consolidation standardizes procurement toward racked, sterile formats across Addenbrooke's Hospital and regional hubs. The Cambridge Science Park cluster generates sustained pull for certified nuclease-free consumables.
North West England
Manchester's biotech incubators at Alderley Park and the Manchester Science Park remain underpenetrated relative to southern clusters, offering distribution partnership opportunities. Health and Safety Executive COSHH mandates elevate filtered tip specifications across Manchester University NHS Foundation Trust laboratories. The region's advanced therapy medicinal product manufacturing scale-up creates demand for ultra-low retention geometries.
Scotland
Edinburgh BioQuarter and the Scottish National Blood Transfusion Service drive specialized tip requirements for cell processing applications. NHS Scotland's national procurement framework aggregates purchasing across regional pathology networks. The Roslin Institute and adjacent biotech clustering sustains demand for high-grade polypropylene consumables in veterinary and agricultural research.
Midlands
Birmingham's Queen Elizabeth Hospital and the University of Birmingham anchor clinical diagnostics demand as NHS pathology networks consolidate. The Medicines and Healthcare products Regulatory Agency's tightened quality standards for laboratory consumables push local distributors toward higher-grade resin specifications. BioCity Nottingham and Leicester's biotech clustering generate mid-tier volume for standard molecular biology workflows.
UK Pipette Tips Market Competitive Landscape
Player mix skews toward diversified life sciences conglomerates with captive distribution networks, compressing margin space for standalone consumables specialists. Three archetypes dominate: integrated platform vendors bundling tips with instrumentation, precision-molding specialists commanding premium positioning through surface engineering, and regional distributors leveraging NHS procurement frameworks. Consolidation pressure intensifies as multi-year supply agreements displace spot purchasing, while flash-free cavity design capabilities separate compliant suppliers from commodity players.
Within the integrated platform tier, Thermo Fisher Scientific Inc. and Eppendorf SE exemplify contrasting approaches to market coverage. Thermo Fisher leverages its nationwide distribution infrastructure to anchor hospital and university contracts through workflow bundling. Eppendorf occupies a precision-specialist position where low-retention geometries command premium placement in pharmaceutical quality control settings. Sartorius AG represents the bioscience consumables archetype, extending single-use portfolios to reduce customer switching across cell and gene therapy manufacturing workflows.
| Leading Market Players |
|---|
| Corning Incorporated |
| Gilson Incorporated |
| Thermo Fisher Scientific Inc. |
| Greiner Bio-One International GmbH |
| INTEGRA Biosciences AG |
| Eppendorf SE |
| Mettler Toledo |
| Starlab International GmbH |
| Sartorius AG |
| Others |
Pricing and Supply Chain Analysis
High-volume injection molding capacity utilization above 85% in medical-grade polypropylene tip manufacturing creates natural scale advantages that compress unit economics for second-tier suppliers. This concentration of molding expertise in Germany and the Netherlands establishes floor prices that UK distributors struggle to undercut, while NHS fixed-price contracts lock manufacturers into margin compression when resin indices spike.
Pricing Analysis
Cost-plus contracts with polypropylene resin indexation dominate NHS procurement frameworks, passing feedstock volatility through to buyers while capping supplier margins. Price differentiation separates ISO 8655-certified diagnostic-grade tips from standard research consumables, with MHRA compliance tiers commanding premium placement. Pricing pressure stems from consolidated pathology networks aggregating volume through single-source tenders that force competitive bidding. Academic research centers exhibit highest price sensitivity due to constrained capital budgets, while cell and gene therapy manufacturers prioritize specification certainty over unit cost.
Supply Chain Analysis
Six-to-eight week inventory buffers for medical-grade polypropylene resin expose UK distributors to polymer price swings that strain working capital. Manufacturing concentration in Germany, the Netherlands, and Denmark feeds UK demand through cross-channel distribution hubs vulnerable to post-Brexit customs friction. Raw material dependencies center on propylene monomer supply from North Sea petrochemical complexes and specialized hydrophobic additive formulations from Swiss specialty chemical suppliers. Single-source vulnerability in flash-free cavity mold tooling creates bottleneck risk for manufacturers scaling filtered tip production. Distribution runs through integrated life sciences distributors holding NHS framework contracts rather than direct manufacturer-to-lab relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from electronic pipetting systems with fixed-tip architectures that eliminate consumable purchasing entirely. Defense of market position requires strategic moves that embed suppliers irreplaceably into validated workflows.
For Market Incumbents: Shield installed-base relationships by embedding tip specifications into NHS pathology network validation protocols that resist switching. Pursue backward integration into medical-grade polypropylene resin compounding to capture margin currently leaked to German petrochemical suppliers. Electronic pipette substitution threat intensifies in high-throughput screening applications where plastic waste reduction mandates drive procurement criteria.
For New Entrants and Emerging Players: Anchor in Manchester and Leeds biotech incubators where distribution partnerships remain underdeveloped relative to the Golden Triangle corridor. Target cell and gene therapy manufacturing workflows requiring certified nuclease-free and ultra-low retention geometries that command premium positioning. Partner with regional NHS collaborative procurement hubs as aggregation creates volume entry points for compliant new suppliers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers holding multi-year framework agreements with consolidated NHS pathology networks that standardize on racked, sterile, filtered formats. Long-term viability favors suppliers with captive resin formulation capabilities and flash-free cavity molding expertise that regulatory compliance increasingly mandates. Acquisition targets should demonstrate ISO 8655 calibration infrastructure and BSI Kitemark certification tracks. Monitor NHS England pathology consolidation timelines as inflection indicators for volume aggregation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Flash-Free Cavity Molding Investment | MHRA aerosol containment mandates elevate technical barriers for compliant tip production. |
| Resin Formulation Backward Integration | Captive hydrophobic additive compounding secures margin and supply continuity against petrochemical volatility. |
| NHS Framework Contract Aggregation | Consolidated pathology network procurement concentrates volume with fewer validated suppliers. |
| Cell Therapy Workflow Certification | Nuclease-free and ultra-low retention specifications open premium tiers in advanced therapy manufacturing. |
| Regional Distribution Partnership | Localized stocking in Manchester and Leeds reduces lead times for underpenetrated northern biotech clusters. |
Research Methodology
A standing panel of NHS procurement managers, CRO supply chain directors, diagnostic laboratory supervisors, and medical device regulatory consultants provided ongoing calibration against operational realities. Primary interviews with these stakeholders combined with secondary validation from MHRA guidance documents, NHS Supply Chain procurement databases, BSI certification registers, and Health and Safety Executive COSHH enforcement records. Bottom-up demand modeling from individual laboratory consumption patterns triangulated against top-down market sizing from distributor shipment data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, material grade, application workflow, and end-user procurement structure. CAGRs derived from trend extrapolation of NHS pathology consolidation timelines, CRO outsourcing growth patterns, and biotech clustering dynamics in the Golden Triangle corridor. Industry-specific forecast inputs incorporated polymer price index trajectories and regulatory compliance cost escalations.
Decision-makers should treat outputs as directional under assumptions of continued NHS consolidation, stable MHRA enforcement intensity, and no disruptive substitution by reusable pipetting systems; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Histopathology Laboratory Equipment Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
South Korea Pipette Tips Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
North America Laboratory Hoods and Enclosure Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Automated Blood Analyzer Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Global Laboratory Washers Market
Laboratory Equipment
Laboratory Data Loggers Market
Laboratory Equipment
Albumin Analyzers Market
Laboratory Equipment
Laboratory Fume Hoods Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Asia Pacific Cell Counting Market