
 Microplate Reader Market | 2026-2036
Microplate Reader Market Size, Share, and Industry Trends Forecast 2026-2036
Microplate Reader Market Intelligence
Direct-to-laboratory distribution is rewriting how microplate reader vendors reach end users in fragmented academic markets. BMG LABTECH GmbH leverages its European manufacturing base to sustain rapid fulfillment cycles for multimode systems. Thermo Fisher Scientific Inc. dominates North American service contracts through its captive field engineering network. Danaher Corporation anchors clinical diagnostics placements via its Beckman Coulter subsidiary's installed base of automated workflows.
A microplate reader is an analytical instrument that detects optical signals—absorbance, fluorescence, or luminescence—across standardized 96-, 384-, or 1536-well formats using photomultiplier tubes or charge-coupled device detectors, enabling quantitative analysis of biological and chemical reactions in high-throughput settings. Multimode readers command premium positioning by consolidating detection modalities into single platforms, reducing laboratory footprint and capital expenditure for pharmaceutical companies. Drug discovery applications absorb the largest share of installed units, though environmental monitoring is gaining velocity as water quality agencies adopt enzymatic assay protocols for contaminant detection.
FDA 21 CFR Part 11 mandates electronic records and signatures for microplate readers used in regulated drug development, compelling vendors to embed audit-trail software and user-access controls. EPA methods 1664 and 8260 reference optical detection techniques that environmental laboratories validate on certified absorbance and fluorescence systems. ISO 13485 quality management requirements govern in vitro diagnostic instrument manufacturing, particularly for clinical laboratories deploying readers under EU IVDR and Health Canada frameworks. Stakeholders must monitor how AI-enabled plate analysis algorithms trigger new software validation standards across FDA, EMA, and PMDA jurisdictions.
Market Dynamics
Pharmaceutical high-throughput screening workflows are compressing detection timelines, forcing vendors to consolidate absorbance, fluorescence, and luminescence modalities into single multimode platforms while embedding FDA 21 CFR Part 11 audit-trail capabilities as baseline requirements.
Growth Catalysts
- Drug Discovery Automation:Pharmaceutical companies are scaling 1536-well format screening to compress lead identification cycles, driving multimode reader procurement for centralized compound libraries.
- EPA Method 1664:Environmental laboratories across the United States are certifying absorbance systems for oil and grease quantification in wastewater, expanding the installed base beyond traditional life science applications.
- German CRO Density:The concentration of contract research organizations in Baden-Württemberg and Bavaria is sustaining above-average replacement demand for high-throughput optical detection systems.
Market Restraints
- Photomultiplier Tube Supply Concentration:Japanese and Russian suppliers dominate photodetector manufacturing, exposing instrument vendors to single-source risk for charge-coupled device alternatives.
- EU IVDR Transition Costs:In vitro diagnostic reclassification under the European Union's 2017/746 regulation is extending validation timelines for clinical microplate readers by 12-18 months.
- Benchtop Spectrophotometer Substitution:Single-cuvette absorbance systems retain cost advantage for laboratories processing under 50 samples daily, limiting reader penetration in small environmental testing facilities.
Strategic Opportunities
- Water Quality Agency Expansion:Municipal utilities in the United States are adopting enzymatic microplate assays for heavy metal detection, creating first-mover advantage for vendors with EPA-certified protocols.
- AI-Enabled Plate Analysis:Machine learning algorithms for edge detection and well-to-well normalization are converging with cloud-based data architectures, enabling predictive maintenance and remote diagnostics as service differentiators.
- Direct-to-Laboratory Distribution:E-commerce platforms with same-day fulfillment capabilities are displacing traditional distributor networks for academic and startup biotechnology accounts with fragmented purchasing authority.
Industry Challenges
- Software Validation Expertise Gap:FDA 21 CFR Part 11 compliance requires specialized quality assurance personnel for electronic records management, a skill set scarce among mid-sized instrument manufacturers.
- Legacy LIMS Integration:Pharmaceutical quality control laboratories operate 15-20 year-old laboratory information management systems with rigid data structures, complicating API development for real-time reader connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microplate Reader Market |
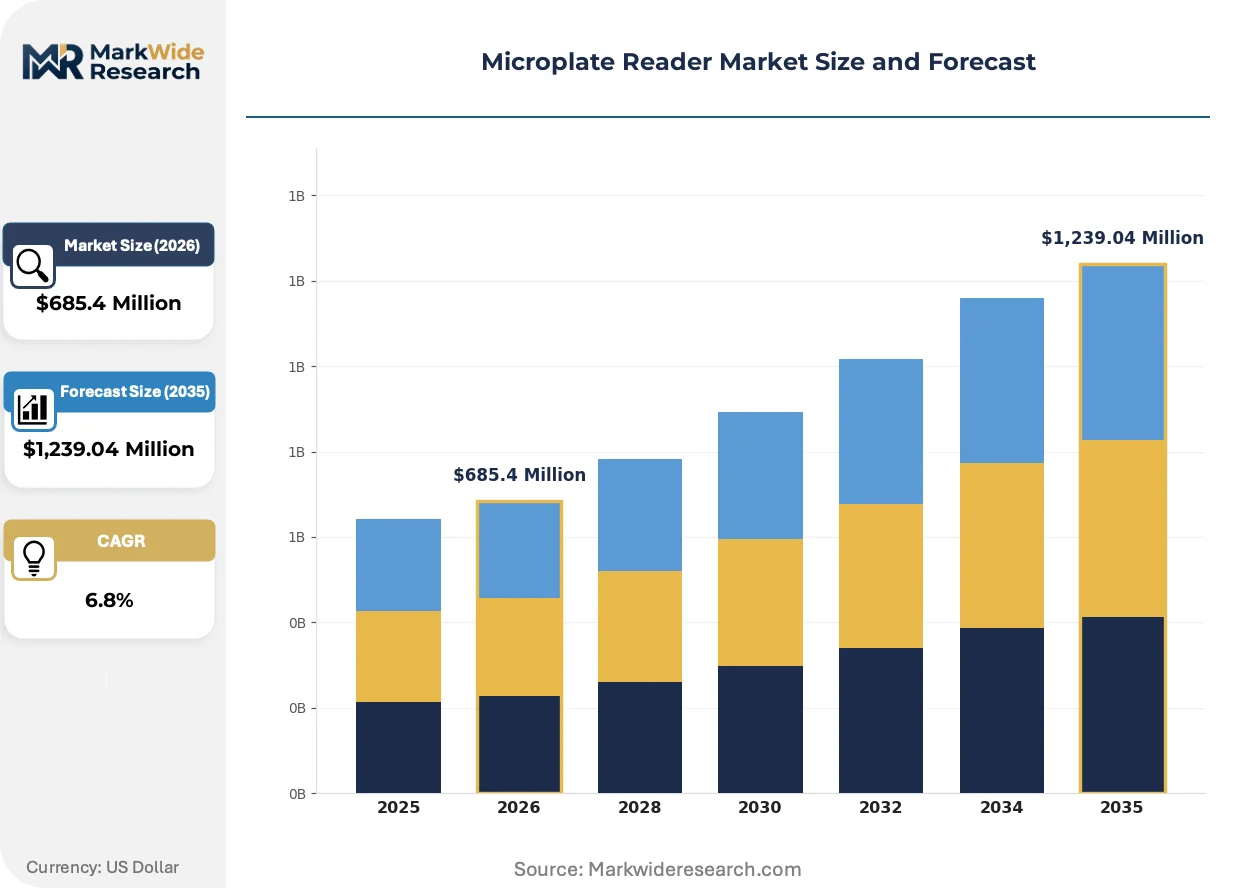
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescence Readers, Luminance Readers, Absorbance Readers, Multimode Readers Application: Drug Discovery, Clinical Diagnostics, Environmental Monitoring, Quality Control End User: Pharmaceutical Companies, Academic Research Institutes, Clinical Laboratories, Biotechnology Firms Technology: Optical Grade, Laser-based, CCD Imaging, Hybrid Technology |
| Companies Covered | BMG LABTECH GmbH, Bio-Rad Laboratories Inc., Thermo Fisher Scientific Inc., Danaher Corporation, Molecular Devices LLC, PerkinElmer Inc., Tecan Group Ltd., Promega Corporation, Agilent Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microplate Reader Market Strategic Shifts & Innovations
Detection hardware is converging with computational analytics, compressing the boundary between raw signal acquisition and interpretable biological insight while regulatory frameworks harden software validation requirements across multiple jurisdictions.
Monolithic multimode optical engines are digitizing the transition from dedicated single-function readers to consolidated platforms. Pharmaceutical screening facilities are standardizing on these systems to reduce capital expenditure and floor space allocation. The technology is digitizing assay workflow standardization by embedding automated protocol libraries that eliminate manual parameter entry across 96-, 384-, and 1536-well formats.
REACH substance restriction proposals for cadmium and lead in electronic components are forcing photodetector redesigns across European supply chains. Component suppliers must qualify alternative phosphor materials for photomultiplier tubes without degrading quantum efficiency specifications. German analytical instrumentation manufacturers are responding by accelerating in-house detector development programs to decouple from Asian component sourcing.
Service contract unbundling is fragmenting how academic laboratories acquire maintenance coverage for multimode systems. Research institutions are shifting from comprehensive manufacturer agreements to third-party field service networks or in-house biomedical engineering teams for routine calibration and lamp replacement. This pattern is most visible in United States National Institutes of Health-funded core facilities with centralized equipment pools and dedicated technical staff.
Microplate Reader Market Segmentation
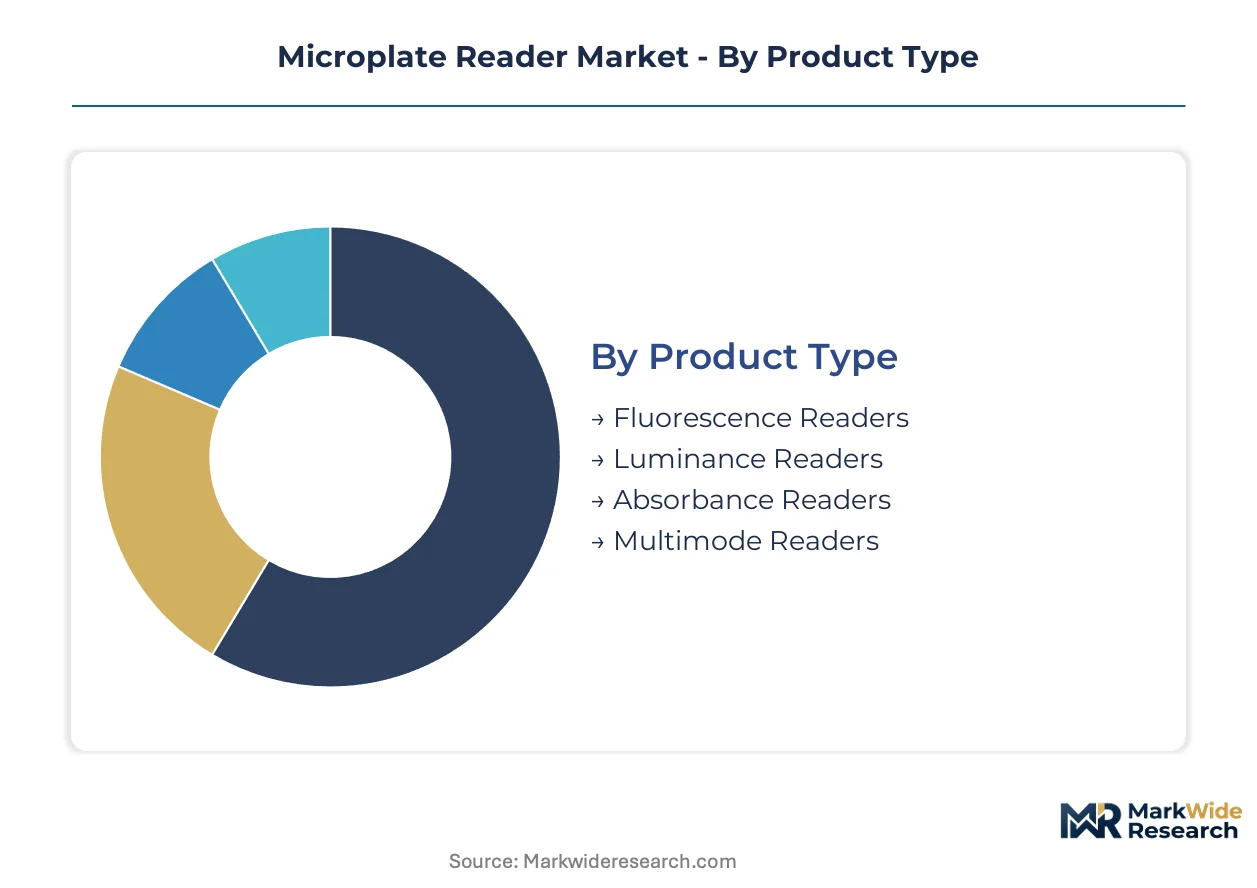
Microplate reader segmentation reveals how detection modality, application intensity, and user sophistication reshape procurement patterns. Pharmaceutical companies prioritize multimode consolidation while environmental agencies drive single-function absorbance demand. Technology choices bifurcate between established photomultiplier architectures and emerging imaging arrays.
Product Type:
Cost tier positioning separates dedicated single-mode instruments from premium consolidated platforms. Entry-level absorbance systems compete on capital efficiency. Multimode configurations command service contract premiums.
- Multimode Readers:These platforms integrate absorbance, fluorescence, and luminescence detection into unified optical engines with automated filter wheel switching. Pharmaceutical compound screening facilities in Germany and the United States are standardizing on these systems to compress floor space and eliminate redundant capital equipment. FDA 21 CFR Part 11 audit-trail embedding has become a non-negotiable specification for drug development deployments.
- Fluorescence Readers:Dedicated systems employ photomultiplier tubes with monochromator or filter-based wavelength selection for quantitative fluorophore detection. Academic core facilities in the United States absorb significant volume for molecular biology protocols, though procurement is fragmenting toward third-party service networks rather than manufacturer comprehensive contracts.
- Luminance Readers:Specialized photon-counting architectures detect bioluminescent reporter signals with enhanced sensitivity for ATP quantification and promoter-reporter assays.
- Absorbance Readers:Single-mode ultraviolet-visible systems dominate environmental monitoring applications where EPA Method 1664 oil and grease quantification drives certification requirements.
Multimode Readers hold installed capacity. Fluorescence Readers is rotating up the share rankings.
Application:
Application intensity varies sharply by regulatory burden and throughput requirements. Drug discovery demands 24-hour operational reliability. Environmental monitoring operates on intermittent batch schedules.
- Drug Discovery:High-throughput screening workflows process 10,000-50,000 compounds daily using 1536-well formats with sub-microliter volumes. Contract research organizations in Baden-Württemberg and Bavaria sustain replacement cycles as lead identification timelines compress. FDA 21 CFR Part 11 compliance mandates reshape vendor selection criteria toward embedded electronic records management.
- Environmental Monitoring:Water quality agencies deploy enzymatic microplate assays for heavy metal and organic contaminant detection. Municipal utilities across the United States are adopting these protocols, creating first-mover advantage for vendors with EPA-certified method implementations.
- Clinical Diagnostics:In vitro diagnostic applications operate under EU IVDR and Health Canada frameworks with ISO 13485 quality management requirements.
- Quality Control:Pharmaceutical manufacturing release testing employs readers for potency and purity verification with validated analytical methods.
Drug Discovery dominates procurement volume. Environmental Monitoring is climbing the fastest.
End User:
Customer type determines purchasing authority structure and service contract preferences. Large pharmaceutical consolidates through central procurement. Academic fragments across individual laboratory budgets.
- Pharmaceutical Companies:Centralized compound libraries and screening facilities drive multimode reader procurement with multi-year service agreements. These organizations embed readers within automated workflow platforms requiring seamless LIMS integration.
- Academic Research Institutes:Fragmented purchasing authority across individual laboratories favors direct-to-laboratory distribution channels with same-day fulfillment. National Institutes of Health-funded core facilities in the United States are unbundling manufacturer service contracts in favor of in-house biomedical engineering teams.
- Clinical Laboratories:Diagnostic deployments require regulatory compliance with FDA, EMA, or PMDA software validation standards depending on jurisdiction.
- Biotechnology Firms:Startup and mid-cap organizations prioritize capital efficiency and flexible assay protocol compatibility.
Pharmaceutical Companies anchor revenue concentration. Academic Research Institutes is rotating up the share rankings.
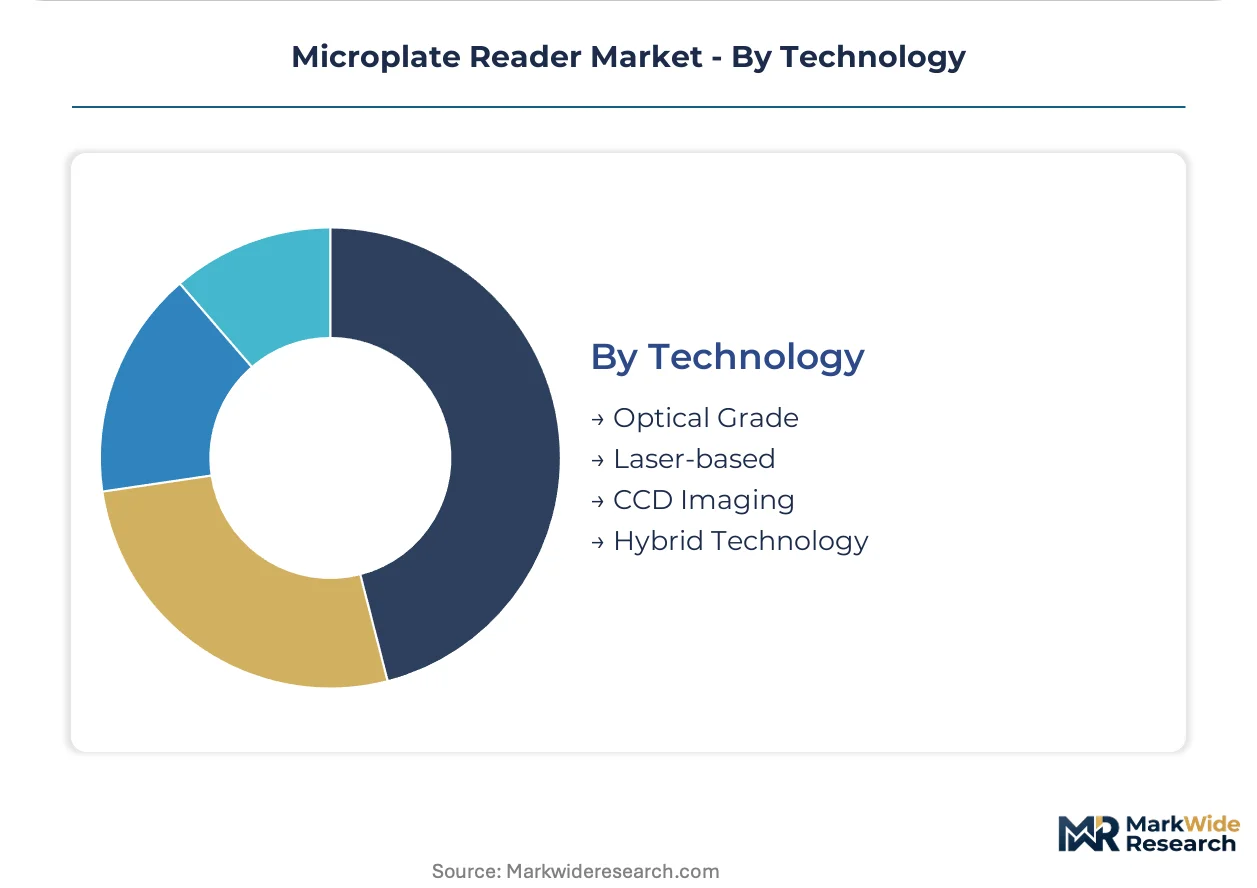
Technology:
Technology maturity separates established photodetector architectures from emerging imaging modalities. Optical grade systems dominate installed base. Laser-based configurations gain share in specialized applications.
- Optical Grade:Photomultiplier tube-based detection with filter or monochromator wavelength selection represents the established architecture with proven linearity and sensitivity specifications. Japanese and Russian suppliers dominate photodetector manufacturing, exposing instrument vendors to single-source supply risk.
- CCD Imaging:Charge-coupled device arrays enable simultaneous whole-plate imaging with spatial resolution for cell-based assays. These systems are expanding in live-cell kinetic applications where temporal resolution outweighs pure sensitivity metrics.
- Laser-based:Solid-state excitation sources provide enhanced stability and reduced warm-up time for time-resolved fluorescence applications.
- Hybrid Technology:Combined photomultiplier and imaging architectures attempt to consolidate sensitivity with spatial information capture.
Optical Grade holds installed capacity. CCD Imaging is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput connects German analytical instrumentation manufacturers to Asian photodetector suppliers, underwriting Europe's concentration of microplate reader production capacity.
United States
Pharmaceutical high-throughput screening facilities in Massachusetts and California drive multimode reader procurement with embedded FDA 21 CFR Part 11 audit-trail requirements. EPA Method 1664 certification mandates for oil and grease quantification expand environmental laboratory demand beyond traditional life science applications. The Research Triangle Park in North Carolina anchors contract research organization density sustaining replacement cycles.
Germany
Baden-Württemberg and Bavaria host dense clusters of contract research organizations generating above-average demand for 1536-well format optical detection systems. REACH substance restriction proposals for cadmium and lead in electronic components force photodetector redesigns across European supply chains. German manufacturers accelerate in-house detector development to reduce Asian component dependency.
Japan
Photomultiplier tube manufacturing concentrates among Japanese suppliers, exposing instrument vendors to single-source risk for charge-coupled device alternatives. PMDA software validation standards for AI-enabled plate analysis algorithms reshape compliance requirements for clinical diagnostic deployments. The Kanto region around Tokyo anchors precision optical component fabrication.
China
Domestic pharmaceutical companies scale high-throughput screening infrastructure for innovative drug development, compressing lead identification timelines. NMPA electronic records requirements for regulated drug development parallel FDA 21 CFR Part 11 frameworks. The Yangtze River Delta concentrates biotechnology startup formation driving fragmented academic procurement patterns.
United Kingdom
London and Cambridge biotech clusters sustain demand for multimode readers with flexible assay protocol compatibility. MHRA alignment with EU IVDR transition timelines extends validation requirements for clinical diagnostic instrument placements. The Golden Triangle research corridor anchors National Health Service-funded core facility equipment pools.
Microplate Reader Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in photodetector and optical filter manufacturing. The vendor base consolidates around captive field service networks and automated workflow integration capabilities. Three archetypes dominate: diversified life science conglomerates with diagnostic installed bases, European analytical instrumentation specialists with rapid fulfillment cycles, and precision optics component suppliers controlling photomultiplier tube supply. Competitive moves center on service contract unbundling for academic accounts and backward integration into detector manufacturing to mitigate supply concentration risk.
Among German analytical instrumentation specialists, BMG LABTECH GmbH occupies a position exemplifying European manufacturing-based fulfillment advantages. Thermo Fisher Scientific Inc. and Danaher Corporation represent the diversified conglomerate archetype, anchoring competitive positioning through captive service infrastructure and diagnostic workflow integration. These three entities collectively illustrate how geographic manufacturing concentration and installed base scale define sustainable market presence.
| Leading Market Players |
|---|
| BMG LABTECH GmbH |
| Bio-Rad Laboratories Inc. |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Molecular Devices LLC |
| PerkinElmer Inc. |
| Tecan Group Ltd. |
| Promega Corporation |
| Agilent Technologies Inc. |
| Others |
Cost & Logistics Intelligence
Japanese and Russian photomultiplier tube suppliers anchor upstream component availability, concentrating margin capture in detector manufacturing while instrument assemblers downstream face cost pass-through pressure from single-source photodetector architectures.
Pricing Analysis
Volume-discount tiering structures separate multimode platform procurement for pharmaceutical compound libraries from single-mode absorbance systems for environmental laboratories. Pricing stratifies across FDA 21 CFR Part 11-certified premium tiers, mid-range research-grade configurations, and economy absorbance units for water quality agencies. Cost compression in entry-level tiers is intensifying as benchtop spectrophotometers retain substitution threat for laboratories processing under 50 samples daily. Academic research institutes exhibit highest price sensitivity due to fragmented purchasing authority, while pharmaceutical companies prioritize audit-trail embedding over capital expenditure minimization.
Supply Chain Analysis
Export-control regimes governing precision optical components limit photodetector flows from Japanese suppliers to European instrument manufacturers, forcing supply chain reconfiguration. Manufacturing concentrates in Germany for analytical instrumentation assembly, Japan for photomultiplier tube fabrication, and China for electronic subcomponent production. Photomultiplier tubes, charge-coupled device arrays, and optical filter wheels constitute critical input dependencies. Single-source vulnerability in photodetector supply exposes vendors to disruption risk from trade restriction expansion. Distribution runs through direct-to-laboratory e-commerce platforms displacing traditional distributor networks for academic and startup biotechnology accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microplate reader penetration sits at early-cycle expansion in municipal water quality applications, with enzymatic assay protocol adoption by United States utilities creating a fresh demand vector beyond established pharmaceutical screening infrastructure.
For Market Incumbents: Entrench service contract dominance through captive field engineering networks that pharmaceutical quality control laboratories cannot replicate in-house. Accelerate backward integration into photodetector manufacturing to reduce dependency on Japanese and Russian suppliers facing export-control exposure. Defensive consolidation around automated workflow integration capabilities protects against benchtop spectrophotometer substitution in small environmental testing facilities.
For New Entrants and Emerging Players: Municipal utilities across the United States represent underpenetrated demand for EPA-certified absorbance systems with Method 1664 protocol implementation. Water quality agencies in secondary metropolitan markets lack incumbent vendor relationships, creating white-space opportunity for first-mover enzymatic assay certification. Direct-to-laboratory distribution with same-day fulfillment capabilities bypasses entrenched distributor relationships that disadvantage new market participants.
For Investors and Strategic Acquirers: Capital is best deployed toward European analytical instrumentation specialists with in-house detector development programs and rapid fulfillment cycle capabilities. Long-term viability rests on decoupling from Asian photodetector supply concentration through captive manufacturing investment. The signal to watch is REACH substance restriction implementation forcing cadmium and lead phosphor redesigns across European supply chains, which would accelerate consolidation among vendors with qualified alternative materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Photodetector Backward Integration | In-house manufacturing of photomultiplier tubes reduces exposure to Japanese and Russian supply concentration risk. |
| EPA Method Certification Program | Pre-validated absorbance protocols for oil and grease quantification capture municipal utility procurement authority. |
| AI-Enabled Plate Analysis Platform | Machine learning algorithms for edge detection create service differentiation through predictive maintenance capabilities. |
| Direct-to-Laboratory Distribution Expansion | E-commerce platforms with same-day fulfillment displace traditional distributors in fragmented academic markets. |
| EU IVDR Compliance Acceleration | ISO 13485 quality management investment captures clinical diagnostic placements under European regulatory frameworks. |
Research Approach
Cross-validation between primary interviews with instrument manufacturers and secondary regulatory filings anchors the qualitative findings on FDA 21 CFR Part 11 compliance requirements. The research team conducted structured discussions with biomedical engineers at National Institutes of Health-funded core facilities, procurement managers at contract research organizations in Baden-Württemberg, quality assurance leads at pharmaceutical manufacturing sites, and field service directors at analytical instrumentation vendors. Secondary sources include EPA method validation databases, FDA 510(k) premarket notification filings, EMA guidance documents on software validation, and ISO 13485 certification registries. Bottom-up unit demand estimates from end-user segments were reconciled with top-down market sizing derived from manufacturer revenue disclosures.
Calibration against historical replacement cycles and installed base depreciation schedules shaped the analytical framework across the projection horizon. Segmentation modeling incorporated detection modality, application intensity, end-user purchasing authority structure, and technology architecture maturity. CAGRs were derived from regression analysis of capital expenditure patterns in pharmaceutical screening facilities and environmental laboratory certification timelines. Industry-specific forecast inputs include 1536-well format adoption rates in high-throughput screening workflows and enzymatic assay protocol penetration in municipal water quality agencies.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified life science conglomerates into detector manufacturing would shift outcomes. Material shifts in REACH substance restriction enforcement or photodetector export-control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Histopathology Testing Equipment Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Laboratory Furnaces Market
Laboratory Equipment
Laboratory Vacuum Drying Oven Market
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
Automated Blood Processing Equipment Market
Laboratory Equipment
Asia Pacific Cell Counting Market
Laboratory Equipment
Micropipette Puller Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Middle East and Africa Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Automated Analyzers Market
Laboratory Equipment
ASEAN Laboratory Equipment Market
Laboratory Equipment
Microplate Washer Market