
 Portable Hemoglobin Analyzer Market | 2026-2036
Portable Hemoglobin Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Hemoglobin Analyzer Market Insights
Leasing and pay-per-test financing is narrowing the capital barrier for mid-sized clinics and blood banks seeking point-of-care hemoglobin testing. Siemens Healthineers leverages its installed base of laboratory systems to cross-sell portable units into emerging markets. HemoCue AB anchors its position through optical method specialization and longstanding relationships with blood donation centers. Masimo Corporation differentiates via pulse-oximetry-adjacent technology that extends into non-invasive hemoglobin monitoring.
A portable hemoglobin analyzer is a compact diagnostic instrument that quantifies hemoglobin concentration in whole blood using optical absorbance, electrochemical sensing, or colorimetric reaction principles, typically delivering results within 15-60 seconds for clinical decision-making. Handheld devices and point-of-care configurations dominate volume shipments due to their suitability for field screening and resource-limited settings. Optical methods sustain the largest technology share while electrochemical approaches represent the fastest-growing segment as manufacturers improve sensor stability and reduce reagent dependence. Blood banks and clinics constitute the core end-user base, though home care settings are gaining traction where remote patient monitoring programs expand.
FDA 510(k) clearance requirements and the EU In Vitro Diagnostic Regulation (IVDR) impose clinical validation burdens that shape product development costs and market entry timelines for portable hemoglobin analyzers. ISO 15189 accreditation standards for medical laboratories further influence instrument specifications and quality control protocols. Stakeholders must monitor evolving reimbursement pathways for point-of-care testing as these determine whether device deployment accelerates or stalls in cost-constrained health systems.
Market Dynamics
Point-of-care financing models and optical-electrochemical technology convergence are compressing capital barriers while fragmenting procurement authority across rural clinics, blood banks, and home monitoring programs.
Growth Catalysts
- IVDR Compliance Deadlines:The EU In Vitro Diagnostic Regulation's 2025-2028 transition window accelerates CE-marked device upgrades across European blood donation networks.
- Anemia Screening Mandates:India's National Iron Plus Initiative drives institutional procurement of handheld analyzers for maternal health camps in Bihar and Uttar Pradesh.
- Non-Invasive Spectroscopy:Multi-wavelength optical sensing reduces venipuncture requirements, expanding screening feasibility in pediatric and geriatric populations.
Market Restraints
- Reagent Supply Concentration:Lyophilized hemoglobin reagents depend on three European chemical suppliers, exposing procurement to batch-to-batch variability and customs delays.
- FDA 510(k) Validation Burden:Clinical equivalence studies for predicate device matching add 14-22 months to US market entry timelines.
- Smartphone-Based Colorimetry:Camera-plus-app diagnostic platforms threaten low-end portable analyzer volumes in price-sensitive Southeast Asian markets.
Strategic Opportunities
- Remote Patient Monitoring Programs:Home care settings in Germany and Japan seek Bluetooth-enabled analyzers for chronic kidney disease management.
- Subscription Service Models:Per-test leasing with automatic calibration scheduling penetrates mid-sized Indonesian clinic chains lacking capital budgets.
- WHO Prequalification Pathway:WHO PQ listing unlocks pooled procurement for anemia screening in sub-Saharan African public health programs.
Industry Challenges
- ISO 15189 Accreditation Complexity:Medical laboratories demand traceable calibration certificates and inter-laboratory comparison data that strain smaller manufacturers' quality systems.
- Biocompatibility Testing Costs:Electrochemical sensor electrode materials require ISO 10993 cytotoxicity and sensitization studies that add $180,000-$240,000 per device variant.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Hemoglobin Analyzer Market |
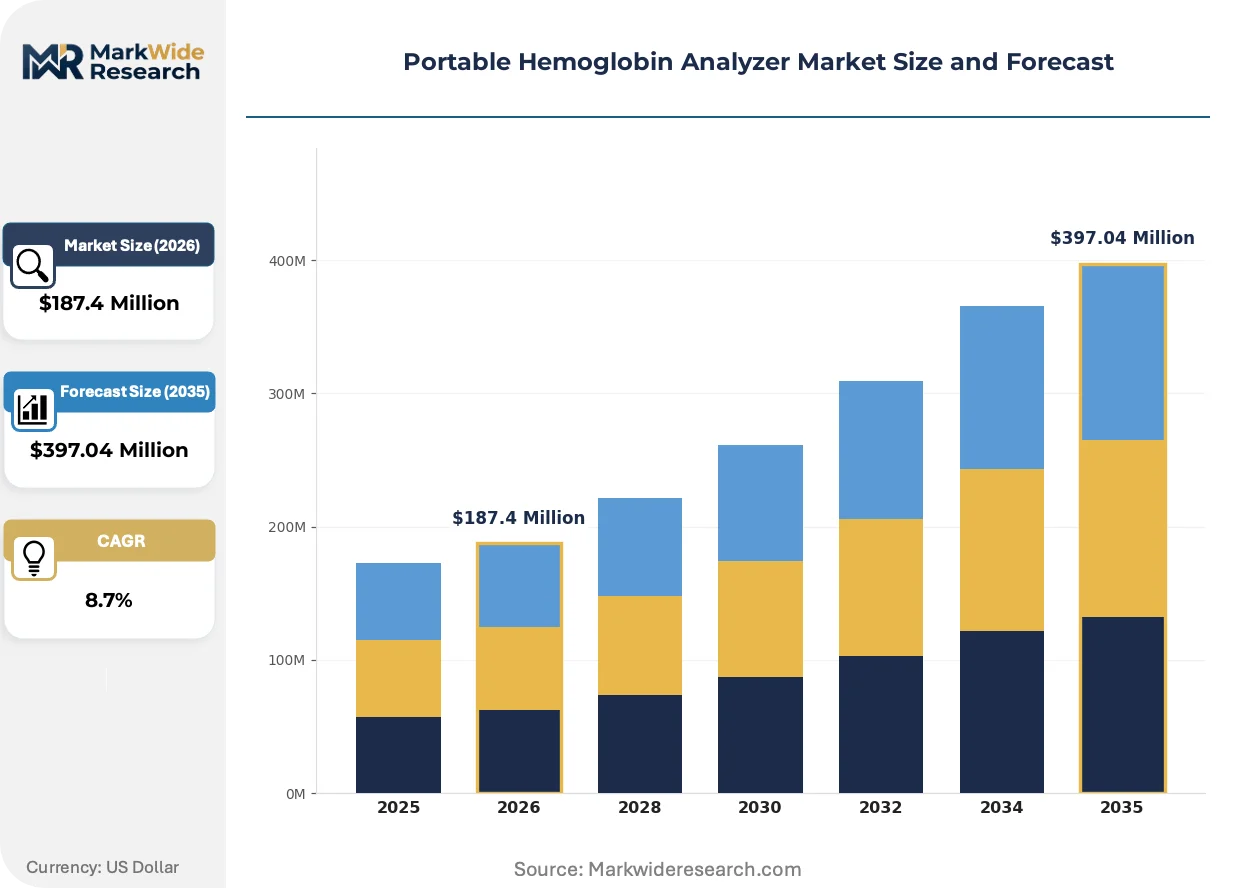
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Analyzers, Handheld Devices, Desktop Analyzers, Point-of-Care Devices Technology: Optical Methods, Electrochemical Methods, Colorimetric Analysis, Ultrasonic Techniques End User: Hospitals, Blood Banks, Clinics, Home Care Settings Application: Anemia Screening, Blood Donation, Clinical Research, Patient Monitoring |
| Companies Covered | Siemens Healthineers, Radiometer Medical ApS, HemoCue AB, Beckman Coulter, Mindray Bio-Medical Electronics, EKF Diagnostics, Masimo Corporation, ACON Laboratories, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Hemoglobin Analyzer Market Trends and Innovations
Portable hemoglobin diagnostics are bifurcating into two innovation tracks: laboratory-grade accuracy in handheld formats, and algorithm-enhanced consumer devices that trade precision for accessibility and connectivity.
Microfluidic capillary electrophoresis chips integrated with smartphone readouts are rendering obsolete single-use cuvette-based photometers in resource-limited settings. Médecins Sans Frontières field clinics in Kenya and Bangladesh have adopted these platforms for rapid anemia triage. The shift compresses per-test consumable costs from $0.80 to $0.15 while eliminating cold-chain reagent storage.
EU MDR Class IIa reclassification requirements impose clinical performance studies and post-market surveillance obligations that favor established manufacturers with regulatory infrastructure. Smaller Asian OEMs face notified body capacity constraints and extended technical documentation reviews. Blood bank procurement committees now prioritize MDR-certified devices over legacy IVDD-compliant instruments.
Diagnostic procurement through group purchasing organizations is consolidating buying power among US hospital networks and Indian state medical services corporations. Independent distributors lose volume to direct manufacturer contracts with standardized service-level agreements. The pattern concentrates most acutely in Tamil Nadu and Karnataka, where state tendering aggregates demand from 400+ primary health centers.
Portable Hemoglobin Analyzer Market Segmentation
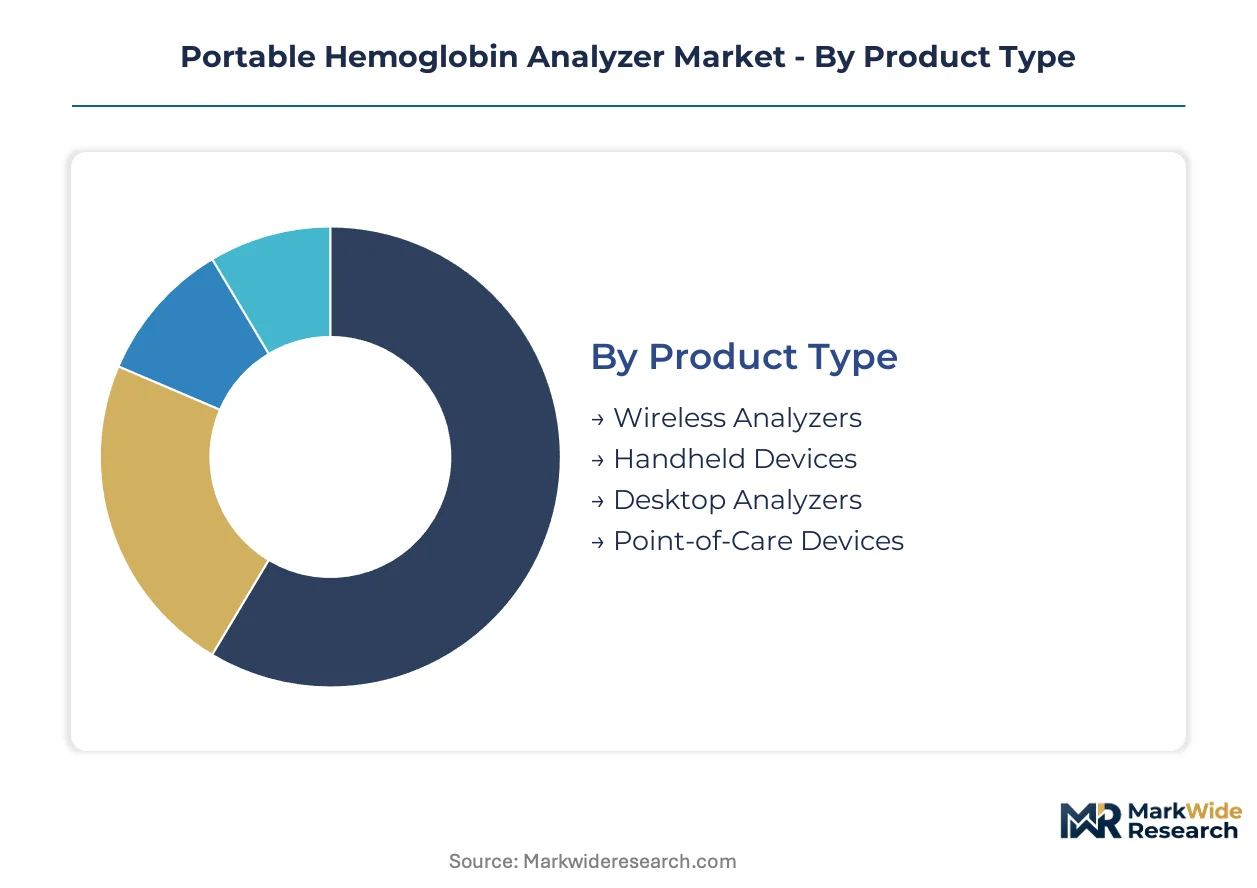
Segmentation in portable hemoglobin analyzers reveals divergent service intensity requirements across product tiers. Wireless and handheld units demand rapid field calibration support, while desktop installations require comprehensive laboratory integration services that reshape vendor profitability profiles.
Product Type:
After-sales service intensity varies dramatically across form factors, with wireless and handheld devices requiring distributed technician networks versus centralized depot service for desktop units.
- Handheld Devices:Battery-powered units weighing under 500 grams deliver capillary blood results in 15-30 seconds through single-button operation. Blood donation camps in Uttar Pradesh and Bihar deploy these for anemia screening under India's National Iron Plus Initiative, where dust exposure and temperature swings strain optical windows and accelerate calibration drift.
- Point-of-Care Devices:Slightly larger than handheld units, these incorporate printer modules and barcode scanners for patient ID tracking in mid-sized clinic chains. Indonesian diagnostic networks favor per-test leasing arrangements that bundle automatic calibration scheduling, reducing capital barriers for facilities serving 50-150 patients daily.
- Wireless Analyzers:Bluetooth-enabled data transmission to laboratory information systems supports remote patient monitoring programs in Germany and Japan for chronic kidney disease management.
- Desktop Analyzers:Benchtop units with automated sample handling serve high-throughput blood bank laboratories requiring traceable calibration certificates under ISO 15189 accreditation standards.
By volume, Handheld Devices leads. By growth pace, Point-of-Care Devices is ahead.
Technology:
Cost tier differentiation separates premium optical platforms from emerging electrochemical alternatives that reduce reagent dependence and cold-chain requirements.
- Optical Methods:Multi-wavelength absorbance spectrophotometry remains the reference standard, measuring hemoglobin-derivative absorption at 540-570 nanometers with coefficient of variation below 2%. European blood donation networks prioritize MDR Class IIa certified optical units over legacy IVDD-compliant instruments during the 2025-2028 transition window.
- Electrochemical Methods:Amperometric sensing of hemoglobin-mediated electron transfer eliminates photometric interference from lipemia or icterus. Sensor electrode materials require ISO 10993 cytotoxicity studies that add substantial per-variant certification costs, favoring established manufacturers with regulatory infrastructure over smaller Asian OEMs facing notified body capacity constraints.
- Colorimetric Analysis:Cyanmethemoglobin formation with visual or photometric endpoint detection persists in resource-limited settings where reagent stability exceeds instrument durability concerns.
- Ultrasonic Techniques:Acoustic attenuation measurement of red cell concentration offers reagent-free operation but struggles with precision in polycythemic samples.
Optical Methods commands the revenue base. Electrochemical Methods is climbing the fastest as manufacturers improve sensor stability.
End User:
Application maturity determines procurement authority concentration, with blood banks consolidating specifications while home care fragments purchasing across individual patients and remote monitoring programs.
- Blood Banks:High-volume screening operations process 200-1,000 donations daily, demanding 99.5% uptime guarantees and four-hour emergency service response. Group purchasing organizations consolidate US hospital network procurement, squeezing independent distributor margins through direct manufacturer contracts with standardized service-level agreements.
- Clinics:Primary health centers in Tamil Nadu and Karnataka aggregate demand through state tendering covering 400+ facilities, prioritizing devices with local language interfaces and battery operation for unreliable grid conditions.
- Hospitals:Emergency departments and pre-operative assessment units integrate portable analyzers with central laboratory quality control protocols.
- Home Care Settings:Bluetooth-enabled devices for chronic disease self-monitoring spread through German and Japanese reimbursement pathways for renal patient management.
Blood Banks dominates procurement volume. Home Care Settings shows the steepest expansion trajectory as reimbursement frameworks mature.
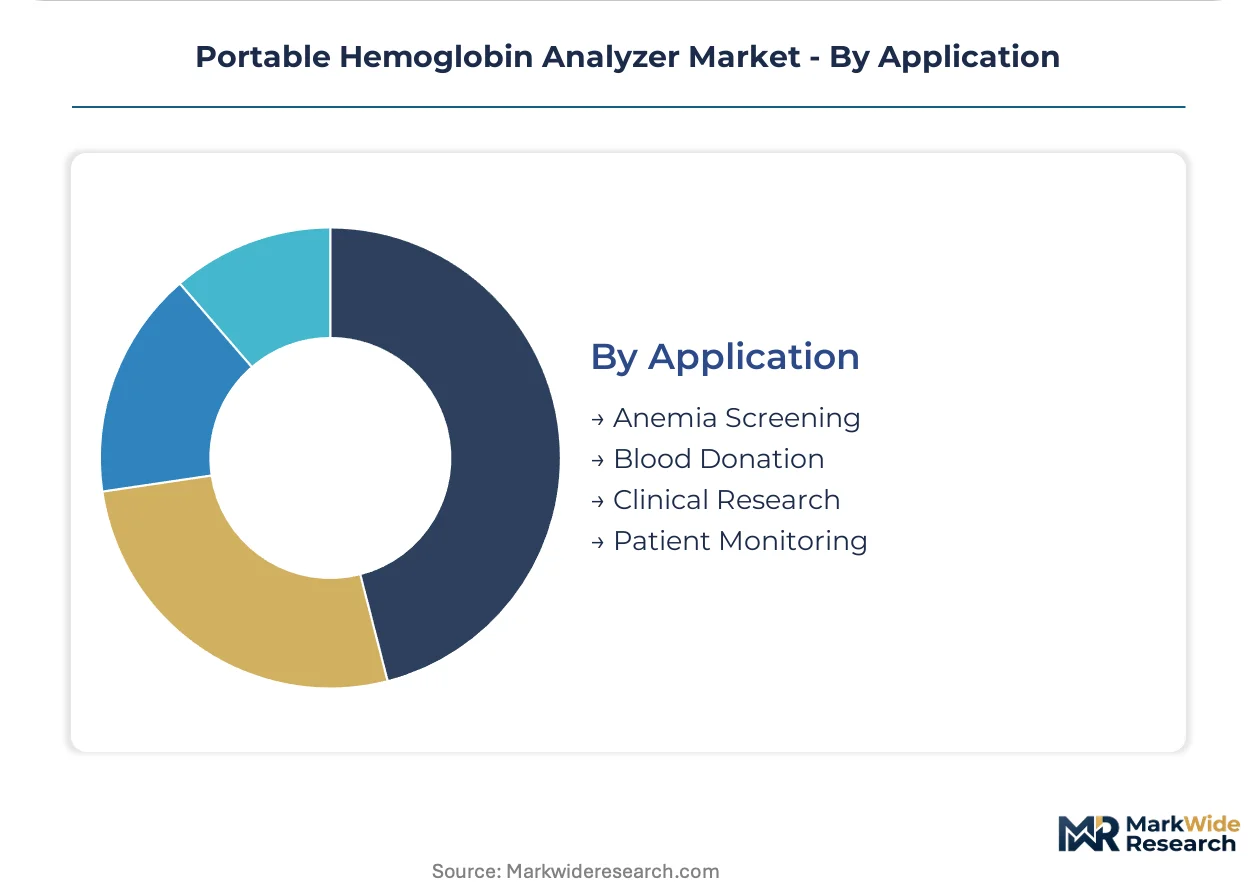
Application:
Customer type segmentation separates institutional screening mandates from precision-dependent clinical research requirements that command premium pricing.
- Anemia Screening:Population-scale hemoglobin assessment in maternal health programs and school-based initiatives drives lowest-cost-per-test procurement. Médecins Sans Frontières field clinics in Kenya and Bangladesh have adopted microfluidic smartphone-readout platforms that compress consumable costs while eliminating cold-chain dependencies.
- Patient Monitoring:Serial hemoglobin tracking in oncology, nephrology, and critical care settings demands trend accuracy and longitudinal data integrity. Non-invasive multi-wavelength spectroscopy reduces venipuncture requirements, expanding feasibility in pediatric and geriatric populations where repeated sampling poses ethical and practical barriers.
- Blood Donation:Pre-donation hemoglobin thresholds protect donor safety and blood product quality, requiring regulatory-compliant documentation for traceability.
- Clinical Research:Phase I-III trials demand calibrated instruments with inter-laboratory comparison data and audit-ready quality systems that strain smaller manufacturers.
Anemia Screening leads by test volume. Patient Monitoring is gaining share fastest through remote care program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's National Iron Plus Initiative and the EU IVDR transition window are accelerating procurement cycles for point-of-care hemoglobin testing across divergent healthcare infrastructure contexts.
United States
Blood bank networks in Texas and California consolidate purchasing through group purchasing organizations that demand FDA 510(k) cleared devices with four-hour emergency service response. The FDA's clinical equivalence study requirements for predicate device matching extend market entry timelines for new entrants. Siemens Healthineers leverages its installed laboratory base to cross-sell portable units into mid-sized hospital networks.
Germany
Remote patient monitoring programs for chronic kidney disease management drive Bluetooth-enabled analyzer adoption in Bavaria and North Rhine-Westphalia. The EU MDR Class IIa reclassification imposes post-market surveillance obligations that favor established manufacturers with regulatory infrastructure. Berlin-based procurement committees now prioritize MDR-certified devices over legacy IVDD-compliant instruments.
India
Maternal health camps in Bihar and Uttar Pradesh deploy handheld analyzers under the National Iron Plus Initiative, where dust exposure and temperature swings strain optical components. CDSCO registration requirements shape product specifications for domestic distribution. Tamil Nadu and Karnataka aggregate demand through state tendering covering 400+ primary health centers with local language interface requirements.
Japan
Home care settings in the Kanto region seek wireless analyzers for renal patient management as reimbursement frameworks mature. PMDA consultation procedures for in vitro diagnostic devices influence development timelines for electrochemical sensor platforms. Osaka-based clinic chains evaluate per-test leasing models to bypass capital budget constraints.
Indonesia
Mid-sized clinic chains in Java adopt subscription service models with automatic calibration scheduling to serve 50-150 patients daily. The national pharmaceutical regulator's import licensing requirements for diagnostic devices create documentation burdens for European suppliers. Jakarta diagnostic networks consolidate procurement authority away from independent distributors toward direct manufacturer contracts.
Portable Hemoglobin Analyzer Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers differentiated by regulatory infrastructure depth and service network reach. Tier-one players maintain notified body relationships and post-market surveillance systems that satisfy EU MDR and FDA requirements. Tier-two specialists compete on optical method refinement for blood donation center specifications. Tier-three regional fabricators target price-sensitive clinic procurement in Southeast Asia through simplified device architectures. Competitive moves concentrate on cross-selling portable units into installed laboratory bases and per-test leasing arrangements that convert capital expenditure into operational budgets.
Among diversified health technology conglomerates, Siemens Healthineers and Abbott Laboratories exemplify tier-one positioning through regulatory infrastructure scale, while HemoCue AB occupies a specialist niche anchored in optical method heritage. Masimo Corporation represents the pulse-oximetry-adjacent technology vector that extends into non-invasive hemoglobin monitoring. These three companies collectively illustrate the competitive spectrum from comprehensive diagnostic platforms to focused measurement specialization.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Radiometer Medical ApS |
| HemoCue AB |
| Beckman Coulter |
| Mindray Bio-Medical Electronics |
| EKF Diagnostics |
| Masimo Corporation |
| ACON Laboratories |
| Abbott Laboratories |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on three European lyophilized reagent suppliers determines both pricing tier spreads and supply chain shape for portable hemoglobin analyzers, exposing procurement to batch-to-batch variability and customs delays that compress margins in price-sensitive Southeast Asian markets.
Pricing Analysis
Certification level (ISO 15189/FDA 510(k)/CE-IVDR grade) creates the primary spread between premium optical platforms and economy electrochemical units. Three-tier pricing structure across MDR-certified premium, IVDD-transition standard, and non-certified economy levels reflects validation burden differentials. Cost compression in the economy tier intensifies because smartphone-based colorimetry substitutes threaten low-end volumes. Blood banks show least price sensitivity due to uptime guarantees, while maternal health camps in Bihar and Uttar Pradesh exhibit highest sensitivity.
Supply Chain Analysis
Tariff exposure between Germany and India dominates supply chain risk for electrochemical sensor electrode materials. Manufacturing concentrates in Germany, China, and South Korea for optical components and sensor substrates. Production draws from specialized chemical suppliers for lyophilized hemoglobin reagents and ISO 10993-certified biocompatible electrode materials. Single-source vulnerability in European reagent supply creates procurement fragility. Distribution runs through group purchasing organizations in US hospital networks and state tendering authorities in Tamil Nadu and Karnataka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Per-test leasing and automatic calibration scheduling represent a service-attach opportunity expanding faster than hardware shipments, converting capital expenditure into recurring operational budgets for mid-sized clinic chains.
For Market Incumbents: Pre-empt smartphone-based colorimetry substitution by bundling Bluetooth-enabled data integration with laboratory information systems. Fortify position through backward integration into electrochemical sensor electrode production to reduce ISO 10993 cytotoxicity study costs. Prioritize MDR Class IIa certification investment ahead of IVDD transition deadlines to lock out smaller Asian OEMs facing notified body capacity constraints. For New Entrants and Emerging Players: Pursue WHO Prequalification pathway entry for sub-Saharan African public health programs, where pooled procurement mechanisms bypass direct sales infrastructure requirements. Target anemia screening mandates under India's National Iron Plus Initiative as the most penetrable institutional segment. Deploy subscription service models with automatic calibration scheduling to bypass capital budget barriers in Indonesian clinic chains. For Investors and Strategic Acquirers: EU IVDR 2025-2028 transition deadlines reshape the acquisition landscape toward targets with established notified body relationships and post-market surveillance infrastructure. Five-to-ten-year viability favors manufacturers with regulatory infrastructure depth over pure-play technology innovators. Monitor FDA 510(k) predicate device matching success rates as the signal indicating which electrochemical platform investments will secure US market entry.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Class IIa certification unlocks European blood bank procurement committees ahead of IVDD obsolescence. |
| Hospital System Partnership | Direct contracts with Tamil Nadu and Karnataka state tendering authorities aggregate 400+ primary health center demand. |
| Software Companion Development | Bluetooth-enabled laboratory information system integration supports German and Japanese remote patient monitoring programs. |
| Reimbursement Strategy | PMDA and German statutory health insurance pathway navigation determines home care setting penetration for renal patient management. |
| WHO Prequalification Pathway | PQ listing enables pooled procurement access for Médecins Sans Frontières field clinics in Kenya and Bangladesh. |
Research Methodology
Operator-level perspectives from blood bank laboratory directors, biomedical engineers at primary health centers, GPO contracts managers, and diagnostic procurement officers anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, EMA MDR transition databases, CDSCO registration records, and CMS Medicare point-of-care testing reimbursement data. Bottom-up instrument shipment tracking and top-down healthcare expenditure modeling provided triangulation.
Scenario-bracketing around IVDR transition timelines and anemia screening mandate expansion shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product form factor, technology platform, end-user setting, and regional regulatory cluster. CAGRs derived from instrument replacement cycles and test volume intensity curves. Industry-specific inputs incorporated reagent supply concentration risk and calibration drift rates under field conditions.
Macroeconomic conditions sit as an overlay; deviation in Indian public health expenditure allocation or EU notified body capacity would shift the trajectory. Forecasts reflect assumptions regarding regulatory transition adherence and reimbursement pathway maturation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Blood Processing and Storage Equipment Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
Laboratory Pulverizer Market
Laboratory Equipment
Vacuum Tissue Processors Market
Laboratory Equipment
Microplate Luminometer Market
Laboratory Equipment
Histopathology Laboratory Equipment Market
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Laboratory Vacuum Drying Oven Market