
 Muffle Laboratory Furnaces Market | 2026-2036
Muffle Laboratory Furnaces Market Size, Share, and Industry Trends Forecast 2026-2036
Muffle Laboratory Furnaces Market Insights
Equipment leasing and performance-based service contracts is rewriting competitive dynamics for smaller laboratories that previously faced high capital barriers. Nabertherm GmbH leverages its German manufacturing base to sustain premium positioning across European research institutions. Thermo Fisher Scientific Inc. anchors North American demand through extensive distribution networks serving quality control labs. Sentro Tech Corporation competes on specialized configurations for ceramics applications in Asian markets.
Muffle laboratory furnaces are enclosed heating chambers designed to isolate samples from combustion byproducts, typically achieving temperatures from 300°C to 1800°C using refractory ceramic insulation and resistance wire or silicon carbide heating elements. These units perform ashing, calcination, and heat treatment processes where contamination control determines experimental validity. Electric furnaces lead product type demand due to precise temperature uniformity and compatibility with cleanroom environments. Heat treatment applications within electronics manufacturing represent the fastest-growing segment as semiconductor substrate processing requirements tighten. Research institutions remain the most concentrated end user category, though industrial R&D budgets show stronger growth momentum.
ISO 13577 safety standards for industrial thermoprocessing equipment shape baseline design requirements, while EPA emissions guidelines influence gas-fired unit specifications in the United States. Ecodesign regulations in Europe drive replacement demand toward energy-recovery systems and improved insulation packages. REACH compliance on refractory materials affects supplier qualification timelines for furnace manufacturers sourcing ceramic components. Stakeholders must evaluate whether regional efficiency mandates will accelerate obsolescence of installed gas-fired units faster than natural replacement cycles.
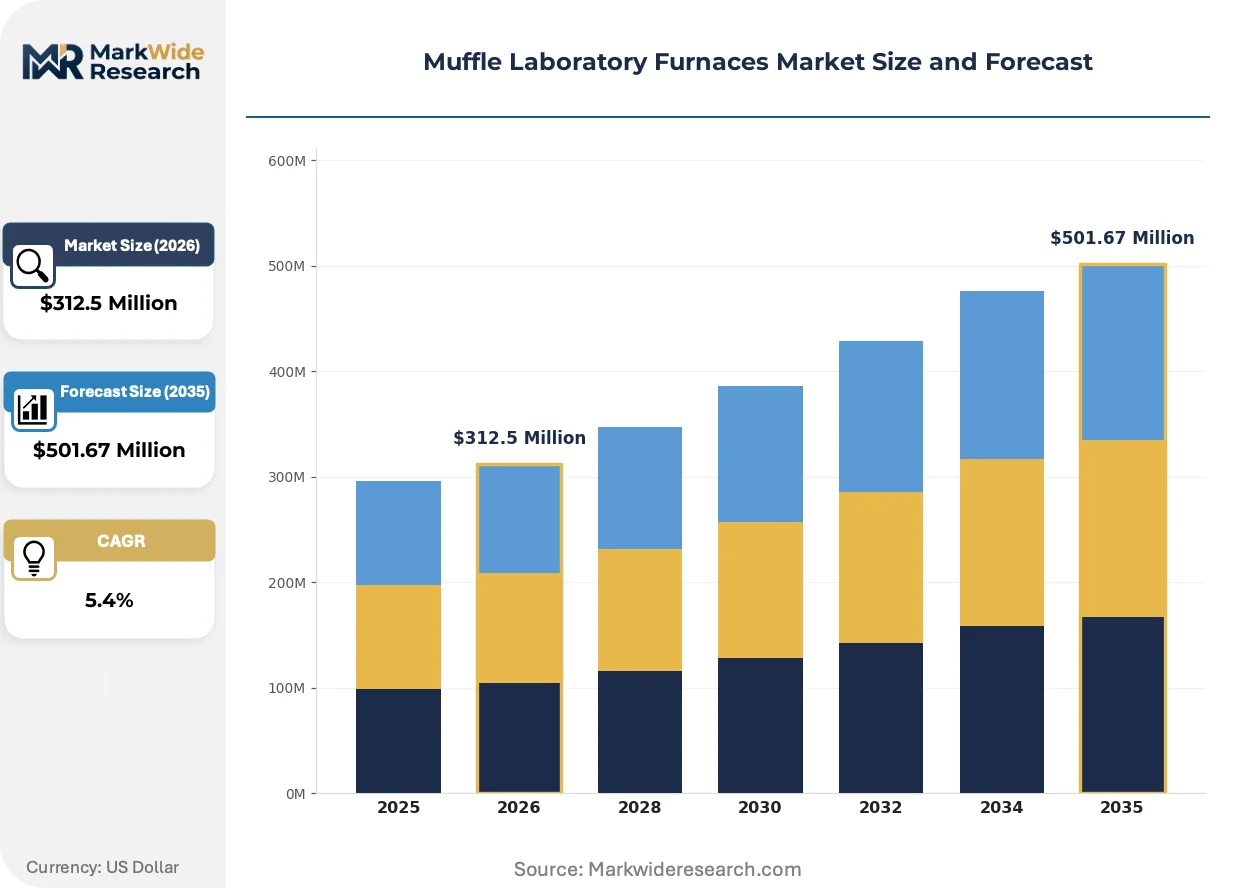
Market Dynamics
Equipment leasing and performance-based service contracts are rewriting competitive dynamics for smaller laboratories that previously faced high capital barriers. Resistance heating technology dominates replacement cycles across industrial R&D centers in the United States.
Growth Catalysts
- REACH compliance on refractory materials:European Ecodesign regulations drive replacement demand toward energy-recovery systems and improved insulation packages in materials testing laboratories.
- Semiconductor substrate processing:Heat treatment applications within electronics manufacturing represent tightening precision requirements for contamination control.
- Electric resistance heating:Industrial R&D centers favor precise temperature uniformity and compatibility with cleanroom environments over gas-fired alternatives.
Market Restraints
- Refractory ceramic supply concentration:REACH compliance affects supplier qualification timelines for furnace manufacturers sourcing ceramic components from limited qualified vendors.
- High capital intensity:Smaller laboratories face upfront equipment costs that strain budgets without financing alternatives or leasing arrangements.
- Gas-fired unit obsolescence risk:Regional efficiency mandates may accelerate obsolescence of installed gas-fired units faster than natural replacement cycles permit.
Strategic Opportunities
- Asian ceramics specialization:Specialized configurations for ceramics applications in Asian markets offer expansion paths beyond saturated Western research markets.
- Energy-recovery system integration:Ecodesign regulations in Europe create demand for upgraded insulation packages and thermal efficiency improvements.
- Performance-based service contracts:Smaller laboratories seek equipment leasing models that transfer operational risk and reduce capital barriers to entry.
Industry Challenges
- ISO 13577 safety certification timelines:Industrial thermoprocessing equipment standards require extensive validation protocols that delay product commercialization.
- Legacy system integration complexity:Research institutions with installed furnace fleets face compatibility barriers when upgrading to modern control architectures.
- Specialized technician scarcity:Operation of high-temperature units requires trained personnel familiar with refractory maintenance and heating element replacement protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Muffle Laboratory Furnaces Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas-fired, Vacuum, Induction Application: Material Testing, Heat Treatment, Ceramics, Electronics Manufacturing End User: Research Institutions, Quality Control Labs, Universities, Industrial R&D Technology: Resistance Heating, Infrared Heating, Convection, Radiant Heating |
| Companies Covered | Thermo Fisher Scientific Inc., Nabertherm GmbH, Carbolite Gero Limited, MTI Corporation, Sentro Tech Corporation, Thermcraft Inc., Heraeus Holding GmbH, Lindberg/Blue M, Bionics Scientific Technologies (P) Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Muffle Laboratory Furnaces Market Trends and Innovations
Digital control architectures and predictive maintenance systems are transforming how laboratories manage thermal processing workflows. Equipment vendors are embedding sensor networks that enable remote monitoring and automated compliance documentation.
Silicon carbide heating elements are virtualizing traditional resistance wire configurations in high-temperature applications. Semiconductor manufacturers in Germany and Japan are adopting these elements for calcination processes requiring sustained operation above 1600°C. This shift is virtualizing maintenance schedules and extending service intervals beyond conventional wire-wound designs.
EPA emissions guidelines in the United States are reshaping gas-fired unit specifications for laboratories in regulated jurisdictions. The industrial consequence is accelerated phase-out of non-compliant combustion systems in favor of electric alternatives. Quality control labs in California and Texas are responding by retrofitting facilities or replacing aging equipment ahead of enforcement deadlines.
Consolidated procurement through group purchasing organizations is compressing vendor margins while expanding access for mid-sized research institutions. Traditional distributor networks serving university systems are losing volume to centralized buying consortia. This pattern is most visible in the United Kingdom and Netherlands where research funding bodies mandate collaborative equipment tendering.
Muffle Laboratory Furnaces Market Segmentation
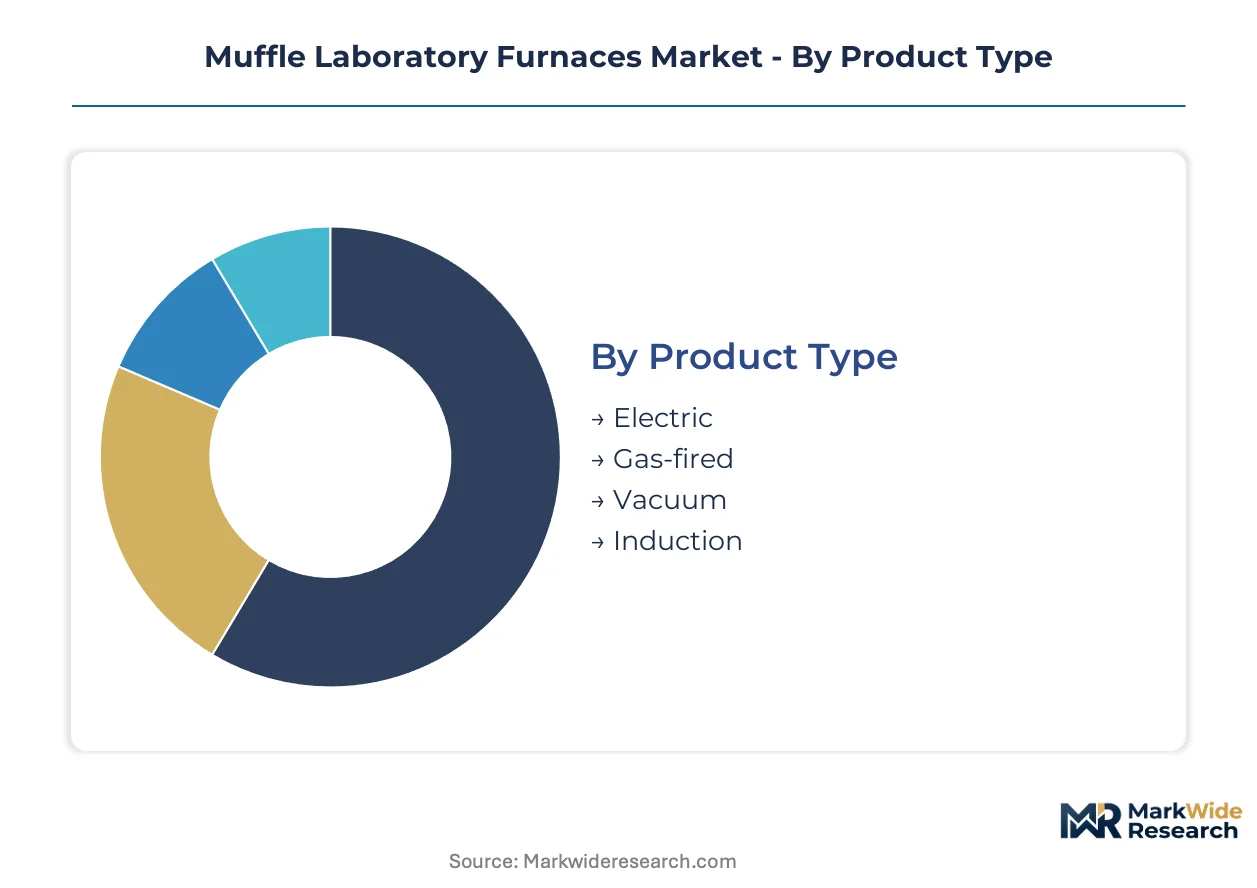
Muffle laboratory furnace purchasing patterns diverge sharply across operational contexts. Service intensity, calibration frequency, and technical support requirements vary by segment, reshaping vendor profitability and customer lifetime value calculations.
Product Type:
After-sales service intensity peaks with electric and vacuum configurations due to heating element replacement cycles and seal maintenance protocols.
- Electric:Resistance wire or silicon carbide elements deliver precise temperature uniformity from 300°C to 1800°C. Quality control labs in Germany favor electric units for REACH-compliant cleanroom compatibility and Ecodesign energy efficiency mandates.
- Vacuum:Sealed chamber designs eliminate oxidation during heat treatment of reactive metals and advanced ceramics. Semiconductor substrate processing facilities in Japan specify vacuum configurations for contamination-sensitive calcination above 1600°C.
- Gas-fired:Combustion-based heating suits high-throughput ashing where emissions regulations permit. EPA guidelines in the United States are accelerating phase-out timelines in regulated jurisdictions.
- Induction:Electromagnetic field heating enables rapid thermal cycling for specialized metallurgical applications. Industrial R&D centers deploy induction units where speed outweighs precision requirements.
By volume, Electric leads. By growth pace, Vacuum is ahead.
Application:
Cost tier differentiation separates capital-intensive electronics manufacturing from routine material testing workflows.
- Electronics Manufacturing:Semiconductor substrate processing demands sub-degree temperature uniformity and particle-free environments. Facilities in Taiwan and South Korea specify silicon carbide heating elements for sustained operation above 1600°C.
- Heat Treatment:Hardening, annealing, and tempering of metal components requires controlled atmosphere capabilities. Automotive supplier labs in Germany integrate energy-recovery systems to meet Ecodesign efficiency thresholds.
- Material Testing:Standardized ashing and gravimetric analysis drives replacement demand in contract laboratories. ISO 13577 safety certification delays product commercialization for vendors serving this segment.
- Ceramics:Sintering and calcination of oxide and non-oxide ceramics requires extended dwell times at peak temperature. Specialized configurations for Asian markets emphasize refractory insulation packages.
Electronics Manufacturing commands the highest unit prices. Ceramics applications are expanding most quickly.
End User:
Customer type determines procurement channel preference and contract structure flexibility.
- Research Institutions:Principal investigator-driven purchasing emphasizes technical specifications over total cost of ownership. Legacy system integration complexity slows upgrade cycles at universities with installed furnace fleets.
- Industrial R&D:Corporate laboratories favor performance-based service contracts that transfer operational risk. Resistance heating technology dominates replacement cycles across United States industrial R&D centers.
- Quality Control Labs:Compliance documentation requirements drive demand for automated data logging and remote monitoring. Group purchasing organizations are compressing vendor margins while expanding access.
- Universities:Budget constraints and shared equipment facilities create price sensitivity. Equipment leasing models reduce capital barriers for smaller laboratories.
Research Institutions concentrate absolute unit demand. Industrial R&D budgets are climbing the fastest.
Technology:
Supply concentration in heating element manufacturing shapes vendor qualification timelines and replacement part availability.
- Resistance Heating:Nickel-chromium wire and silicon carbide rods provide predictable thermal profiles across standardized chamber geometries. Industrial R&D centers in the United States specify resistance heating for proven reliability.
- Infrared Heating:Quartz lamp arrays enable rapid thermal cycling for thin-film processing and semiconductor annealing. Electronics manufacturers in Japan adopt infrared for selective heating applications.
- Convection:Forced air circulation improves temperature uniformity in large-volume chambers. Material testing laboratories deploy convection for batch processing of multiple samples.
- Radiant Heating:Ceramic fiber heaters distribute heat through infrared radiation without direct element contact. Specialized configurations for ceramics applications in Asian markets leverage radiant designs.
Resistance Heating retains the largest installed base. Infrared Heating is gaining share fastest in semiconductor processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for high-temperature refractory ceramics concentrates supply leverage in Germany and China, while export-oriented furnace assembly clusters in the United States and Japan shape finished equipment trade flows. Regional regulatory divergence on emissions and energy efficiency is fragmenting product specifications across jurisdictions.
United States
Industrial R&D centers in Massachusetts and California drive replacement demand for resistance-heating configurations that satisfy EPA emissions guidelines. The agency's enforcement deadlines in regulated jurisdictions accelerate phase-out of non-compliant combustion systems. Quality control labs in Texas and the Pacific Northwest respond by retrofitting facilities or replacing aging equipment ahead of schedule.
Germany
Materials testing laboratories in Bavaria and Baden-Württemberg expand procurement of electric muffle units to meet stricter Ecodesign requirements for energy efficiency. REACH compliance on refractory materials affects supplier qualification timelines for furnace manufacturers sourcing ceramic components. Research institutions in Berlin-Brandenburg and North Rhine-Westphalia prioritize energy-recovery systems and improved insulation packages.
China
Semiconductor substrate processing facilities in the Yangtze River Delta and Pearl River Delta specify silicon carbide heating elements for sustained operation above 1600°C. The country's dual carbon goals tighten energy efficiency standards for industrial thermoprocessing equipment. Ceramics manufacturers in Shandong Province and Sichuan-Chongqing region adopt specialized furnace configurations for oxide and non-oxide sintering applications.
Japan
Electronics manufacturers in Kanto and Kansai regions adopt infrared heating configurations for selective annealing of thin-film semiconductor devices. METI efficiency standards influence procurement criteria for laboratory-scale thermal processing equipment. Vacuum furnace demand concentrates in Nagoya's Chubu industrial corridor for contamination-sensitive calcination above 1600°C.
South Korea
Semiconductor foundries in the Seoul Capital Area and Busan-Ulsan region specify sub-degree temperature uniformity for substrate processing workflows. MFDS equipment safety guidelines intersect with corporate sustainability mandates to favor electric over gas-fired alternatives. Display panel manufacturers in Gwangju-Honam deploy rapid thermal cycling units for thin-film transistor fabrication.
Muffle Laboratory Furnaces Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in heating elements and refractory ceramics. The vendor base organizes into three tiers: multinational laboratory equipment conglomerates with distribution scale, mid-cap regional furnace fabricators with customization depth, and specialized ceramic component suppliers with captive metallurgy expertise. Strategic moves concentrate on geographic expansion through distribution partnerships and backward integration into heating element manufacturing to secure supply continuity.
Among German manufacturing specialists, Nabertherm GmbH exemplifies premium positioning anchored in European research institution relationships. Thermo Fisher Scientific Inc. represents the integrated platform tier with extensive North American distribution networks. Sentro Tech Corporation occupies a position within specialized configuration supply for ceramics applications. These three archetypes illustrate how competitive positioning diverges between scale-driven service coverage and application-specific engineering depth.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Nabertherm GmbH |
| Carbolite Gero Limited |
| MTI Corporation |
| Sentro Tech Corporation |
| Thermcraft Inc. |
| Heraeus Holding GmbH |
| Lindberg/Blue M |
| Bionics Scientific Technologies (P) Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese silicon carbide heating element production is compressing margins for furnace manufacturers while simultaneously lowering input costs for European and North American assemblers. This utilization imbalance rewards buyers with procurement leverage in contract negotiations while forcing suppliers toward performance-based service bundling.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Price differentiation hinges on ISO 13577 certification tier and after-sales service intensity, with research institutions least sensitive and universities most price-constrained. Cost compression in standard-grade electric units is intensifying because group purchasing organizations aggregate demand across mid-sized laboratories. Vacuum configurations with silicon carbide elements command premium positioning due to limited qualified vendors and extended replacement intervals.
Supply Chain Analysis
Contract manufacturing for furnace assembly concentrates in Germany, the United States, and China, with Nabertherm GmbH and Thermo Fisher Scientific Inc. retaining in-house production. Supply draws from high-purity alumina refractories sourced from China and Germany, nickel-chromium wire from Japan, and silicon carbide rods from Chinese specialty ceramics producers. Single-source vulnerability in silicon carbide heating elements creates qualification bottlenecks when REACH compliance updates trigger vendor re-approval. Distribution runs through laboratory equipment distributors serving research institutions and direct sales teams for industrial R&D accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where predictive maintenance systems and remote monitoring architectures are redefining vendor-customer relationships beyond transactional equipment sales.
For Market Incumbents: Harden defensive positions by deepening backward integration into silicon carbide heating element manufacturing to escape supply qualification delays. Secure channel control through exclusive service contracts with university purchasing consortia in Germany and the Netherlands. The threat of consolidated procurement through group purchasing organizations demands certification investment in ISO 13577 validation protocols to maintain premium tier access.
For New Entrants and Emerging Players: Pursue white-space expansion in Asian ceramics applications where specialized furnace configurations face limited indigenous competition. Target South Korean semiconductor substrate processing facilities seeking sub-degree temperature uniformity alternatives to established Japanese suppliers. A performance-based leasing go-to-market angle transfers capital barriers from cash-constrained laboratories while building installed base for aftermarket service revenue.
For Investors and Strategic Acquirers: Long-term, this sits as a replacement-cycle consolidation play because Ecodesign mandates and EPA emissions deadlines accelerate obsolescence of installed gas-fired fleets. Acquisition targets should emphasize mid-cap regional fabricators with customization depth and captive heating element supply relationships. Watch for inflection signals in silicon carbide spot pricing and REACH compliance update timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Captive silicon carbide production secures supply continuity against REACH-driven vendor requalification delays. |
| Performance-Based Service Contracts | Equipment leasing transfers operational risk from universities facing capital constraints to vendor balance sheets. |
| Predictive Maintenance Platform Launch | Sensor-enabled remote monitoring repositions furnace vendors as workflow partners rather than hardware suppliers. |
| Energy-Recovery System Integration | Ecodesign-compliant insulation packages capture replacement demand in German materials testing laboratories. |
| Asian Ceramics Specialization | Customized refractory configurations for oxide sintering penetrate underserved markets in Shandong and Sichuan provinces. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with laboratory equipment procurement managers at research institutions, maintenance directors at industrial R&D centers, furnace manufacturing plant engineers, and aftermarket service heads at regional distributors. Secondary validation drew from EPA emissions enforcement records, ECHA REACH substance registrations, ISO 13577 certification databases, and customs trade data for high-temperature ceramics. Bottom-up unit demand estimates triangulated against top-down market sizing from equipment vendor revenue disclosures.
Calibration against historical replacement cycles and regulatory enforcement timelines shaped projections across the analysis window. Segmentation dimensions modeled include product type, application workflow, end-user category, heating technology, and regional regulatory cluster. CAGRs derived from weighted average of technology diffusion rates and compliance-driven replacement elasticity. Industry-specific inputs incorporated semiconductor capital expenditure patterns and European Ecodesign implementation schedules.
Sensitivities concentrate around REACH substance restriction updates, silicon carbide supply disruptions, and EPA enforcement acceleration in regulated U.S. jurisdictions. Forecasts embed assumptions regarding natural replacement cycles versus regulatory-forced obsolescence. Quarterly review of heating element spot pricing and certification timeline announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Laboratory Vacuum Drying Oven Market
Laboratory Equipment
Colony Counters Market
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Cell Analysis Instruments Market
Laboratory Equipment
Pipettes and Accessories Market
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
Automated Plate Readers Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Cuvettes Market
Laboratory Equipment
North America Laboratory Hoods and Enclosure Market
Laboratory Equipment
Albumin Analyzers Market
Laboratory Equipment
Laboratory Fume Hoods Market
Laboratory Equipment
Micropipette Puller Market
Laboratory Equipment
Laboratory Furniture Market
Laboratory Equipment
C-Reactive Protein Analyzers Market
Laboratory Equipment
Hemostasis Analyzers Market