
 Electrophoresis Equipment and Supplies Market | 2026-2036
Electrophoresis Equipment and Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Electrophoresis Equipment and Supplies Market Intelligence
A transition toward direct-to-laboratory procurement models is rewriting the established distribution landscape for electrophoresis supplies. Thermo Fisher Scientific leverages its extensive e-commerce platform to capture a significant share of this direct business. Bio-Rad Laboratories sustains its position through strong relationships with academic research institutions and specialized distributors. Meanwhile, Agilent Technologies differentiates with integrated workflow solutions that bundle equipment and consumables for specific analytical applications.
Electrophoresis equipment facilitates the separation of macromolecules such as DNA, RNA, and proteins based on their charge and size. This technique applies a controlled electric field across a gel matrix, typically composed of agarose or polyacrylamide, to induce migration for analytical and preparative purposes. Within the technology landscape, capillary electrophoresis is gaining traction for automated, high-throughput workflows in pharmaceutical quality control. DNA analysis continues to represent the largest application segment, driven by genomics research and forensic science.
Regulatory frameworks from bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA impose strict validation requirements on equipment used in diagnostics and pharmaceutical manufacturing. These standards directly influence instrument design and quality control protocols for consumables, ensuring data integrity for regulatory submissions. Stakeholders must now decide whether to invest in integrated, automated systems for high-throughput screening or continue relying on modular, standalone components for specialized research.
Market Dynamics
The central force shaping the market is the increasing complexity of biologic drugs, which necessitates more sophisticated and validated electrophoresis techniques to meet stringent quality control mandates from regulators like the FDA and EMA for protein characterization.
Growth Catalysts
- Capillary Electrophoresis Adoption:This technology's automation and high-throughput capabilities are driving its use in pharmaceutical quality control, where speed and reproducibility are critical for analyzing large batches of biologics.
- Genomics and Forensics Expansion:Sustained investment in genomics research and the consistent use of DNA fingerprinting in forensic science secure a large, stable demand base for agarose gel electrophoresis equipment and supplies.
- Stringent Regulatory Mandates:Quality control standards from the EMA and FDA for therapeutic proteins and monoclonal antibodies compel laboratories to invest in advanced, validated electrophoresis systems to ensure data integrity for submissions.
Market Restraints
- High Capital Investment:The significant upfront cost of fully automated capillary electrophoresis and 2D electrophoresis systems presents a substantial barrier for smaller academic laboratories and startups with limited budgets.
- Technical Limitations of Gels:The manual preparation of polyacrylamide gels is time-consuming and exposes technicians to neurotoxic acrylamide, while agarose gels offer limited resolution for small protein fragments.
- Threat from Alternative Technologies:For certain protein identification and quantification tasks, techniques like liquid chromatography-mass spectrometry (LC-MS) offer higher sensitivity and specificity, posing a substitution risk in well-funded research settings.
Strategic Opportunities
- Point-of-Care Diagnostics:Miniaturization of electrophoresis technology into microfluidic chips opens opportunities for developing rapid, portable diagnostic tests for infectious diseases and genetic screening outside of traditional lab settings.
- Emerging Biotech Hubs:Expanding government and private investment in the biotechnology sectors of countries like Brazil and South Korea creates new geographic markets for equipment and consumable sales.
- AI-Powered Data Analysis:Integrating artificial intelligence and machine learning algorithms with electrophoresis software offers a path to automate gel image analysis, pattern recognition, and data interpretation, reducing manual error.
Industry Challenges
- Specialized Skills Gap:A shortage of technicians proficient in advanced techniques, particularly in troubleshooting complex 2D electrophoresis separations and interpreting capillary electropherograms, limits the operational efficiency of advanced systems.
- Protocol Standardization Deficit:A lack of universally accepted standards for reagents, gel formulations, and running conditions across different vendor platforms leads to data variability, complicating inter-laboratory study comparisons.
- LIMS Integration Complexity:Integrating new, automated electrophoresis platforms with a facility's existing Laboratory Information Management System (LIMS) can be complex and costly, creating implementation delays and data flow bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrophoresis Equipment and Supplies Market |
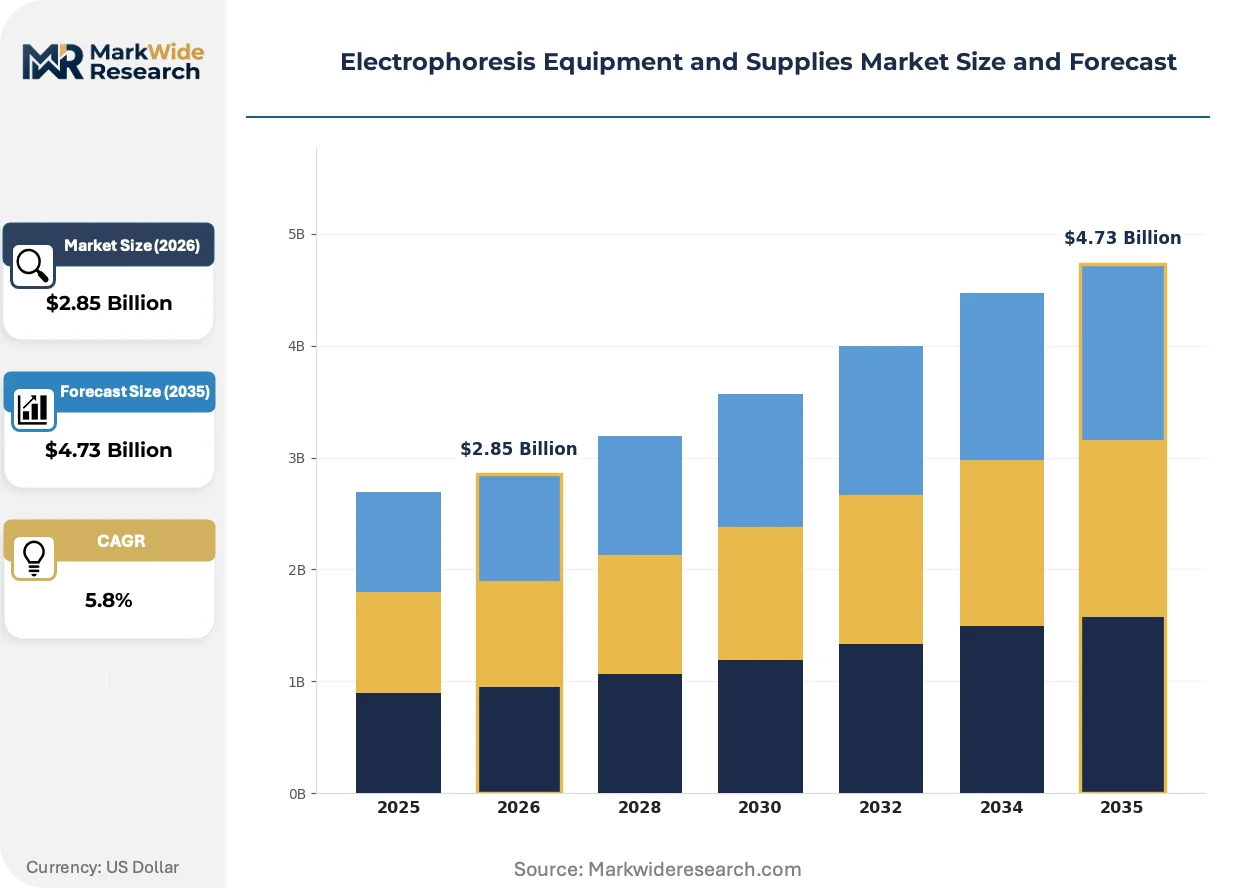
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.73 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Gel Systems, Vertical Gel Systems, Power Supplies, Electrophoresis Chambers, Accessories Technology: Agarose Gel Electrophoresis, Polyacrylamide Gel Electrophoresis, Capillary Electrophoresis, Pulsed Field Electrophoresis, Microfluidic Electrophoresis Application: DNA Analysis, Protein Separation, RNA Studies, Forensic Labs, Quality Control Testing End User: Research Institutes, Biotechnology Firms, Educational Institutions, Pharmaceutical Developers, Environmental Testing Labs |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Danaher Corporation, Agilent Technologies, GE HealthCare Technologies, Merck KGaA, PerkinElmer, QIAGEN, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrophoresis Equipment and Supplies Market Strategic Shifts & Innovations
A fundamental shift toward automation and data-centric workflows defines the current evolution of electrophoresis. This transition is driven by the need for higher throughput, improved reproducibility, and seamless regulatory compliance in analytical laboratories across pharmaceutical and research sectors.
Microfluidic chip-based electrophoresis integrates sample preparation and separation onto a single, disposable device. Pharmaceutical quality control labs and clinical diagnostics developers are adopting this format for its speed and minimal sample volume requirements. This miniaturized technology is hybridizing traditional manual techniques with automated lab-on-a-chip capabilities, enabling new workflows for high-throughput screening and potential point-of-care applications.
The push for data integrity under frameworks like the FDA's 21 CFR Part 11 and the EMA's Annex 11 is a significant regulatory driver. This forces manufacturers to embed secure audit trails, electronic signatures, and controlled user access directly into instrument software. Pharmaceutical manufacturing and clinical diagnostic laboratories are most affected, prioritizing systems with built-in compliance features to ensure data is secure and traceable for regulatory filings.
A move away from one-time capital equipment purchases toward reagent rental agreements and subscription-based consumable models is gaining traction. This business model alters the traditional sales process, benefiting suppliers who can provide guaranteed supply chain stability and ongoing technical support. The shift is most pronounced within large contract research organizations and academic consortia in the United States and Germany seeking to manage operational budgets more predictably.
Electrophoresis Equipment and Supplies Market Segmentation
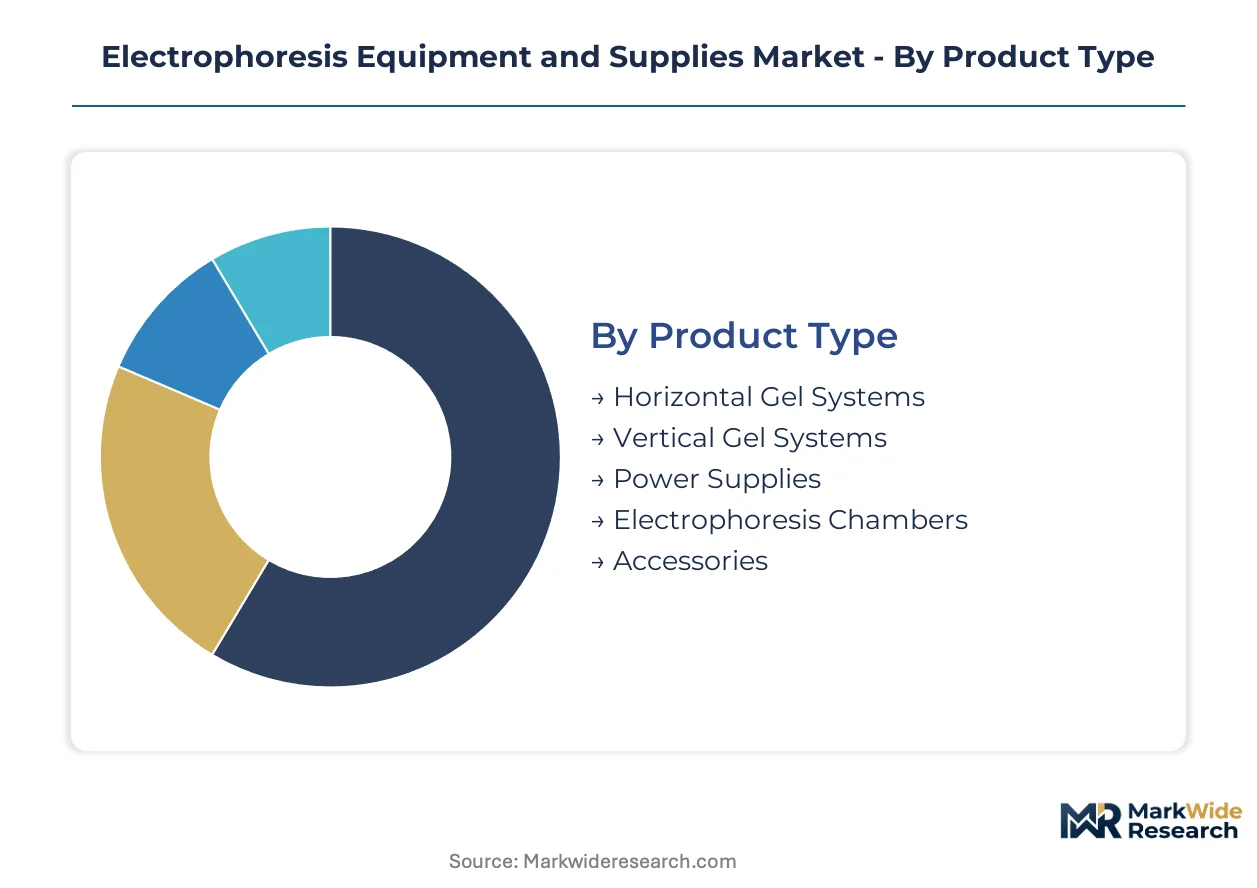
The Electrophoresis Equipment and Supplies market segments reveal distinct procurement patterns and technological preferences across various laboratory settings. Understanding these divisions helps stakeholders tailor product development and distribution strategies. Each segment reflects unique operational requirements and regulatory compliance demands.
Product Type:
The turnover rates for electrophoresis products vary significantly, with consumables like accessories experiencing rapid replenishment cycles, while core equipment such as power supplies have longer replacement schedules.
- Horizontal Gel Systems:These systems are widely used for DNA and RNA separation, featuring a gel cast horizontally and submerged in buffer. Demand concentrates in genomics research laboratories and academic institutions for routine DNA analysis.
- Vertical Gel Systems:Designed primarily for protein separation, these systems hold the gel vertically between two plates. Pharmaceutical development and proteomics research drive consistent demand for high-resolution protein characterization.
- Power Supplies:Essential for generating the electric field, these units provide controlled voltage and current to drive electrophoretic separation. Their longevity means procurement focuses on reliability and advanced safety features for long-term laboratory operation.
- Electrophoresis Chambers:These enclosures house the gel and buffer during the separation process, ensuring a stable environment. Research and quality control applications require robust chambers for consistent performance.
- Accessories:This segment includes combs, spacers, gel casting trays, and electrodes, which are frequently replaced items. Rapid consumption in high-throughput research facilities and diagnostic labs drives this segment.
Accessories anchor the volume base while Power Supplies gain share at the steepest rate due to increasing demand for automated systems.
Technology:
Cost efficiency and throughput capabilities differentiate electrophoresis technologies, influencing adoption rates across diverse research and industrial applications.
- Capillary Electrophoresis:This automated technique separates molecules within a narrow capillary, offering high resolution and rapid analysis. Pharmaceutical quality control and clinical diagnostics increasingly adopt this technology for its precision.
- Agarose Gel Electrophoresis:A fundamental technique for separating DNA and RNA based on size, it uses agarose as the gel matrix. Genomics research and forensic science laboratories represent the largest user base for this established method.
- Polyacrylamide Gel Electrophoresis:Employed primarily for protein separation and small nucleic acids, this method uses polyacrylamide gels for superior resolution. Proteomics studies and vaccine development rely on its fine separation capabilities.
- Pulsed Field Electrophoresis:This specialized technique separates very large DNA molecules (megabase pairs) by periodically changing the electric field direction. Advanced genomics and microbial typing laboratories utilize this method for complex genome analysis.
- Microfluidic Electrophoresis:Integrating separation onto microchips, this technology enables rapid analysis with minimal sample and reagent volumes. Point-of-care diagnostics and miniaturized analytical systems are key areas of development.
Agarose Gel Electrophoresis holds the largest market share, while Microfluidic Electrophoresis shows the most rapid expansion.
Application:
Electrophoresis applications range from fundamental biological research to stringent quality control, each demanding specific instrument capabilities and consumable properties.
- DNA Analysis:This segment involves separating and analyzing DNA fragments for genotyping, sequencing, and genetic diagnostics. Genomics research and forensic laboratories are primary users, driving substantial demand.
- Protein Separation:Critical for proteomics, drug discovery, and antibody characterization, this application separates proteins based on size, charge, or both. Pharmaceutical companies and biotechnology firms require high-resolution systems for this purpose.
- RNA Studies:Used for analyzing RNA integrity, quantification, and gene expression, this application is vital in molecular biology research. Academic research institutions and gene therapy developers frequently employ RNA electrophoresis.
- Forensic Labs:Electrophoresis is indispensable for DNA fingerprinting, paternity testing, and crime scene investigation in forensic science. Law enforcement agencies and specialized forensic centers maintain consistent demand for robust systems.
- Quality Control Testing:This application ensures the purity and integrity of biopharmaceuticals, vaccines, and other biological products. Pharmaceutical manufacturers and contract research organizations use validated systems for regulatory compliance.
DNA Analysis generates the largest market volume, with Quality Control Testing exhibiting the steepest growth trajectory.
End User:
The varied operational scales and funding structures of end-user segments significantly influence procurement decisions for electrophoresis equipment and supplies.
- Research Institutes:These institutions, including universities and government laboratories, conduct fundamental and applied biological research. Their procurement is often driven by grant funding and the need for versatile, high-performance systems.
- Biotechnology Firms:Focused on developing new biological products and technologies, these companies require advanced electrophoresis systems for R&D and product validation. Innovation and high-throughput capabilities are critical for their operations.
- Educational Institutions:Colleges and universities use electrophoresis equipment for teaching practical molecular biology and biochemistry. Affordability and ease of use are important factors for these educational settings.
- Pharmaceutical Developers:Companies engaged in drug discovery, development, and manufacturing rely on electrophoresis for protein characterization, quality control, and regulatory submissions. Validated, automated systems are paramount for these users.
- Environmental Testing Labs:These laboratories use electrophoresis for detecting and analyzing pollutants, microorganisms, and genetic material in environmental samples. Robust and reliable systems are necessary for accurate environmental monitoring.
Research Institutes constitute the largest end-user segment, while Pharmaceutical Developers are expanding their adoption most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US FDA's stringent quality control mandates drive significant demand for advanced electrophoresis systems across North America. These regulations ensure data integrity for biopharmaceutical submissions, influencing procurement decisions. This market's regional dynamics reflect diverse regulatory landscapes and research priorities.
United States
Genomics research and biopharmaceutical development create consistent demand for electrophoresis equipment in the United States. FDA mandates for therapeutic protein characterization compel investment in validated systems. The Boston-Cambridge biotech hub continues to drive innovation in high-throughput analytical solutions.
Germany
Academic proteomics and pharmaceutical R&D are significant demand drivers for advanced electrophoresis technologies in Germany. EMA guidelines for biologics quality control shape instrument design and validation requirements. Munich's biotech corridor actively supports the adoption of automated capillary electrophoresis systems.
China
Expanding biotechnology sectors and forensic science applications fuel the market for electrophoresis supplies in China. NMPA validation requirements for diagnostic instruments influence local manufacturing standards. Shanghai's biomedical parks foster new applications and local production capabilities.
Japan
Advanced genomics studies and vaccine development projects sustain the demand for high-resolution electrophoresis in Japan. PMDA standards for pharmaceutical manufacturing impact the adoption of compliant analytical platforms. Tokyo's research institutions lead the way in protein analysis techniques.
United Kingdom
Academic research institutions and contract research organizations represent steady demand for versatile electrophoresis systems in the United Kingdom. EMA compliance for drug development continues to influence laboratory investment decisions. The Oxford-Cambridge arc serves as a hub for life science innovation and technology adoption.
Electrophoresis Equipment and Supplies Market Key Industry Players
Specialized technology providers and broad-portfolio suppliers split the electrophoresis equipment and supplies market. The industry structure shows a mix of established players offering comprehensive solutions and niche innovators focusing on specific analytical challenges. Strategic partnerships and targeted portfolio diversification are dominant competitive moves.
Within the broad-portfolio supplier archetype, Thermo Fisher Scientific and Danaher Corporation exemplify companies leveraging extensive distribution networks and diverse product offerings. Bio-Rad Laboratories, Inc. occupies a position among specialists known for strong academic relationships and focused product lines. Agilent Technologies, Inc. represents firms emphasizing integrated workflow solutions that bundle equipment and consumables for specific applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Agilent Technologies |
| GE HealthCare Technologies |
| Merck KGaA |
| PerkinElmer |
| QIAGEN |
| Lonza Group |
| Others |
Cost & Logistics Intelligence
Munich's biotech corridor, with its specialized manufacturing capabilities, significantly influences the pricing power for advanced electrophoresis systems. This concentration of expertise and production capacity drives the cost structure for high-end instruments, impacting global market accessibility.
Pricing Analysis
Geographic price spreads exist, with validated systems costing more in regions with stringent regulatory oversight like the US and Europe. A hybrid pricing model prevails, combining capital equipment purchases for instruments with subscription-based reagent rental agreements for consumables. Price differentiation stems from after-sales service bundles and regulatory compliance certifications, such as FDA validation. Pricing pressure is intensifying for commoditized agarose gels due to increased competition, while automated capillary electrophoresis systems command premium pricing due to integrated software and specialized R&D. Academic laboratories exhibit the highest price sensitivity, contrasting with pharmaceutical developers who prioritize validated system performance.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are increasingly offered by major vendors to manage procurement cycles for high-capital equipment. Geographic supply concentration primarily resides in the United States, Germany, and China, which host key manufacturing hubs for electrophoresis components. The supply chain relies heavily on specialized electronics for automated systems and high-purity gel matrices like agarose and polyacrylamide. Single-source vulnerability for advanced microfluidic chips represents a structural risk. Distribution runs through a dual model, leveraging direct-to-laboratory e-commerce platforms alongside specialized distributors for academic and research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption, driven by the rapid adoption of capillary electrophoresis and increasingly stringent regulatory mandates from bodies like the FDA and EMA for biopharmaceutical quality control.
For Market Incumbents: Harden existing direct-to-laboratory distribution channels by enhancing e-commerce platforms and technical support capabilities. Invest heavily in AI-powered data analysis software to differentiate automated electrophoresis systems, mitigating the threat from alternative technologies like LC-MS. Focus R&D on miniaturization and integration to address the specialized skills gap among technicians. Pursue certification investments for new regulatory standards, particularly for pharmaceutical manufacturing applications.
For New Entrants and Emerging Players: Point-of-care diagnostics leveraging microfluidic chips represents a penetrable entry point due to unmet demand for rapid, portable testing. Emerging biotech hubs in Brazil and South Korea offer new geographic markets for targeted expansion. Offer integrated workflow solutions that bundle microfluidic equipment with application-specific reagents, providing a compelling go-to-market angle for specialized research and clinical diagnostic developers.
For Investors and Strategic Acquirers: Long-term, this sits as a growth play because the increasing complexity of biologic drugs necessitates more sophisticated and validated electrophoresis techniques. Niche innovators specializing in microfluidics, AI-driven analytics, or advanced gel chemistry present attractive acquisition targets. The signal to watch is the accelerating adoption rates of automated capillary electrophoresis systems in pharmaceutical quality control laboratories, indicating a shift towards high-throughput, compliant solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-Powered Gel Analysis Software | Automates complex data interpretation, reducing manual error and improving throughput for research labs. |
| Platform Integration: Microfluidic Chip-Based Systems | Enables rapid, low-volume sample analysis, critical for point-of-care diagnostics development. |
| Strategic Partnership: Academic Research Institutions | Fosters early-stage technology adoption and provides valuable feedback for product development. |
| Geographic Expansion: Emerging Biotech Hubs | Captures new market share in regions with increasing investment in biotechnology infrastructure. |
| Certification Investment: FDA 21 CFR Part 11 Compliance | Ensures data integrity and traceability for pharmaceutical quality control and regulatory submissions. |
Research Approach
A standing panel of R&D scientists, pharmaceutical quality control managers, academic researchers, and procurement officers provided ongoing calibration for market assumptions. This primary qualitative data was combined with extensive secondary validation from sources including FDA filings, EMA submissions, scientific journals, and company financial reports. The analysis triangulated bottom-up data from individual product segments with top-down market sizing approaches.
Scenario-based modeling was employed to bracket potential market outcomes across the analysis window. The forecast framework segmented the market by product type, technology, application, end-user, and regional regulatory environment. Compound annual growth rates were derived from historical trends, projected technology adoption rates, and the anticipated impact of evolving regulatory requirements. Key industry-specific forecast inputs included the global biologics pipeline growth and R&D spending in genomics.
Practitioners should monitor new disruptive technologies, shifts in regulatory enforcement, or unforeseen global economic downturns for early signals of market deviation. Forecasts reflect assumptions documented through this rigorous process. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Middle East and Africa Laboratory Hoods and Enclosure Market
Laboratory Equipment
Albumin Analyzers Market
Laboratory Equipment
South Korea Pipette Tips Market
Laboratory Equipment
Asia Pacific Cell Counting Market
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
Beaker Market
Laboratory Equipment
Global Hematology Instruments and Reagents Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Blood Testing Equipment Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Laboratory Data Loggers Market
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Laboratory Furniture Market
Laboratory Equipment
Laboratory Temperature Control Units Market
Laboratory Equipment
Cuvettes Market