
 Life Sciences and Laboratory Equipment Market | 2026-2036
Life Sciences and Laboratory Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Life Sciences and Laboratory Equipment Market Intelligence
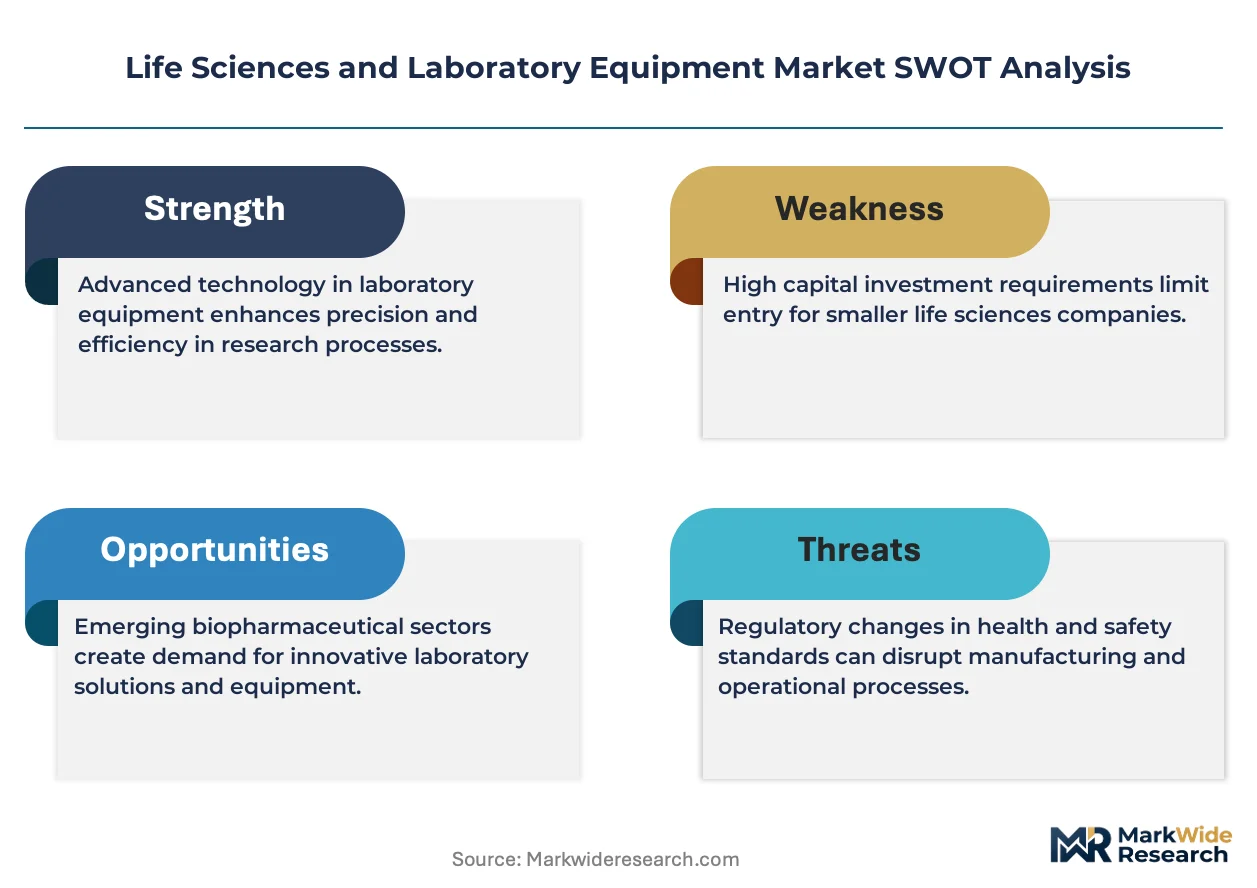
The long-standing reliance on academic centers for foundational research is unwinding as commercially-focused biotech firms and diagnostic labs increase their capital expenditures on advanced instrumentation. Thermo Fisher Scientific leverages its extensive portfolio to serve these emerging clients. Agilent Technologies specializes in analytical instruments for high-growth proteomics applications, while Danaher’s life sciences segment competes through a multi-brand strategy targeting specific workflows in drug discovery.
Life sciences and laboratory equipment comprises a range of instruments designed for scientific analysis, research, and quality control. These devices, including centrifuges, spectrophotometers, and incubators, operate with high precision to separate, identify, and quantify biological and chemical materials. Chromatography and mass spectrometry technologies command premium pricing and are integral to high-value drug discovery and proteomics applications. Conversely, foundational equipment like autoclaves represents a mature, volume-driven category serving academic and basic research institutes.
Regulatory frameworks, including the US FDA's 21 CFR Part 11 and Europe's Medical Device Regulation (MDR), dictate stringent instrument validation and data integrity protocols. Concurrently, standards from China's NMPA influence market access and product design for equipment used in its rapidly expanding clinical diagnostics sector. Navigating the convergence of these diverse data integrity requirements with increasing laboratory automation will define competitive success for equipment manufacturers.
Market Dynamics
The transition from academically-funded basic research to commercially-driven drug discovery and diagnostics is the central force shaping the market. This shift prioritizes high-throughput automation, data integrity, and workflow-specific instrumentation over general-purpose academic tools.
Growth Catalysts
- Accelerated Drug Discovery:Pharmaceutical investment in AI-powered drug discovery platforms accelerates research timelines, necessitating more advanced and higher-throughput analytical instruments to validate computational findings.
- Government Biotechnology Investment:Significant state-level funding in China's biotechnology sector creates concentrated demand for a full spectrum of laboratory equipment, from basic incubators to advanced mass spectrometers.
- Expansion of Proteomics:The growth of proteomics and multi-omics research for personalized medicine drives demand for premium-priced chromatography and mass spectrometry systems capable of complex protein analysis.
Market Restraints
- High Capital Costs:The substantial upfront investment required for advanced instruments like next-generation sequencers and mass spectrometers creates a significant barrier to adoption for smaller research labs and academic institutions.
- Data Integration Complexity:Integrating new, automated equipment with disparate legacy Laboratory Information Management Systems (LIMS) presents a major technical and financial hurdle, limiting the potential of fully automated workflows.
- Divergent Regulatory Standards:Instrument manufacturers face increased development costs and complexity in designing products that simultaneously comply with data integrity rules from the US FDA, Europe's MDR, and China's NMPA.
Strategic Opportunities
- Point-of-Care Instrumentation:The convergence of microfluidics with analytical technologies enables the development of miniaturized, portable instruments, opening opportunities in decentralized clinical testing and field-based environmental analysis.
- Cell and Gene Therapy Quality Control:The emergence of cell and gene therapy manufacturing creates a new market for specialized, GMP-compliant analytical instruments to ensure the quality, safety, and efficacy of these novel treatments.
- Southeast Asian Market Entry:As countries like Vietnam and Thailand expand their healthcare and research infrastructure, there is an opportunity to supply foundational and mid-range laboratory equipment to these underpenetrated markets.
Industry Challenges
- Specialized Talent Scarcity:A shortage of technicians skilled in operating and maintaining complex automated systems and interpreting the data from advanced analytical instruments constrains laboratory productivity and expansion.
- Instrument Validation Burden:The lengthy and rigorous process of validating new equipment to meet regulatory standards, such as Europe's MDR for diagnostic devices, delays product launches and increases R&D expenditures.
- Legacy System Interoperability:Ensuring new, data-intensive instruments can communicate seamlessly with a lab's existing informatics infrastructure remains a persistent operational challenge, hindering the realization of fully connected lab environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Life Sciences and Laboratory Equipment Market |
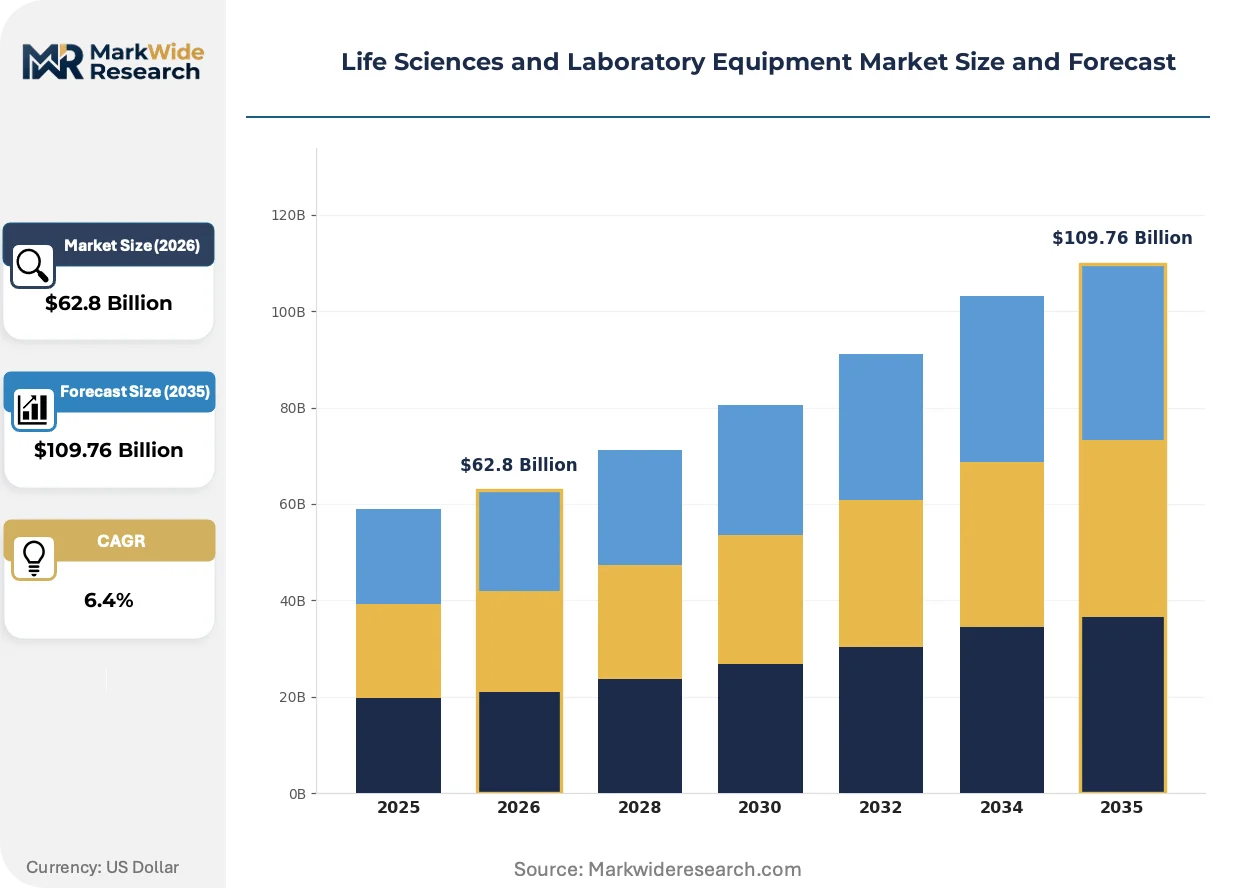
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $109.76 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microscopes, Centrifuges, Spectrophotometers, Autoclaves, Incubators Technology: PCR, Flow Cytometry, Mass Spectrometry, Chromatography, Electrophoresis Application: Genomics, Proteomics, Drug Discovery, Clinical Diagnostics, Environmental Analysis End User: Research Institutes, Biotech Firms, Diagnostic Labs, Academic Centers, Pharmaceutical Companies |
| Companies Covered | Shimadzu, Waters Corporation, Thermo Fisher Scientific, PerkinElmer, Bruker, Danaher, Roche, Bio-Rad Laboratories, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Life Sciences and Laboratory Equipment Market Strategic Shifts & Innovations
The market's evolution is defined by the dual pressures of increasing automation and stringent data integrity mandates. These forces are fundamentally changing instrument design, laboratory workflows, and the economic models for equipment acquisition and maintenance.
Single-cell analysis technologies provide high-resolution data on individual cells, a departure from traditional bulk-sample methods. Oncology and immunology research labs are rapidly adopting these systems to study cellular heterogeneity in complex diseases. The adoption of this technology is fragmenting the conventional tissue analysis market, creating a distinct, high-value segment for specialized instruments.
Europe's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance on equipment classified as in-vitro diagnostic (IVD) devices. This forces manufacturers of clinical analyzers to undertake more extensive validation and update their quality management systems. The IVD instrument segment is most affected, facing longer development cycles and higher compliance costs.
A shift toward subscription and reagent rental agreements for high-value instrumentation is altering procurement patterns. This model displaces the traditional one-time capital equipment purchase, allowing labs to access advanced technology with lower upfront investment. This trend is most visible among start-up biotechnology firms in North America and Europe that need to conserve capital for research activities.
Life Sciences and Laboratory Equipment Market Segmentation
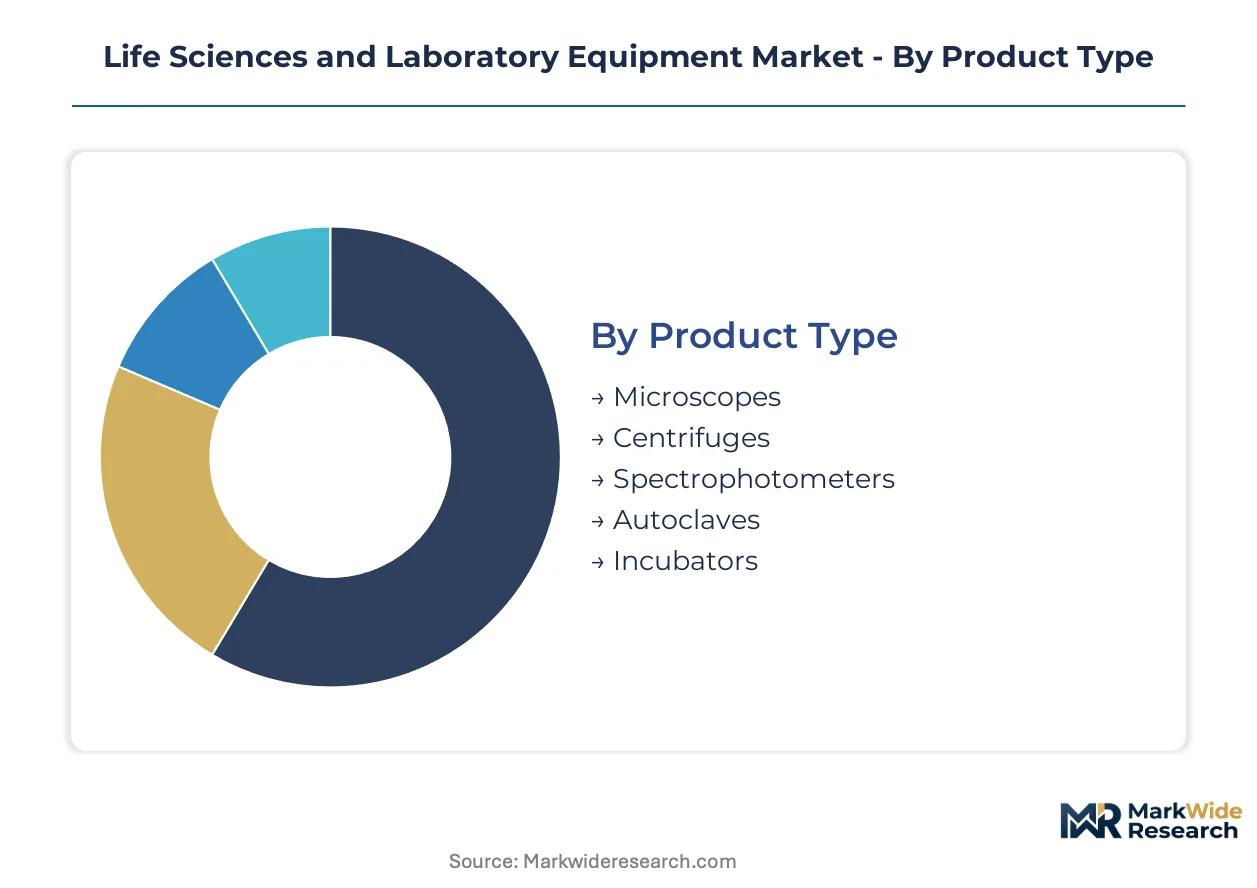
Market segmentation for life sciences and laboratory equipment reveals distinct procurement patterns and technological demands across various user groups. Understanding these segments enables manufacturers to tailor product development and distribution strategies. Each category reflects unique operational requirements and investment priorities within the scientific community.
Product Type:
The distribution channels for laboratory equipment vary significantly by product type, with some segments flowing through specialized scientific suppliers and others via broader catalog vendors.
- Microscopes:These instruments encompass optical, electron, and confocal systems used for visualizing cellular structures and microorganisms at high resolution. Demand concentrates in advanced cellular biology labs and academic research centers across Europe, driven by fundamental discovery and disease mechanism elucidation.
- Spectrophotometers:These devices accurately measure light absorption or transmission through a sample, providing quantitative analysis of chemical or biological concentrations. Pharmaceutical companies and diagnostic labs in North America drive demand, leveraging them for quality control, assay development, and drug compound characterization.
- Centrifuges:Centrifuges separate components of liquid mixtures by density through rapid rotation, essential for sample preparation in clinical diagnostics and molecular biology labs.
- Autoclaves:Autoclaves sterilize laboratory equipment, glassware, and media using high-pressure saturated steam, serving as a critical foundational tool for maintaining aseptic conditions in research and clinical settings.
- Incubators:Incubators maintain optimal temperature, humidity, and CO2 levels for cell culture and microbial growth, widely utilized across life science research and biotechnology for controlled experimentation.
By volume, Autoclaves lead the product type segment. By growth pace, Microscopes are ahead.
Technology:
Different technologies cater to specific research applications and analytical challenges, influencing instrument design and adoption rates across various scientific disciplines.
- Mass Spectrometry:This technology identifies and quantifies molecules by measuring their mass-to-charge ratio, offering high sensitivity and specificity for complex sample analysis. Proteomics and metabolomics research in the US and Germany drives demand, critical for biomarker discovery and personalized medicine development.
- Chromatography:Chromatography encompasses techniques like HPLC and GC that separate complex mixtures into individual components based on differential partitioning between stationary and mobile phases. Pharmaceutical R&D and quality control in Japan and Switzerland rely on this technology, vital for drug purity assessment and formulation analysis.
- PCR:Polymerase Chain Reaction (PCR) amplifies specific DNA sequences exponentially, forming a cornerstone technology for molecular diagnostics, gene expression analysis, and genetic research.
- Flow Cytometry:Flow cytometry analyzes and sorts individual cells or particles based on light scattering and fluorescence properties, essential for immunology, hematology, and cancer research.
- Electrophoresis:Electrophoresis separates macromolecules such as DNA, RNA, and proteins by size and electrical charge using an electric field, fundamental for molecular biology and biochemical analysis.
Mass Spectrometry commands premium pricing due to its advanced capabilities. PCR offers broad utility across diverse research and diagnostic settings.
Application:
The specific end-user type often dictates the required instrumentation, with distinct needs for research, diagnostics, or environmental monitoring driving equipment specifications.
- Drug Discovery:This application involves the entire process from target identification and lead compound screening to preclinical testing of new therapeutic compounds. Large pharmaceutical companies and contract research organizations globally drive demand, focused on accelerating time-to-market for novel medicines.
- Clinical Diagnostics:Clinical diagnostics utilizes laboratory tests to detect, diagnose, monitor, and manage diseases in patient samples, requiring high-throughput and reliable instrumentation. Hospital labs and reference laboratories in China and India drive this segment, propelled by expanding healthcare access and disease surveillance programs.
- Genomics:Genomics focuses on the structure, function, evolution, and mapping of genomes, supporting personalized medicine initiatives and understanding genetic predispositions to diseases.
- Proteomics:Proteomics studies the entire set of proteins expressed by an organism or cell type, critical for understanding disease mechanisms, identifying drug targets, and developing biomarkers.
- Environmental Analysis:Environmental analysis utilizes laboratory equipment to monitor pollutants, characterize environmental samples, and assess ecosystem health, supporting regulatory compliance and ecological studies.
Drug Discovery applications drive demand for high-throughput automation. Clinical Diagnostics requires stringent regulatory compliance for instrument validation.
End User:
The volume of equipment procurement and the sophistication of instruments purchased vary significantly across different end-user segments within the life sciences market.
- Biotech Firms:These agile, often venture-backed companies develop novel therapeutics, diagnostics, or research tools, characterized by rapid innovation cycles. Demand for capital-intensive, cutting-edge instruments concentrates in biotech clusters like Boston and the San Francisco Bay Area, fueling rapid scientific advancement.
- Pharmaceutical Companies:Large, established corporations engaged in comprehensive drug development, manufacturing, and commercialization represent a significant end-user segment. Demand for advanced analytical systems for R&D and quality control in Germany and the US ensures product safety, efficacy, and regulatory adherence.
- Research Institutes:Research institutes, including government-funded and private centers, conduct foundational and applied scientific investigations, requiring a broad spectrum of laboratory equipment for diverse projects.
- Diagnostic Labs:Diagnostic labs provide clinical testing services for disease diagnosis, prognosis, and patient monitoring, necessitating high-throughput, reliable, and often automated instrumentation.
- Academic Centers:Universities and colleges focus on education and basic scientific research, representing a foundational market for versatile, robust, and often general-purpose laboratory equipment.
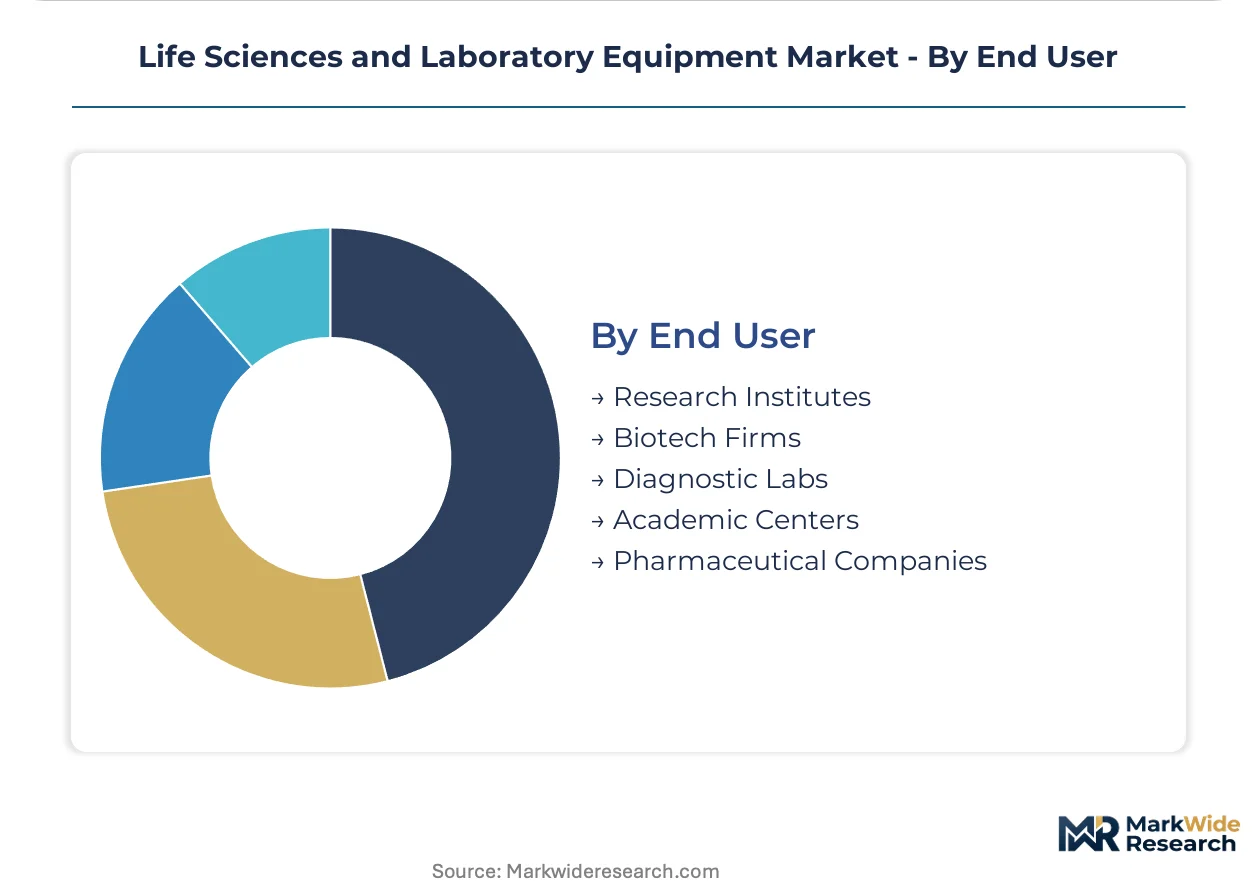
Biotech Firms prioritize cutting-edge technology for rapid innovation. Academic Centers represent a foundational market for general-purpose equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment from Germany often flows into research centers across the United States, supporting advanced analytical needs. This global market sees instruments from Japan and the US reaching burgeoning biotech hubs in China and India. Specialized laboratory tools facilitate scientific advancements worldwide.
United States
Accelerated drug discovery programs and expanding proteomics research drive significant demand for advanced laboratory equipment in the United States. The US FDA's 21 CFR Part 11 mandates stringent data integrity protocols, influencing instrument design and validation. Boston's biotech cluster drives innovation, with numerous firms investing heavily in cutting-edge analytical instrumentation for novel therapeutic development.
China
Government investment in biotechnology and an expanding clinical diagnostics sector fuel substantial demand for laboratory equipment across China. China's NMPA influences market access and product design, setting standards for medical devices and diagnostics. Shanghai's Zhangjiang Hi-Tech Park concentrates numerous biotech companies and research institutes, driving concentrated demand for advanced instrumentation.
Germany
Pharmaceutical research and development, alongside advanced proteomics applications, underpin robust demand for laboratory equipment in Germany. Europe's Medical Device Regulation (MDR) imposes stricter requirements for IVD devices, necessitating extensive validation. Munich's life sciences ecosystem, including various Fraunhofer Institutes, actively procures high-precision analytical instruments for diverse research projects.
Japan
Japanese pharmaceutical R&D and stringent quality control for drug purity assessment drive consistent demand for advanced laboratory equipment. PMDA regulations guide the development and approval of medical devices and in-vitro diagnostics, influencing instrument design. The Tokyo metropolitan area houses major pharmaceutical companies and research institutions, focusing on high-value chromatography and mass spectrometry systems.
India
Expanding clinical diagnostics and a growing pharmaceutical manufacturing sector generate substantial demand for laboratory equipment across India. CDSCO guidelines govern the import, manufacture, and sale of medical devices, influencing product specifications. Hyderabad's Genome Valley fosters numerous biotech and pharma companies, increasing procurement of essential lab tools for research and quality control.
Life Sciences and Laboratory Equipment Market Key Industry Players
Listed leaders compete with private specialists across analytical instrumentation and workflow solutions within the life sciences market. The industry exhibits a tiered structure, with global conglomerates offering broad portfolios alongside niche players specializing in specific technologies. Strategic archetypes include diversified instrument providers, specialized analytical technology firms, and integrated workflow solution suppliers. Companies often engage in portfolio diversification and strategic partnerships to expand their market reach.
Within the diversified instrument provider archetype, Thermo Fisher Scientific and Danaher exemplify broad market coverage, offering extensive portfolios across various life science applications. Agilent Technologies, a prominent US-based corporation, sits within the specialized analytical technology segment, focusing on advanced analytical instruments for high-growth proteomics. These companies anchor significant portions of the market, serving both large pharmaceutical enterprises and emerging biotechnology firms. Their strategic positioning allows them to address complex research and diagnostic needs across multiple geographies.
| Leading Market Players |
|---|
| Shimadzu |
| Waters Corporation |
| Thermo Fisher Scientific |
| PerkinElmer |
| Bruker |
| Danaher |
| Roche |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Others |
Cost & Logistics Intelligence
Extended instrument lead times for advanced analytical systems directly influence pricing power for manufacturers, particularly for high-value components with concentrated supply chains. This dynamic shapes procurement patterns across the life sciences and laboratory equipment market.
Pricing Analysis
A significant technology-generation pricing gap exists between cutting-edge mass spectrometers and foundational centrifuges, reflecting their distinct R&D investments and performance capabilities. The dominant pricing structure is a hybrid, combining one-time capital equipment purchases with recurring subscription and reagent rental agreements, especially for high-throughput systems. Price differentiation stems from precision specifications and regulatory compliance certifications, such as those mandated by the US FDA or Europe's MDR. Pricing pressure intensifies for mature, volume-driven equipment due to commoditization and broader market competition. Academic centers typically exhibit the highest price sensitivity, contrasting with biotech firms prioritizing cutting-edge performance.
Supply Chain Analysis
Just-in-time inventory strategies are common for high-volume consumables, while strategic stockpiles protect against disruptions for specialized components. Geographic supply concentration for precision optical components often resides in Germany and Japan, while basic labware and some electronic assemblies are frequently sourced from China. The market relies heavily on specialized polymers and diagnostic reagents as critical raw material dependencies. Single-source vulnerability for highly specialized sensors represents a persistent structural risk. Distribution runs through a mix of specialized scientific distributors and direct sales channels, particularly for complex, high-value instrumentation requiring extensive technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is currently in an early-cycle expansion phase, primarily driven by accelerated drug discovery programs and the increasing adoption of personalized medicine approaches.
For Market Incumbents:
Compound existing R&D investments in AI-powered analytical platforms to outpace emerging AI-driven computational biology firms. Integrate vertical capabilities into data analytics platforms to offer comprehensive workflow solutions, mitigating the threat of fragmented data integration. Secure long-term supply agreements for critical components sourced from specialized manufacturers to buffer against supply chain volatility. Pursue strategic acquisitions of niche technology providers to broaden portfolio depth in high-growth areas like single-cell analysis.
For New Entrants and Emerging Players:
Certification fast-track pathways for novel diagnostic devices, leveraging microfluidics, offer a significant white-space opportunity in decentralized testing. Target underpenetrated Southeast Asian markets with foundational and mid-range laboratory equipment, where healthcare infrastructure is expanding. Focus on developing user-friendly, workflow-specific instruments for specialized applications, such as cell and gene therapy quality control. A compelling go-to-market angle involves offering flexible subscription models and localized technical support to lower upfront adoption barriers for smaller labs.
For Investors and Strategic Acquirers:
Carve-out targets emerge from diversified conglomerates seeking to divest non-core life science segments, presenting opportunities for focused investment. The long-term viability of this market is anchored in the persistent demand from personalized medicine and multi-omics research over the next 5-10 years. Acquisition targets should prioritize niche analytical technology firms with strong intellectual property in areas like advanced proteomics or single-cell analysis. The signal to watch is the consolidation of Laboratory Information Management Systems (LIMS) providers, indicating a maturing market for integrated lab solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnerships | Forging alliances with AI firms integrates advanced computational capabilities into laboratory instruments for enhanced data analysis. |
| Geographic Expansion | Entering underpenetrated markets like Southeast Asia expands customer bases and establishes early market leadership. |
| R&D Investment | Developing next-generation single-cell analysis platforms addresses specific research needs in oncology and immunology. |
| Regulatory Compliance Programs | Ensuring adherence to evolving global standards like Europe's MDR and China's NMPA facilitates market access and product acceptance. |
| Subscription Model Development | Offering flexible access to high-value instrumentation reduces upfront capital expenditure for biotechnology start-ups and academic centers. |
Research Approach
Initial hypotheses were tested against primary input from research directors, lab managers, regulatory specialists, and procurement officers, and refined through iterative feedback. This approach combined in-depth interviews with a comprehensive review of secondary data sources to ensure robust market insights. Key secondary sources included FDA/NMPA/MDR guidelines, industry association reports, patent databases, and company financial filings. Bottom-up and top-down triangulation validated market sizing and segmentation across various data points.
Variance decomposition was applied to isolate the impact of key market drivers and restraints on overall market trajectory over the projection horizon. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional regulatory environment. Compound annual growth rates were derived from historical data trends and projected future demand scenarios. Key industry-specific forecast inputs included pharmaceutical R&D spending and government biotechnology investment across leading economies.
Decision-makers should treat outputs as directional under current regulatory stability and technological evolution; material deviation would warrant model refresh. Forecasts reflect assumptions regarding continued investment in drug discovery and diagnostics. Unforeseen geopolitical shifts or rapid disruptive technology adoption represent significant risk factors. Revision becomes warranted when major regulatory frameworks undergo fundamental restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Global Hematology Analyzers and Reagents Market
Laboratory Equipment
Micropipette Puller Market
Laboratory Equipment
Human Milk Analyzers Market
Laboratory Equipment
Beaker Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Laboratory Furnaces Market
Laboratory Equipment
Electronic Multichannel Pipettes Market
Laboratory Equipment
United States Pipette Tips Market
Laboratory Equipment
Laboratory Temperature Control Units Market
Laboratory Equipment
Capillary Blood Collection Tubes Market
Laboratory Equipment
Global Blood Gas Analyzers Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Global Slide Stainer Market
Laboratory Equipment
Global Blood Collection Tubes Market
Laboratory Equipment
Blood Processing and Storage Equipment Market
Laboratory Equipment
Hotplate Stirrers Market