
 Microdontia Treatment Market | 2026-2036
Microdontia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Microdontia Treatment Market Analytics
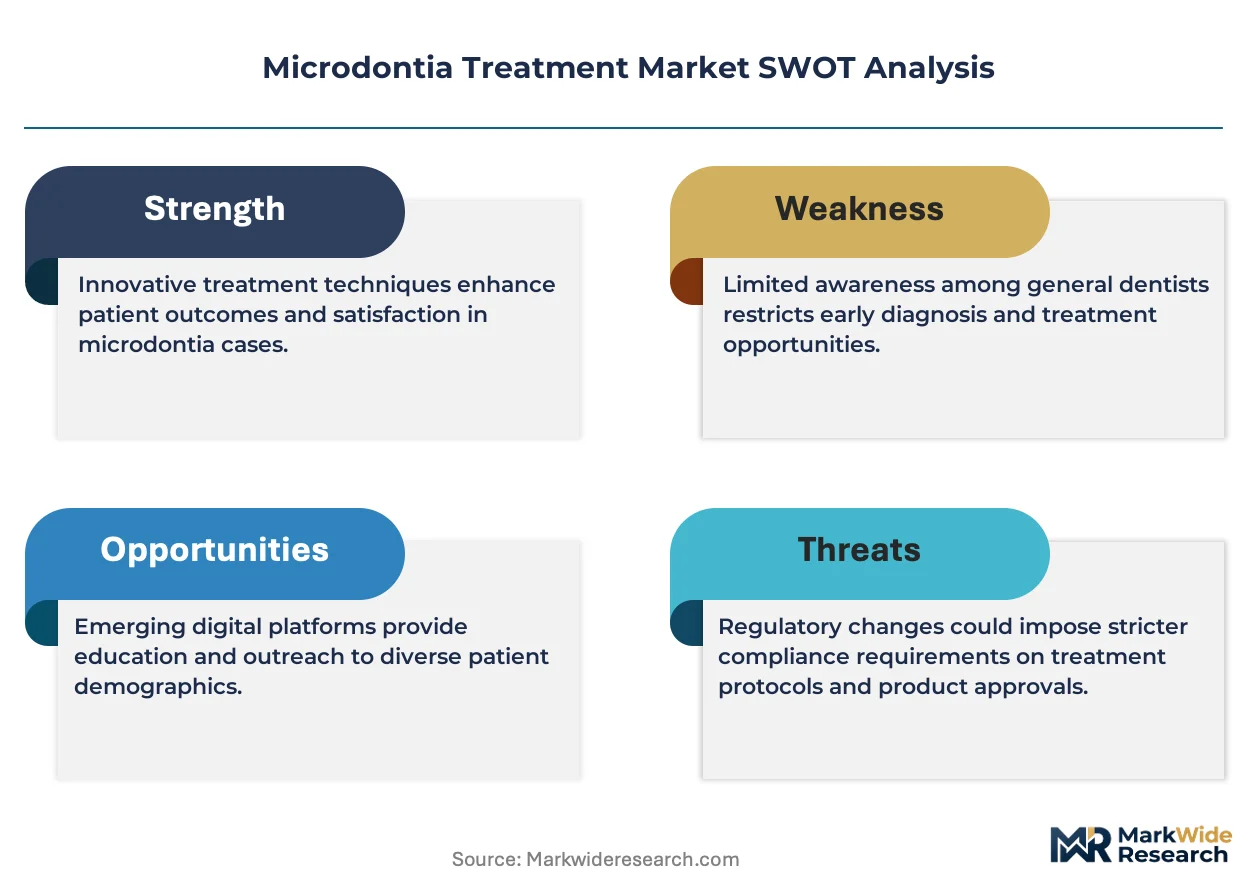
Digital intraoral scanning is narrowing the precision gap between traditional impressions and chairside restorative workflows. 3M Company leverages its materials science portfolio to sustain adhesive bonding leadership across pediatric and adult microdontia cases. Straumann anchors premium implant-abutment-crown integration for congenitally undersized teeth. Dentsply Sirona competes through vertical control of CAD/CAM milling hardware and sintering furnaces.
Microdontia treatment encompasses prosthetic and orthodontic interventions that restore function and aesthetics to teeth with dimensions below population norms, typically involving lithium disilicate or zirconia restorations fabricated via subtractive milling or additive manufacturing. Crowns and veneers dominate product type revenue as clinicians favor full-coverage solutions for severe size discrepancies, while bonding retains share in adolescent cases where tooth preservation matters. CAD/CAM technology leads the technology segment in margin contribution, though 3D printing captures the fastest growth in orthodontic aligner and surgical guide applications.
FDA 510(k) pathways govern restorative material biocompatibility and mechanical performance claims in the United States, while the EU MDR and CE marking requirements reshape market access for European manufacturers of custom dental devices. ISO 13485 quality management standards and HIPAA privacy rules further constrain how patient scan data flows through cloud-based treatment planning platforms. Stakeholders must weigh capital deployment between in-office digital fabrication networks and centralized production hubs as reimbursement rates for prosthodontic procedures compress.
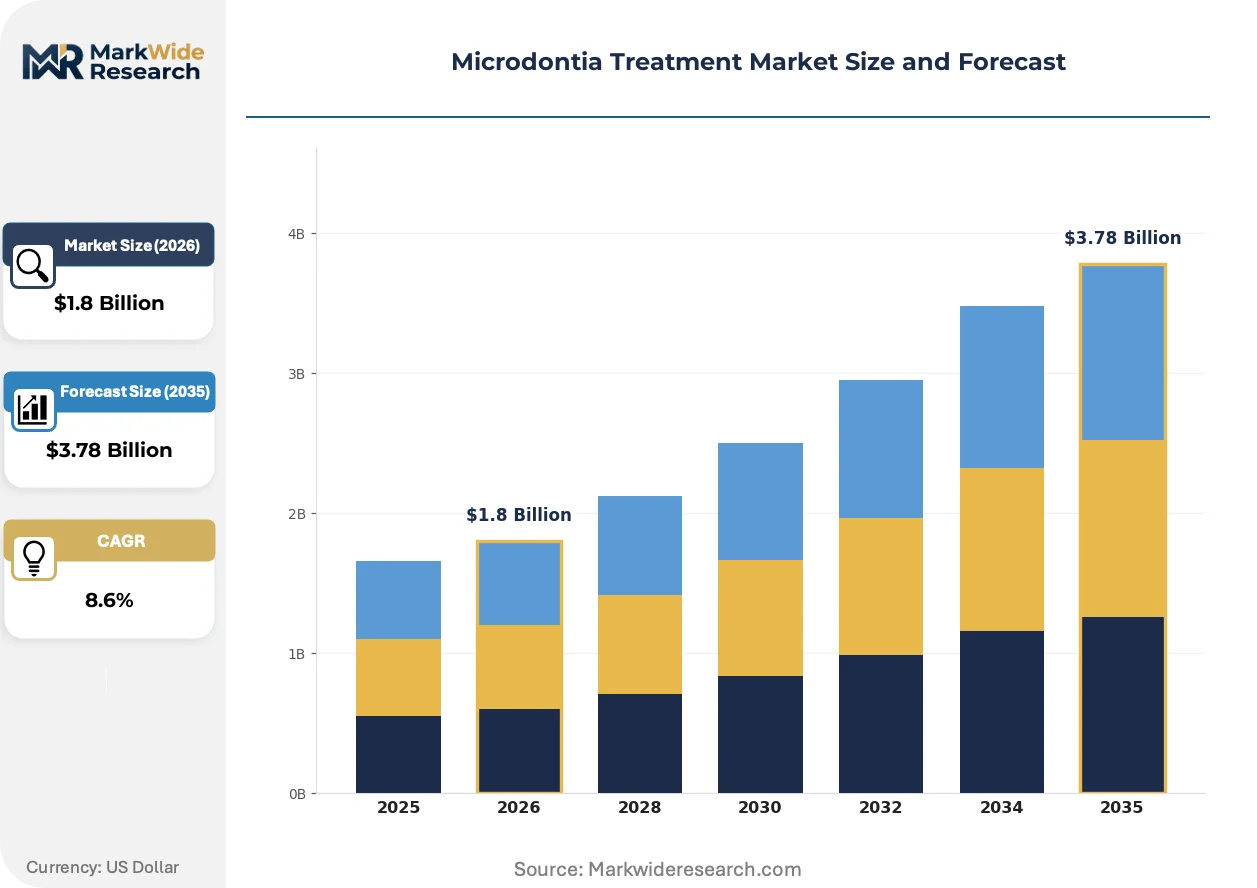
Market Dynamics
Chairside CAD/CAM fabrication is compressing treatment timelines from multi-week laboratory workflows to same-day procedures, forcing capital allocation decisions between in-office milling systems and centralized production networks.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance for 3D-printed biocompatible polymers accelerates restorative device commercialization timelines in the United States.
- Orthodontic specialist density:Concentrated practitioner networks in metropolitan clusters drive procedure volume and technology adoption velocity.
- Lithium disilicate material properties:Superior esthetics and fracture resistance expand indications from anterior veneers to posterior crowns.
Market Restraints
- Zirconia powder supply concentration:Sourcing dependency on limited high-purity ceramic feedstock suppliers creates input cost volatility.
- EU MDR compliance burden:Enhanced clinical evidence requirements for custom dental devices extend market access timelines for European manufacturers.
- Direct composite bonding substitution:Conservative tooth-preserving alternatives capture adolescent cases where enamel reduction is undesirable.
Strategic Opportunities
- Cloud-based treatment planning platforms:HIPAA-compliant data infrastructure enables remote specialist consultation and centralized design services.
- Additive manufacturing convergence:Integration of photopolymerization with intraoral scanning creates orthodontic aligner and surgical guide production capabilities.
- ISO 13485 certification differentiation:Quality management credentials unlock institutional procurement channels and group practice networks.
Industry Challenges
- CAD/CAM technician training deficits:Shortage of operators proficient in both digital design software and subtractive milling parameters constrains chairside utilization rates.
- Capital equipment depreciation cycles:Rapid hardware obsolescence pressures return-on-investment calculations for dental office technology investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microdontia Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crowns, Veneers, Bonding, Orthodontics Delivery Mode: In-Office, Home Care, Telehealth, Surgical End User: Pediatric Clinics, Dental Offices, Orthodontic Specialists, Research Institutions Technology: 3D Printing, CAD/CAM, Digital Imaging, Traditional Techniques |
| Companies Covered | 3M Company, Danaher Corporation, Patterson Dental, Carestream Health, Inc., Planmeca OY, Henry Schein, Straumann, Align Technology, Inc., Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microdontia Treatment Market Evolving Landscape
Digital intraoral scanning accuracy improvements are eliminating the precision gap with conventional elastomeric impressions while enabling entirely new fabrication workflows.
Photopolymer resin formulations optimized for biocompatibility and wear resistance are rendering obsolete the distinction between provisional and definitive restorations in select clinical applications. Multi-practice dental service organizations are adopting these materials at accelerating pace for same-day crown delivery. The compression of laboratory intermediation is redistributing margin capture toward chairside technology vendors.
EU MDR recast requirements for custom-made medical devices are imposing clinical evaluation obligations that reshape European competitive dynamics. Manufacturers must now maintain post-market surveillance systems and periodic safety update reports for patient-specific restorations. Smaller laboratories without regulatory affairs infrastructure are outsourcing compliance or exiting the market.
Consolidated procurement by dental service organizations is unbundling traditional supplier relationships and imposing price transparency requirements. Group purchasing organizations negotiate directly with material manufacturers, bypassing distributor markups. This concentration is most pronounced in the United States where practice aggregation has advanced furthest.
Microdontia Treatment Market Segmentation
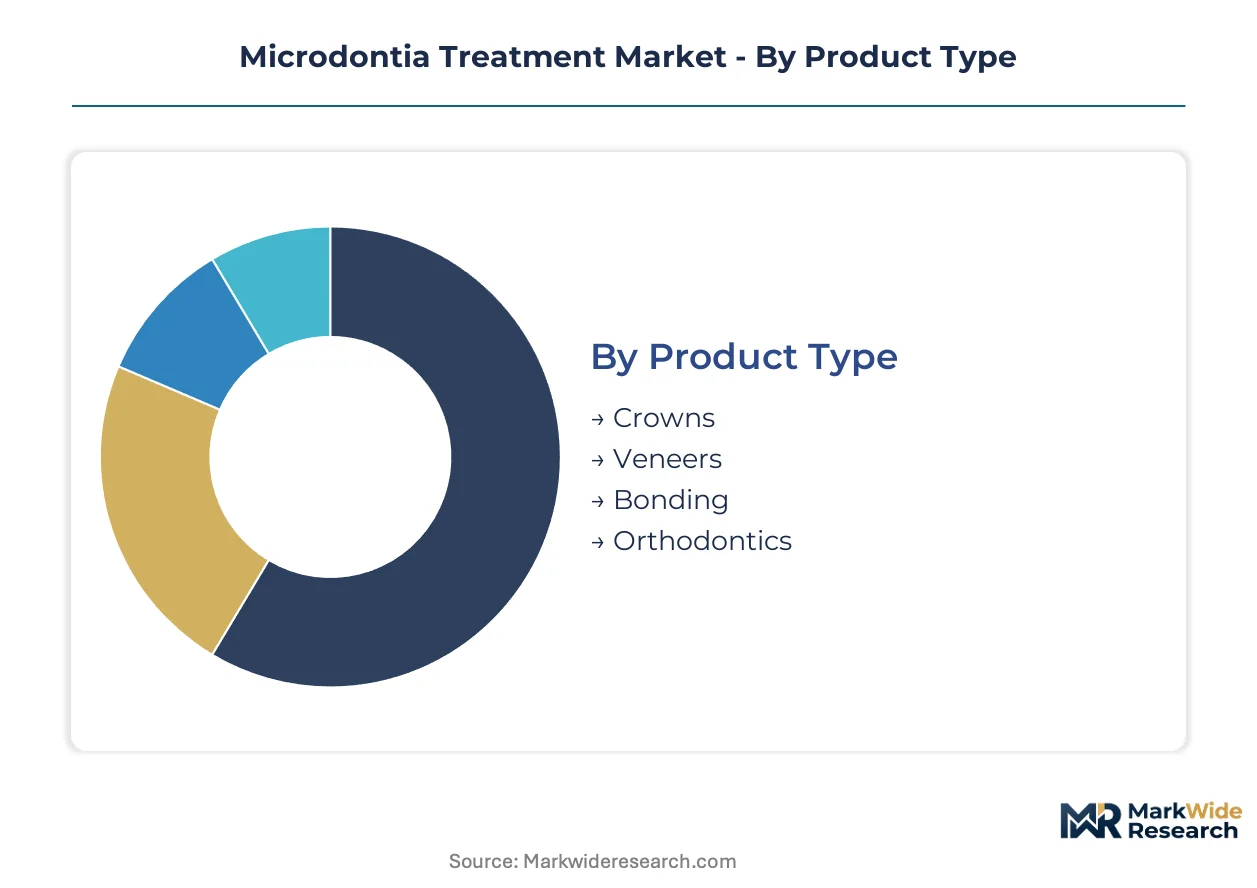
Microdontia treatment modalities fragment across restorative approaches, fabrication workflows, and care settings. Each segmentation axis reveals distinct margin structures, regulatory burdens, and technology substitution patterns that shape vendor positioning.
Product Type:
Mature full-coverage solutions coexist with emerging conservative alternatives as clinicians weigh durability against enamel preservation.
- Crowns:Lithium disilicate and zirconia full-coverage restorations address severe dimensional discrepancies where structural integrity is paramount. Demand concentrates among adult patients in the United States seeking definitive solutions for posterior microdontia, driven by insurance reimbursement for prosthodontic procedures.
- Veneers:Minimal-preparation ceramic laminates restore anterior aesthetics with conservative tooth reduction. Adoption accelerates in cosmetic-focused dental offices across metropolitan clusters where elective procedure penetration outpaces general practice benchmarks.
- Bonding:Direct composite resin applications preserve tooth structure in adolescent cases.
- Orthodontics:Clear aligner and fixed appliance therapies reposition teeth to compensate for size anomalies.
Crowns retain volume leadership; bonding holds the steepest expansion curve among pediatric populations.
Delivery Mode:
Cost tier stratification separates capital-intensive chairside fabrication from lower-touch remote and home-based alternatives.
- In-Office:Chairside CAD/CAM milling and 3D printing enable same-day crown delivery, eliminating laboratory intermediation. Deployment concentrates in dental service organization networks across the United States where capital pooling justifies hardware investment.
- Surgical:Implant-abutment-crown integration for congenitally missing or severely undersized teeth requires specialist-operatory infrastructure.
- Telehealth:Remote consultation and treatment planning platforms extend specialist reach into underserved geographies.
- Home Care:Retainer and aligner maintenance protocols support post-treatment stability.
In-office delivery captures the highest margin per procedure; telehealth is climbing the fastest as HIPAA-compliant infrastructure matures.
End User:
Customer type determines purchasing authority, with consolidated procurement reshaping traditional supplier relationships.
- Dental Offices:General practice settings represent the primary volume channel for restorative microdontia treatment, increasingly adopting chairside fabrication technology to compress treatment timelines.
- Orthodontic Specialists:Concentrated practitioner networks in metropolitan United States clusters drive aligner-based volume and technology adoption velocity.
- Pediatric Clinics:Conservative bonding and interceptive orthodontic protocols dominate this channel where enamel preservation guides clinical decision-making.
- Research Institutions:Academic medical centers generate clinical evidence and train next-generation practitioners on emerging techniques.
Dental offices dominate absolute procedure volume; orthodontic specialists demonstrate the steepest technology adoption trajectory.
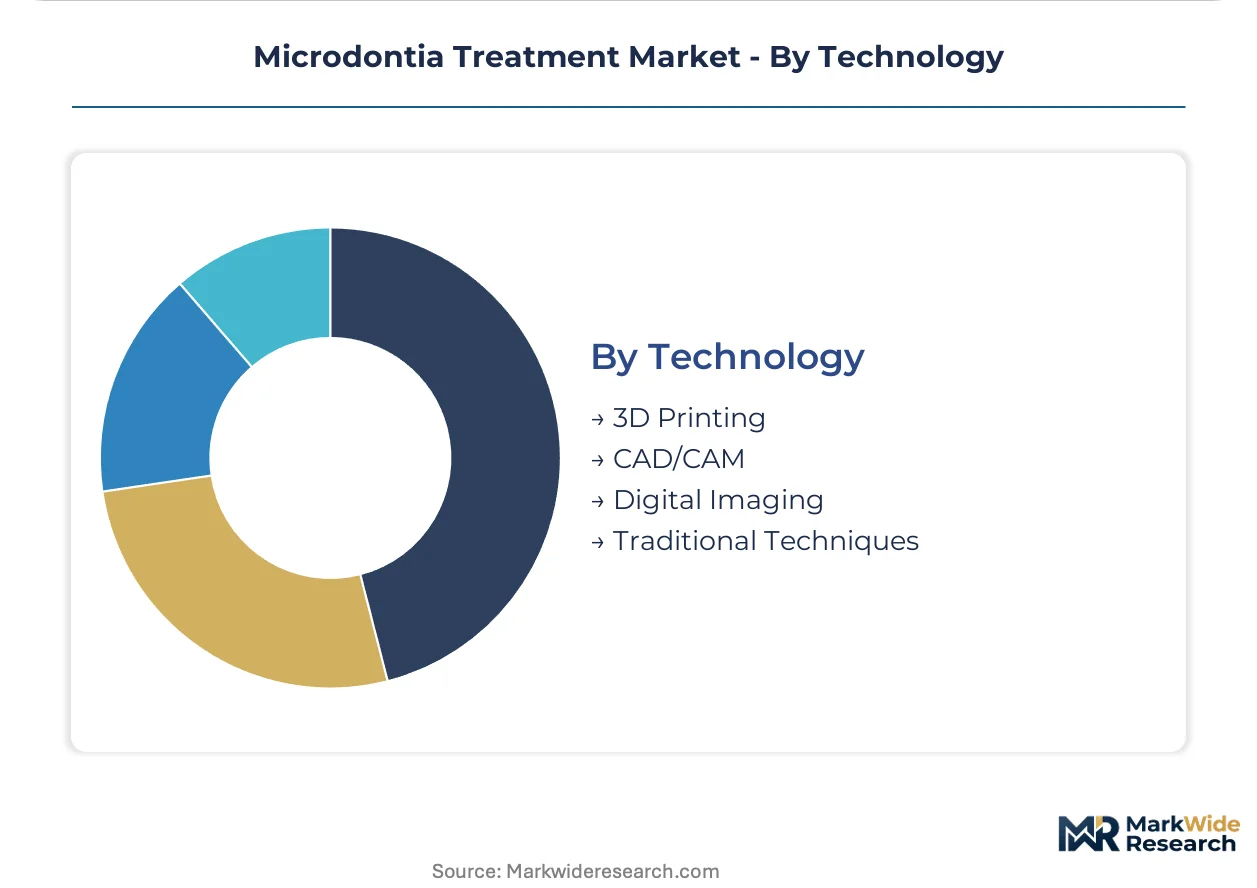
Technology:
Application focus distinguishes subtractive milling for definitive restorations from additive processes targeting orthodontic workflows.
- CAD/CAM:Computer-aided design and subtractive milling of ceramic blocks produces lithium disilicate and zirconia restorations with precision exceeding conventional laboratory methods. Adoption concentrates in dental offices seeking same-day crown delivery capabilities.
- 3D Printing:Photopolymerization and selective laser sintering enable orthodontic aligner, surgical guide, and provisional restoration fabrication. FDA 510(k) pathway streamlining for biocompatible polymers accelerates restorative device commercialization timelines.
- Digital Imaging:Intraoral scanning eliminates elastomeric impression materials while enabling cloud-based treatment planning.
- Traditional Techniques:Conventional laboratory-based waxing, casting, and porcelain layering retain niche applications.
CAD/CAM maintains installed base leadership; 3D printing is gaining share fastest as material biocompatibility approvals expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthodontic specialist density and elective cosmetic procedure penetration concentrate buyer power in metropolitan clusters across select developed markets. Dental service organization consolidation and chairside technology adoption velocity separate high-investment regions from price-sensitive peripheries.
United States
Metropolitan clusters in California, Texas, and the Northeast Corridor drive procedure volume through concentrated orthodontic specialist networks. FDA 510(k) pathway streamlining for 3D-printed biocompatible polymers accelerates restorative device commercialization timelines. Greater Boston and Pacific Northwest dental offices deploy chairside CAD/CAM systems at rates exceeding national benchmarks.
Germany
Premium implant-abutment-crown integration demand concentrates in Bavaria and Baden-Württemberg manufacturing belts. EU MDR recast requirements for custom-made medical devices impose clinical evaluation obligations that reshape competitive dynamics. North Rhine-Westphalia dental laboratories face compliance-driven consolidation as smaller operators exit.
Japan
Aging demographics and aesthetic consciousness elevate microdontia treatment priority in Kanto and Kansai metropolitan zones. METI industrial policy supports domestic dental device manufacturing competitiveness. Tokyo-Osaka corridor practices adopt digital intraoral scanning at penetration rates approaching Western European levels.
China
Rising disposable incomes in Yangtze River Delta and Pearl River Delta urban centers expand addressable demand for cosmetic dental interventions. NMPA regulatory frameworks govern biocompatible polymer approvals for restorative applications. Shanghai and Shenzhen dental clinics represent early adopters of chairside milling technology.
Brazil
Cosmetic dentistry culture and private insurance coverage expansion support treatment demand in São Paulo and Rio de Janeiro metropolitan regions. ANVISA regulatory oversight shapes market access timelines for imported restorative materials. Southeast Brazil dental service organizations aggregate procurement volume for CAD/CAM hardware negotiations.
Microdontia Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Dental service organization procurement concentration favors vendors with capital equipment financing capabilities and multi-site service infrastructure. Three archetypes dominate: diversified healthcare conglomerates with dental divisions, pure-play dental technology specialists, and regional laboratory networks with digital fabrication capabilities. Competitive moves center on backward integration into ceramic powder supply and cloud-based treatment planning platform development.
Among diversified healthcare conglomerates, 3M Company and Danaher Corporation occupy positions spanning adhesive materials through imaging hardware. Dentsply Sirona exemplifies vertical control of CAD/CAM milling hardware and sintering furnaces. Straumann represents premium implant-abutment-crown integration specialists competing on precision and biological performance.
| Leading Market Players |
|---|
| 3M Company |
| Danaher Corporation |
| Patterson Dental |
| Carestream Health, Inc. |
| Planmeca OY |
| Henry Schein |
| Straumann |
| Align Technology, Inc. |
| Dentsply Sirona |
| Others |
Value Network & Pricing Analysis
Undercapacity in European zirconia powder refining is forcing Japanese and Chinese ceramic suppliers to absorb freight premiums while dental laboratories pass input volatility through to chairside CAD/CAM hardware vendors. This utilization squeeze concentrates pricing power among high-purity feedstock holders and compresses margins for mid-tier restorative device assemblers.
Pricing Analysis
Cost-plus contracts with quarterly zirconia indexation dominate raw material procurement between dental laboratories and ceramic suppliers. Three-tier pricing structure across premium lithium disilicate, standard zirconia, and economy composite resin tiers reflects ISO 13485 certification status and chairside delivery speed. Cost compression in economy tiers is intensifying because dental service organizations aggregate procurement volume and demand price transparency. Pediatric clinics exhibit highest price sensitivity due to reimbursement constraints, while cosmetic-focused metropolitan practices demonstrate lowest sensitivity.
Supply Chain Analysis
Contract manufacturing for CAD/CAM milling hardware concentrates in Germany, Switzerland, and Japan where precision engineering capabilities anchor production. Zirconia powder supply draws from limited high-purity ceramic feedstock suppliers in Japan and Germany, while photopolymer resins for 3D printing rest on specialty chemical production in the United States and Netherlands. Single-source vulnerability in zirconia powder creates exposure to geopolitical disruption and input cost spikes. Distribution runs through dental service organization group purchasing organizations that negotiate directly with manufacturers, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) pathway streamlining for 3D-printed biocompatible polymers constitutes a regulatory inflection accelerating restorative device commercialization and compressing incumbent technology refresh cycles.
For Market Incumbents: Insulate adhesive bonding leadership through backward integration into ceramic powder supply and captive ISO 13485 certification infrastructure. 3M Company and Dentsply Sirona must defend against photopolymer resin substitution by embedding sensors into chairside milling systems that lock in consumable replenishment. Cloud-based treatment planning platform control represents the priority defensive lever against centralized design service competitors. For New Entrants and Emerging Players: Southeast Brazil dental service organization networks represent the most penetrable geography where ANVISA regulatory familiarity barriers remain lower than FDA or EU MDR compliance burdens. Aligner-based orthodontic workflows in pediatric clinics offer white-space entry with lower capital requirements than chairside CAD/CAM hardware. Target telehealth-enabled remote consultation platforms as the go-to-market angle, leveraging HIPAA-compliant infrastructure partnerships to bypass physical operatory investments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among dental technology specialists with consumable-anchored hardware ecosystems. Long-term viability across the projection horizon rests on identifying targets with ISO 13485 certification differentiation and group practice network procurement relationships. The signal to watch is dental service organization consolidation velocity in metropolitan United States clusters as inflection indicator for chairside technology deployment rates.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Expedited clearance for 3D-printed polymers compresses product development timelines against EU MDR competitors. |
| Cloud Platform Integration | HIPAA-compliant treatment planning infrastructure enables remote specialist consultation and centralized design services. |
| Backward Integration into Zirconia Supply | Captive ceramic powder sourcing insulates margin position against feedstock concentration volatility. |
| Dental Service Organization Partnership | Multi-site procurement relationships lock in volume commitments and reduce customer acquisition costs. |
| ISO 13485 Certification Investment | Quality management credentials unlock institutional procurement channels and group practice network access. |
Research Methodology
Initial hypotheses were tested against primary input from prosthodontists, orthodontic specialists, dental laboratory technicians, and group purchasing organization procurement managers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and dental service organization capital expenditure disclosures. Bottom-up procedure volume estimates triangulated with top-down market sizing across technology segments.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation dimensions including product type, delivery mode, end user, and technology platform. CAGRs derived from procedure volume growth rates, technology substitution curves, and reimbursement trend analysis. Forecast inputs incorporated intraoral scanner adoption penetration, chairside CAD/CAM hardware depreciation cycles, and 3D printing material biocompatibility approval trajectories.
Practitioners should monitor FDA 510(k) clearance velocity for photopolymer resins and EU MDR post-market surveillance enforcement intensity for early signals of competitive repositioning. Forecasts reflect assumptions regarding dental service organization consolidation pace and zirconia powder supply stability. Cross-checking against CMS Medicare reimbursement rate disclosures and commercial payer policy bulletins is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Services
Dental Fluoride Treatment Market
Dental Services
Dental Service Organization Market
Dental Services
United States Dental Services Market
Dental Services
Periodontal Dental Service Market
Dental Services
Chronic Gingivostomatitis Treatment Market
Dental Services
EMEA Dental Service Organization Market
Dental Services
US Dental Chains Market
Dental Services
Orthodontic Services Market
Dental Services
Dental Market
Dental Services
Global Dental Support Organizations Market
Dental Services
Teledentistry Market
Dental Services
Dental Services Market