
 Automated Blood Processing Equipment Market | 2026-2036
Automated Blood Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Blood Processing Equipment Market Analysis
Closed-system processing standards are reorganizing procurement priorities across blood collection networks. Terumo Corporation leverages its integrated apheresis platform to anchor positions in therapeutic plasma exchange programs. Haemonetics Corporation sustains manufacturing scale across North American and European service networks, while Grifols S.A. specializes in vertically controlled plasma supply chains that feed captive fractionation demand.
Automated blood processing equipment comprises electromechanical systems that separate whole blood into cellular and acellular components through centrifugal force gradients, membrane filtration, or continuous flow separation at controlled rotational speeds and temperature parameters. These systems serve the primary commercial purpose of producing standardized, pathogen-reduced blood components for transfusion and plasma-derived biopharmaceutical manufacturing. Plasma fractionation systems capture the dominant margin pool given their capital intensity and biopharma linkages, while apheresis technology leads growth due to expanding therapeutic indications beyond traditional donation. Blood banks represent the most concentrated end-user channel, though diagnostic laboratories are gaining share as pre-transfusion testing protocols tighten.
The FDA enforces Current Good Manufacturing Practice standards for blood and blood components under 21 CFR 606, while the EMA's Blood Products Working Party coordinates European quality benchmarks through the EU Blood Directive. The WHO's Global Benchmarking Tool further shapes market access requirements for manufacturers seeking procurement contracts with national health systems. Stakeholders must monitor how evolving pathogen inactivation mandates and sustainability reporting obligations under the EU Green Deal reshape equipment specification sheets and facility upgrade timelines.
Market Dynamics
Closed-system automation mandates from the FDA and EMA are forcing blood banks to retire open-bench processing lines, compressing replacement cycles and consolidating procurement authority within national collection networks.
Growth Catalysts
- Pathogen Inactivation Mandates:The FDA's 21 CFR 606 standards for component purity are accelerating upgrades to automated closed-system platforms that integrate leukoreduction and viral inactivation.
- Therapeutic Plasma Exchange Expansion:Neurology and nephrology departments are scaling apheresis programs for myasthenia gravis and anti-GBM disease, pulling equipment into hospital settings.
- Plasma Fractionation Capacity:Biopharma demand for immunoglobulin and albumin feedstocks is concentrating investment in high-throughput centrifugal separation systems.
Market Restraints
- Stainless Steel and Precision Electronics Costs:Volatility in medical-grade alloys and semiconductor components is squeezing margins on capital equipment manufacturing.
- Single-Source Component Dependencies:Specialized centrifuge rotors and membrane cassettes rely on concentrated German and Japanese precision engineering suppliers.
- Validation Timeline Friction:FDA 510(k) and EMA CE marking pathways for novel separation technologies extend commercialization cycles beyond typical medical device benchmarks.
Strategic Opportunities
- Point-of-Care Blood Processing:Military field hospitals and rural trauma centers present untapped demand for portable, battery-operated separation units.
- EU Green Deal Equipment Standards:Sustainability reporting obligations under the EU Green Deal are creating preference for energy-efficient, refrigerant-reduced processing platforms.
- AI-Enabled Quality Control:Machine vision integration with centrifugal systems enables real-time component grading, opening premium pricing for automated decision-support modules.
Industry Challenges
- Biomedical Equipment Technician Shortage:Specialized training for electromechanical blood processing systems lags deployment rates, extending downtime during preventive maintenance windows.
- Legacy LIS Integration Complexity:Hospital laboratory information systems require custom middleware development to capture automated processing data streams, delaying go-live dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Blood Processing Equipment Market |
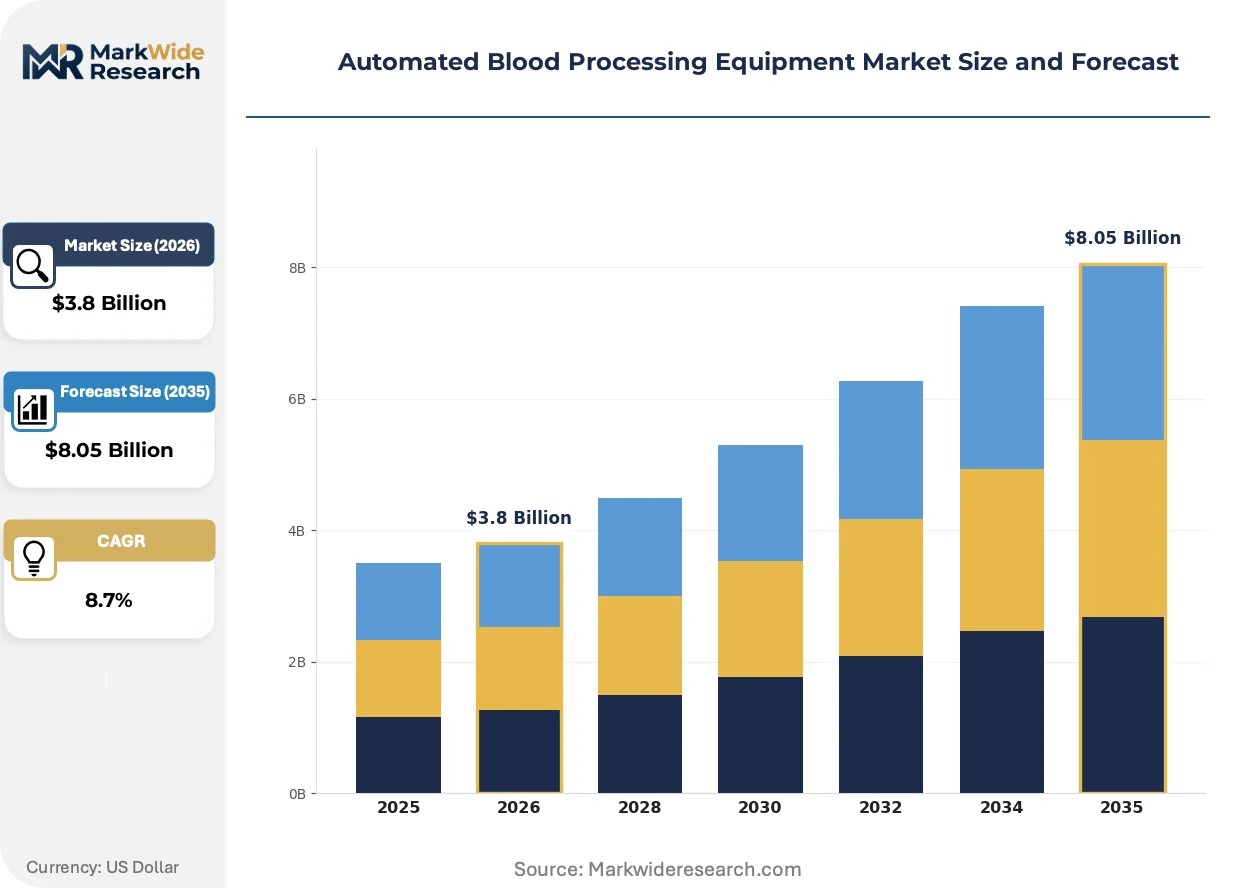
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Separators, Plasma Fractionation Systems, Blood Bag Systems, Blood Component Separators Technology: Continuous Flow Processing, Apheresis, Centrifugation, Filtration End User: Hospitals, Blood Banks, Diagnostic Laboratories, Research Institutes Application: Transfusion Medicine, Therapeutic Apheresis, Blood Donation, Hematology |
| Companies Covered | Terumo Corporation, Haemonetics Corporation, Grifols S.A., Abbott Laboratories, Fresenius Kabi AG, Beckman Coulter, Sysmex Corporation, Bio-Rad Laboratories, Ortho Clinical Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Blood Processing Equipment Market Emerging Trajectories
Automation architectures are converging around closed-loop control systems that reduce human touchpoints, while regulatory pressure on component traceability is embedding sensor networks deeper into separation hardware.
Microfluidic separation technology is miniaturizing blood component extraction into cartridge-based platforms that operate at microliter scales. Point-of-care transfusion services and battlefield medicine units are piloting these systems for rapid plasma separation. The technology is miniaturizing capital requirements and shifting processing capacity from centralized blood banks toward distributed clinical settings.
The EU Medical Device Regulation (MDR) is tightening post-market surveillance obligations for blood processing equipment manufacturers. Device history records must now capture component-level traceability through supply chains. High-volume plasma fractionation facilities in Germany and France are responding by demanding vendor-managed inventory agreements that transfer compliance documentation burden to equipment suppliers.
Service unbundling is separating hardware procurement from maintenance contracts in blood bank purchasing patterns. Large hospital networks in the United States are negotiating multi-year service level agreements independent of capital equipment financing, compressing vendor margins on aftermarket support. This shift is most pronounced among integrated delivery networks consolidating blood services across multiple acute care facilities.
Automated Blood Processing Equipment Market Segmentation
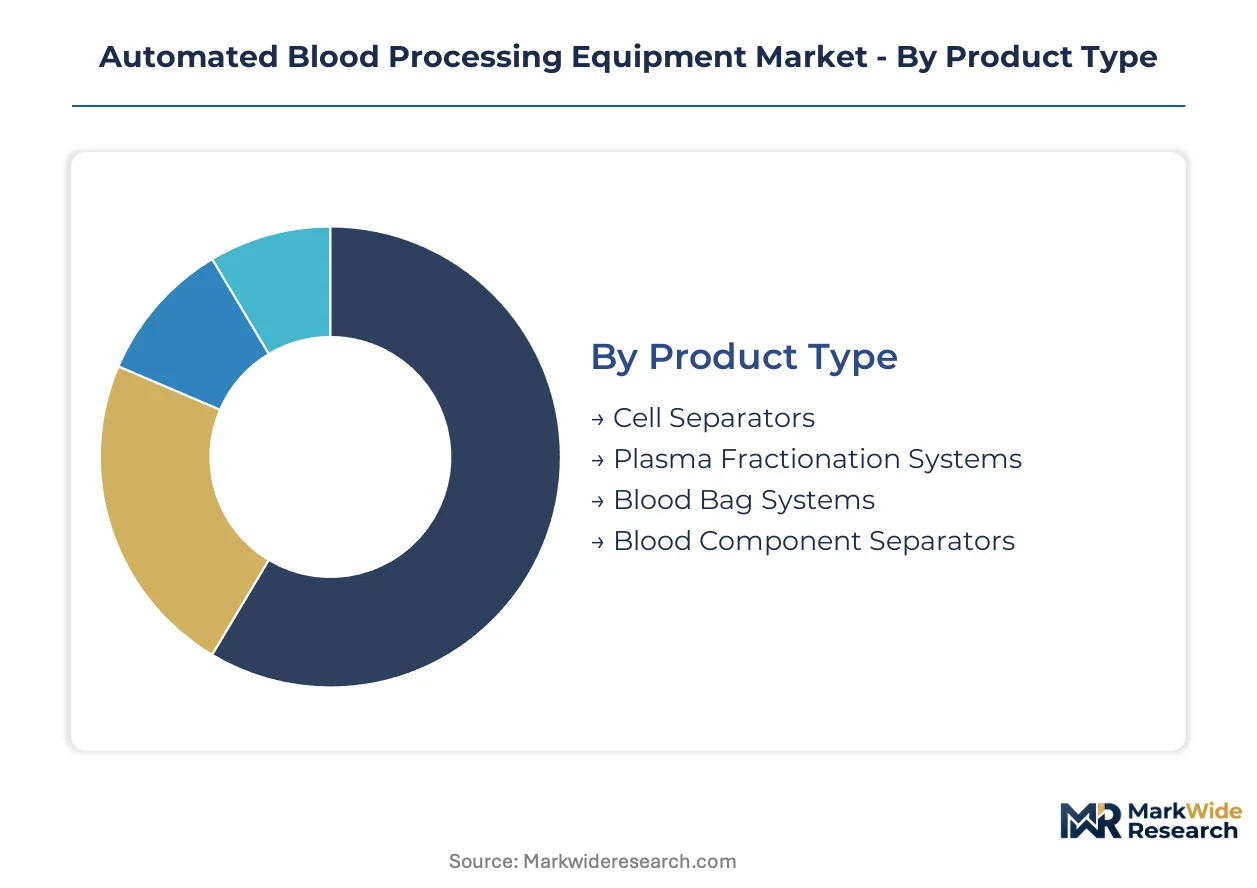
Automated blood processing equipment segments by capital intensity, regulatory pathway, and end-user procurement authority. Margin pools concentrate in plasma fractionation and apheresis technology where biopharma linkages command premium pricing.
Product Type:
Margin concentration follows capital intensity and captive plasma supply chain integration.
- Plasma Fractionation Systems:High-throughput centrifugal separation platforms process source plasma into immunoglobulin and albumin feedstocks. German and French fractionation facilities drive demand for closed-system automation that satisfies EMA pathogen inactivation mandates.
- Cell Separators:Electromechanical platforms isolate specific blood cell populations through differential centrifugation. United States hospital networks are scaling therapeutic apheresis programs for neurology departments, pulling equipment into acute care settings.
- Blood Bag Systems:Single-use collection and processing containers integrate with automated separation hardware.
- Blood Component Separators:Modular units extract platelets, plasma, and red cell concentrates from whole blood units.
Plasma Fractionation Systems hold installed capacity. Cell Separators is rotating up the share rankings.
Technology:
Procurement patterns split between high-volume continuous processing and precision therapeutic applications.
- Apheresis:Continuous flow systems extract specific blood components while returning remainder to the donor. United States blood collection organizations are expanding mobile apheresis fleets to serve rural donor bases and hospital-based therapeutic programs.
- Centrifugation:Differential density separation remains the workhorse technology for blood component isolation. Blood banks across Spain and Italy are retiring open-bench centrifuges in favor of closed-system platforms that satisfy EU Blood Directive traceability requirements.
- Continuous Flow Processing:Automated loop systems enable high-throughput plasma collection with minimal operator intervention.
- Filtration:Membrane-based separation targets leukoreduction and pathogen reduction applications.
Centrifugation dominates current installed base. Apheresis is climbing the fastest as therapeutic indications multiply.
End User:
Customer concentration determines contract structure and service bundling terms.
- Blood Banks:National collection networks operate centralized processing facilities with high equipment utilization rates. The American Red Cross and Canadian Blood Services are consolidating procurement authority across regional processing centers, compressing vendor margins through volume aggregation.
- Hospitals:Acute care facilities deploy point-of-care processing for emergency transfusion services. Trauma centers in Texas and California are piloting rapid plasma separation units to reduce dependence on blood bank inventory.
- Diagnostic Laboratories:Pre-transfusion testing protocols are pulling automated processing into reference lab workflows.
- Research Institutes:Cell therapy development programs demand small-batch separation systems with flexible protocols.
Blood Banks anchor procurement volume. Hospitals is gaining share fastest as therapeutic apheresis decentralizes.
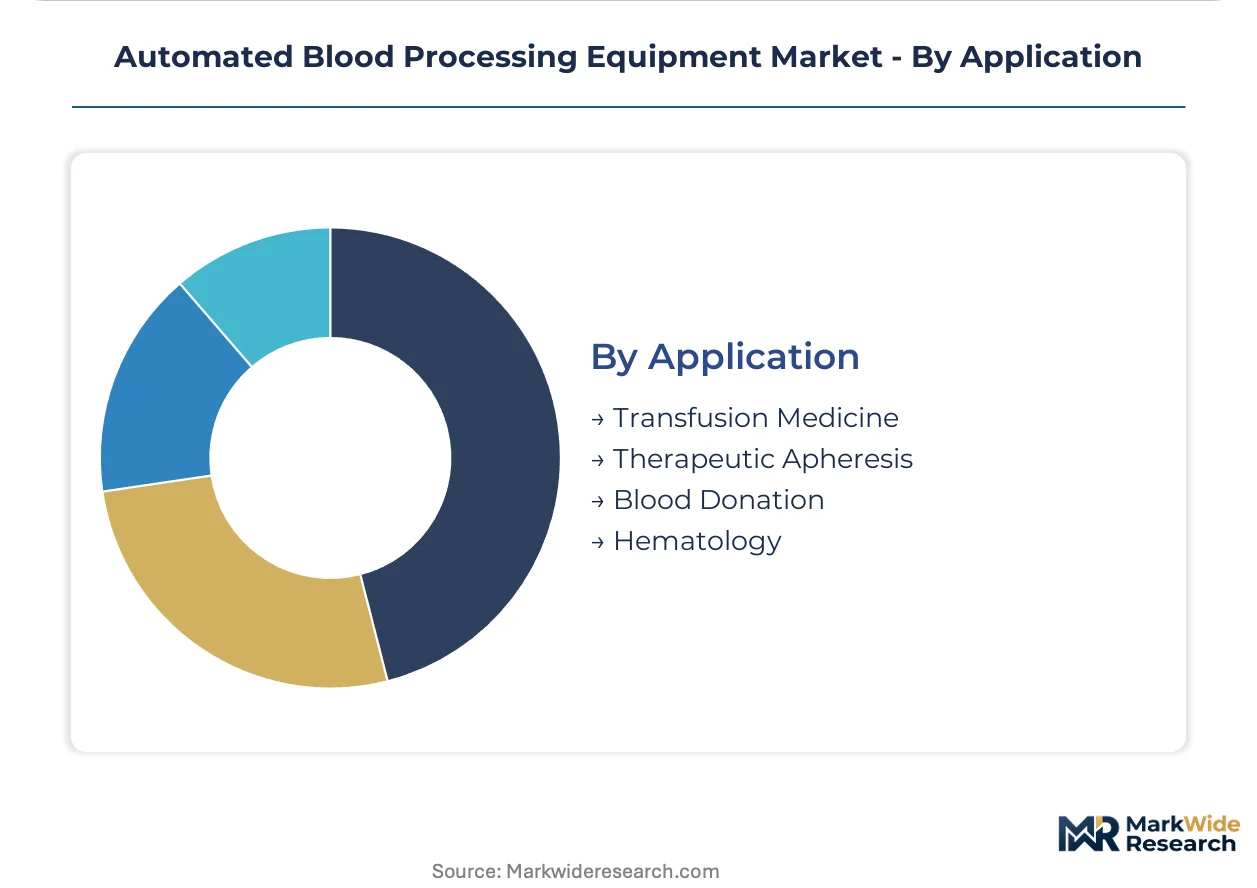
Application:
Revenue stability varies between mature transfusion services and expanding therapeutic protocols.
- Therapeutic Apheresis:Plasma exchange procedures treat autoimmune and renal indications beyond traditional donation. Mayo Clinic and Cleveland Clinic are scaling inpatient apheresis programs for myasthenia gravis and anti-GBM disease, requiring dedicated equipment deployment.
- Transfusion Medicine:Component preparation for red cell, platelet, and plasma transfusion represents the baseline demand pool. Japanese Red Cross facilities are upgrading to FDA-equivalent closed-system standards to maintain export eligibility for plasma derivatives.
- Blood Donation:Automated whole blood and apheresis collection sustains donor base maintenance.
- Hematology:Specialized processing supports stem cell harvest and cellular therapy manufacturing.
Transfusion Medicine holds procedure volume. Therapeutic Apheresis is expanding most quickly as clinical indications broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision engineering for centrifuge rotors and membrane cassettes clusters in Germany and Japan, while FDA and EMA regulatory tightening compresses replacement cycles across North American and European blood collection networks.
United States
The American Red Cross and hospital networks in Texas and California are driving equipment replacement for therapeutic apheresis programs. FDA 21 CFR 606 standards mandate closed-system automation for component purity. Boston-area medical centers are piloting AI-enabled quality control modules integrated with centrifugal separation hardware.
Germany
Plasma fractionation facilities in Hesse and Bavaria command premium pricing for high-throughput centrifugal systems feeding immunoglobulin production. EMA's Blood Products Working Party enforces EU Blood Directive traceability through the EU Medical Device Regulation. Frankfurt-Rhine-Main clusters vendor-managed inventory agreements transferring compliance documentation burden to suppliers.
Japan
Japanese Red Cross facilities are upgrading to FDA-equivalent closed-system standards to maintain export eligibility for plasma derivatives. METI coordinates domestic quality benchmarks aligned with international pathogen inactivation protocols. Osaka-Kobe industrial corridor concentrates precision manufacturing for medical-grade alloys used in separation hardware.
France
High-volume plasma fractionation sites in Île-de-France are demanding energy-efficient platforms under EU Green Deal sustainability reporting obligations. ANSM enforces post-market surveillance obligations through tightened device history record requirements. Paris-Saclay research cluster is advancing microfluidic cartridge-based separation for point-of-care applications.
China
Domestic blood collection organizations are expanding automated processing capacity to reduce dependence on imported plasma derivatives. NMPA alignment with international GMP standards is accelerating facility upgrades in Yangtze River Delta medical manufacturing zones. Shanghai-based hospitals are scaling therapeutic apheresis for autoimmune indications.
Automated Blood Processing Equipment Market Vendor Landscape
Concentration sits with integrated apheresis platform specialists and vertically controlled plasma supply chain operators. Three tiers structure competitive positioning: multinational electromechanical system manufacturers with North American and European service networks, biopharma-linked fractionation equipment suppliers with captive demand, and precision component fabricators supplying concentrated German and Japanese engineering clusters. Dominant competitive moves include service unbundling that separates hardware procurement from maintenance contracts, and backward integration into membrane cassette and centrifuge rotor production to reduce single-source dependencies.
Among Japan-based electromechanical specialists, Terumo Corporation and Sysmex Corporation occupy positions anchoring integrated apheresis and diagnostic workflow automation respectively. Haemonetics Corporation exemplifies the North American manufacturing scale archetype with extensive service network coverage. Grifols S.A. represents the vertically integrated plasma supply chain model, while Fresenius Kabi AG anchors German-engineered fractionation and transfusion technology within hospital and blood bank procurement channels.
| Leading Market Players |
|---|
| Terumo Corporation |
| Haemonetics Corporation |
| Grifols S.A. |
| Abbott Laboratories |
| Fresenius Kabi AG |
| Beckman Coulter |
| Sysmex Corporation |
| Bio-Rad Laboratories |
| Ortho Clinical Diagnostics |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for precision-engineered centrifuge rotors concentrate procurement leverage among German and Japanese fabricators, compressing margin buffers for equipment assemblers while amplifying pricing power at the component tier. This lead-time structure forces blood processing OEMs into long-term offtake agreements that lock in cost positions before FDA and EMA regulatory mandates accelerate replacement demand.
Pricing Analysis
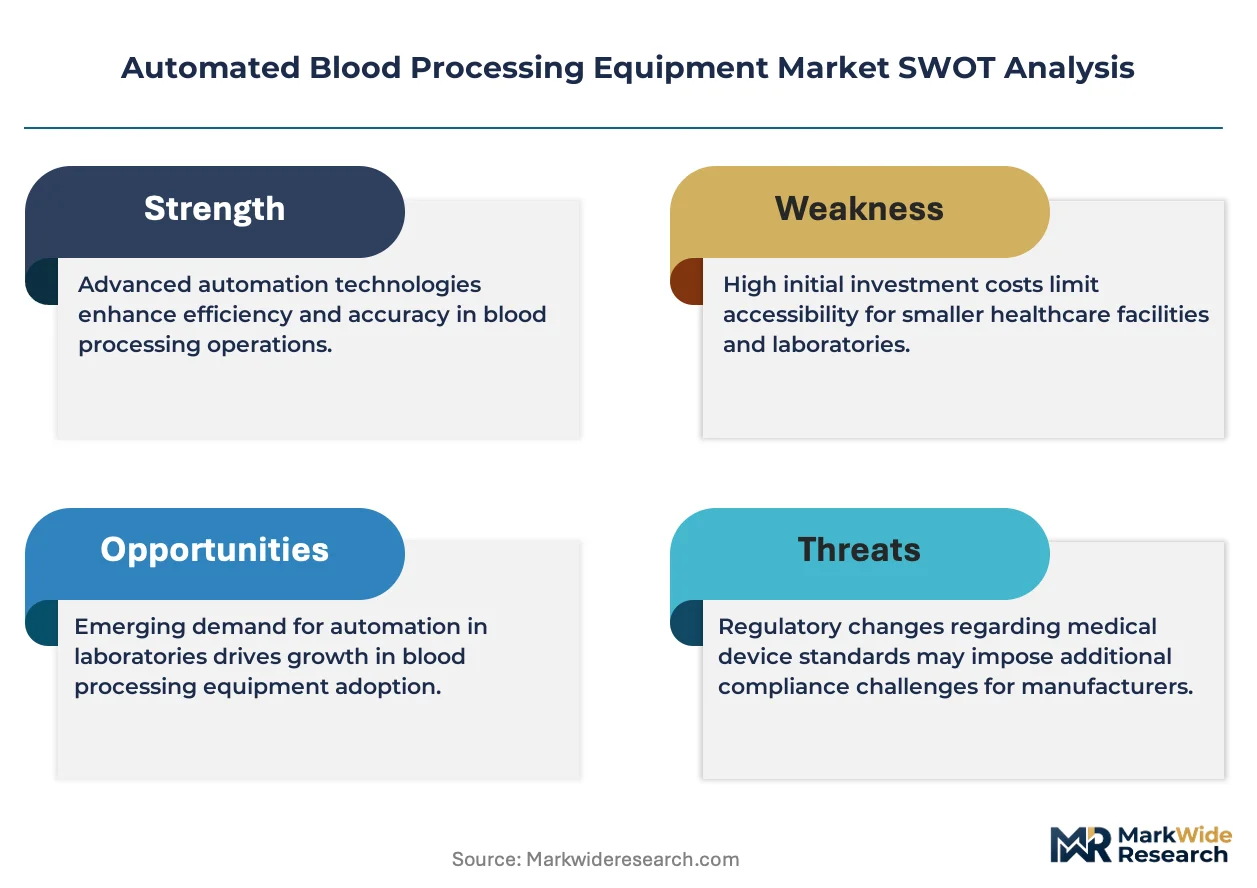
FDA 21 CFR 606 dictates the pricing tier structure across automated blood processing equipment, separating closed-system platforms with integrated pathogen inactivation from open-bench legacy units. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling, with hospital networks negotiating unbundled maintenance contracts that compress vendor margins. Cost compression in standard-tier centrifugation systems is intensifying because stainless steel alloy volatility feeds through medical-grade component sourcing. Blood banks represent the most price-sensitive buyer segment, while plasma fractionation facilities prioritize throughput reliability over unit economics.
Supply Chain Analysis
Port congestion on trans-Pacific lanes from Osaka-Kobe to Long Beach extends inbound logistics timelines for medical-grade alloy shipments, forcing safety stock accumulation at assembly facilities. Precision manufacturing clusters in Germany, Japan, and Switzerland anchor supply for specialized centrifuge rotors, membrane cassettes, and temperature control modules. Raw material dependencies draw from nickel-titanium superalloys, semiconductor-grade sensors, and pathogen-reduction chemical reagents. Single-source vulnerability concentrates at the rotor fabrication tier where three German suppliers control proprietary forging techniques. Distribution runs through vendor-managed inventory agreements that transfer compliance documentation burden to equipment suppliers serving European fractionation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-loop automation architectures and pathogen inactivation mandates are compressing replacement cycles across blood collection networks, creating high-growth disruption as regulatory tightening outpaces legacy equipment depreciation schedules.
For Market Incumbents: Consolidate service network density across North American hospital corridors to defend against emerging point-of-care entrants. Lock in multi-year vendor-managed inventory agreements with German fractionation facilities before EU MDR traceability requirements harden. Backward integration into membrane cassette production reduces single-source exposure to Japanese precision engineering suppliers.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for AI-enabled quality control modules open immediate white-space in the premium tier where incumbents lag machine vision integration. Target rural trauma centers in Texas and California with portable apheresis units that bypass blood bank inventory dependence. Lead with battery-operated separation platforms that satisfy military field hospital procurement specifications.
For Investors and Strategic Acquirers: Long-term, this sits as a biopharma-captive infrastructure play because plasma fractionation capacity expansion ties equipment demand to immunoglobulin and albumin feedstock pricing. Acquisition candidates cluster among precision component fabricators with proprietary rotor forging capabilities and existing EMA quality agreements. Watch for EU Green Deal sustainability reporting obligations triggering accelerated replacement of refrigerant-heavy legacy platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR compliance unlocks vendor-managed inventory contracts with French fractionation sites. |
| Hospital System Partnership | Integrated delivery networks consolidate therapeutic apheresis procurement across multi-facility footprints. |
| Software Companion Development | AI-enabled quality control modules command premium pricing from Boston-area medical centers. |
| Backward Integration | In-house rotor production insulates margins from German precision engineering supplier concentration. |
| Reimbursement Strategy | Therapeutic plasma exchange coding alignment pulls equipment into neurology department capital budgets. |
Methodological Framework
The analysis maps plasma fractionation systems, apheresis platforms, and blood component separators, each validated through biomedical equipment technicians, hospital purchasing committee members, blood bank operations directors, and GPO contracts managers. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA CE marking databases, hospital procurement records, and EU Blood Directive implementation reports. Bottom-up equipment deployment counts triangulate against top-down plasma derivative production volume estimates.
Consistency checks validated volume and value outputs against external benchmarks including plasma fractionation capacity announcements and national blood collection organization capital expenditure disclosures. The analytical framework segments by product type, technology architecture, end-user procurement authority, and application across the projection horizon. CAGRs derive from installed base replacement modeling and therapeutic indication expansion curves. Forecast inputs incorporate pathogen inactivation mandate timelines and EU Green Deal equipment efficiency standards.
Decision-makers should treat outputs as directional under assumptions of regulatory enforcement continuity and biopharma plasma demand stability; material deviation in alloy pricing or FDA inspection intensity would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
US Cath Labs Market
Laboratory Equipment
Global Automated Analyzers Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Laboratory Furniture Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Global Pipettes and Pipettors Market
Laboratory Equipment
Automated Blood Analyzer Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Latin America Laboratory Equipment and Disposables Market
Laboratory Equipment
Electrophoresis Equipment and Supplies Market
Laboratory Equipment
Global Hematology Analyzers and Reagents Market
Laboratory Equipment
Absorbance Micro Plate Reader Market
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Vacuum Tissue Processors Market
Laboratory Equipment
Blood Volume Analyzer Market