
 Laboratory Supplies Market | 2026-2036
Laboratory Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Supplies Market Intelligence
Subscription-based instrument service contracts and software-defined analytics modules is rebalancing how laboratory capital budgets get allocated, shifting preference toward operational expenditure models over upfront hardware purchases. Thermo Fisher Scientific leverages its installed base of chromatography and mass spectrometry platforms to sustain recurring revenue through embedded service agreements. Danaher anchors its competitive posture through in-house production of consumables that pair with its analytical instrumentation ecosystems. Agilent Technologies differentiates by controlling calibration and compliance software updates that lock in multi-year client relationships.
Laboratory supplies encompass consumables, equipment, chemicals, and glassware engineered to precise tolerances for analytical reproducibility, including borosilicate glassware rated for thermal shock resistance and reagent-grade chemicals meeting ACS purity specifications. These products serve primary industrial purposes in quantitative research, diagnostic validation, and process quality assurance where protocol standardization determines experimental validity. Consumables command the largest revenue pool due to recurring replacement cycles, while equipment segments carry higher per-unit margins concentrated in mass spectrometry and automated liquid handling systems. Research applications absorb the greatest volume of supplies, though clinical diagnostics segments are expanding fastest as hospital laboratories centralize testing menus under CAP accreditation pressures.
FDA quality system regulation and ISO 17025 accreditation standards shape supplier qualification protocols, forcing distributors to maintain chain-of-custody documentation and lot-traceability databases. EPA good laboratory practice guidelines and OSHA laboratory safety standards further constrain chemical handling and waste disposal specifications, elevating compliance costs for smaller regional vendors. Stakeholders must monitor how NIST reference material programs and evolving CLIA complexity requirements recalibrate procurement specifications for clinical-grade consumables.
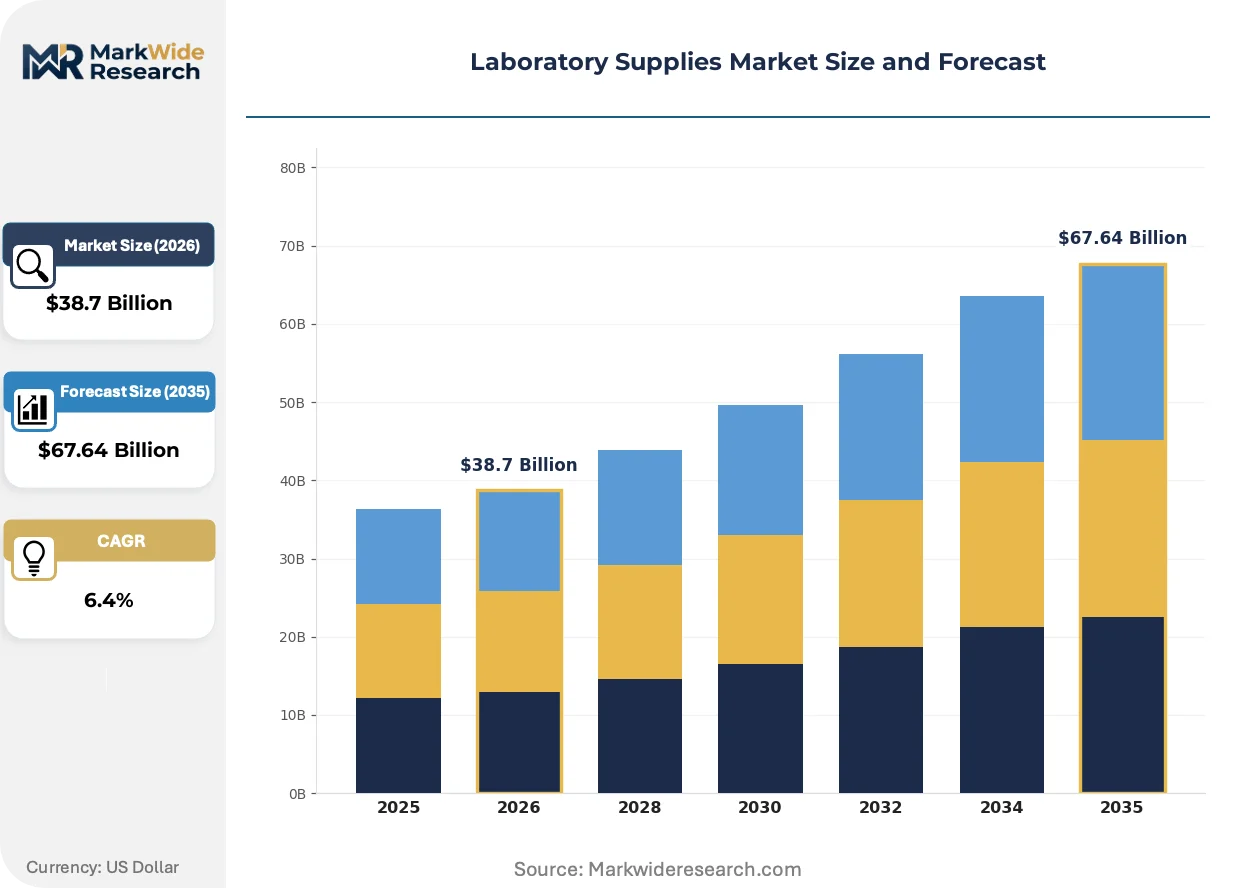
Market Dynamics
Subscription-based instrument service contracts and software-defined analytics modules are rebalancing how laboratory capital budgets get allocated, shifting preference toward operational expenditure models over upfront hardware purchases.
Growth Catalysts
- NIH Funding Cycles:Academic institutions in the United States are expanding procurement of advanced consumables for genomic research workflows, driving sustained instrument refresh programs in Boston and San Diego biotech clusters.
- FDA Quality System Regulation:The updated regulation for device manufacturing reshapes supplier qualification requirements, forcing distributors to maintain chain-of-custody documentation and lot-traceability databases.
- Automated Liquid Handling:High-throughput screening facilities are adopting robotic pipetting systems to compress protocol standardization timelines and reduce human error in quantitative research.
Market Restraints
- Specialty Glass Supply Concentration:Borosilicate glassware production concentrates among German and Chinese manufacturers, exposing buyers to thermal shock resistance specification delays during logistics disruptions.
- Reagent-Grade Chemical Volatility:ACS purity specification solvents face feedstock price swings tied to petroleum derivatives, compressing margins for smaller regional vendors.
- ISO 17025 Accreditation Burden:Testing laboratories must maintain exhaustive calibration records and proficiency testing documentation, elevating fixed compliance costs that deter market entry.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Domestic manufacturing incentives are attracting consumables producers to establish local production of diagnostic-grade plastics and sterile packaging.
- Cell Therapy Manufacturing:GMP-grade single-use bioreactor bags and aseptic connectors represent underpenetrated demand from contract development organizations building-out commercial-scale capacity.
- Cloud-Connected Instrumentation:Remote diagnostics and predictive maintenance modules are converging with traditional hardware sales, opening recurring revenue streams for field service organizations.
Industry Challenges
- Metrology Technician Scarcity:Mass spectrometry and chromatography calibration requires specialized expertise that outpaces vocational training program output, extending instrument downtime during peak research cycles.
- CLIA Complexity Recalibration:Hospital laboratories centralizing testing menus under CAP accreditation pressures face multi-year validation timelines for new assay platforms, delaying consumables conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Supplies Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumables, Equipment, Chemicals, Glassware Application: Research, Clinical, Quality Control, Education End User: Pharmaceuticals, Academic Institutions, Hospitals, Biotechnology Distribution Channel: Online, Wholesalers, Direct Sales, Distributors |
| Companies Covered | Bio-Rad Laboratories, Shimadzu Corporation, Thermo Fisher Scientific, PerkinElmer, FUJIFILM Holdings Corporation, Danaher, Bruker, Waters Corporation, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Supplies Market Strategic Shifts & Innovations
Artificial intelligence-driven experimental design and digital twin simulation are compressing R&D cycles, forcing suppliers to embed predictive analytics into consumables ordering systems and instrument control software.
Mass spectrometry platforms are converging with cloud-native data pipelines, enabling real-time spectral matching against decentralized reference libraries. Pharmaceutical quality control laboratories are adopting these integrated workflows to accelerate impurity profiling and reduce batch release timelines. The technology is converging with vendor-managed inventory systems, allowing reagent consumption patterns to trigger automated procurement replenishment.
REACH authorization requirements for persistent organic pollutants are restricting perfluorinated compound use in laboratory coatings and seals, forcing manufacturers to reformulate O-rings and gaskets for chromatography systems. The European Chemicals Agency's expanded substance evaluation program is extending compliance documentation timelines for imported consumables. Clinical diagnostics segments are responding by qualifying alternative fluoropolymer-free materials ahead of sunset date enforcement.
Academic core facilities are consolidating purchasing authority under centralized procurement offices, displacing principal investigator-driven ad-hoc ordering. Group purchasing organizations are capturing volume commitments from research universities in exchange for standardized catalog pricing and dedicated stockholding agreements. This concentration is most visible across United States R1 institutions, where NIH indirect cost recovery rules favor multi-year supply contracts over transactional spot purchasing.
Laboratory Supplies Market Segmentation
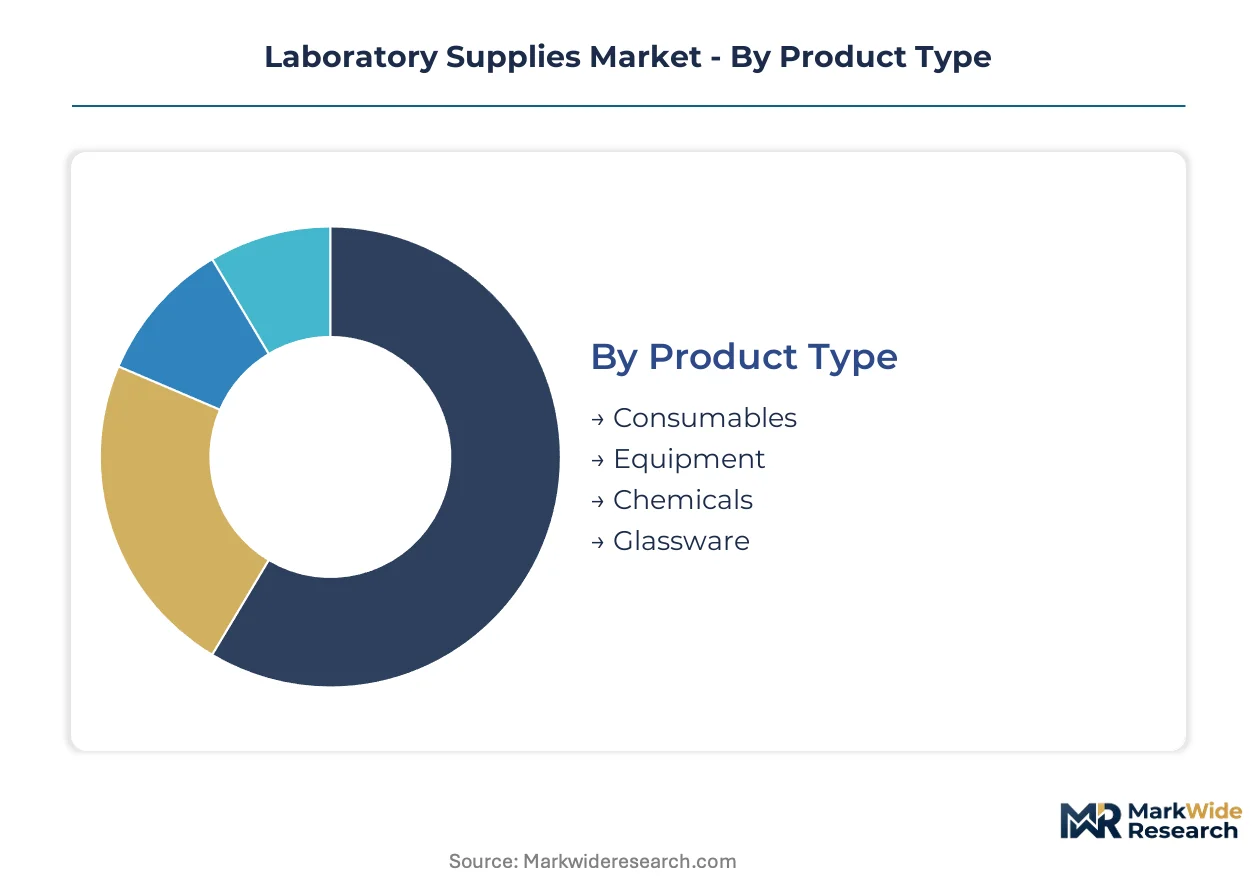
Laboratory supplies segmentation reveals divergent margin structures and procurement behaviors across product categories. Equipment segments command premium pricing through multi-year service contracts, while consumables generate recurring revenue through predictable replacement cycles tied to experimental throughput.
Product Type:
Volume concentrates in consumables with their perpetual replenishment cycles, while equipment captures value through upfront capital expenditure and embedded software licensing.
- Consumables:Single-use plastics, filtration membranes, and chromatography columns engineered to ISO 17025 traceability standards. Demand clusters in United States academic core facilities where NIH-funded genomic workflows consume pipette tips and PCR plates at industrial scale.
- Equipment:Automated liquid handling workstations and mass spectrometry platforms requiring specialized metrology calibration. Pharmaceutical quality control laboratories in Germany and Switzerland anchor procurement, driven by EMA good manufacturing practice validation requirements for batch release testing.
- Chemicals:Reagent-grade solvents and certified reference materials meeting ACS purity specifications.
- Glassware:Borosilicate beakers and volumetric flasks rated for thermal shock resistance.
Mature deployment sits with Glassware. Newer deployment is concentrated in Consumables.
Application:
Research applications absorb the greatest absolute volume, though clinical segments are climbing the fastest as hospital laboratories consolidate testing menus under accreditation pressures.
- Research:Quantitative experimental workflows spanning genomics, proteomics, and materials science. Academic institutions in Boston and San Diego biotech clusters sustain instrument refresh programs, while European Research Council grants drive comparable procurement across Max Planck Institute facilities.
- Clinical:Diagnostic validation and patient sample processing under CLIA complexity requirements. United States hospital systems centralizing laboratory services generate concentrated demand for CAP-accredited consumables and automated analyzers.
- Quality Control:Process validation and impurity profiling for pharmaceutical manufacturing release.
- Education:Undergraduate teaching laboratories with standardized protocol requirements.
Established infrastructure dominates Quality Control. Accelerating investment flows into Clinical.
End User:
Pharmaceutical procurement emphasizes GMP-grade certification and audit-ready documentation, while academic buyers prioritize cost efficiency and grant-funded flexibility.
- Pharmaceuticals:Commercial manufacturing and analytical development requiring FDA quality system regulation compliance. Contract development organizations building cell therapy capacity generate underpenetrated demand for single-use bioreactor systems.
- Academic Institutions:Principal investigator-driven research with fragmented purchasing authority now consolidating under centralized procurement offices. Group purchasing organizations capture volume commitments from United States R1 universities through multi-year supply contracts.
- Hospitals:Centralized laboratory services managing high-throughput diagnostic menus.
- Biotechnology:Venture-funded startups with accelerated capital deployment timelines.
Traditional dominance rests with Pharmaceuticals. Emerging intensity characterizes Biotechnology.
Distribution Channel:
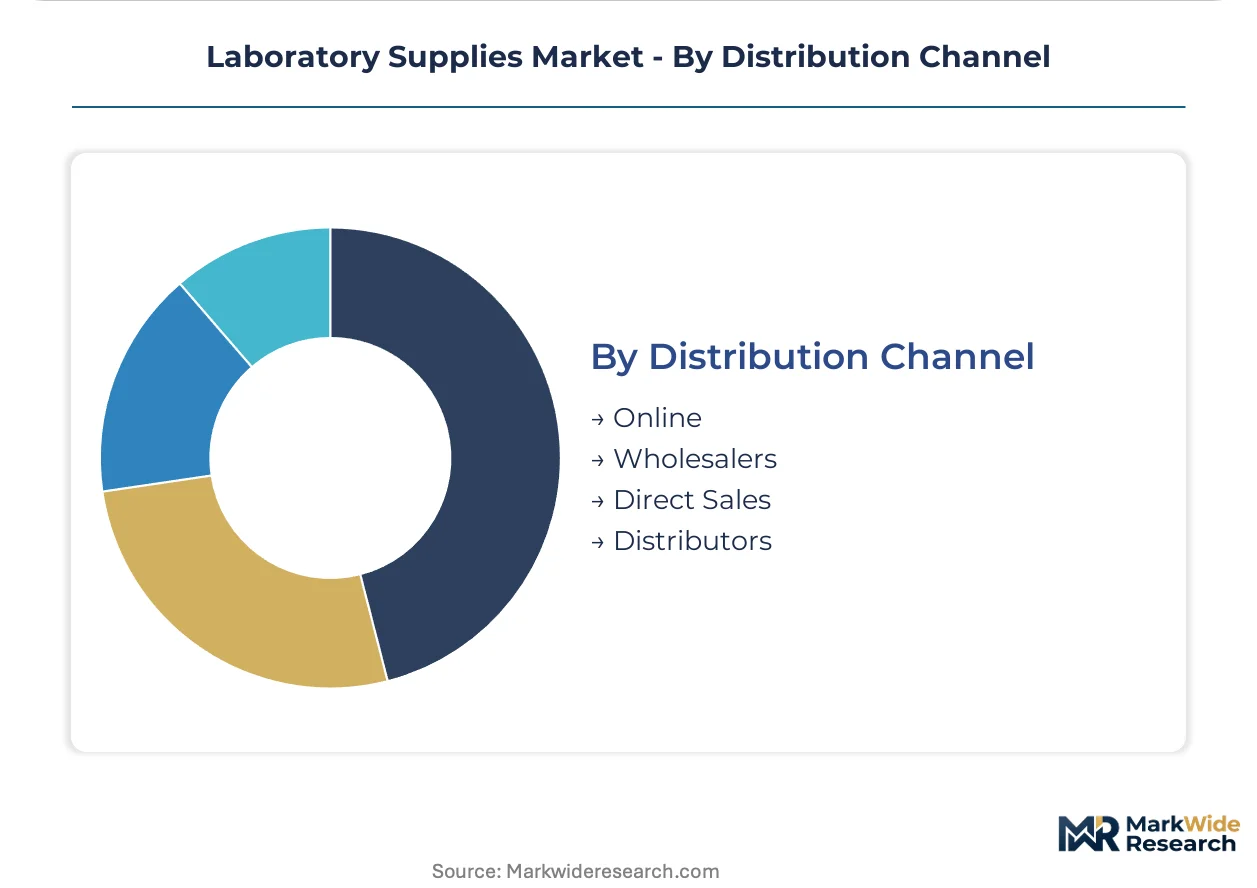
Direct sales relationships secure multi-year service contracts for complex instrumentation, while digital platforms capture transactional consumables procurement with compressed delivery timelines.
- Online:E-procurement portals with real-time inventory visibility and automated reorder triggers. Academic core facilities and small biotechnology startups leverage vendor-managed inventory systems for chromatography solvents and cell culture media.
- Direct Sales:Field service engineers embedding predictive maintenance modules and calibration software updates. Thermo Fisher Scientific and Agilent Technologies lock in multi-year relationships through instrument control software licensing.
- Wholesalers:Regional inventory pooling for standardized glassware and general laboratory chemicals.
- Distributors:Specialized value-added resellers with ISO 17025 accreditation documentation capabilities.
Longstanding penetration defines Direct Sales. Rapid expansion marks Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China concentrate borosilicate glassware manufacturing, while the United States absorbs the largest share of high-value analytical instrumentation. Consumption patterns diverge sharply between research-intensive economies with NIH or ERC funding streams and manufacturing hubs serving export markets.
United States
NIH funding cycles drive sustained instrument refresh programs across Boston and San Diego biotech clusters. FDA quality system regulations force distributors to maintain chain-of-custody documentation and lot-traceability databases. Academic core facilities in Massachusetts and California are consolidating purchasing authority under centralized procurement offices.
Germany
EMA good manufacturing practice validation requirements anchor pharmaceutical quality control laboratory procurement. REACH authorization requirements for persistent organic pollutants are restricting perfluorinated compound use in laboratory coatings and seals. The Rhine-Main and Upper Bavaria regions concentrate metrology calibration expertise for mass spectrometry platforms.
China
Domestic production of diagnostic-grade plastics is expanding under medical device manufacturing incentives. NMPA regulations reshape supplier qualification protocols for imported analytical instrumentation. Shanghai and Suzhou industrial parks are attracting consumables producers building regional distribution networks.
India
PLI scheme incentives for medical devices are attracting consumables producers to establish local production of sterile packaging. CDSCO regulations constrain chemical handling and waste disposal specifications for clinical-grade materials. Hyderabad and Bengaluru biotech corridors generate concentrated demand for single-use bioreactor systems.
Switzerland
Swissmedic certification requirements elevate compliance documentation timelines for clinical-grade consumables. Basel and Zurich anchor pharmaceutical analytical development spending on automated liquid handling workstations. Contract development organizations building cell therapy capacity generate underpenetrated demand for GMP-grade aseptic connectors.
Laboratory Supplies Market Key Industry Players
Top-tier vendors anchor multi-year service contracts, while mid-tier specialists compete on consumables volume and regional responsiveness. The vendor base stratifies across three tiers: integrated life science conglomerates with chromatography and mass spectrometry ecosystems, precision instrument specialists with embedded software licensing, and regional consumables fabricators with ISO 17025 accreditation. Dominant competitive moves include backward integration into consumables production and geographic expansion through field service organization buildouts.
Among diversified life science conglomerates, Thermo Fisher Scientific, Danaher, and Agilent Technologies exemplify distinct strategic archetypes. Thermo Fisher Scientific occupies a position anchored by installed base leverage and recurring service revenue. Danaher represents the consumables-captive model with in-house production pairing with analytical instrumentation. Agilent Technologies sits within the compliance-software tier, controlling calibration updates that lock in multi-year client relationships.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Shimadzu Corporation |
| Thermo Fisher Scientific |
| PerkinElmer |
| FUJIFILM Holdings Corporation |
| Danaher |
| Bruker |
| Waters Corporation |
| Agilent Technologies |
| Others |
Cost & Logistics Intelligence
Academic core facilities consolidating purchasing authority under centralized procurement offices are shifting laboratory supplies procurement toward multi-year contract pricing with standardized catalog commitments. This buyer concentration amplifies volume discount leverage while compressing margins for distributors serving fragmented principal investigator-driven spot purchasing.
Pricing Analysis
Cost-down pressure on consumables tiers accelerates because group purchasing organizations capture volume commitments from United States R1 universities in exchange for dedicated stockholding agreements. Three-tier pricing structure across premium, standard, and economy levels separates GMP-grade certified consumables from research-grade materials and teaching-laboratory generics. Price differentiation traces to ISO 17025 accreditation status and after-sales calibration bundling. Biotechnology startups with venture-funded capital deployment timelines exhibit lowest price sensitivity, while undergraduate teaching laboratories face strict budget caps.
Supply Chain Analysis
FDA quality system regulation and ISO 17025 accreditation requirements gate supplier qualification, forcing distributors to maintain chain-of-custody documentation and lot-traceability databases. Borosilicate glassware production concentrates in Germany and China, while reagent-grade chemical synthesis anchors in the United States and Switzerland. Feedstock price volatility in petroleum-derived solvents creates margin compression risk for regional vendors. Distribution runs through direct sales relationships for complex instrumentation and e-procurement portals for transactional consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-connected instrumentation with predictive maintenance modules is displacing traditional hardware-only sales models, forcing stakeholders to recalibrate capital deployment strategies around recurring revenue architectures.
For Market Incumbents: Deepen backward integration into consumables production to capture replacement cycle revenue streams and defend against independent suppliers. Lock in multi-year service contracts through embedded calibration software that increases switching costs for mass spectrometry and chromatography platforms. Prioritize field service organization buildouts in Boston and San Diego biotech clusters where NIH funding sustains instrument refresh demand.
For New Entrants and Emerging Players: Contract development organizations building commercial-scale cell therapy capacity represent an underserved buyer archetype with underpenetrated demand for GMP-grade single-use bioreactor bags and aseptic connectors. India's PLI scheme for medical devices offers geographic entry point for sterile packaging producers seeking domestic manufacturing incentives. Lead with vendor-managed inventory systems that automate replenishment triggers based on reagent consumption patterns.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional consumables fabricators with ISO 17025 accreditation capabilities in European markets facing REACH compliance documentation burdens. Long-term viability hinges on software-defined analytics modules converging with traditional hardware. Watch NIST reference material program updates as inflection indicator for clinical-grade consumables procurement specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Consumables Backward Integration | In-house production of filtration membranes and chromatography columns secures recurring revenue streams. |
| Cloud-Native Platform Integration | Remote diagnostics modules converge with mass spectrometry hardware to enable predictive maintenance contracts. |
| Geographic Expansion to India | PLI scheme incentives attract sterile packaging producers to Hyderabad and Bengaluru biotech corridors. |
| Regulatory Certification Investment | FDA quality system regulation compliance opens pharmaceutical manufacturing procurement channels. |
| Strategic Partnership with Academic GPOs | Multi-year supply contracts with R1 universities capture NIH-funded genomic workflow demand. |
Research Approach
SEC 10-K filings, EMA good manufacturing practice validation records, and NIH funding disbursement databases formed the secondary backbone, supplemented by customs trade data for borosilicate glassware and reagent-grade chemical imports. Primary interviews with laboratory procurement managers at academic core facilities, field service engineers at analytical instrumentation vendors, GPO contracts managers, and biomedical engineers at hospital systems validated demand patterns and pricing structures. Bottom-up consumables volume estimates triangulated against top-down equipment installed base analysis.
Historical instrument refresh cycles and consumables replacement velocity informed trendline extrapolation across the analysis window. Segmentation dimensions modeled include product type, application, end user, and distribution channel, with regulatory complexity tier as an industry-specific overlay. CAGRs derived from NIH funding trajectory analysis, biotech venture deployment patterns, and CAP accreditation expansion timelines.
Revisions become necessary when FDA quality system regulation updates, REACH authorization expansions, or CLIA complexity recalibrations materially alter supplier qualification protocols. Forecasts reflect assumptions about sustained NIH appropriations and continued biotech clustering in established hubs. A model refresh is warranted upon material change in NIST reference material program specifications or India's PLI scheme incentive structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Histopathology Laboratory Equipment Market
Laboratory Equipment
North America Laboratory Hoods and Enclosure Market
Laboratory Equipment
UK Pipette Tips Market
Laboratory Equipment
Asia Pacific Cell Counting Market
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Global Laboratory Equipment and Disposables Market
Laboratory Equipment
Global Pipette Tips Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Colony Counters Market
Laboratory Equipment
Global Laboratory Hoods and Enclosure Market
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Muffle Laboratory Furnaces Market
Laboratory Equipment
Vacuum Tissue Processors Market
Laboratory Equipment
Capillary Blood Collection Tubes Market
Laboratory Equipment
Global Laboratory Plasticware Market