
 Cath Lab Market | 2026-2036
Cath Lab Market Size, Share, and Industry Trends Forecast 2026-2036
Cath Lab Market Analysis
Market Context with Strategic Players
Ambulatory surgical centers are redrawing cath lab demand as hospital systems decentralize elective interventional procedures. Siemens Healthineers leverages its imaging-integrated angiography platforms to dominate high-acuity installations across North America. Abbott Laboratories anchors its position through catheter and stent portfolios that compete directly in coronary intervention workflows. Philips sustains technology leadership in fluoroscopy-guided systems while navigating pricing pressures from integrated delivery networks.
Technical Definition and Structural Segments
A cath lab is a specialized procedure room equipped with angiography systems, patient monitoring arrays, and sterile instrumentation for minimally invasive cardiovascular and peripheral vascular interventions, typically operating with X-ray fluoroscopy at 15-30 frames per second for real-time vessel visualization. The primary purpose is diagnostic imaging and therapeutic delivery within the circulatory system without open surgery. Angiography systems command the largest capital expenditure share among product types, while interventional cardiology applications generate the highest procedure volume and associated consumables demand. Optical coherence tomography technology is expanding fastest for intravascular imaging, though fluoroscopy retains near-universal adoption due to lower per-procedure cost and established physician training pathways.
Regulatory Frame and Forward Outlook
FDA 510(k) clearance pathways govern angiography system and stent introductions in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for IVUS and OCT systems sold in Europe. ISO 13485 quality management certification has become a baseline threshold for supplier qualification by major hospital purchasing coalitions. Stakeholders must monitor whether CMS reimbursement adjustments for site-of-service differentials between hospital outpatient departments and ambulatory surgical centers will accelerate or constrain cath lab capital deployment.
Market Dynamics
Ambulatory surgical centers are decentralizing cath lab capacity away from hospital campuses, forcing equipment suppliers to reconfigure service models and pricing structures for lower-acuity settings with compressed installation footprints.
Growth Catalysts
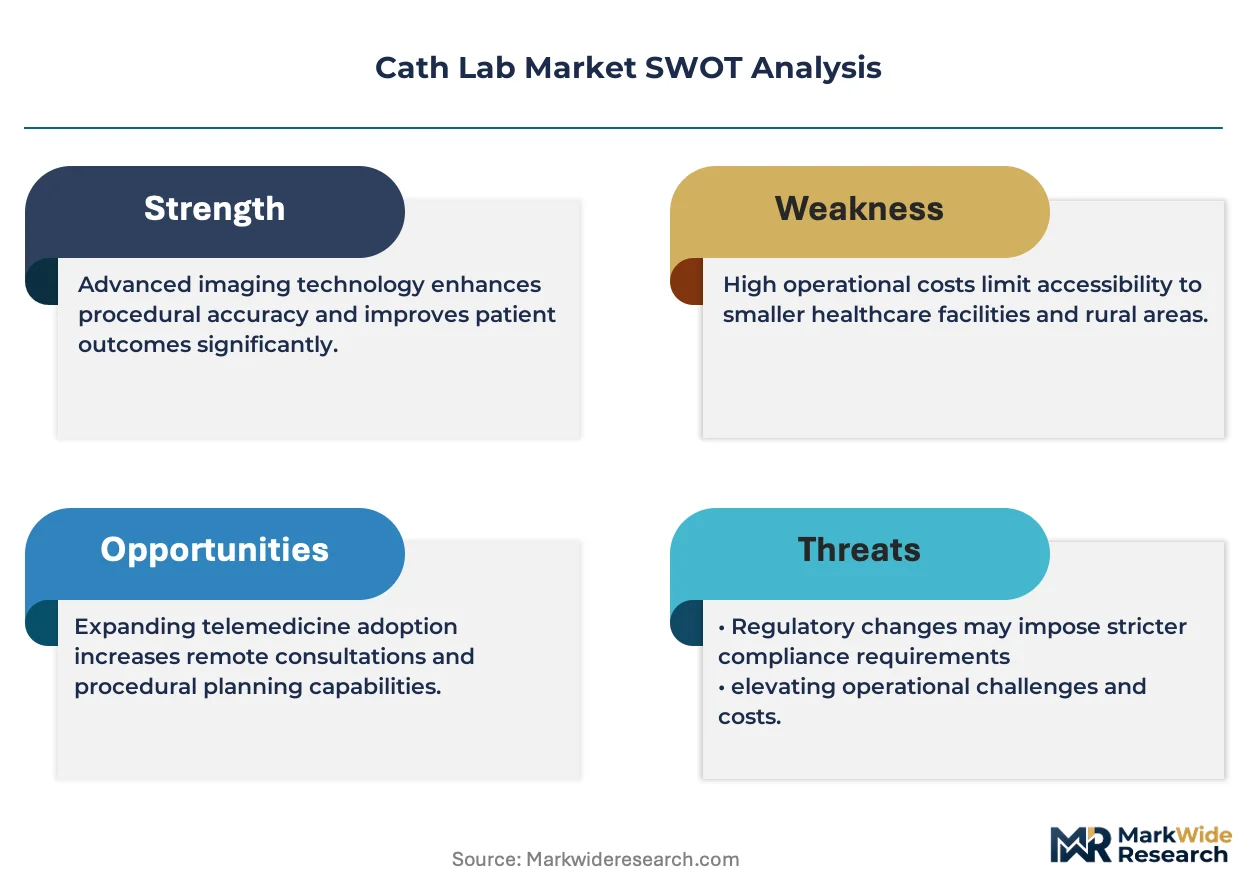
- Site-of-service reimbursement differentials:CMS payment adjustments favoring ASC-based cardiac catheterization are redirecting elective PCI volume from hospital outpatient departments, expanding addressable equipment demand.
- Optical coherence tomography integration:High-resolution intravascular imaging adoption is accelerating diagnostic precision requirements and driving complementary hardware upgrades in existing lab installations.
- Peripheral vascular intervention expansion:Rising diabetes prevalence in the United States is generating procedural demand for limb-salvage interventions that require dedicated angiography infrastructure.
Market Restraints
- Capital intensity barriers:Angiography system procurement requires $800,000-$2.5 million upfront investment, constraining ASC expansion in markets with limited financing access.
- Physician supply concentration:Interventional cardiologist training pipeline bottlenecks in rural United States regions limit procedural volume growth regardless of equipment availability.
- Fluoroscopy dose liability:OSHA radiation exposure monitoring requirements and associated litigation risk elevate operational compliance costs for high-volume operators.
Strategic Opportunities
- Refurbished system channels:Certified pre-owned angiography platforms are penetrating price-sensitive ASC segments previously excluded from new equipment markets.
- AI-powered image guidance:Machine learning-based vessel segmentation and stent sizing algorithms are creating differentiation opportunities against legacy fluoroscopy-only workflows.
- Hybrid operating room convergence:Cardiac surgery programs are integrating catheterization capability into surgical suites, expanding the addressable installed base beyond standalone cath labs.
Industry Challenges
- Interventional technologist shortages:Specialized radiologic technologist training programs are failing to keep pace with ASC expansion, creating staffing bottlenecks for new lab activations.
- Legacy PACS integration friction:New angiography systems face interoperability barriers with entrenched hospital imaging archives, extending deployment timelines and elevating IT consulting costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cath Lab Market |
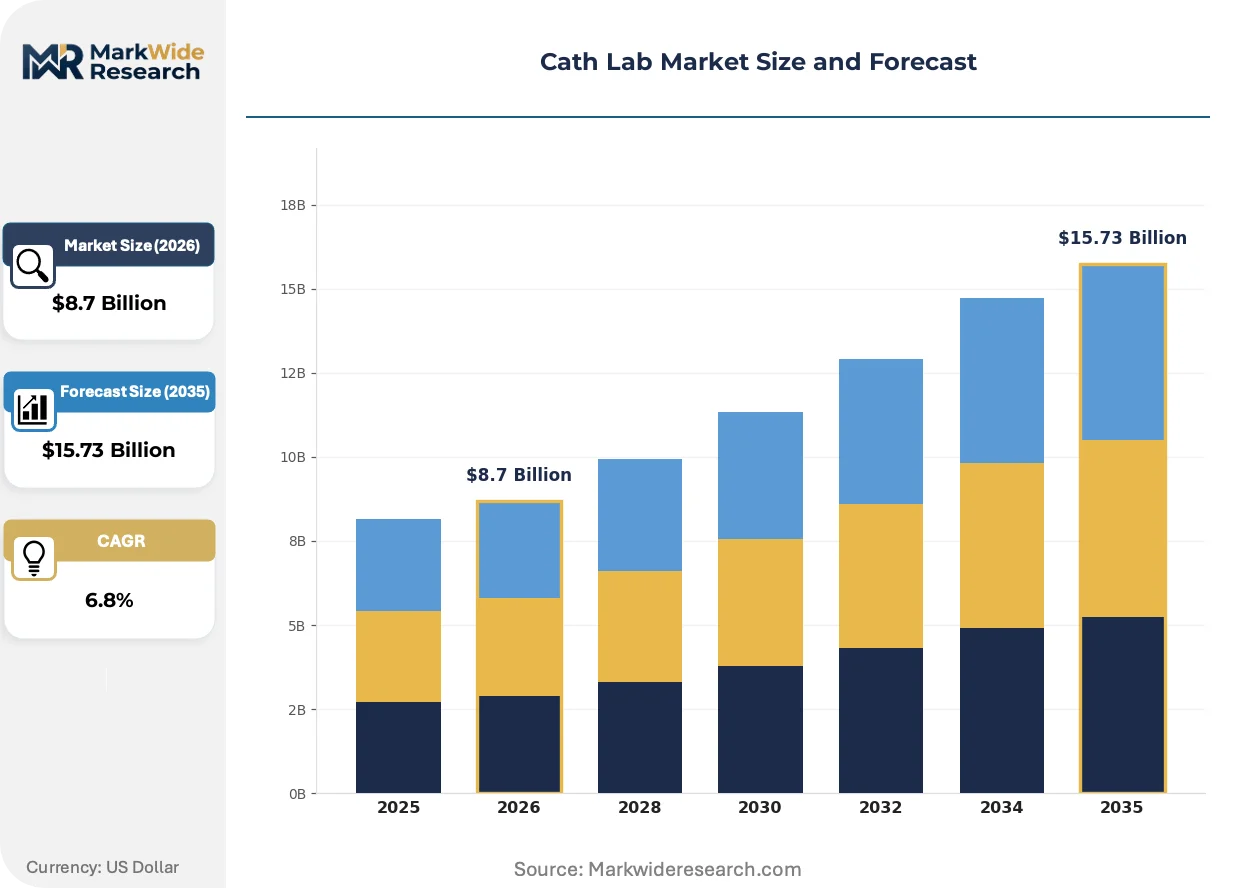
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angiography Systems, Catheters, IVUS Systems, Stents End User: Hospitals, Cardiology Centers, Ambulatory Surgical Centers, Diagnostic Labs Technology: Optical Coherence Tomography, Fluoroscopy, Magnetic Resonance Imaging, Computed Tomography Application: Coronary Angiography, Peripheral Angiography, Electrophysiology, Interventional Cardiology |
| Companies Covered | Medtronic, Boston Scientific Corporation, Siemens Healthineers, Shimadzu Corporation, Johnson & Johnson, Koninklijke Philips N.V., Abbott Laboratories, B. Braun Melsungen AG, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cath Lab Market Emerging Trajectories
Digital integration and workflow automation are compressing procedure times while expanding the clinical workforce eligible to operate cath lab equipment, fundamentally altering capital deployment logic for facility planners.
Intravascular ultrasound catheters are miniaturizing from 3.5 French to 2.6 French profiles while maintaining acoustic frequency bandwidth, enabling distal vessel access previously unreachable with conventional platforms. Community-based interventional programs are adopting these slim-profile systems to expand their anatomical case mix without referral to tertiary centers. Device miniaturization is compressing the functional differentiation between high-volume academic installations and mid-tier community labs.
FDA 510(k) clearance pathways for software-as-a-medical-device are tightening evidentiary requirements for AI-based angiographic analysis tools, extending development timelines for algorithm vendors. The agency's enhanced scrutiny of training dataset representativeness is forcing developers to expand demographic diversity in validation cohorts. European manufacturers are responding by front-loading clinical evidence generation to maintain parallel EU MDR compliance.
Integrated delivery networks are consolidating cath lab purchasing decisions into centralized capital committees, displacing individual hospital cath lab director autonomy in equipment selection. Physician preference items face heightened standardization pressure as IDNs negotiate enterprise-wide angiography system contracts. This concentration is most visible in the United States, where ten largest health systems now control over one-third of PCI volume.
Cath Lab Market Segmentation

Equipment procurement patterns in cath labs diverge sharply across facility types and procedure volumes, with capital intensity thresholds determining which segments absorb premium imaging platforms versus refurbished alternatives. Understanding these fault lines reveals where vendors must reconfigure service models and pricing architectures to capture expansion opportunities.
Product Type:
Margin pools concentrate in angiography systems where installed base lock-in generates multi-year service contracts and consumable pull-through.
- Angiography Systems:These X-ray fluoroscopy platforms integrate C-arm gantries, digital flat-panel detectors, and hemodynamic monitoring arrays at 15-30 frames per second acquisition rates. Hospital systems in the United States anchor demand for premium configurations with rotational angiography and 3D roadmap fusion, though ambulatory surgical centers are compressing specification requirements to hit sub-$1.5 million price points.
- Catheters:Diagnostic and guiding catheters span 4 French to 8 French profiles with hydrophilic coatings and torque-responsive shaft construction. Peripheral vascular programs in diabetes-prevalent regions are driving demand for long sheaths and support catheters that enable transradial access for limb-salvage procedures.
- IVUS Systems:Intravascular ultrasound consoles with 40-60 MHz rotational transducers deliver cross-sectional lumen morphology.
- Stents:Drug-eluting and bare-metal coronary platforms compete on deliverability and polymer biocompatibility profiles.
Angiography systems hold installed capacity. IVUS systems are rotating up the share rankings.
End User:
Volume concentration shifts toward outpatient settings where reimbursement differentials are rewriting site-of-service economics.
- Hospitals:Academic medical centers and community hospitals maintain the highest-acuity caseloads with hybrid operating room integration and 24/7 STEMI activation protocols. These installations demand premium system uptime guarantees and specialized interventional technologist staffing models that elevate operational overhead.
- Ambulatory Surgical Centers:Freestanding catheterization labs exploit CMS payment differentials for elective PCI and diagnostic angiography, operating with leaner teams and compressed physical footprints. Equipment suppliers are responding with remote service architectures and standardized configuration bundles that reduce installation complexity.
- Cardiology Centers:Physician-owned single-specialty facilities concentrate on outpatient diagnostic procedures.
- Diagnostic Labs:Imaging-only facilities without interventional capability focus on non-invasive vascular assessment.
Hospitals retain procedural volume leadership. Ambulatory surgical centers are climbing the fastest in new installation share.
Technology:
Adoption velocity separates legacy fluoroscopy dominance from emerging modalities competing on diagnostic precision.
- Optical Coherence Tomography:Near-infrared light interferometry achieves 10-20 micron resolution for stent apposition assessment and plaque characterization. Japanese and European interventional programs are expanding OCT-guided PCI protocols, though United States adoption remains constrained by incremental reimbursement and capital equipment requirements.
- Fluoroscopy:Pulsed and continuous X-ray transmission with flat-panel detection remains the universal backbone for real-time catheter navigation. Dose reduction algorithms and collimation automation are addressing OSHA radiation exposure monitoring requirements that elevate liability costs for high-volume operators.
- Magnetic Resonance Imaging:MR-guided catheterization enables zero-radiation structural heart procedures in specialized congenital programs.
- Computed Tomography:CT-fluoroscopy fusion supports pre-procedural planning for complex chronic total occlusion revascularization.
Fluoroscopy commands near-universal installed base. Optical coherence tomography is gaining share fastest among upgrade cycles.
Application:
Procedure reimbursement rates and clinical workforce availability determine where capital deployment concentrates within service line portfolios.
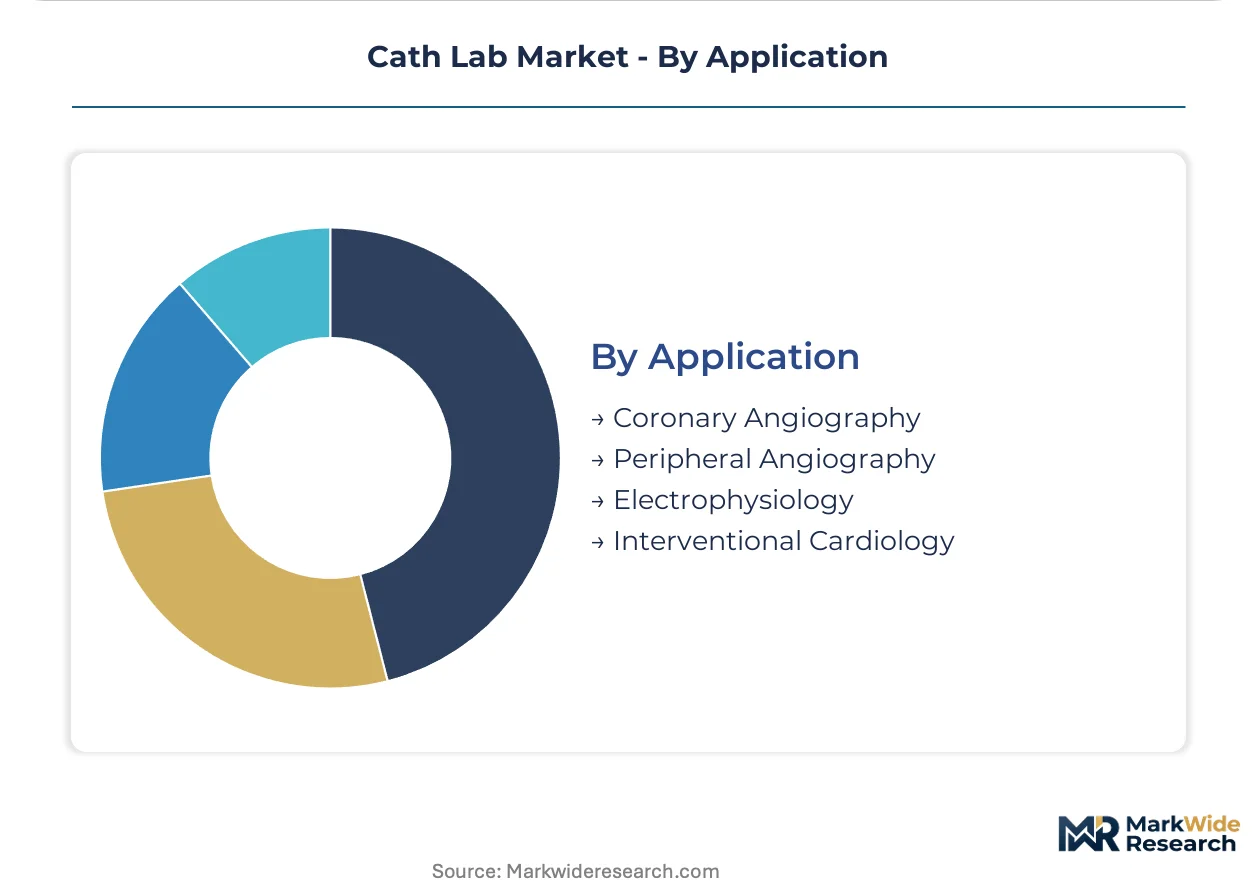
- Interventional Cardiology:Percutaneous coronary intervention with stent deployment generates the highest consumable throughput and physician productivity metrics. United States Medicare reimbursement structures favor hospital outpatient department site-of-service for complex multi-vessel cases, though ASC migration is accelerating for single-vessel elective procedures.
- Coronary Angiography:Diagnostic catheterization for chest pain evaluation and pre-surgical assessment maintains the largest procedure volume denominator. Transradial access adoption is compressing recovery times and enabling same-day discharge protocols that align with ambulatory surgical center operational models.
- Peripheral Angiography:Lower extremity runoff imaging supports limb-salvage intervention in diabetic populations.
- Electrophysiology:Ablation and device implantation procedures require specialized 3D electroanatomic mapping integration.
Interventional cardiology holds procedural revenue concentration. Peripheral angiography is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth logistics corridor underpins United States cath lab equipment distribution, with centralized warehousing feeding both coastal hospital systems and inland ambulatory surgical center expansions. Interstate highway density and cargo airport capacity determine manufacturer service response times across the lower forty-eight states.
United States
Medicare site-of-service reimbursement differentials are accelerating ambulatory surgical center catheterization capacity buildouts in Florida and Texas. FDA 510(k) premarket notification requirements govern angiography system introductions, extending product development timelines for software-integrated platforms. The Cleveland Clinic cardiovascular cluster anchors interventional cardiology training pipelines that supply physician talent to expanding Midwest ASC networks.
Germany
EU Medical Device Regulation clinical evidence requirements are reshaping intravascular imaging system approval pathways for manufacturers serving European markets. The country's statutory health insurance reimbursement framework maintains hospital outpatient department preference for complex PCI cases. Siemens Healthineers maintains its global headquarters and primary manufacturing footprint in Erlangen, anchoring Bavaria's medical imaging industrial cluster.
Japan
PMDA regulatory pathways for optical coherence tomography systems are accelerating faster than FDA equivalents, enabling earlier adoption of high-resolution intravascular imaging protocols. METI industrial policy supports domestic angiography equipment manufacturing through targeted R&D subsidies. The Tokyo-Osaka medical corridor concentrates interventional cardiology procedure volume and associated capital equipment demand.
India
CDSCO medical device registration requirements are tightening quality management system expectations for imported angiography platforms entering the domestic market. PLI scheme incentives for domestic manufacturing are attracting cath lab equipment assembly investments to Gujarat and Karnataka. Apollo Hospitals and Max Healthcare are expanding catheterization capacity in Delhi-NCR and Hyderabad to capture outbound medical tourism revenue.
Brazil
ANVISA regulatory harmonization with international standards is streamlining angiography system import licensing for multinational suppliers. Private health insurance reimbursement rates favor hospital-based cardiac catheterization over ambulatory alternatives, constraining ASC penetration. São Paulo's Hospital das Clínicas complex anchors the country's interventional cardiology training and referral infrastructure.
Cath Lab Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity tiers, with publicly traded conglomerates dominating high-acuity system installations while private equipment fabricators capture price-sensitive refurbishment channels. The vendor base stratifies into three tiers: integrated imaging conglomerates with multi-modality portfolios, catheter and stent specialists with consumable-heavy revenue models, and regional equipment assemblers serving emerging markets. Archetypes include full-stack platform providers, disposable-focused intervention specialists, and certified pre-owned system refurbishers. Competitive moves concentrate on enterprise-wide purchasing contract consolidation and AI-powered image guidance differentiation.
Within the integrated imaging tier, Siemens Healthineers and Koninklijke Philips N.V. exemplify platform providers with angiography-fluoroscopy convergence capabilities. Abbott Laboratories occupies a position among intervention-focused specialists with catheter and stent portfolios that compete directly in coronary workflows. Among diversified health technology conglomerates, GE Healthcare represents the archetype of imaging equipment suppliers navigating pricing pressure from consolidated delivery networks. These three anchors demonstrate how competitive positioning depends on whether revenue concentrates in capital equipment, consumables, or hybrid service models.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Siemens Healthineers |
| Shimadzu Corporation |
| Johnson & Johnson |
| Koninklijke Philips N.V. |
| Abbott Laboratories |
| B. Braun Melsungen AG |
| GE Healthcare |
| Others |
Supply Flow & Price Mechanics
Flat-panel detector substitution for legacy image intensifiers simultaneously redraws supplier geography toward East Asian sensor fabrication clusters and compresses per-unit pricing curves for mid-tier angiography configurations. This component transition concentrates cost negotiation leverage with IDN procurement committees while fragmenting sourcing strategies across ASC and hospital tiers.
Pricing Analysis
Volume-discount tiering structures dominate enterprise purchasing, with three-tier pricing separating premium rotational angiography systems from standard fluoroscopy platforms and economy refurbished alternatives. Price differentiation rests on FDA 510(k) clearance tier and ISO 13485 certification status, with brand premiums persisting for Siemens Healthineers and Philips installations. Cost compression in the economy tier intensifies because certified pre-owned channels expand inventory liquidity. Ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers prioritize uptime guarantees over capital outlay.
Supply Chain Analysis
Strategic stockpiling of X-ray tubes and high-voltage generators characterizes hospital system procurement, contrasting with just-in-time consumable replenishment for catheter and stent inventories. Manufacturing concentrates in Germany, Japan, and the United States for angiography system final assembly, while China and South Korea anchor flat-panel detector substrate production. Supply chains draw from rare earth elements for scintillator crystals, precision bearings for C-arm gantries, and semiconductor components for image processing. Single-source vulnerability in rotating anode X-ray tube supply elevates risk exposure. Distribution runs through regional service hubs with field engineer deployment for installation and maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation, with ten largest United States health systems now controlling over one-third of PCI volume and displacing individual cath lab director autonomy.
For Market Incumbents: Shield installed base lock-in through multi-year service contract extensions and proprietary software ecosystem tethering. Deepen backward integration into AI-powered image guidance development to differentiate against algorithm vendors. Defend against refurbished system channel erosion by introducing certified pre-owned programs with factory warranty coverage. For New Entrants and Emerging Players: Anchor in ambulatory surgical center expansion corridors where price sensitivity and compressed installation timelines create white-space opportunity. Target peripheral vascular intervention applications in diabetes-prevalent regions with slim-profile IVUS catheter offerings. Pursue GPO contract participation as the primary go-to-market pathway for hospital system penetration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed refurbished equipment specialists and AI algorithm developers awaiting FDA 510(k) clearance resolution. Long-term viability centers on software-integrated platform convergence rather than standalone hardware manufacturing. Monitor CMS site-of-service reimbursement adjustments as the critical inflection signal for ASC capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates angiography system market entry while imposing evidentiary requirements on software-integrated platforms. |
| Hospital System Partnership | Secures enterprise-wide purchasing contracts with IDNs that displace physician preference item autonomy. |
| Software Companion Development | Enables AI-powered vessel segmentation and stent sizing algorithms that differentiate against legacy fluoroscopy workflows. |
| Reimbursement Strategy | Aligns ASC site-of-service economics with CMS payment differentials for elective PCI migration. |
| CE Marking Pathway | Opens European market access under EU MDR clinical evidence requirements for IVUS and OCT systems. |
Methodological Framework
Desk research of FDA 510(k) filings, CMS reimbursement databases, and hospital procurement records preceded structured interviews with interventional cardiologists, biomedical engineers, GPO contracts managers, and ASC operations directors. Primary fieldwork with equipment suppliers and IDN capital committees combined with secondary validation against ISO 13485 certification registries and trade customs data. Bottom-up procedure volume modeling triangulated against top-down capital expenditure estimates across the analysis window.
Variance-decomposition framing separated volume growth from price-mix effects across product type, end user, technology, and application segmentations. CAGRs derived from logistic diffusion curves for technology adoption and replacement cycle assumptions for installed base turnover. Forecast inputs incorporated interventional cardiologist training pipeline constraints and site-of-service reimbursement elasticity parameters.
Decision-makers should treat outputs as directional under stable CMS reimbursement policy and steady interventional workforce expansion assumptions; material deviation would warrant model refresh. Revision becomes warranted when ASC site-of-service payment differentials or AI software regulatory pathways cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Blood Bank Refrigerators Market
Medical Equipment
Medical Vending Machines Market
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
Sanitary Napkin Equipment Market
Medical Equipment
Global Refrigerated Incubators Market
Medical Equipment
Asia-Pacific Nuclear Medicine Equipment Market
Medical Equipment
Autopsy Saw Market
Medical Equipment
Global Medical Carts Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Equine Operating Tables Market
Medical Equipment
US Durable Medical Equipment Market
Medical Equipment
Europe Medical Device Reprocessing Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Global Stereotactic Radiosurgery (Gamma Knife) Market