
 Laboratory Vacuum Drying Oven Market | 2026-2036
Laboratory Vacuum Drying Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Vacuum Drying Oven Market Insights
Contract research organizations is reorganizing procurement priorities for laboratory vacuum drying ovens as biopharma outsourcing deepens. Thermo Fisher Scientific leverages its distribution density across North American research corridors to sustain instrument placement rates. Binder GmbH anchors its position through precision temperature uniformity specifications that differentiate it in European pharmaceutical quality control labs. Yiheng Scientific Instruments competes on cost-engineered bench-top configurations for academic institutes in Asia-Pacific.
A laboratory vacuum drying oven removes moisture from heat-sensitive materials by reducing chamber pressure to lower boiling points, typically operating between 5 mbar and atmospheric pressure with temperature ranges from 40°C to 250°C depending on thermal sensitivity of the substrate. Floor-standing units dominate capital deployment in pharmaceutical research facilities where batch volumes exceed bench-scale limits, while infrared heating technology captures margin pools from polymer testing applications requiring rapid thermal ramp rates without oxidative degradation. Conventional heating retains volume leadership across academic institutes where equipment budgets constrain technology selection.
FDA validation guidelines for pharmaceutical manufacturing equipment shape design requirements for vacuum drying ovens deployed in GMP environments, while REACH substance restrictions influence seal and gasket material selections in European supply chains. ISO 9001 quality management certification functions as a baseline market access credential for original equipment manufacturers serving contract research organizations. Stakeholders must monitor evolving EMA Annex 15 qualification standards and dual carbon goals in China as these frameworks progressively redefine energy efficiency benchmarks and documentation burdens for thermal processing equipment.
Market Dynamics
Pharmaceutical quality control protocols are tightening thermal processing tolerances, forcing equipment manufacturers to recalibrate chamber uniformity specifications and validation documentation workflows for GMP-compliant installations.
Growth Catalysts
- EMA Annex 15 qualification standards:European pharmaceutical manufacturers are accelerating replacement cycles for aging thermal equipment to meet evolving qualification benchmarks for critical process parameters.
- Biopharma manufacturing clusters:Concentrated investment in Germany, China, and the United States is generating sustained capital deployment for floor-standing vacuum drying systems in multi-product facilities.
- Infrared heating modules:Polymer testing laboratories are specifying rapid thermal ramp configurations to prevent oxidative degradation in temperature-sensitive substrate analysis.
Market Restraints
- Stainless steel input volatility:Chamber construction costs fluctuate with commodity pricing for corrosion-resistant alloys specified in pharmaceutical-grade equipment.
- European supply concentration:REACH-compliant seal and gasket material sourcing is narrowing to certified suppliers within EU regulatory jurisdiction.
- Conventional heating retention:Academic budget constraints perpetuate demand for lower-cost thermal technologies despite performance limitations.
Strategic Opportunities
- China dual carbon goals:Energy efficiency mandates are creating replacement demand for legacy equipment in research institutes pursuing carbon neutrality targets.
- Contract research organization channel expansion:Outsourced pharmaceutical development is concentrating procurement authority with CMOs managing multi-site equipment standardization.
- Bench-top configuration convergence:Academic institutes in Asia-Pacific are specifying compact units with digital data logging for teaching laboratory modernization.
Industry Challenges
- Thermal validation engineering capacity:Pharmaceutical manufacturers face extended commissioning timelines due to scarcity of technicians proficient in IQ/OQ/PQ documentation for vacuum thermal systems.
- Legacy control system integration:Facilities with established building management architectures encounter protocol compatibility barriers when deploying ovens with modern digital interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Vacuum Drying Oven Market |
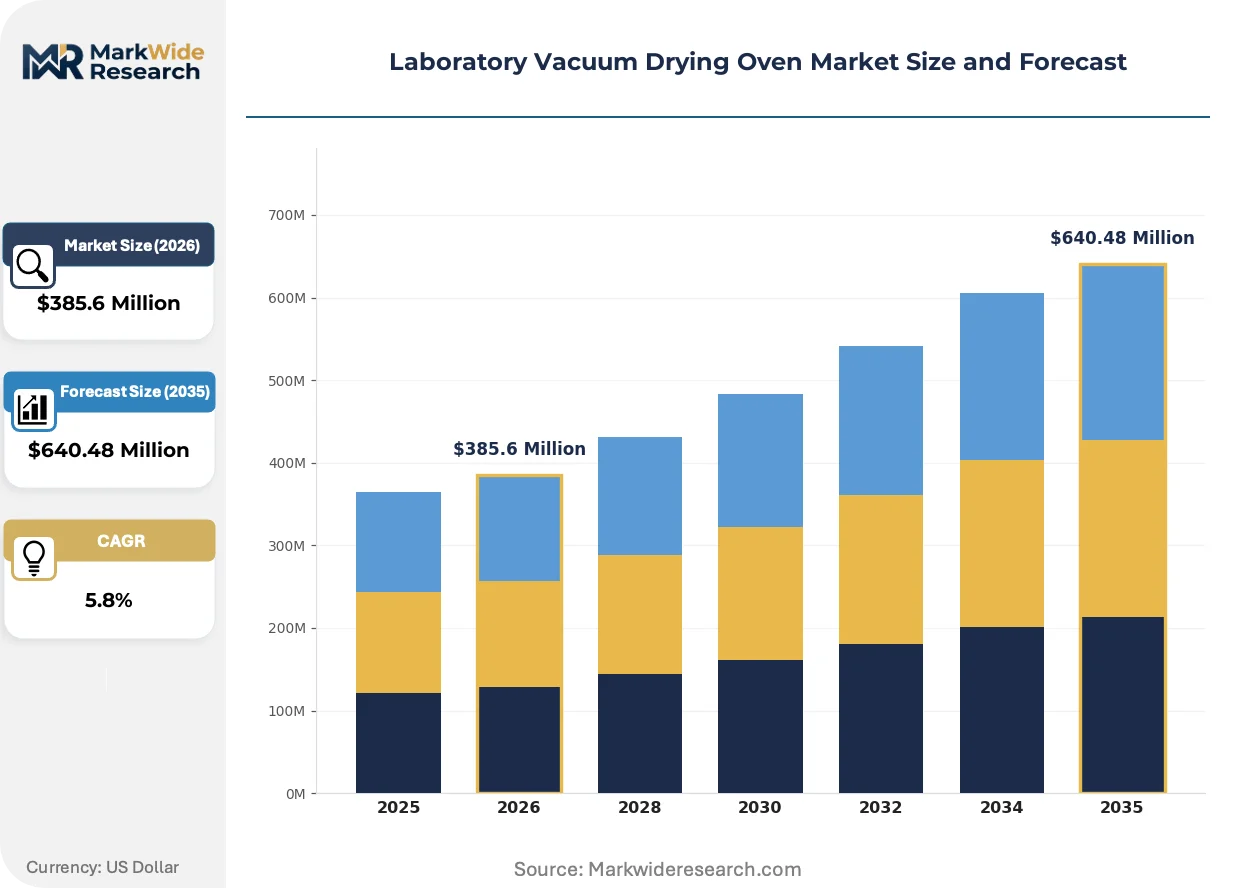
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench-Top, Floor-Standing, Portable, Vacuum Oven Chambers Technology: Conventional Heating, Infrared Heating, Microwave Heating, Ultrasonic Heating Application: Biochemical Analysis, Pharmaceutical Research, Polymer Testing, Food Quality Control End User: Research Labs, Academic Institutes, Quality Control Units, Contract Research Organizations |
| Companies Covered | Across International, Yiheng Scientific Instruments, Thermo Fisher Scientific, Yamato Scientific, Nanbei Instruments, Binder GmbH, BOXUN, Carbolite Gero, Memmert GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Vacuum Drying Oven Market Trends and Innovations
Equipment architecture is fragmenting along performance-versus-cost axes as divergent end-use requirements reshape R&D investment priorities and manufacturing scale configurations.
Infrared heating technology is bifurcating the product landscape between premium rapid-thermal systems and conventional conductive configurations. Polymer research facilities and materials science departments are specifying infrared modules for applications requiring precise ramp rate control without atmospheric oxidation. This thermal modality is compressing cycle times in quality control workflows while commanding margin premiums that conventional heating cannot sustain.
REACH substance restrictions are mandating fluoropolymer-free seal materials in European supply chains. Equipment manufacturers are requalifying chamber gasket specifications to maintain CE marking compliance under evolving chemical hazard classifications. Pharmaceutical OEMs serving EMA-regulated facilities are absorbing material conversion costs while accelerating documentation updates for existing installed bases.
Service contract unbundling is separating preventive maintenance from capital acquisition in CRO procurement frameworks. Large contract research organizations are negotiating multi-year calibration and validation service agreements independent of initial equipment purchase. This purchasing pattern is most visible in North American biopharma corridors where asset utilization rates justify dedicated technical support staffing.
Laboratory Vacuum Drying Oven Market Segmentation
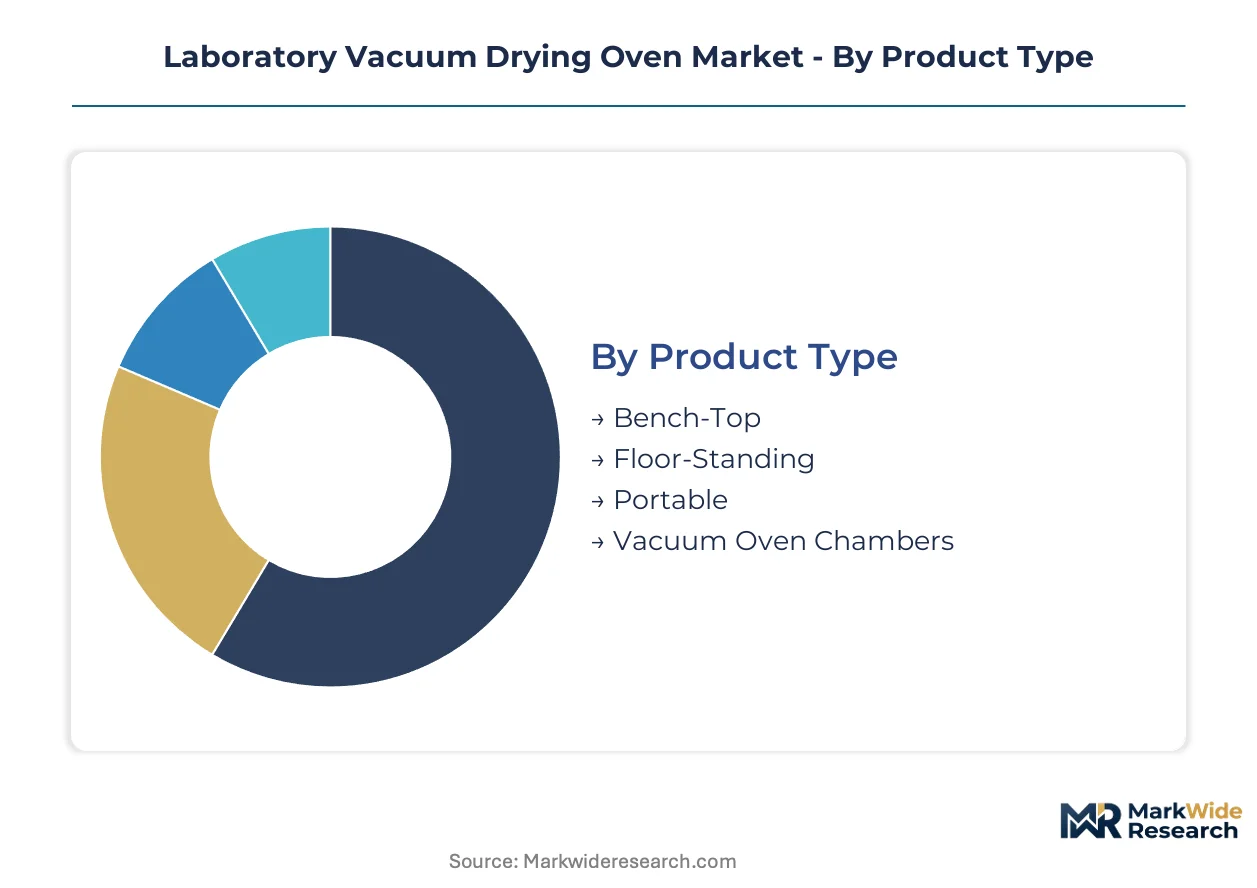
Equipment configuration and thermal modality choices in laboratory vacuum drying ovens reflect divergent end-use priorities across pharmaceutical manufacturing, academic research, and industrial quality control. Segmentation reveals where capital deployment concentrates and which specifications command margin premiums.
Product Type:
Substitution pressure from compact modular systems is reshaping capital allocation across facility scales, with bench configurations threatening floor-standing dominance in mid-volume applications.
- Bench-Top:Compact units designed for limited workspace and sample volumes, typically accommodating 20-60 liter chamber capacities. Demand concentrates in academic institutes across China and India where equipment budgets constrain procurement authority, with digital data logging specifications accelerating replacement cycles in teaching laboratories. Bench-top configurations anchor the volume base while portable systems gain share at the steepest rate.
- Floor-Standing:High-capacity installations exceeding 200 liters for batch processing in multi-product pharmaceutical facilities. Investment clusters in Germany's Rhine-Main biopharma corridor and Massachusetts research hubs where GMP validation requirements necessitate dedicated floor space and specialized commissioning protocols.
- Portable:Mobile configurations with castor-mounted chassis for field deployment and temporary laboratory setups. Field research stations and mobile testing units in Australia and Canada specify these for remote sample processing where fixed infrastructure is unavailable.
- Vacuum Oven Chambers:Modular chamber systems for integration into custom thermal processing lines. Custom equipment integrators in Switzerland and the Netherlands deploy these for specialized pharmaceutical drying workflows requiring non-standard chamber geometries.
Floor-standing units retain the largest installed base while portable configurations expand most quickly in field research applications.
Technology:
Cost tier stratification separates premium rapid-thermal modalities from established conductive heating, with infrared modules commanding substantial price premiums in polymer research workflows.
- Conventional Heating:Resistive heating elements with conductive thermal transfer, the established standard for budget-constrained procurement. Academic institutes in Brazil and Mexico perpetuate demand despite slower ramp rates and inferior temperature uniformity, as capital limitations override performance specifications.
- Infrared Heating:Radiant thermal modules enabling precise ramp rate control without oxidative degradation. Polymer testing laboratories in Germany and Japan specify these configurations for temperature-sensitive substrate analysis, accepting substantial cost premiums for cycle time compression and sample integrity protection. Infrared heating anchors the margin base while ultrasonic heating gains share fastest in specialized materials processing.
- Microwave Heating:Dielectric heating for rapid moisture removal in specific substrate categories. Food quality control facilities in France and Italy deploy these for agricultural product testing where volumetric heating accelerates drying protocols.
- Ultrasonic Heating:Acoustic energy-assisted drying for fragile biological specimens. Niche applications in Swiss and Danish pharmaceutical research facilities processing heat-labile compounds where conventional thermal methods risk denaturation.
Conventional heating retains volume leadership while infrared configurations capture the steepest margin expansion trajectory.
Application:
Application-driven demand concentrates in quality control workflows where regulatory validation requirements elevate equipment specifications and extend replacement cycles.
- Biochemical Analysis:Drying protocols for enzyme preparations, protein crystals, and cellular materials requiring precise thermal control. Research labs in Singapore and South Korea specify these for proteomics workflows where moisture removal must preserve biological activity.
- Pharmaceutical Research:Active pharmaceutical ingredient drying and formulation development under GMP documentation requirements. Manufacturing clusters in New Jersey and Basel drive capital deployment for validated thermal systems with complete IQ/OQ/PQ documentation packages. Pharmaceutical research anchors the revenue base while polymer testing climbs the fastest in materials science expansion.
- Polymer Testing:Thermal processing of synthetic and natural polymers for mechanical property validation. Testing laboratories in Germany and the United States specify infrared-equipped systems to prevent oxidative degradation during thermal cycling.
- Food Quality Control:Moisture content determination in agricultural and processed food products. Regulatory laboratories in Italy and Spain deploy these for EU-compliant food safety testing under EFSA methodological standards.
Pharmaceutical research commands the largest equipment investment while polymer testing demonstrates the steepest adoption acceleration.
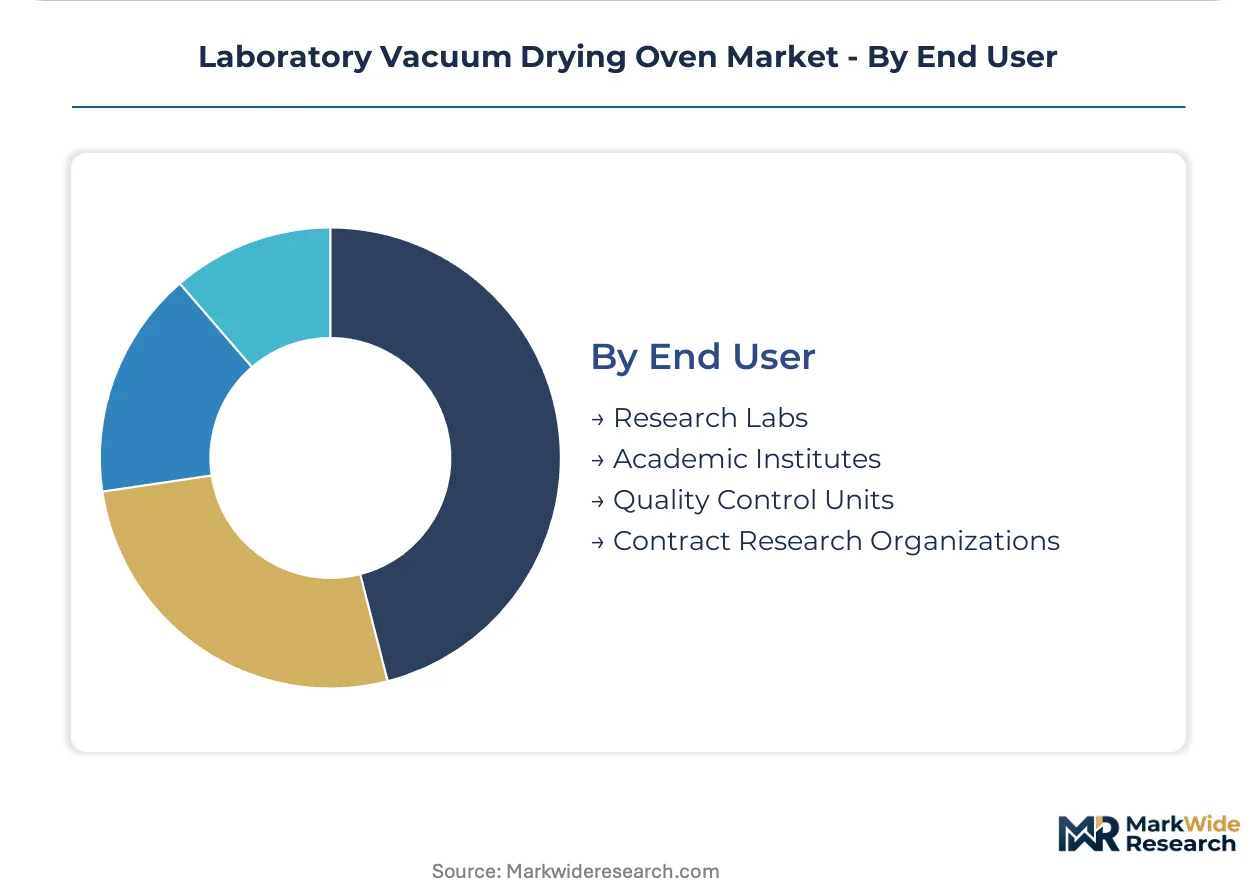
End User:
Customer type segmentation reveals divergent procurement authority structures, with contract research organizations consolidating multi-site standardization decisions.
- Research Labs:Corporate and government R&D facilities with dedicated capital budgets for specialized equipment. National laboratories in the United States and Max Planck institutes in Germany maintain dedicated thermal processing infrastructure for proprietary research programs.
- Academic Institutes:Universities and teaching hospitals with constrained procurement authority and extended replacement cycles. Institutions across India and Vietnam prioritize cost-engineered bench-top configurations for undergraduate laboratory instruction. Academic procurement anchors the volume base while contract research organization demand expands most rapidly.
- Quality Control Units:In-house testing departments within manufacturing organizations. Pharmaceutical manufacturers in Ireland and Puerto Rico maintain validated vacuum drying capacity for release testing under FDA and EMA guidelines.
- Contract Research Organizations:Outsourced service providers managing multi-site equipment standardization for pharmaceutical clients. Large CROs in North Carolina and Bavaria negotiate enterprise-wide thermal equipment specifications to ensure cross-facility method transferability.
Academic institutes sustain the broadest installed base while contract research organizations drive the steepest procurement volume acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters for laboratory vacuum drying ovens concentrate in Germany, China, and the United States, with regulatory validation requirements in pharmaceutical hubs driving specification divergence across these supply centers.
Germany
EMA Annex 15 qualification standards accelerate replacement demand for thermal equipment in pharmaceutical quality control labs. REACH substance restrictions mandate fluoropolymer-free seal materials, narrowing compliant supplier networks to certified EU vendors. The Rhine-Main biopharma corridor sustains capital deployment for floor-standing GMP-validated systems.
United States
FDA validation guidelines shape design requirements for vacuum drying ovens deployed in contract research organizations and multi-product manufacturing facilities. Massachusetts and New Jersey research hubs generate concentrated procurement of validated thermal systems with complete IQ/OQ/PQ documentation. Thermo Fisher Scientific leverages distribution density across North American research corridors to sustain instrument placement rates.
China
Dual carbon goals create replacement demand for legacy equipment in research institutes pursuing carbon neutrality targets. NMPA and GB standards elevate equipment validation benchmarks for biopharma manufacturing clusters expanding in Shanghai and Suzhou. Yiheng Scientific Instruments competes on cost-engineered bench-top configurations for academic institutes across Asia-Pacific.
Japan
METI energy efficiency directives and PMDA pharmaceutical manufacturing standards elevate thermal processing equipment specifications. Yamato Scientific anchors domestic supply for polymer testing laboratories requiring precise ramp rate control. Tokyo and Osaka materials science departments specify infrared-equipped systems for temperature-sensitive substrate analysis.
Switzerland
Swissmedic pharmaceutical regulations and precision manufacturing traditions sustain demand for high-specification vacuum thermal systems. Basel's pharmaceutical research cluster drives investment in validated equipment for active pharmaceutical ingredient drying. Custom equipment integrators deploy modular vacuum oven chambers for specialized pharmaceutical drying workflows requiring non-standard geometries.
Laboratory Vacuum Drying Oven Market Competitive Landscape
Concentration sits with diversified laboratory equipment conglomerates and specialized thermal processing manufacturers. The vendor base spans three tiers: multinational life sciences conglomerates with broad distribution networks, mid-cap European precision engineering specialists, and cost-optimized Asian fabricators serving academic procurement channels. Strategic archetypes include validation-focused pharmaceutical specialists, rapid-thermal technology innovators, and volume-driven bench-scale producers. Competitive moves center on service contract unbundling and multi-site standardization partnerships with contract research organizations.
Among diversified life sciences conglomerates, Thermo Fisher Scientific exemplifies the scale-driven archetype with extensive North American distribution infrastructure. German precision engineering specialists Binder GmbH and Memmert GmbH occupy positions defined by temperature uniformity specifications and EMA-compliant validation documentation. Chinese fabricators Yiheng Scientific Instruments and Nanbei Instruments represent the cost-optimized tier, targeting academic procurement channels across Asia-Pacific with compact bench-top configurations.
| Leading Market Players |
|---|
| Across International |
| Yiheng Scientific Instruments |
| Thermo Fisher Scientific |
| Yamato Scientific |
| Nanbei Instruments |
| Binder GmbH |
| BOXUN |
| Carbolite Gero |
| Memmert GmbH |
| Others |
Pricing and Supply Chain Analysis
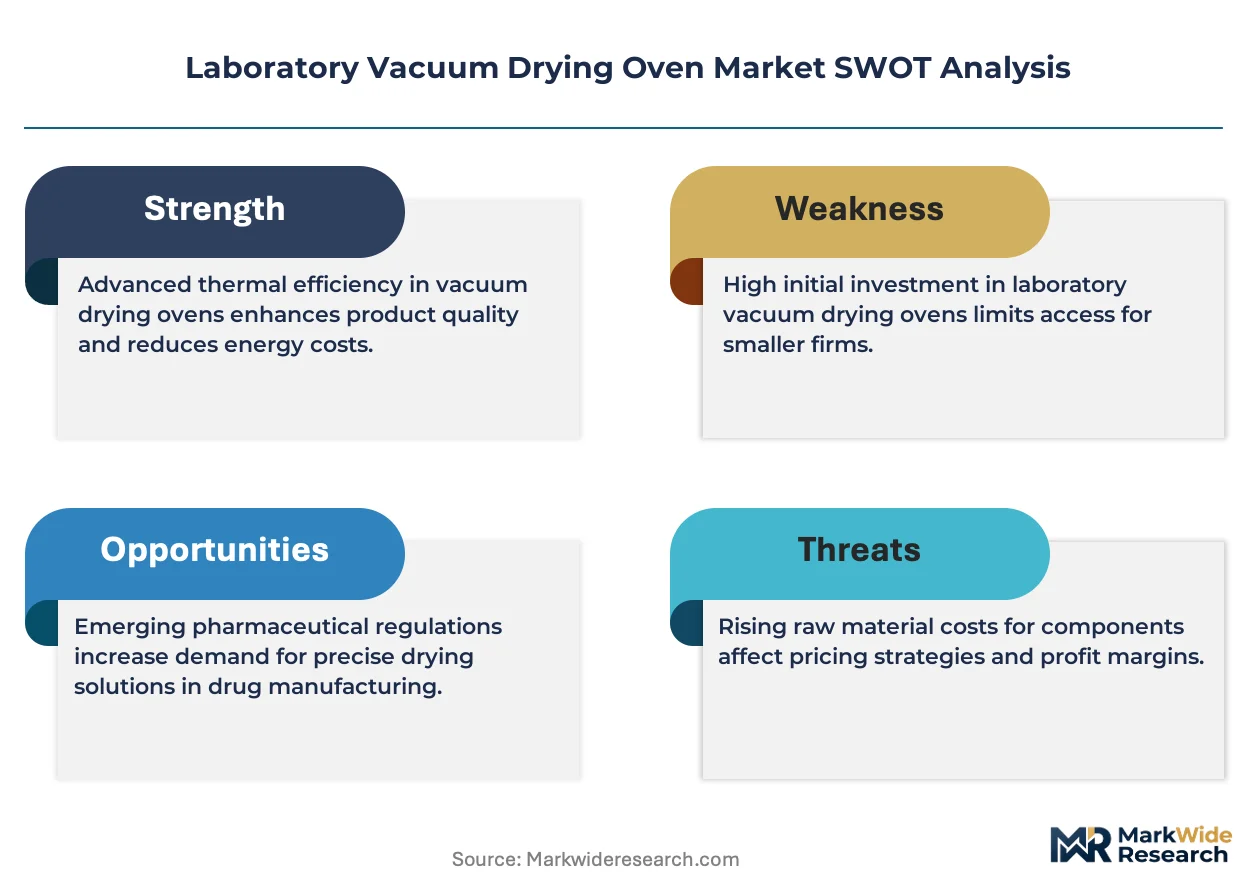
EMA Annex 15 qualification standards gate both supplier qualification and price differentiation simultaneously, forcing pharmaceutical-grade equipment manufacturers to absorb compliance costs while commanding validation premiums that budget-tier alternatives cannot access.
Pricing Analysis
FDA validation guidelines dictate the pricing tier structure across the laboratory vacuum drying oven market. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated floor-standing systems with complete IQ/OQ/PQ documentation from bench-scale academic units and portable field configurations. Cost compression in economy tiers is intensifying because Chinese fabricators are scaling production of compact units for Asia-Pacific teaching laboratories. Academic institutes in India and Vietnam exhibit the highest price sensitivity, while contract research organizations in Massachusetts and Bavaria prioritize validation completeness over unit economics.
Supply Chain Analysis
Stainless steel alloy procurement from German and Japanese specialty mills underwrites chamber construction quality for pharmaceutical-grade equipment. Corrosion-resistant 316L stainless steel, fluoropolymer-free gasket materials, and precision temperature control modules anchor component sourcing. Single-source vulnerability concentrates in REACH-compliant seal suppliers certified within EU regulatory jurisdiction. Distribution runs through laboratory equipment distributors with validated service capabilities in biopharma manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as contract research organizations consolidate multi-site procurement authority, creating niche openings for specialized validation service providers and rapid-thermal technology innovators.
For Market Incumbents: Consolidate service contract unbundling capabilities to capture recurring revenue from CRO calibration and validation agreements. Deepen backward integration into precision temperature control module production to defend margin position against infrared heating technology displacement. Anchor capacity expansion in China's Suzhou biopharma corridor to intercept dual carbon-driven replacement demand. For New Entrants and Emerging Players: Anchor in portable vacuum drying configurations for field research stations in Australia and Canada where mobile infrastructure gaps persist. Target polymer testing laboratories in Germany and Japan specifying infrared-equipped systems for oxidative degradation-sensitive substrates. Pursue digital data logging integration as the primary go-to-market angle for Asia-Pacific academic modernization cycles. For Investors and Strategic Acquirers: NMPA and GB standard elevation reshapes the acquisition landscape toward validation-capable equipment manufacturers serving China's expanding biopharma manufacturing base. Long-term viability favors precision engineering specialists with established EMA-compliant documentation workflows over pure-play cost optimizers. Monitor EMA Annex 15 revision timelines as the critical signal for European replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Documentation Unbundling | Separates IQ/OQ/PQ packages from capital sales to capture CRO recurring revenue streams. |
| Infrared Heating Module Integration | Enables polymer testing laboratories to command cycle-time premiums in materials science workflows. |
| REACH-Compliant Material Conversion | Maintains CE marking access while absorbing fluoropolymer-free gasket requalification costs. |
| Multi-Site CRO Partnership Structuring | Secures enterprise-wide equipment standardization contracts across North Carolina and Bavaria corridors. |
| Bench-Top Digital Data Logging Upgrade | Accelerates replacement cycles in China and India teaching laboratories pursuing modernization. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical quality control units, contract research organization procurement directors, academic laboratory managers, and thermal equipment maintenance technicians. Secondary validation drew from FDA 483 inspection observations, EMA qualification guidance documents, NMPA equipment registration databases, and ISO 9001 certification registries. Bottom-up equipment shipment analysis triangulated against top-down biopharma capital expenditure disclosures.
Across the analysis window, the forecasting framework modeled product type segmentation by chamber capacity tier, thermal modality by heating technology, application by regulatory validation requirement, and end user by procurement authority structure. CAGRs were derived from replacement cycle analysis correlated with regulatory revision timelines. Forecast inputs incorporated stainless steel commodity price trajectories and EMA Annex 15 implementation pace assumptions.
Material uncertainties — regulatory revision timing, commodity alloy price volatility, and CRO consolidation pace — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as dual carbon goal enforcement intensity and REACH substance restriction scope evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Laboratory Pulverizer Market
Laboratory Equipment
Blood Testing Equipment Market
Laboratory Equipment
Vacuum Blood Collection Tube Market
Laboratory Equipment
Micropipette Puller Market
Laboratory Equipment
Global Blood Gas Analyzers Market
Laboratory Equipment
Microplate Handling Instruments Market
Laboratory Equipment
Benchtop Centrifuges Market
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Cuvettes Market
Laboratory Equipment
Laboratory Fume Hoods Market
Laboratory Equipment
Scalable Clinical Chemistry Analyzers Market
Laboratory Equipment
C-Reactive Protein Analyzers Market
Laboratory Equipment
Laboratory Refrigerators and Ovens Market
Laboratory Equipment
Laboratory Temperature Control Units Market