
 Scalable Clinical Chemistry Analyzers Market | 2026-2036
Scalable Clinical Chemistry Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Scalable Clinical Chemistry Analyzers Market Insights
High-throughput specification tiers is unwinding legacy procurement patterns in clinical chemistry. Roche leverages its installed base of modular platforms to sustain recurring reagent revenue across major health systems. Siemens Healthineers anchors its position through deep integration with hospital informatics networks. Beckman Coulter differentiates via manufacturing scale that supports rapid turnaround on large-volume analyzer contracts.
Scalable clinical chemistry analyzers are automated instruments that process biochemical assays on patient samples, typically handling throughput from 200 to over 2,000 tests per hour with photometric detection at wavelengths spanning 340–800 nm. Their primary commercial purpose is to deliver standardized, high-volume diagnostic results while minimizing manual sample handling and reducing operator-dependent variability. Floor-standing analyzers capture the dominant share of capital expenditure as laboratories prioritize throughput density per square meter of laboratory space. Immunoassay technology integration represents the fastest-growing configuration, driven by demand for consolidated chemistry-immunoassay workflows that reduce sample aliquoting steps.
FDA quality system regulation and CLIA proficiency testing requirements shape analyzer design priorities, particularly around traceability of calibrators and built-in quality control protocols. ISO 15189 accreditation standards for medical laboratories create downstream pressure on manufacturers to deliver instruments with comprehensive audit trails and automated quality management features. Stakeholders must monitor how emerging CMS reimbursement rules for laboratory-developed tests affect the economic justification for analyzer capacity expansion in mid-sized hospital laboratories.
Market Dynamics
Consolidation of integrated delivery networks in the United States is compressing vendor negotiation cycles and forcing analyzer manufacturers to restructure their commercial terms around multi-hospital enterprise contracts rather than individual laboratory purchases.
Growth Catalysts
- CLIA Proficiency Testing Requirements:United States hospital laboratories face escalating compliance burdens that favor automated analyzers with built-in quality control protocols and comprehensive audit trails, accelerating replacement of legacy manual systems.
- India's Diagnostic Infrastructure Expansion:Tier-2 and Tier-3 cities across Maharashtra, Tamil Nadu, and Karnataka are establishing centralized reference laboratories that require high-throughput chemistry platforms to serve dispersed clinic networks.
- Photometric Detection Advancement:Expanded wavelength ranges from 340–800 nm enable broader assay menus on single platforms, reducing the capital footprint for mid-sized laboratories seeking consolidated testing capabilities.
Market Restraints
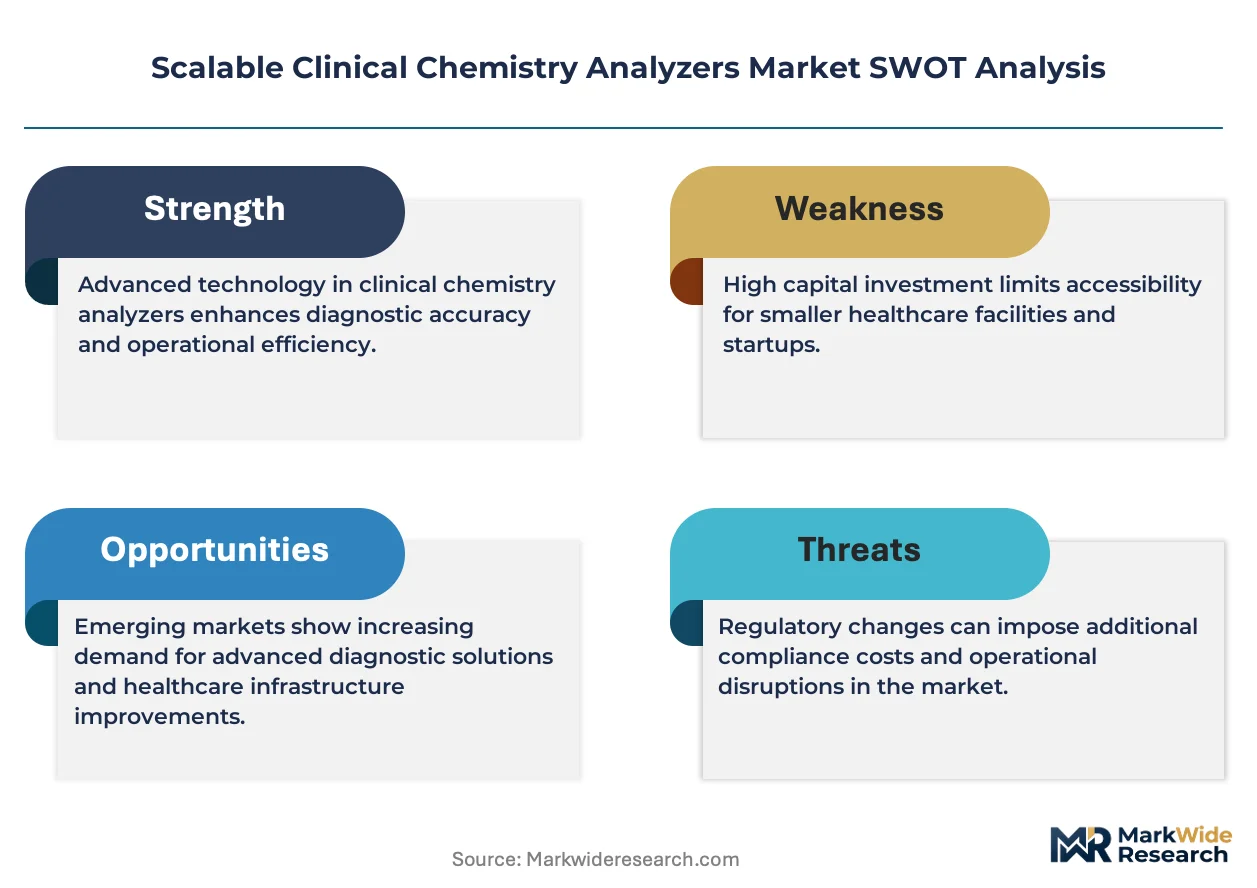
- Reagent Supply Concentration:Proprietary reagent lock-in strategies from dominant platform vendors create switching costs that trap laboratories in unfavorable long-term consumable contracts, limiting competitive pricing pressure.
- Specialized Biomedical Engineering Talent Scarcity:Maintenance and calibration of modular analyzer systems requires technicians trained in both photometric optics and fluidic mechanics, a skill combination concentrated in metropolitan hospital clusters.
- Point-of-Care Testing Substitution:Handheld and cartridge-based chemistry devices for emergency departments and satellite clinics are capturing lower-complexity assays that previously flowed to core laboratory analyzers.
Strategic Opportunities
- Brazil's SUS Network Modernization:Public hospital laboratories under ANVISA oversight are receiving federal infrastructure allocations to replace aging semi-automated systems with scalable platforms capable of 1,000+ tests per hour.
- Chemistry-Immunoassay Convergence:Integrated workflows combining photometric chemistry with chemiluminescent immunoassay on unified sample handling tracks eliminate aliquoting steps and reduce pre-analytical error rates for high-volume hospital laboratories.
- Saudi Arabia's Healthcare Privatization:MOHAP's transition of diagnostic services to private operators creates demand for analyzer fleets that can serve both inpatient and outpatient volumes across newly consolidated laboratory networks.
Industry Challenges
- ISO 15189 Accreditation Timelines:Medical laboratories pursuing accreditation face 12-18 month implementation cycles for quality management systems, delaying analyzer procurement decisions and extending sales cycles for vendors.
- Legacy LIS Integration Complexity:Hospital information systems built on 1990s-era architectures require expensive middleware development to exchange data with modern analyzer audit trail formats, inflating total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scalable Clinical Chemistry Analyzers Market |
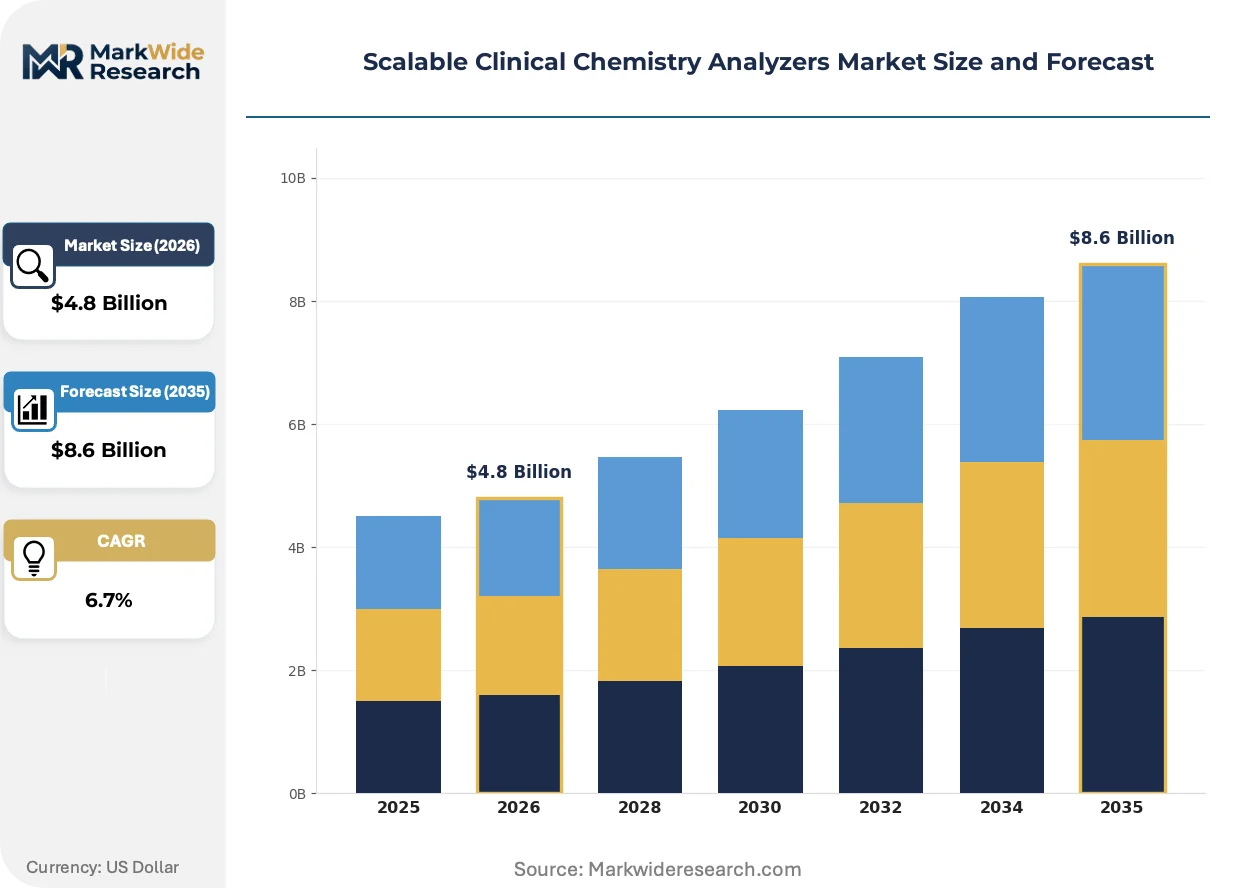
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Analyzers, Floor-Standing Analyzers, Portable Analyzers, Large-Volume Analyzers Technology: Colorimetric, Fluorometric, Electrochemical, Immunoassay End User: Hospitals, Diagnostic Laboratories, Research Institutions, Blood Banks Application: Routine Testing, Emergency Testing, Specialized Testing, Research Testing |
| Companies Covered | Roche, Thermo Fisher Scientific, Siemens Healthineers, Beckman Coulter, Mindray Medical, ELITechGroup, Horiba Medical, Abbott Laboratories, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scalable Clinical Chemistry Analyzers Market Trends and Innovations
Analyzer architecture is pivoting from discrete chemistry and immunoassay islands toward unified sample-to-result platforms that compress laboratory footprint while expanding test menu breadth. This structural shift is reshaping vendor R&D priorities and buyer evaluation criteria simultaneously.
Random-access sampling with continuous loading capability is displacing batch-mode processing in high-throughput hospital laboratories. Academic medical centers in the United States and Germany are prioritizing these architectures to eliminate workflow bottlenecks during morning specimen surges. The technology is displacing legacy rack-based systems that required operator intervention between batch cycles, compressing turnaround time guarantees from hours to minutes for stat testing.
The FDA's updated quality system regulation for in vitro diagnostic devices imposes stricter design control documentation and post-market surveillance requirements on analyzer manufacturers. Device establishments must now maintain electronic records linking calibrator traceability to specific production lots, extending development timelines by 8-14 months for new platform submissions. United States-based manufacturers are responding by embedding automated quality management modules that generate audit-ready documentation during routine operation.
Integrated delivery networks are consolidating laboratory procurement decisions at the enterprise level rather than delegating to individual hospital laboratories. This concentration transfers negotiating leverage from laboratory directors to supply chain executives who prioritize standardized platforms across multi-site networks. The pattern is most visible in United States health systems spanning 10+ hospitals, where single-vendor chemistry-immunoassay contracts now cover 60-80% of affiliated laboratory volume.
Scalable Clinical Chemistry Analyzers Market Segmentation
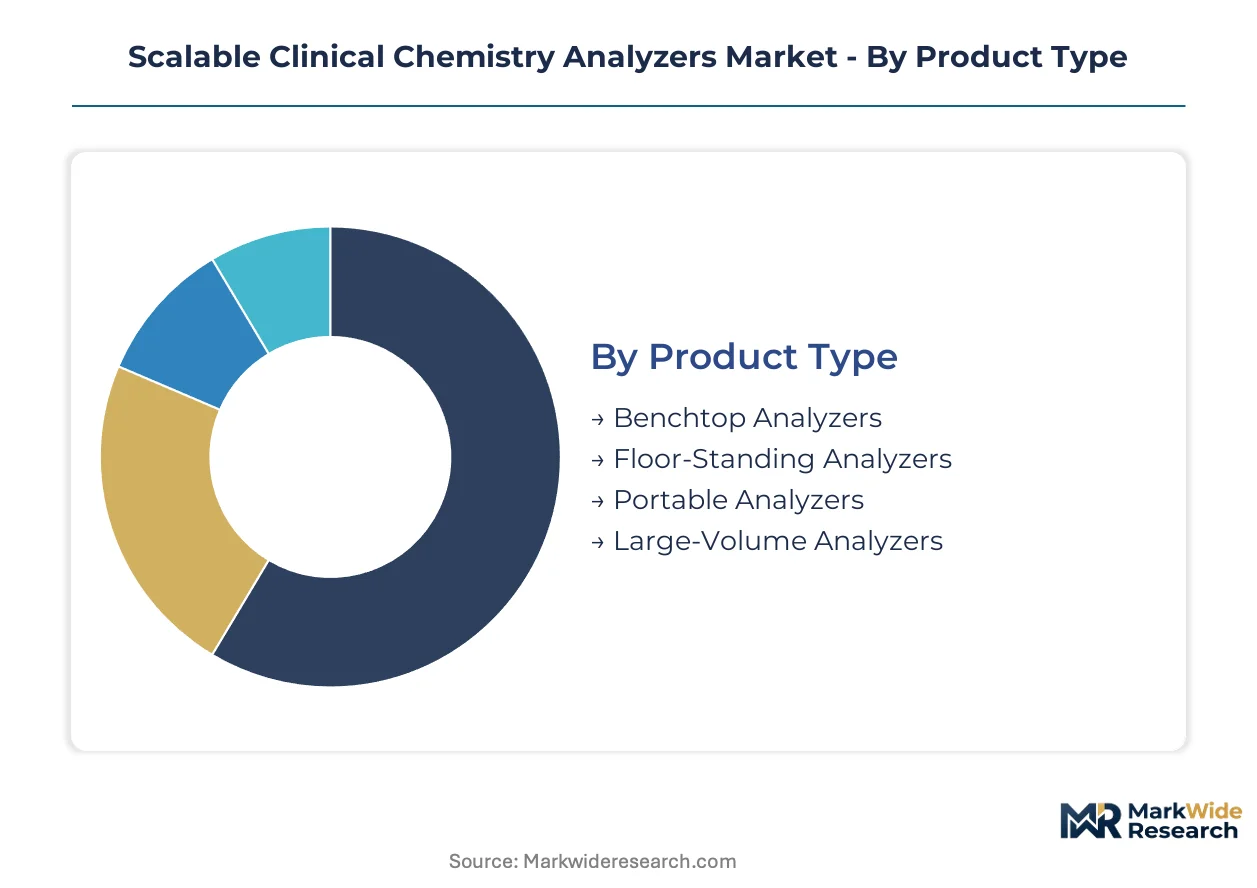
Segmentation in the scalable clinical chemistry analyzers market reveals how substitution pressures and workflow consolidation reshape procurement priorities across product tiers, detection modalities, and end-use settings. Laboratories now evaluate segments through the lens of throughput density, reagent flexibility, and informatics compatibility rather than standalone instrument specifications.
Product Type:
Floor-standing analyzers face intensifying substitution pressure from benchtop systems as mid-sized laboratories reconsider capital deployment against declining inpatient volumes.
- Floor-Standing Analyzers:These systems process 800–2,000+ tests per hour with modular reagent capacity exceeding 100 positions. United States integrated delivery networks concentrate demand here, driven by CLIA proficiency testing burdens that favor comprehensive built-in quality control protocols over distributed smaller units.
- Benchtop Analyzers:Compact platforms delivering 200–600 tests per hour now incorporate random-access sampling previously exclusive to larger systems. India's Tier-2 and Tier-3 cities are expanding procurement of these units as centralized reference laboratories serve dispersed clinic networks without full-scale floor-standing infrastructure.
- Portable Analyzers:Cartridge-based systems for 50–150 tests per hour capture emergency department and satellite clinic volumes that previously flowed to core laboratories.
- Large-Volume Analyzers:Ultra-high-throughput platforms exceeding 2,000 tests per hour serve national reference laboratories and blood bank screening operations with continuous loading architectures.
Floor-standing analyzers retain volume leadership; benchtop systems hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium photometric platforms from emerging electrochemical alternatives as laboratories balance assay menu breadth against per-test consumable economics.
- Immunoassay:Chemiluminescent detection integrated with chemistry workflows eliminates sample aliquoting steps. Academic medical centers in Germany and the United States prioritize these convergent platforms to compress turnaround time guarantees during morning specimen surges.
- Colorimetric:Photometric detection at 340–800 nm wavelengths underpins routine chemistry panels including liver function, renal markers, and lipid profiles. Brazil's SUS network modernization allocates federal infrastructure funds specifically for colorimetric-capable platforms replacing aging semi-automated systems.
- Fluorometric:Higher-sensitivity detection for trace analytes and specialized metabolic panels commands premium positioning in research-oriented hospital laboratories.
- Electrochemical:Ion-selective electrode technology for electrolyte and blood gas analysis offers lower consumable costs but narrower assay menus than photometric alternatives.
Colorimetric technology anchors installed base economics; immunoassay integration delivers the fastest volume gains.
End User:
Customer type concentration shifts toward enterprise-level procurement as integrated delivery networks consolidate vendor negotiation leverage away from individual laboratory directors.
- Hospitals:Inpatient and outpatient volumes across emergency, surgical, and chronic care units drive demand for 24/7 operational reliability. Saudi Arabia's healthcare privatization under MOHAP creates analyzer fleet requirements serving newly consolidated laboratory networks spanning multiple facilities.
- Diagnostic Laboratories:Independent and hospital-affiliated reference labs prioritize throughput density per square meter and standardized reagent contracts across multi-site operations.
- Research Institutions:Academic medical centers require flexible assay development capabilities and audit trail documentation supporting ISO 15189 accreditation timelines.
- Blood Banks:Screening operations for infectious disease markers and blood chemistry panels demand continuous processing architectures with minimal operator intervention.
Hospitals command the largest capital allocation; diagnostic laboratories are climbing the fastest as outpatient testing decentralizes.
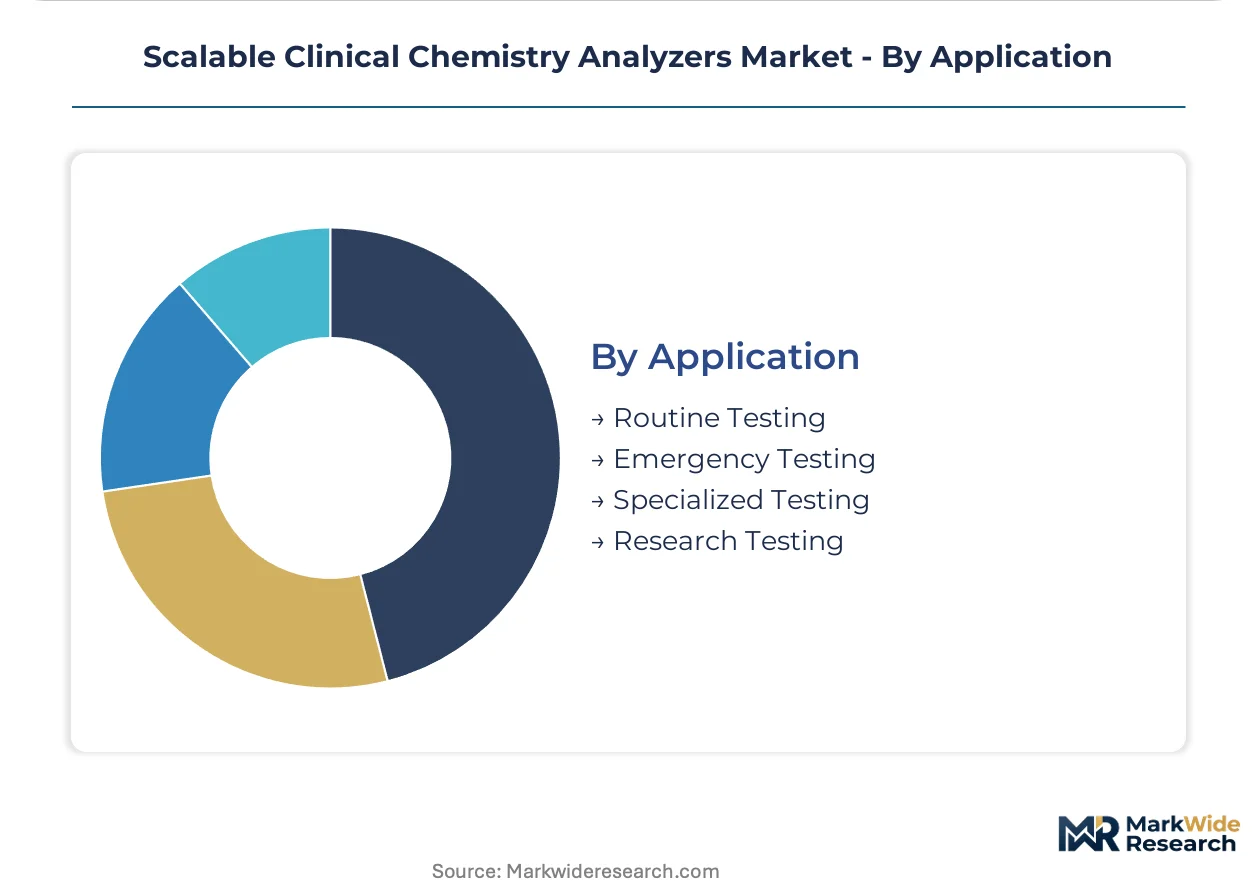
Application:
Maturity gradients separate commoditized routine workflows from emerging specialized testing configurations that command premium positioning and dedicated analyzer capacity.
- Routine Testing:High-frequency chemistry panels for diabetes monitoring, lipid management, and basic metabolic profiles generate recurring volume. United States hospital laboratories automate these workflows first when replacing legacy manual systems under CLIA compliance pressure.
- Specialized Testing:Therapeutic drug monitoring, tumor markers, and endocrine panels require broader wavelength ranges and immunoassay integration. These applications justify dedicated analyzer capacity in academic medical centers pursuing research funding and subspecialty referrals.
- Emergency Testing:Stat turnaround requirements for critical care decisions favor random-access architectures with continuous loading capability over batch-mode processing.
- Research Testing:Assay development and clinical trial support demand open-system flexibility and comprehensive audit trail documentation for regulatory submission packages.
Routine testing retains volume leadership; specialized testing holds the steepest expansion curve as precision medicine protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates among integrated delivery networks in the United States, German academic medical centers, and India's expanding reference laboratory infrastructure. These three markets generate the majority of capital deployment for high-throughput chemistry platforms. Regulatory divergence across FDA, EMA, and CDSCO jurisdictions shapes distinct procurement timelines and technical specifications.
United States
Hospital laboratories in Texas, Florida, and Ohio are consolidating automated testing capacity under enterprise-wide contracts spanning 10+ facilities. FDA's updated quality system regulation for in vitro diagnostic devices extends development timelines by 8-14 months, favoring established vendors with modular platform architectures. The Southeast hospital cluster around Atlanta and Charlotte is replacing legacy manual systems ahead of CLIA proficiency testing deadlines.
Germany
Academic medical centers in Bavaria and Baden-Württemberg prioritize random-access sampling with continuous loading capability to eliminate morning specimen surge bottlenecks. EMA's In Vitro Diagnostic Regulation (IVDR) imposes stricter conformity assessment requirements on analyzer manufacturers, compressing the notified body capacity for CE marking. The Munich-Stuttgart corridor hosts concentrated procurement decision-making for chemistry-immunoassay convergent platforms.
India
Tier-2 and Tier-3 cities across Maharashtra, Tamil Nadu, and Karnataka are establishing centralized reference laboratories requiring 1,000+ tests per hour capacity. CDSCO's medical device rules mandate import license compliance for foreign-manufactured analyzers, creating regulatory friction for non-domestic vendors. The Pune-Chennai-Bengaluru triangle is capturing federal infrastructure allocations for diagnostic network expansion.
Brazil
Public hospital laboratories under ANVISA oversight are receiving federal infrastructure allocations to replace aging semi-automated systems. The SUS network modernization program targets 1,000+ tests per hour platforms for state reference laboratories. São Paulo and Minas Gerais concentrate procurement volume as state health secretariats consolidate laboratory networks.
Saudi Arabia
MOHAP's transition of diagnostic services to private operators creates demand for analyzer fleets serving inpatient and outpatient volumes across consolidated laboratory networks. The Riyadh-Jeddah corridor is capturing privatization-driven capital deployment for unified chemistry-immunoassay workflows. Western Region hospital clusters are standardizing platforms under new operator management contracts.
Scalable Clinical Chemistry Analyzers Market Competitive Landscape
Concentration sits with diversified diagnostics conglomerates that leverage installed base economics and reagent lock-in strategies. Three to five integrated players capture the majority of enterprise contract value across major health systems. The competitive terrain separates modular platform specialists, reagent-anchored incumbents, and emerging regional challengers. Dominant moves include chemistry-immunoassay convergence investments and multi-hospital enterprise contract restructuring.
Within the installed-base archetype, Roche, Siemens Healthineers, and Beckman Coulter occupy positions sustained by recurring reagent revenue and deep integration with hospital informatics networks. These diversified diagnostics conglomerates exemplify the capital-intensive, high-switching-cost structure that defines procurement negotiations with integrated delivery networks. Mindray Medical represents the regional challenger archetype, anchoring competitive pressure in Asia-Pacific and emerging market price tiers.
| Leading Market Players |
|---|
| Roche |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Beckman Coulter |
| Mindray Medical |
| ELITechGroup |
| Horiba Medical |
| Abbott Laboratories |
| Danaher Corporation |
| Others |
Pricing and Supply Chain Analysis
Cartridge-based reagent systems displacing traditional liquid reagent formats are redrawing procurement economics and supplier geography simultaneously. This substitution compresses per-test costs for mid-sized hospital laboratories while concentrating manufacturing investment in Germany and Japan where precision molding capabilities for disposable consumables anchor production.
Pricing Analysis
FDA's updated quality system regulation dictates the pricing tier structure across the installed base. Three-tier pricing structure across premium, standard, and economy levels separates modular chemistry-immunoassay platforms from standalone chemistry units and refurbished legacy systems. Price differentiation hinges on CLIA compliance automation depth and ISO 15189 audit trail sophistication. Cost compression in the economy tier is intensifying because India's Tier-2 reference laboratories prioritize capital efficiency over feature breadth. Diagnostic laboratories serving integrated delivery networks exhibit lowest price sensitivity; standalone rural hospitals display highest.
Supply Chain Analysis
Germany and Japan anchor precision optical component fabrication for photometric detection modules. China and South Korea feed printed circuit board assemblies and stepper motor subsystems. Taiwan sources monochromator gratings and interference filters. Supply chain risk centers on single-source vulnerability for proprietary reagent formulations locked to specific analyzer architectures. Distribution runs through GPO contracts at integrated delivery networks and direct manufacturer relationships for independent reference laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where chemistry-immunoassay convergence is redefining vendor lock-in dynamics. Interoperability demands from enterprise laboratory networks are forcing modular architectures over closed proprietary systems.
For Market Incumbents: Consolidate reagent supply contracts across multi-hospital IDN footprints to deepen switching-cost moats. Acquire benchtop analyzer specialists in India and Brazil before regional challengers capture reference laboratory procurement. CLIA proficiency testing burdens favor vendors with automated quality control modules; accelerate R&D here. Backward integration into precision-molded consumables secures margin against polymer price volatility.
For New Entrants and Emerging Players: CDSCO's fast-track medical device approval pathway for analyzers manufactured under ISO 13485 offers regulatory arbitrage against FDA-timeline incumbents. Target Brazil's SUS network modernization and Saudi Arabia's privatizing laboratory networks where incumbent reagent lock-in remains shallow. Penetrate via benchtop systems with open reagent compatibility, bypassing proprietary consumable economics that trap buyers elsewhere. Anchor go-to-market through distributor partnerships with existing hospital engineering service networks.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified diagnostics conglomerates with reagent recurring revenue over pure-play hardware vendors. Long-term viability across a decade horizon rests on chemistry-immunoassay integration depth and IDN contract penetration. Target acquisition archetype: regional benchtop specialists with CDSCO or ANVISA approvals and established service footprints in India or Brazil. Watch CMS reimbursement rule shifts for laboratory-developed tests as inflection signal for mid-sized hospital capital deployment appetite.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemistry-Immunoassay Platform Convergence | Eliminates sample aliquoting steps and compresses turnaround time guarantees for academic medical centers. |
| CE Marking Pathway Under IVDR | EMA's stricter conformity assessment compresses notified body capacity and extends timelines for new platform submissions. |
| Hospital System Partnership Restructuring | Enterprise contracts spanning 10+ facilities transfer negotiating leverage from laboratory directors to supply chain executives. |
| Software Companion Development | Middleware solutions bridge legacy LIS architectures with modern analyzer audit trail formats, inflating total cost of ownership. |
| Reimbursement Strategy Alignment | CMS rules for laboratory-developed tests shape economic justification for analyzer capacity expansion in mid-sized hospitals. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA IVDR technical documentation, CDSCO medical device registration databases, and GPO contract disclosure records. Primary interviews engaged biomedical engineering directors, hospital purchasing committee members, reference laboratory operations managers, and IVD regulatory affairs specialists. Secondary validation drew from SEC 10-K instrument revenue disclosures, ISO 15189 accreditation body reports, and customs import data for analyzer shipments. Bottom-up triangulation of installed base economics against top-down health system capital expenditure tracking anchored market sizing.
Segmentation dimensions modeled include product type tier, detection technology modality, end-user setting, and application workflow maturity across the projection horizon. CAGRs derive from regression analysis of historical replacement cycles, CLIA compliance deadline clustering, and IDN consolidation trajectories. Forecast inputs incorporate photometric wavelength expansion roadmaps, random-access sampling adoption curves, and reagent menu breadth expansion timelines.
Decision-makers should treat outputs as directional under assumptions of sustained IDN consolidation, stable CLIA proficiency testing burdens, and continued chemistry-immunoassay workflow convergence; material deviation in CMS reimbursement policy or point-of-care testing substitution rates would warrant model refresh. Recalibration cycles align with material shifts in regulatory deadline clustering and health system merger activity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Benchtop Centrifuges Market
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Portable Hemoglobin Analyzer Market
Laboratory Equipment
Laboratory Pulverizer Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Pipettes and Accessories Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Histopathology Laboratory Equipment Market
Laboratory Equipment
Blood Volume Analyzer Market
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Global Laboratory Plasticware Market
Laboratory Equipment
Automated Plate Readers Market
Laboratory Equipment
Latin America Laboratory Equipment and Disposables Market
Laboratory Equipment
Automated Blood Analyzer Market
Laboratory Equipment
Orbital Shakers Market