
 US Cannabis Testing Market | 2026-2036
US Cannabis Testing Market Size, Share, and Industry Trends Forecast 2026-2036
US Cannabis Testing Market Analysis
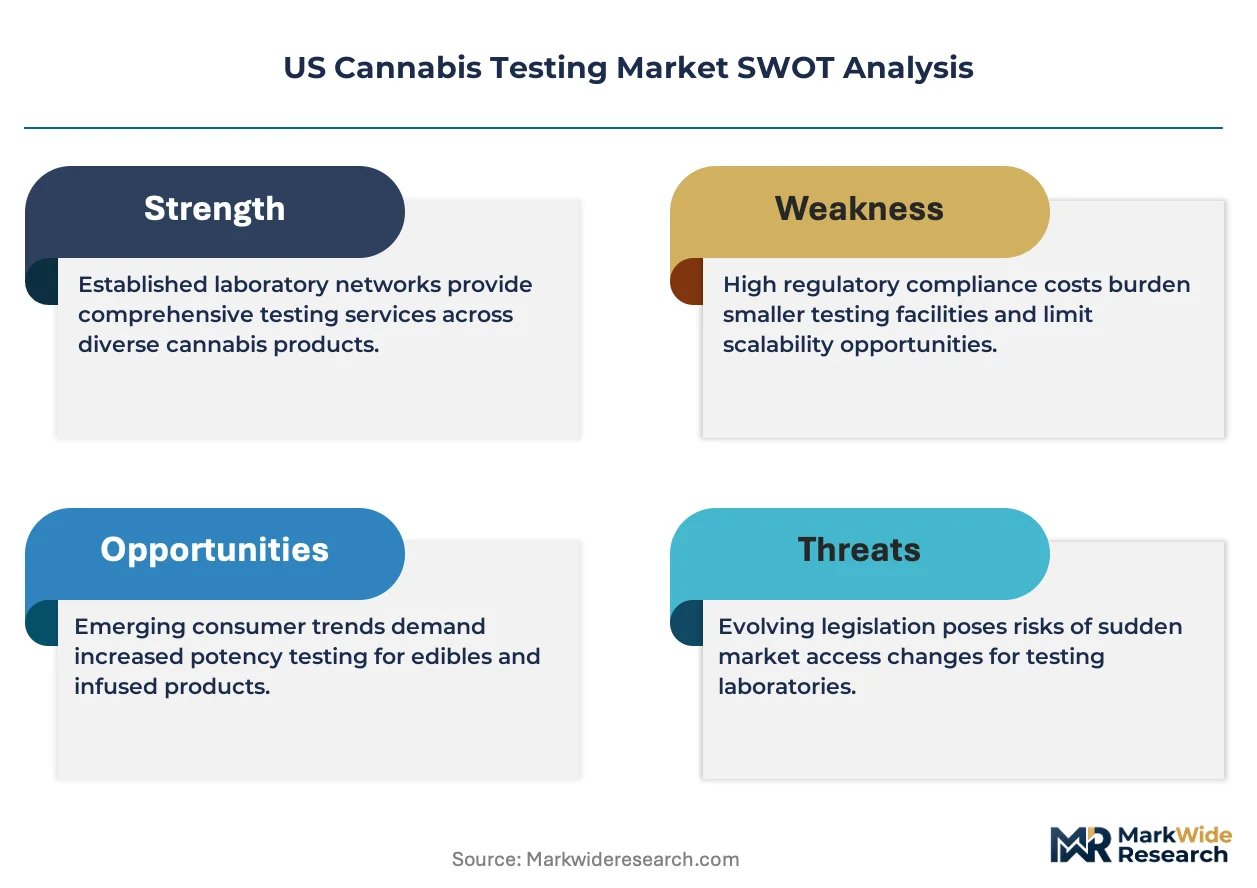
Capital-intensity divergence between multi-state laboratory networks and single-site operators is unwinding competitive stability. SC Laboratories leverages its California headquarters to anchor West Coast cultivator relationships. Kaycha Labs competes through state-level licensing breadth. Steep Hill Labs differentiates via early-mover positioning in emerging state markets.
US cannabis testing encompasses analytical verification of cannabinoid content, terpene profiles, and contaminant thresholds in regulated cannabis products, typically employing high-performance liquid chromatography (HPLC) for THC quantification and inductively coupled plasma mass spectrometry (ICP-MS) for heavy metals detection. The primary purpose centers on consumer safety assurance and regulatory compliance for state-legal cannabis distribution. Potency testing occupies the largest revenue share due to universal state mandates for THC labeling accuracy. Chromatography leads technology deployment, though mass spectrometry gains ground for multi-analyte pesticide panels. Sample type revenue concentrates in flower testing, with concentrates representing the fastest-growing category as derivative product lines expand.
FDA maintains oversight of cannabis-derived pharmaceutical pathways, while state departments of agriculture and public health enforce batch-release testing protocols under DEA Schedule I constraints. OSHA standards govern laboratory workplace exposure to organic solvents used in sample preparation. State regulators in California, Colorado, and Oregon set maximum allowable limits for mycotoxins and residual solvents that directly determine laboratory testing menu breadth. Stakeholders must monitor federal rescheduling proceedings, as any shift in controlled substance classification would trigger wholesale restructuring of interstate reference standard access and method validation requirements.
Market Dynamics
California's Central Valley laboratory cluster concentrates testing capacity where cultivator density creates volume leverage, while state-level THC potency caps and mandatory heavy metals protocols force continuous equipment upgrades and method validation investments.
Growth Catalysts
- DEA Schedule I Constraints:Interstate commerce barriers protect state-licensed laboratories from out-of-state competition, creating captive regional markets with stable pricing power.
- OSHA Workplace Exposure Standards:Mandatory solvent handling protocols drive demand for automated sample preparation systems that reduce technician contact with organic compounds.
- Flower-to-Concentrate Product Shift:Derivative manufacturing expansion multiplies testing touchpoints per gram of raw input, as concentrates require residual solvent, terpene profile, and potency verification.
Market Restraints
- Reference Standard Supply Concentration:DEA-licensed manufacturers of certified cannabinoid standards operate under federal controlled substance restrictions, creating procurement bottlenecks for laboratories in emerging state markets.
- Equipment Import Dependency:High-performance liquid chromatography and inductively coupled plasma mass spectrometry systems originate from German, Japanese, and US precision instrument manufacturers, exposing operators to currency volatility and extended lead times.
- Method Validation Burden:State departments of agriculture require laboratory-specific validation for each analyte matrix combination, preventing economies of scale in multi-state expansion.
Strategic Opportunities
- Texas and Florida Market Entry:Limited-service medical programs in these states anticipate expansion toward comprehensive adult-use frameworks, creating first-mover positioning windows for testing infrastructure.
- Hemp-Derived Cannabinoid Testing:2018 Farm Bill compliance verification for delta-8 THC and other isomers opens adjacent revenue streams using existing chromatography assets.
- Blockchain Batch Certification:Immutable chain-of-custody records address dispensary and consumer demands for transparent provenance documentation.
Industry Challenges
- Analytical Chemist Talent Scarcity:Cross-training between pharmaceutical and cannabis laboratories remains limited by stigma and compensation gaps, constraining quality control staffing.
- Turnaround Time Compression:Cultivators operating just-in-time harvest schedules demand 24-48 hour results, forcing laboratories to maintain excess capacity during seasonal demand troughs.
- Inter-Laboratory Proficiency Disparities:Ring-test programs reveal significant variance in THC quantification across facilities, undermining regulator and retailer confidence in batch-release decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cannabis Testing Market |
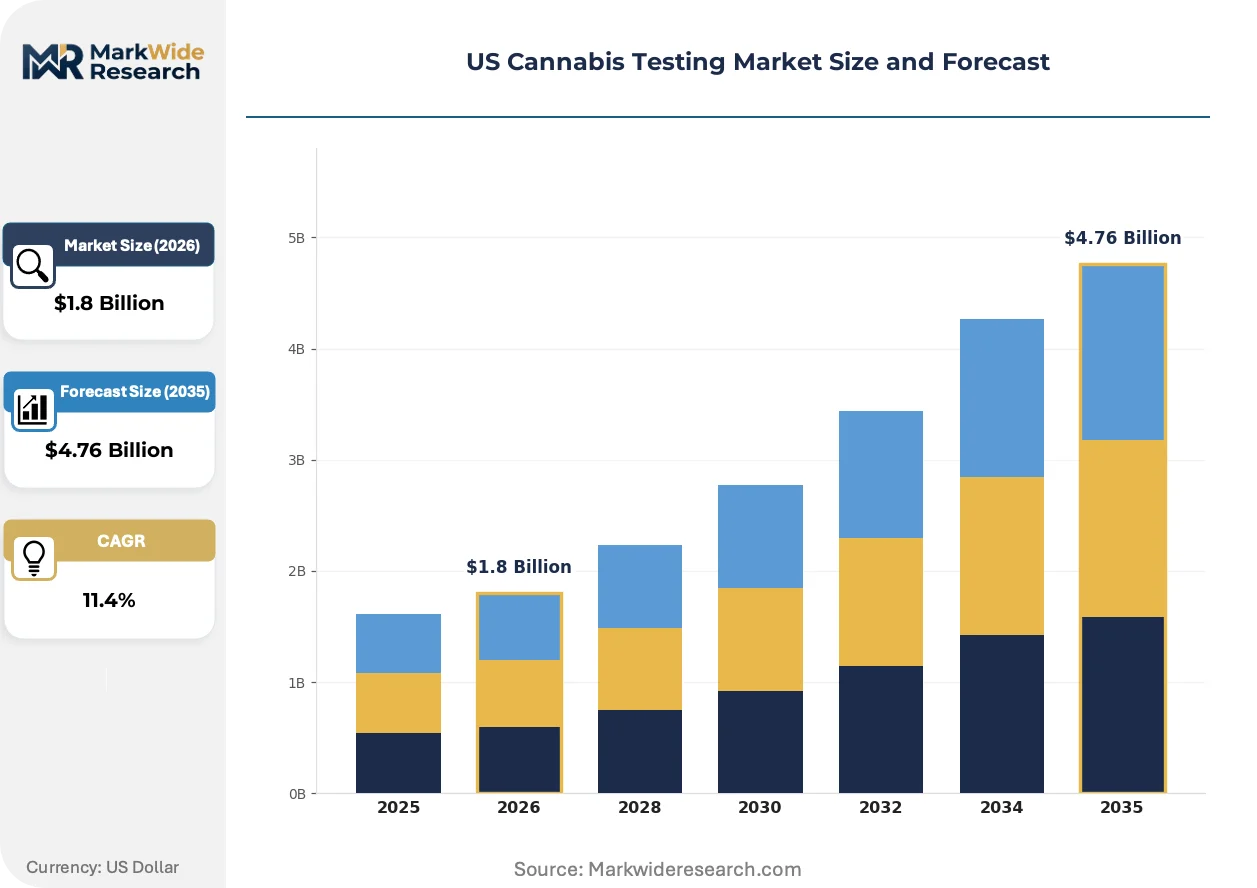
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Type: Potency Testing, Residual Solvent Analysis, Microbial Testing, Heavy Metals Testing Sample Type: Flower, Oil, Edibles, Concentrates Technology: Chromatography, Spectroscopy, Mass Spectrometry, Immunoassays End User: Laboratories, Dispensaries, Cultivators, Research Institutions |
| Companies Covered | SC Laboratories, Anresco Laboratories, Green Leaf Lab, CW Analytical Laboratories, Digipath, Kaycha Labs, PharmLabs, ACT Laboratories, Steep Hill Labs, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cannabis Testing Market Emerging Trajectories
Chromatography platforms are splitting into divergent performance tiers while regulatory fragmentation forces method customization, and cultivator consolidation is reshaping buyer power dynamics across state markets.
Mass spectrometry is bifurcating laboratory capital strategies. Triple-quadrupole systems enable simultaneous pesticide, mycotoxin, and heavy metals screening in single injections, compressing per-sample costs for high-volume Central Valley operators. Single-site laboratories in emerging markets retain diode-array HPLC for potency-only workflows, accepting limited service menus to defer seven-figure equipment investments.
California's Bureau of Cannabis Control mandates universal batch testing for 66 distinct pesticide residues, with Oregon and Colorado adopting comparable panel breadth. This regulatory convergence forces multi-state operators to standardize method portfolios across facilities, eliminating geography-specific efficiency advantages. Small laboratories respond through cooperative purchasing agreements for reference materials and shared proficiency testing subscriptions.
Dispensary procurement is consolidating around integrated software platforms that automate certificate-of-analysis ingestion and inventory hold-release decisions. This behavior shift compresses laboratory sales cycles toward API-first connectivity rather than relationship-based account management. California and Colorado retailers lead this transition, where enterprise point-of-sale systems now require direct laboratory data feeds as a vendor qualification threshold.
US Cannabis Testing Market Segmentation
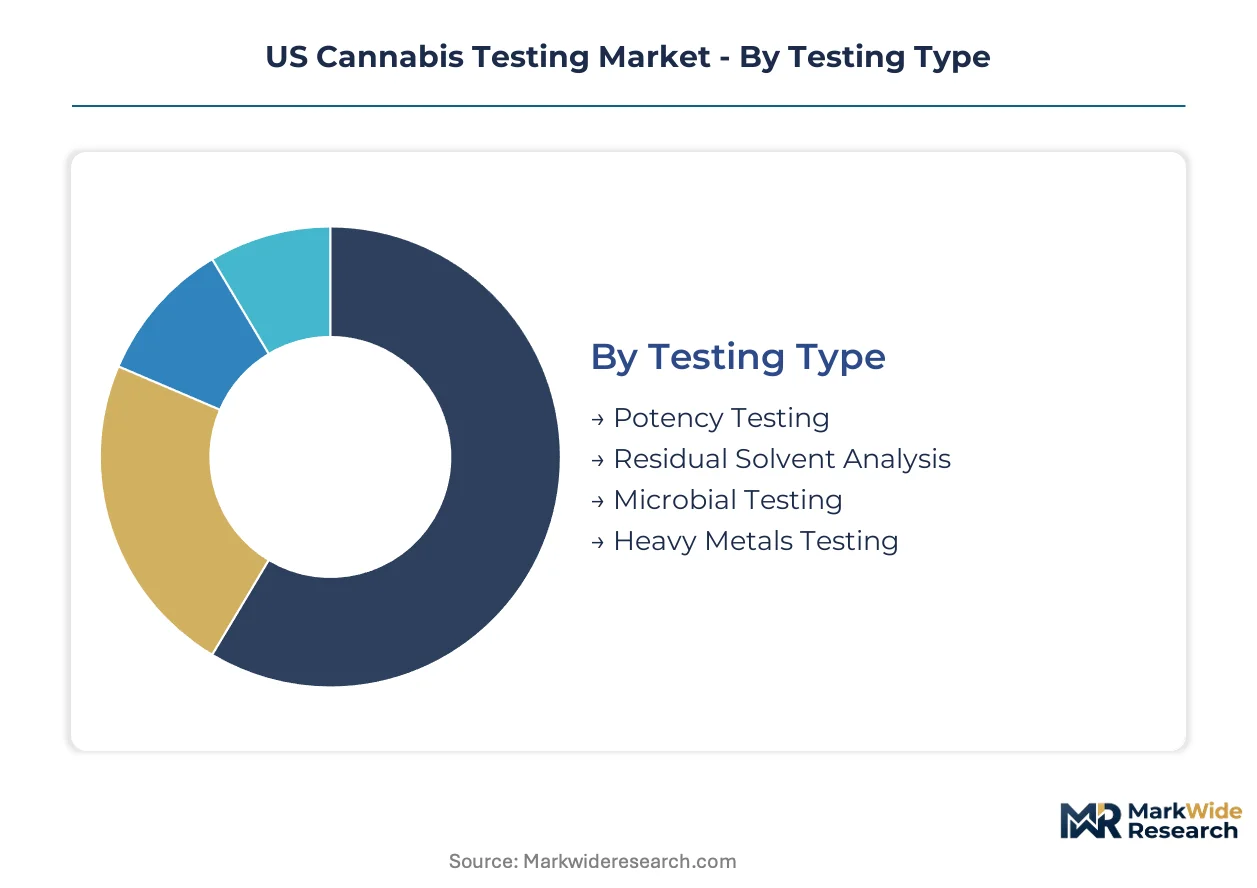
Testing service configuration in the US cannabis market reflects divergent capital requirements across state regulatory regimes. Laboratories must align equipment portfolios with specific contaminant mandates rather than pursuing universal analytical platforms.
Testing Type:
Margin pools concentrate in high-frequency, state-mandated screening where batch volume creates equipment utilization leverage.
- Potency Testing:HPLC-based THC and CBD quantification forms the universal regulatory baseline across all state programs. California's Bureau of Cannabis Control and Colorado's Marijuana Enforcement Division require potency verification for every commercial batch, anchoring revenue stability for laboratories serving high-cultivation-density regions.
- Heavy Metals Testing:ICP-MS detection of arsenic, cadmium, lead, and mercury addresses California's Proposition 65 liability exposure and Oregon's mandatory screening protocols. Central Valley laboratories processing outdoor-grown flower face elevated sample volumes due to soil contamination risks in agricultural zones.
- Residual Solvent Analysis:GC-MS identification of butane, propane, and ethanol traces in hydrocarbon-extracted concentrates.
- Microbial Testing:PCR and culture-based detection of Salmonella, E. coli, and Aspergillus species in raw flower.
The dominant share belongs to Potency Testing, while Heavy Metals Testing is closing the gap fastest.
Sample Type:
Processing complexity and regulatory touchpoint density determine per-sample revenue capture across material categories.
- Flower:Raw cannabis biomass requires potency, moisture content, microbial, and heavy metals screening as the foundational testing workflow. California's Central Valley cultivator cluster generates sustained volume for laboratories positioned near Fresno and Kern County growing operations.
- Concentrates:Extracted oils and waxes demand residual solvent, terpene profile, and potency verification—multiplying analytical steps per gram of input material. Oregon's solventless rosin market and Colorado's hydrocarbon extraction sector drive specialized method development investments.
- Oil:Vape cartridge and tincture matrices requiring viscosity-adjusted sample preparation protocols.
- Edibles:Food-matrix interference challenges for cannabinoid extraction and homogeneity verification.
Flower maintains volume leadership, though Concentrates is expanding most quickly as derivative product lines proliferate.
Technology:
Capital deployment strategies split between multi-analyte platform consolidation and single-purpose instrument specialization.
- Chromatography:HPLC systems with diode-array detection dominate potency-only workflows for cost-conscious single-site operators. California and Colorado laboratories standardize on Agilent and Waters platforms to streamline method transfer across multi-state networks.
- Mass Spectrometry:Triple-quadrupole LC-MS/MS enables simultaneous pesticide, mycotoxin, and heavy metals quantification in single injections. High-volume Central Valley facilities deploy these systems to compress per-sample costs and meet California's 66-pesticide residue mandate.
- Spectroscopy:FTIR and NIR platforms for rapid terpene screening and incoming material qualification.
- Immunoassays:Lateral flow and ELISA methods for presumptive microbial contamination screening.
Chromatography holds installed base dominance, yet Mass Spectrometry is gaining share fastest through multi-analyte efficiency gains.
End User:
Procurement authority and technical sophistication shape service contracting terms and pricing tolerance.
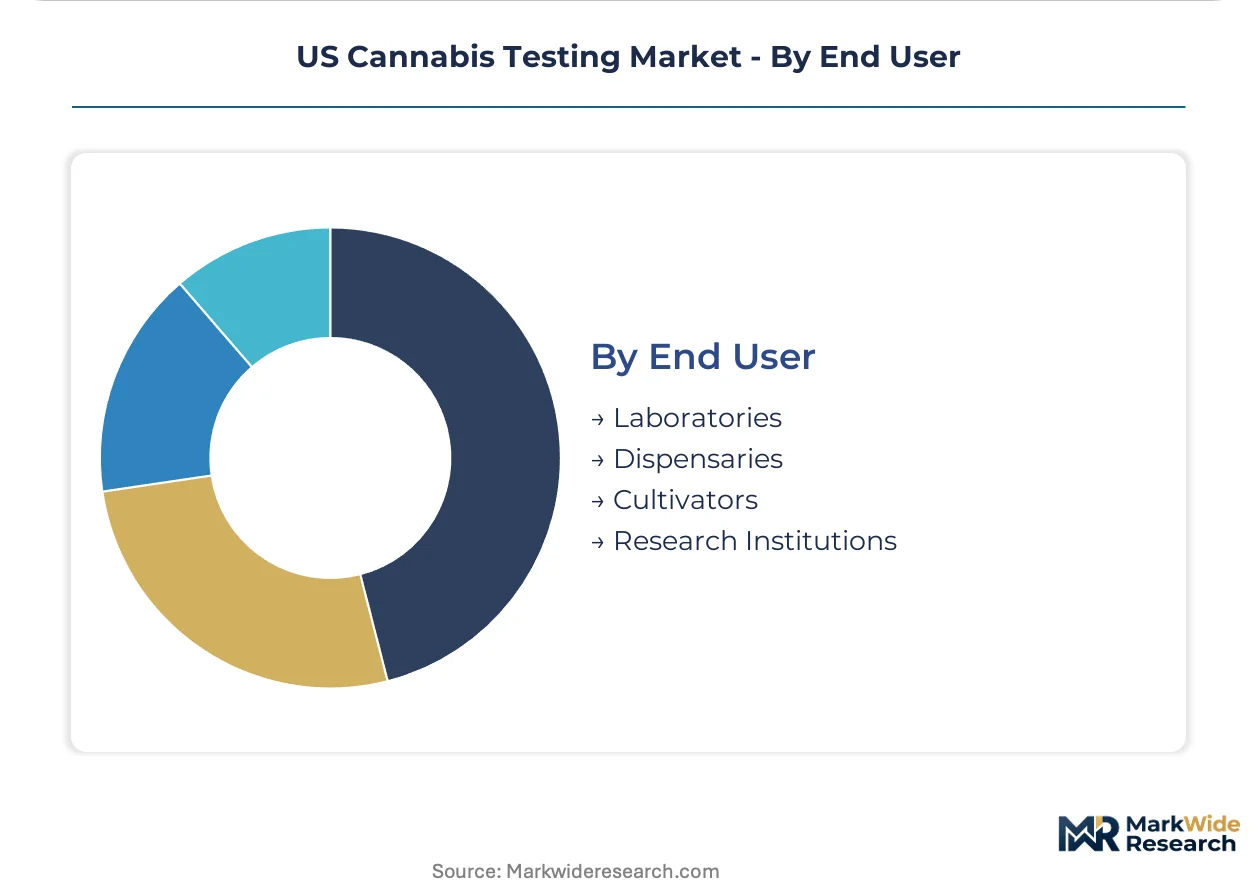
- Laboratories:Third-party analytical facilities serving cultivators and manufacturers under state licensing requirements. California's ISO 17025-accredited laboratories command premium positioning for dispensary-facing certificate-of-analysis distribution.
- Cultivators:Licensed growing operations requiring pre-harvest testing and batch-release documentation. Oregon's craft cannabis sector and Colorado's outdoor farms drive seasonal demand spikes that strain laboratory turnaround capacity.
- Dispensaries:Retail operators verifying supplier certificates and conducting spot-check screening.
- Research Institutions:Academic and pharmaceutical investigators studying cannabinoid pharmacology under DEA Schedule I research licenses.
Laboratories capture the largest service contract value, while Cultivators is climbing the fastest as vertical integration trends accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California's Central Valley laboratory cluster, where cultivator density creates volume leverage unavailable to Rocky Mountain or Pacific Northwest operators. Texas and Florida laboratories command premium rates due to limited-service medical frameworks that restrict testing infrastructure deployment.
California
Central Valley cultivator density around Fresno and Kern County sustains the nation's highest testing volumes. The Bureau of Cannabis Control mandates universal batch screening for 66 pesticide residues, forcing continuous method validation investments. SC Laboratories anchors its headquarters in Santa Cruz to capture West Coast cultivator relationships and multi-state method standardization.
Colorado
Outdoor cultivation in Pueblo County and hydrocarbon extraction in Denver drive seasonal demand spikes for residual solvent analysis. The Marijuana Enforcement Division requires potency verification for every commercial batch, stabilizing revenue for laboratories serving the Front Range. Steep Hill Labs maintains early-mover positioning to capture emerging state market transitions.
Oregon
Solventless rosin markets in the Willamette Valley and craft cannabis sectors create specialized method development demand. Mandatory heavy metals protocols align with California's Proposition 65 liability standards, enabling multi-state operators to transfer validation protocols. Green Leaf Lab leverages Portland's regulatory sophistication to anchor Pacific Northwest service contracts.
Texas
Limited-service medical programs restrict laboratory licensing to a handful of approved facilities, creating artificial scarcity and elevated pricing. The Department of Public Safety maintains strict oversight of testing protocols for low-THC cannabis products. Kaycha Labs competes through state-level licensing breadth to position for anticipated adult-use framework expansion.
Florida
Vertical integration requirements force medical marijuana treatment centers to maintain captive testing relationships, compressing third-party laboratory margins. The Department of Health's Office of Medical Marijuana Use regulates batch-release standards for a concentrated oligopoly of licensed operators. PharmLabs and ACT Laboratories target positioning windows ahead of potential regulatory liberalization.
US Cannabis Testing Market Vendor Landscape
Concentration sits with multi-state laboratory networks that standardize methods across California, Colorado, and Oregon facilities. Single-site operators in emerging markets accept limited service menus to defer capital-intensive mass spectrometry investments. Three archetypes dominate: West Coast volume leaders, state-level licensing breadth competitors, and early-mover specialists in transitional markets. Competitive moves center on cooperative purchasing agreements for DEA-restricted reference materials and API-first software integrations with dispensary point-of-sale systems.
Within the West Coast volume tier, SC Laboratories exemplifies headquarters-anchored network expansion, while Anresco Laboratories occupies a position among California ISO 17025-accredited facilities serving premium dispensary channels. Kaycha Labs represents the state-level licensing breadth archetype, competing across fragmented regulatory jurisdictions rather than concentrating geographic density.
| Leading Market Players |
|---|
| SC Laboratories |
| Anresco Laboratories |
| Green Leaf Lab |
| CW Analytical Laboratories |
| Digipath |
| Kaycha Labs |
| PharmLabs |
| ACT Laboratories |
| Steep Hill Labs |
| Others |
Supply Flow & Price Mechanics
Triple-quadrupole mass spectrometry displacement of diode-array HPLC in high-volume California laboratories simultaneously concentrates supply geography around Central Valley equipment hubs and compresses per-sample pricing economics for potency-only operators in emerging state markets.
Pricing Analysis
The customization-premium spread between ISO 17025-accredited full-service laboratories and limited-menu single-site operators spans roughly 40-60% per sample. Contract-based long-term offtake agreements dominate buyer relationships, with price differentiation driven by certification tier and volume scale. Pricing pressure stems from cultivator consolidation in California and Colorado, where larger growing operations negotiate enterprise rates. Small craft cultivators in Oregon's Willamette Valley exhibit highest price sensitivity, while multi-state vertically integrated operators accept premium pricing for standardized cross-facility protocols.
Supply Chain Analysis
Germany, Japan, and the United States anchor precision instrument manufacturing for HPLC and ICP-MS systems deployed across American cannabis laboratories. Reference standard supply draws from DEA-licensed domestic manufacturers and limited European certified producers, creating procurement bottlenecks for pesticide and cannabinoid calibration materials. Single-source vulnerability concentrates in high-purity helium sourcing for GC-MS residual solvent analysis, with distribution running through authorized distributor networks rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against in-house laboratory buildouts by vertically integrated multi-state operators, which threaten third-party testing margins through captive volume capture.
For Market Incumbents: Shield reference standard inventory positions through multi-year DEA-licensed manufacturer agreements before federal rescheduling disrupts interstate commerce rules. Deepen backward integration into proficiency testing program administration to lock cultivator relationships beyond transactional sample processing. Prioritize API-first software connectivity with dispensary point-of-sale systems to embed laboratory data flows as switching costs rise.
For New Entrants and Emerging Players: ISO 17025 fast-track accreditation in Texas and Florida offers positioning windows ahead of anticipated adult-use framework expansions. Target limited-service medical markets where artificial licensing scarcity sustains premium pricing. Lead with hemp-derived cannabinoid compliance testing using transferable chromatography assets to generate revenue during state cannabis program maturation.
For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors multi-state network operators with standardized method portfolios. Long-term viability hinges on federal rescheduling outcomes that would restructure reference standard access and interstate laboratory expansion rules. Monitor DEA policy proceedings as the primary inflection signal for valuation recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-State ISO 17025 Accreditation | Enables method standardization across California, Colorado, and Oregon facilities under Bureau of Cannabis Control requirements. |
| API-First Dispensary Integration | Automates certificate-of-analysis ingestion into enterprise point-of-sale systems, creating vendor lock-in. |
| DEA Reference Standard Stockpiling | Secures multi-year cannabinoid and pesticide calibration material supply before federal rescheduling disrupts procurement. |
| Hemp-Derived Cannabinoid Testing Expansion | Captures 2018 Farm Bill compliance revenue using existing chromatography infrastructure during cannabis program gaps. |
| Blockchain Batch Certification Deployment | Addresses dispensary and consumer chain-of-custody transparency demands through immutable provenance records. |
Methodological Framework
Initial hypotheses were tested against primary input from laboratory operations directors, state regulatory compliance officers, cultivator procurement managers, and analytical instrument sales engineers, then refined through secondary validation against FDA cannabis-derived pharmaceutical guidance documents, state department of agriculture batch-testing regulations, DEA controlled substance scheduling proceedings, and OSHA laboratory workplace exposure standards. Bottom-up cultivation volume estimates triangulated against top-down state program revenue projections.
Variance decomposition across the projection horizon separated volume growth from pricing trajectory and mix shift effects. Segmentation dimensions modeled include testing type, sample matrix, technology platform, and state regulatory framework cluster. CAGRs derived from equipment installation base growth, cultivator license issuance trends, and batch testing frequency mandates. Industry-specific inputs incorporated California's 66-pesticide residue panel expansion and federal rescheduling probability scenarios.
Decision-makers should treat outputs as directional under sustained DEA Schedule I classification and stable state regulatory frameworks; material deviation through federal rescheduling or interstate commerce liberalization would warrant model refresh. Recalibration cycles align with material shifts in DEA scheduling proceedings, state adult-use program launches, and reference standard supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Indoor Allergen and Particulate Exposure Assessment Test Devices Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Nucleic Acid Testing Market
Testing Services
Pharmaceutical Quality Control Market
Testing Services
Global HIV Self Test Kits Market
Testing Services
Global Endotoxin and Pyrogen Testing Market
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
In-Vitro Diagnostic Services Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Nipah Virus Testing Market
Testing Services
US Bowie Dick Test Pack Market
Testing Services
Mycological Testing Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Global Rapid Test Market
Testing Services
Global Anti Thrombin III Testing Market