
 Marijuana Sensors Market | 2026-2036
Marijuana Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Marijuana Sensors Market Analytics
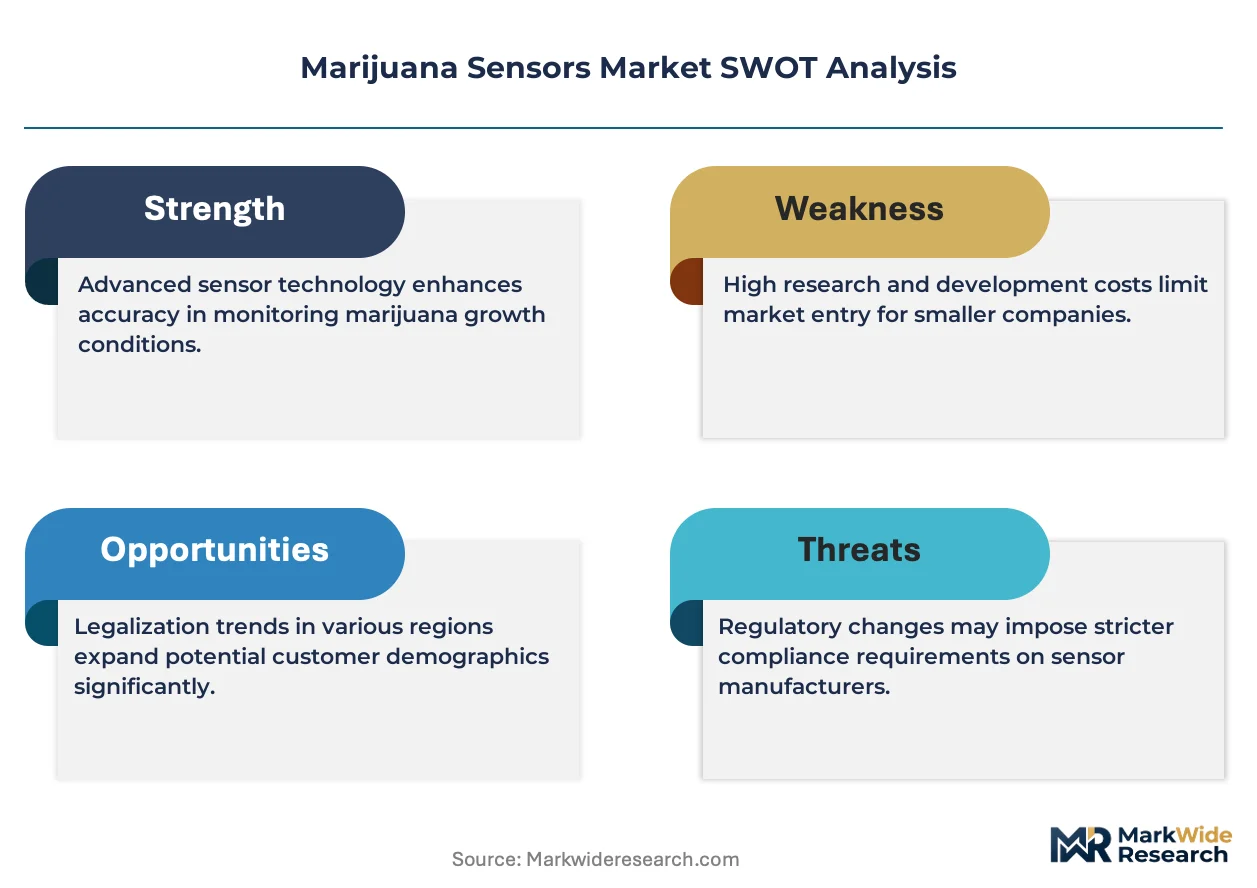
ISO/IEC 17025 accreditation for cannabis testing laboratories is bifurcating competitive access in the marijuana sensors sector. Hound Labs, Inc. leverages its dual alcohol-THC breathalyzer platform to anchor law enforcement demand. Soter Technologies, LLC specializes in environmental vapor detection for institutional settings. STORZ & BICKEL GmbH dominates precision hardware integration with medical-grade extraction systems.
Marijuana sensors are electrochemical, optical, or semiconductor-based devices engineered to detect tetrahydrocannabinol (THC), cannabidiol (CBD), or volatile organic compounds at parts-per-billion sensitivity, primarily serving regulatory compliance, quality assurance, and security screening functions. Environmental Sensors lead product-type revenue due to continuous air-quality mandates in enclosed grow operations, while IoT-enabled deployments capture the fastest expansion as cultivators integrate real-time canopy monitoring with automated climate control. Cloud-Based deployment models concentrate margin pools through recurring software-subscription revenue layered over hardware sales.
The FDA oversees cannabis product quality thresholds, while the DEA's controlled-substance scheduling directly constrains sensor deployment in federal jurisdictions. State-level cannabis legalization frameworks, including California's Bureau of Cannabis Management requirements and Colorado's Marijuana Enforcement Division rules, create fragmented but substantial compliance-driven demand. Stakeholders must monitor pending federal rescheduling decisions that would instantly reshape interstate commerce and sensor standardization requirements.
Market Dynamics
The marijuana sensors sector is being fundamentally restructured by the collision of precision agriculture mandates with fragmented federal-state regulatory divergence, forcing manufacturers to engineer dual-calibration systems for conflicting compliance frameworks.
Growth Catalysts
- California Bureau of Cannabis Management air-quality mandates:Licensed cultivators must deploy continuous volatile organic compound monitoring, creating baseline demand for environmental sensor arrays.
- Roadside THC detection procurement:State police departments are acquiring portable breathalyzer-equivalent devices for impaired-driving enforcement.
- Cloud-native architecture penetration:Cultivation facilities are replacing on-premise data loggers with subscription-based analytics platforms.
Market Restraints
- DEA Schedule I classification:Federal prohibition blocks interstate sensor calibration standardization and restricts research-grade device deployment.
- Indium tin oxide supply concentration:Optical sensor manufacturers face input cost volatility from concentrated East Asian refining capacity.
- Cross-reactivity limitations:Electrochemical sensors struggle to distinguish THC from structurally similar cannabinoids in complex matrices.
Strategic Opportunities
- German BfArM medical cannabis framework expansion:Europe's largest reimbursed market is mandating GMP-compliant quality control infrastructure.
- AI-driven spectral analysis convergence:Machine learning algorithms paired with near-infrared sensors enable real-time cannabinoid potency prediction.
- Direct-to-grower e-commerce channels:Bypassing traditional horticultural distribution unlocks margin capture in mid-scale operations.
Industry Challenges
- ISO/IEC 17025 accreditation timelines:Laboratory sensor validation protocols extend 18-24 months, delaying product commercialization.
- Legacy climate control integration:Retrofitting IoT sensors into existing HVAC systems requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marijuana Sensors Market |
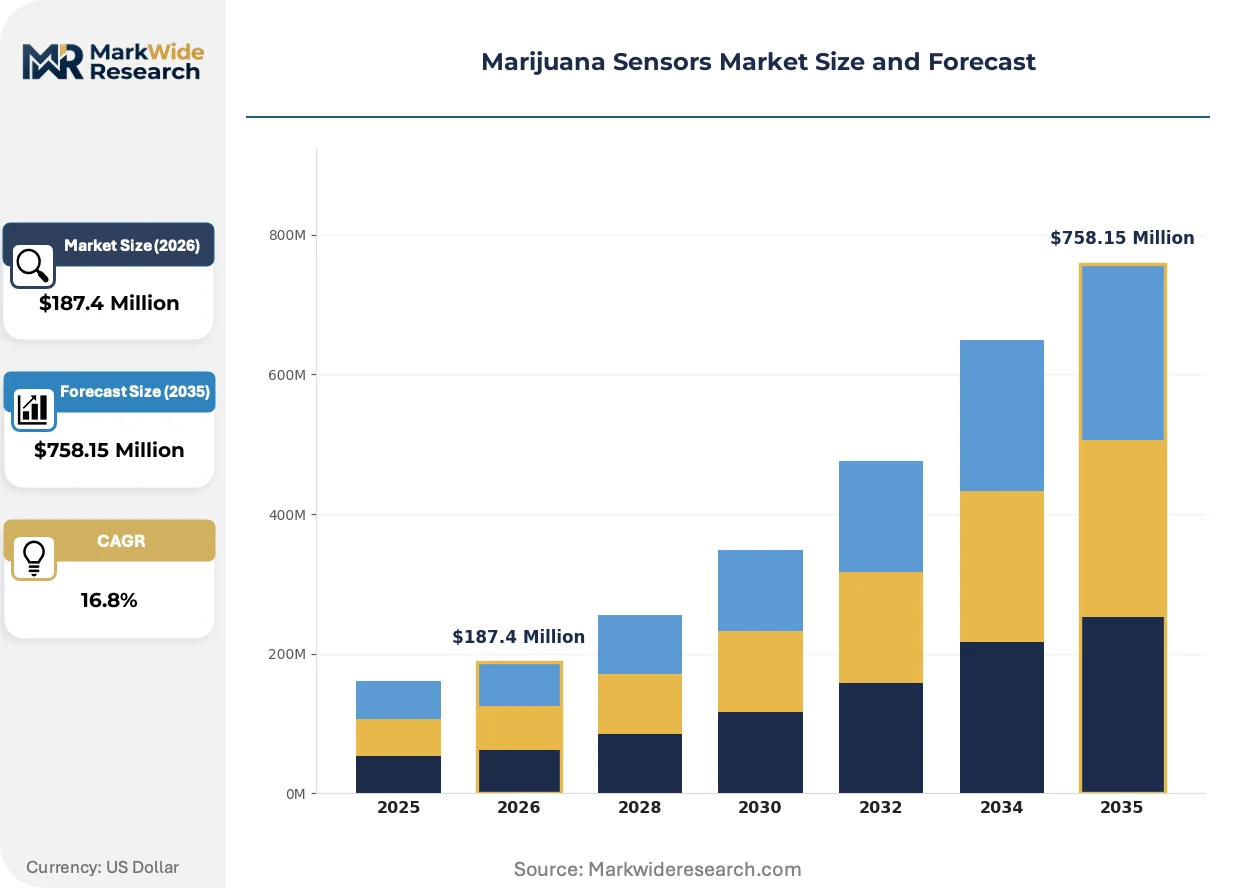
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soil Sensors, Environmental Sensors, Light Sensors, Moisture Sensors Deployment: On-Premises, Cloud-Based, Hybrid, Remote End User: Cultivators, Research Facilities, Dispensaries, Agricultural Firms Technology: IoT, RFID, Wireless, Analog |
| Companies Covered | Forensics Detectors, LLC, Soter Technologies, LLC, Swift Sensors, Inc., Triton Sensors LLC, Hound Labs, Inc., tCheck, Syqe Medical, Resolve Digital Health, STORZ & BICKEL GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marijuana Sensors Market Evolving Landscape
Sensor architecture is pivoting from discrete hardware sales toward integrated data-service ecosystems, with hardware margins compressing while software-subscription revenue pools deepen.
Surface-enhanced Raman spectroscopy is miniaturizing from benchtop laboratory instruments to handheld field devices. Cultivators in Colorado and Oregon are adopting these units for at-harvest potency screening. The technology is miniaturizing quality-control workflows previously requiring third-party laboratory outsourcing, compressing testing turnaround from days to minutes.
EMA's evolving guidance on cannabis-based medicinal products is forcing manufacturers to validate sensor traceability chains under pharmaceutical GMP. Industrial consequence includes mandatory audit trails for every calibration event. Medical-grade extraction facilities in the Netherlands and Denmark are retrofitting environmental monitoring systems to meet these documentation requirements.
Buyer purchasing patterns are consolidating around bundled sensor-analytics contracts rather than standalone hardware procurement. Distributors serving commercial greenhouses are repositioning as full-stack compliance partners. This consolidation is most visible in California's Central Valley, where multi-facility operators negotiate enterprise-wide monitoring agreements spanning dozens of licensed sites.
Marijuana Sensors Market Segmentation
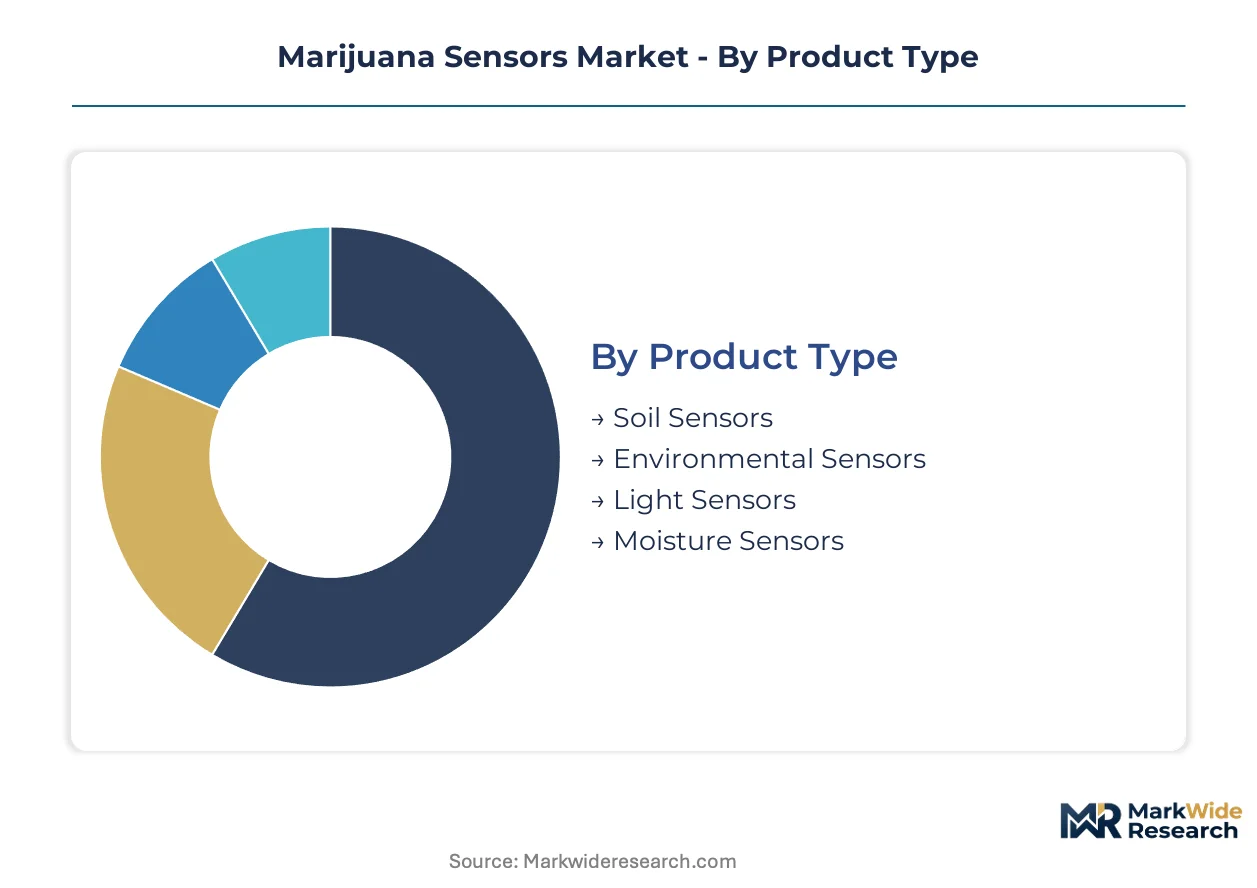
Segmentation in the marijuana sensors market reveals how regulatory fragmentation and cultivation scale reshape procurement patterns. Buyers cluster around distinct technology tiers based on compliance burden and operational sophistication.
Product Type:
Environmental Sensors anchor domestic demand through California's air-quality mandates, while Soil Sensors follow export-led trajectories into European medical cannabis frameworks.
- Environmental Sensors:These devices monitor volatile organic compounds, temperature, and humidity at parts-per-billion sensitivity. California's Bureau of Cannabis Management mandates continuous VOC monitoring in enclosed grow operations, forcing licensed cultivators to deploy dense sensor arrays. Compliance deadlines compress procurement cycles.
- Soil Sensors:Electrochemical probes measure pH, electrical conductivity, and nutrient ion concentration in root-zone substrates. German BfArM GMP requirements for medical cannabis are driving sensor density in Dutch and Danish greenhouse operations. Precision agriculture subsidies accelerate replacement cycles.
- Light Sensors:Quantum PAR sensors quantify photosynthetic photon flux density across canopy layers. Colorado's Marijuana Enforcement Division tracks energy efficiency metrics.
- Moisture Sensors:Tensiometers and capacitance probes manage irrigation scheduling in drought-stressed cultivation regions. Oregon's water-use reporting requirements shape specification sheets.
Environmental Sensors command the established base. The steepest expansion runs through Soil Sensors.
Deployment:
Margin structures diverge sharply across deployment modes, with recurring revenue models concentrating in subscription tiers and capital expenditure patterns dominating perpetual-license segments.
- Cloud-Based:Architecture delivers real-time analytics through API-connected dashboards with automated threshold alerting. California multi-facility operators negotiate enterprise agreements spanning dozens of licensed sites. Subscription layering over hardware compresses customer acquisition costs.
- On-Premises:Local data logging with air-gapped security architecture serves research facilities under DEA Schedule I constraints. Federal prohibition blocks cloud data transmission for controlled-substance studies. Capital budgeting cycles extend 24-36 months.
- Hybrid:Edge computing with selective cloud synchronization balances latency requirements against compliance documentation. Mid-scale cultivators in Michigan and Illinois favor this architecture.
- Remote:Satellite or cellular-connected units serve outdoor cultivation in remote Oregon and Northern California counties. Connectivity dead zones drive specialized hardware specifications.
On-Premises retains the compliance-driven core. Cloud-Based deployments are climbing the fastest.
End User:
Customer concentration patterns reflect licensing density, with vertically integrated operators demanding bundled sensor-analytics contracts and fragmented craft cultivators prioritizing standalone hardware.
- Cultivators:Licensed grow operations from craft-scale to multi-acre greenhouse complexes. California's Central Valley corridor concentrates procurement volume through enterprise monitoring agreements.
- Research Facilities:Academic and private laboratories studying cannabinoid biosynthesis and extraction optimization. DEA licensing requirements constrain vendor qualification.
- Dispensaries:Retail operations requiring security screening and quality verification at point of sale. State-level testing mandate variations create specification complexity.
- Agricultural Firms:Diversified horticultural companies entering cannabis through existing greenhouse infrastructure. Legacy climate control retrofit requirements shape integration costs.
Cultivators absorb the dominant share. Research Facilities are gaining share fastest amid federal rescheduling anticipation.
Technology:
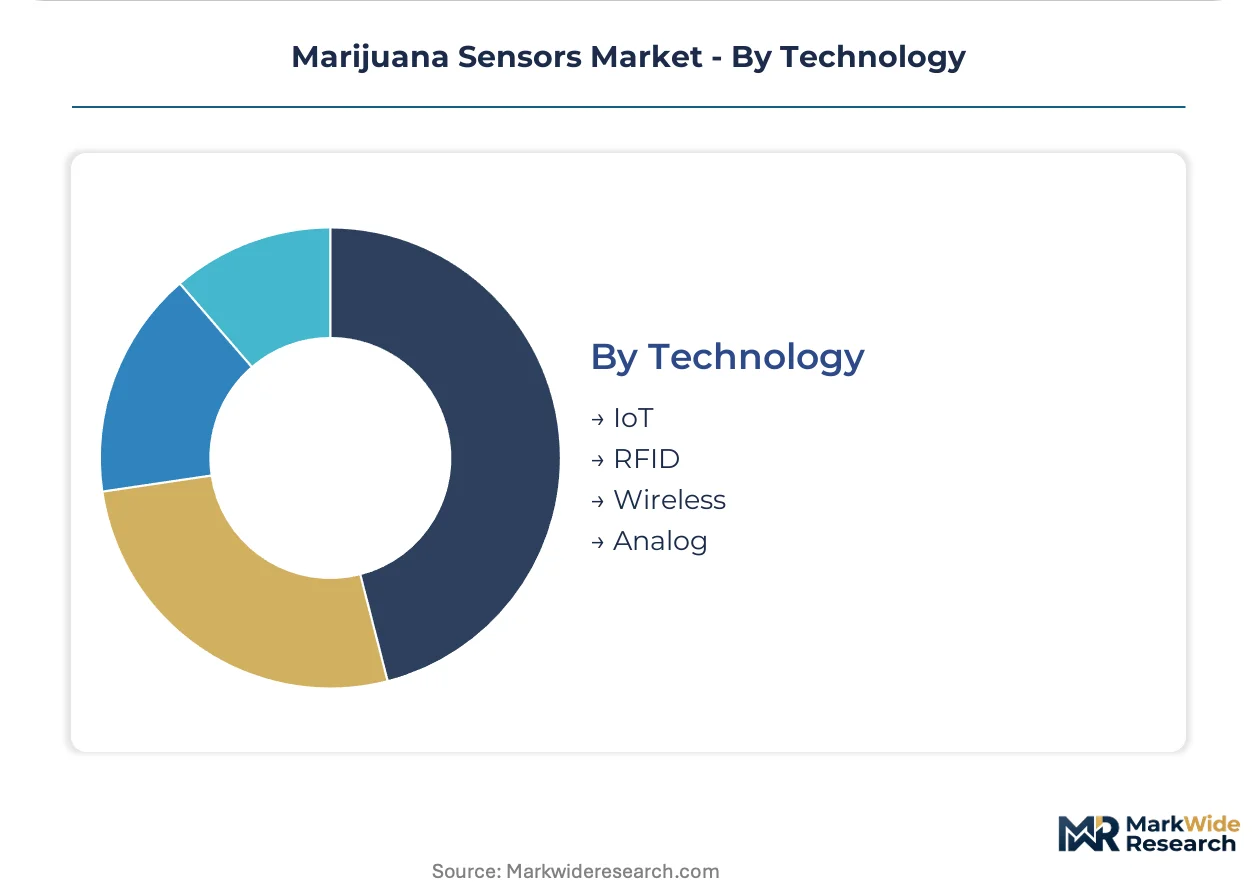
Interoperability standards fragment across protocol generations, with legacy wireless installations constraining upgrade paths and greenfield deployments favoring mesh-networked IoT architectures.
- IoT:Mesh-networked sensors with MQTT protocol integration enable real-time canopy monitoring with automated climate control feedback loops. Colorado cultivators lead adoption of AI-driven spectral analysis convergence. Machine learning algorithms paired with near-infrared sensors enable at-harvest potency prediction.
- Wireless:Proprietary RF protocols and LoRaWAN deployments serve extended-range outdoor cultivation. FCC Part 15 compliance certification adds 6-9 months to product launch timelines.
- RFID:Track-and-trace compliance for seed-to-sale inventory management. State-level traceability system variations force multi-protocol hardware support.
- Analog:Legacy 4-20mA and voltage-output sensors in retrofit installations. HVAC integration middleware requirements extend deployment timelines.
Wireless retains the installed base. IoT represents the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal rescheduling anticipation in the United States is accelerating sensor procurement cycles, while Germany's BfArM medical cannabis expansion and Canada's mature legalization framework are reshaping compliance-driven demand across North America and Europe.
United States
California's Bureau of Cannabis Management mandates continuous volatile organic compound monitoring in enclosed grow operations, forcing licensed cultivators in the Central Valley corridor to deploy dense environmental sensor arrays. The DEA's Schedule I classification blocks interstate calibration standardization, constraining research-grade device deployment. Colorado's Marijuana Enforcement Division tracks energy efficiency metrics, driving quantum PAR sensor adoption across Denver-Boulder cultivation clusters.
Germany
BfArM's medical cannabis framework expansion mandates GMP-compliant quality control infrastructure across reimbursed cultivation operations. EMA guidance on cannabis-based medicinal products requires validated sensor traceability chains with mandatory audit trails for every calibration event. Dutch and Danish greenhouse operators serving German demand are retrofitting environmental monitoring systems in the Venlo region and Aalsmeer cluster.
Canada
Health Canada's cannabis regulations impose strict quality assurance testing requirements, driving laboratory sensor validation protocols. The country's federal legalization enables cloud-based deployment models without Schedule I constraints blocking data transmission. Ontario's Niagara region and British Columbia's Okanagan Valley concentrate precision agriculture sensor density among licensed producers.
Netherlands
Medical-grade extraction facilities in the Randstad region retrofit environmental monitoring systems to meet pharmaceutical GMP documentation requirements. The country's mature greenhouse horticulture infrastructure accelerates IoT sensor integration with legacy climate control systems. Wageningen University's agrotech research cluster advances spectral analysis convergence for real-time cannabinoid potency prediction.
Australia
TGA's evolving guidance on medicinal cannabis products shapes quality-control sensor specifications for licensed domestic production. Victoria's Gippsland region and Queensland's Sunshine Coast host emerging cultivation operations adopting cloud-native monitoring architectures. The country's isolated geography drives remote satellite-connected sensor deployments for outdoor cultivation compliance.
Marijuana Sensors Market Competitive Landscape
Player mix skews toward specialized technology developers with dual-use platform capabilities, creating a tiered structure where breathalyzer-equivalent device manufacturers occupy premium positions alongside environmental monitoring specialists. Three strategic archetypes dominate: law enforcement-focused portable detection developers, precision agriculture IoT integrators, and medical-grade extraction system hardware partners. Competitive moves concentrate on strategic partnerships bridging sensor hardware with analytics software, plus geographic expansion into newly regulated European medical cannabis markets.
Within the law enforcement-focused tier, Hound Labs, Inc. and Triton Sensors LLC represent portable detection platform developers, while Soter Technologies, LLC exemplifies environmental vapor detection specialization for institutional settings. STORZ & BICKEL GmbH anchors the medical-grade hardware integration archetype. These three companies occupy distinct competitive positions shaped by regulatory fragmentation across federal and state jurisdictions, with each archetype capturing margin pools tied to specific compliance mandates rather than undifferentiated hardware sales.
| Leading Market Players |
|---|
| Forensics Detectors, LLC |
| Soter Technologies, LLC |
| Swift Sensors, Inc. |
| Triton Sensors LLC |
| Hound Labs, Inc. |
| tCheck |
| Syqe Medical |
| Resolve Digital Health |
| STORZ & BICKEL GmbH |
| Others |
Value Network & Pricing Analysis
ISO/IEC 17025 laboratory accreditation gates both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb extended validation timelines while cultivators pay premiums for certified calibration chains.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA-grade and ISO/IEC 17025-accredited sensors commanding substantial premiums over uncertified alternatives. SaaS-tiered subscription models dominate cloud-based deployments, while per-unit transactional pricing persists for standalone hardware in craft-scale operations. Price differentiation reflects calibration traceability depth and GMP documentation capabilities. Cost compression in standard-tier environmental sensors intensifies as Asian manufacturers expand production capacity. Craft cultivators exhibit highest price sensitivity, while multi-facility operators in California's Central Valley prioritize bundled sensor-analytics contracts over unit economics.
Supply Chain Analysis
Inventory lead times for indium tin oxide and specialized optical components extend 16-24 weeks, constraining production responsiveness for near-infrared and Raman spectroscopy devices. Manufacturing concentrates in Germany for medical-grade extraction systems, the United States for law enforcement breathalyzer platforms, and China for commodity environmental sensor arrays. Raw material dependencies include rare-earth phosphors, precision optical filters, and electrochemical electrode substrates. Single-source vulnerability in East Asian indium refining capacity exposes margin volatility. Distribution runs through horticultural equipment distributors repositioning as compliance partners, plus direct-to-grower e-commerce channels for mid-scale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution by laboratory outsourcing services and DIY spectral analysis kits that threaten to commoditize at-harvest potency screening.
For Market Incumbents: Fortify calibration service revenue through captive ISO/IEC 17025 laboratory networks, locking cultivators into recurring validation contracts. Deepen backward integration into optical component supply to offset indium tin oxide price volatility. Prioritize middleware development for legacy HVAC integration to defend against retrofit-focused challengers. For New Entrants and Emerging Players: Differentiate on AI-driven spectral analysis convergence, targeting mid-scale cultivators in Michigan and Illinois underserved by enterprise-focused incumbents. White-space opportunities concentrate in German BfArM-compliant GMP documentation systems for Dutch and Danish greenhouse operators. Pursue direct-to-grower e-commerce channels bypassing traditional horticultural distribution. For Investors and Strategic Acquirers: Federal rescheduling anticipation reshapes the acquisition landscape, elevating targets with DEA research-grade device approvals and interstate calibration standardization capabilities. Long-term viability hinges on software-subscription revenue depth rather than hardware shipment volumes. Monitor FDA guidance evolution on cannabis-derived compounds as the critical inflection signal for quality-control infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 17025 Laboratory Accreditation | Unlocks premium pricing in California Bureau of Cannabis Management compliance-driven procurement. |
| AI-Driven Spectral Analysis Integration | Enables real-time cannabinoid potency prediction for Colorado cultivators compressing testing workflows. |
| Backward Integration into Optical Components | Reduces exposure to East Asian indium tin oxide supply concentration and price volatility. |
| Cloud-Native Platform Expansion | Captures recurring software-subscription revenue from California multi-facility enterprise agreements. |
| German BfArM Compliance Certification | Opens Europe's largest reimbursed medical cannabis market with mandatory audit trail requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA enforcement letters, state cannabis regulatory filings, and DEA controlled-substance research registrations. Conversations with cultivation operations managers, compliance officers at licensed California facilities, environmental sensor procurement leads, and laboratory accreditation auditors informed demand-side validation. Secondary sources include Health Canada cannabis regulations, German BfArM medical cannabis framework documents, EMA guidance publications, and SEC filings from publicly traded horticultural technology providers. Bottom-up unit economics triangulate against top-down market sizing across product type, deployment model, and end-user segments.
Segmentation dimensions modeled span environmental versus soil versus light sensor categories, cloud-based versus on-premises versus hybrid deployment architectures, and cultivator versus research facility versus dispensary end-user archetypes. Technology tier segmentation incorporates IoT-enabled, wireless, RFID, and analog protocol generations. CAGRs derive from regression analysis of historical procurement patterns against regulatory mandate implementation timelines. Industry-specific forecast inputs include California Bureau of Cannabis Management air-quality compliance deadlines and German BfArM GMP infrastructure rollout schedules.
Material uncertainties — federal rescheduling decisions, DEA Schedule I reclassification timing, and EMA pharmaceutical GMP guidance evolution — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding state-level legalization progression and laboratory accreditation adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
Missouri Medical Cannabis Market
Cannabis/Marijuana
CBD Hemp Oil Market
Cannabis/Marijuana
Cannabis Concentrate Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Market
Cannabis/Marijuana
Global Marijuana Market
Cannabis/Marijuana
Global Cannabis ERP Software Market
Cannabis/Marijuana
Trichome Separator/Extractor Market
Cannabis/Marijuana
Cannabis Infused Edible Products Market
Cannabis/Marijuana
Morocco Medical Cannabis Market
Cannabis/Marijuana
Synthetic Cannabinoids Market
Cannabis/Marijuana
Arizona Legal Cannabis Market
Cannabis/Marijuana
Biometric Cannabis Storage Boxes Market
Cannabis/Marijuana
Handheld Marijuana Vaporizer Market
Cannabis/Marijuana
CBD Gummies Market
Cannabis/Marijuana
Cannabis Technology Market