
 Global Rapid Test Market | 2026-2036
Global Rapid Test Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rapid Test Market Foresight
Clinical laboratory technician shortages across developed health systems is collapsing throughput capacity at centralized diagnostic facilities. Abbott leverages its vertically integrated manufacturing footprint to sustain supply continuity for immunoassay platforms. Thermo Fisher Scientific dominates molecular rapid test development through its controlled distribution of reagent kits and thermal cycler compatibility. Roche Diagnostics anchors European market access through its specialized channel relationships with hospital procurement networks.
A rapid test delivers diagnostic results within minutes through portable devices that detect target analytes via immunochromatographic, enzymatic, or nucleic acid amplification reactions without laboratory infrastructure. Lateral flow strips typically operate at 15-30 nanogram per milliliter sensitivity thresholds using cellulose nitrate membranes conjugated with colored nanoparticles for visual readout. Immunoassay formats command the largest margin pools in hospital settings where quantitative biomarker thresholds guide treatment decisions. Molecular segments represent the fastest-growing category as polymerase chain reaction miniaturization enables same-day pathogen identification at remote clinics previously dependent on centralized laboratories.
The FDA's Emergency Use Authorization framework and the EMA's CE-IVD marking requirements under the In Vitro Diagnostic Medical Devices Regulation shape product development timelines and market entry pathways for manufacturers. India's CDSCO enforces import licensing and local clinical validation standards that filter non-compliant devices from government procurement channels. Stakeholders must monitor evolving reimbursement codes for home testing deployments as payers recalibrate coverage models between supervised and self-administered diagnostic encounters.
Market Dynamics
Decentralized diagnostic infrastructure is compressing testing timelines from days to minutes, forcing manufacturers to reconfigure supply chains around portable consumables rather than capital-intensive laboratory instruments.
Growth Catalysts
- EU IVDR Compliance Deadlines:The European Union's In Vitro Diagnostic Medical Devices Regulation is accelerating product portfolio rationalization among established manufacturers, clearing shelf space for compliant rapid test platforms in hospital procurement channels.
- Cellulose Nitrate Membrane Advances:Improved conjugation chemistry at 15-30 nanogram per milliliter sensitivity thresholds is expanding infectious disease detection capabilities into resource-limited settings without cold chain requirements.
- India CDSCO Localization Mandates:India's Central Drugs Standard Control Organization import licensing requirements are filtering non-compliant devices from government procurement, creating protected market access for validated domestic and regional manufacturers.
Market Restraints
- Reagent Kit Concentration:Controlled distribution of polymerase chain reaction reagent kits by dominant suppliers creates supply vulnerability for molecular rapid test manufacturers dependent on thermal cycler compatibility.
- Clinical Validation Costs:Multi-site prospective studies required for FDA Emergency Use Authorization pathway entry impose capital barriers that exclude mid-scale developers from infectious disease screening segments.
- Lateral Flow Sensitivity Ceiling:Immunochromatographic visual readout formats face fundamental detection limits that exclude quantitative biomarker applications requiring picogram-level precision.
Strategic Opportunities
- German Hospital Procurement Networks:Specialized channel relationships with decentralized testing infrastructure programs offer first-mover positioning for quantitative immunoassay platforms in Europe's largest diagnostic market.
- Home Testing Reimbursement Recalibration:Payer coverage model evolution between supervised and self-administered diagnostic encounters is opening reimbursed distribution channels previously restricted to clinical settings.
- PCR Miniaturization Convergence:Integration of isothermal amplification with smartphone-connected readers is enabling same-day pathogen identification at remote clinics previously dependent on centralized laboratory networks.
Industry Challenges
- Clinical Laboratory Technician Scarcity:Collapsing throughput capacity at centralized diagnostic facilities is forcing rapid test manufacturers to absorb training and quality assurance responsibilities previously handled by hospital laboratory staff.
- Multi-Jurisdiction Certification Timelines:Parallel FDA Emergency Use Authorization, EMA CE-IVD marking, and CDSCO import licensing processes create product launch delays that compress commercialization windows for time-sensitive infectious disease assays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rapid Test Market |
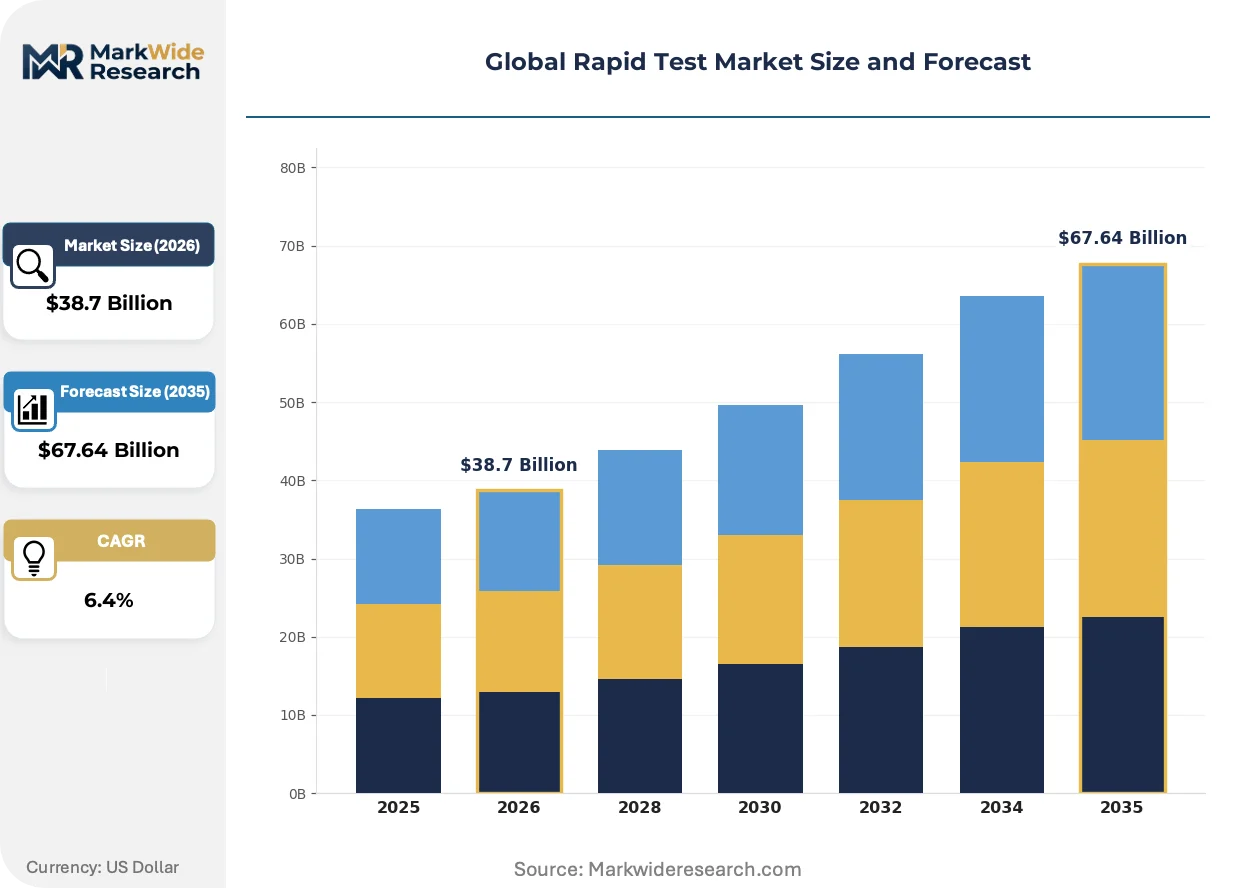
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Lateral Flow, Immunoassay, Molecular, Enzyme Immunoassay, Agglutination End User: Diagnostic Laboratories, Point-of-Care Centers, Blood Banks, Research Institutes, Pharmaceutical Companies Application: Infectious Disease Detection, Pregnancy Screening, Drug Abuse Testing, Food Safety, Environmental Testing Deployment: Hospital Settings, Remote Clinics, Home Testing Kits, Mobile Testing Units, Clinics |
| Companies Covered | Becton, Dickinson and Company, Thermo Fisher Scientific, Abbott, Quidel Corporation, Hologic, Roche Diagnostics, bioMérieux SA, Bio-Rad Laboratories, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rapid Test Market Shifts & Advancements
Miniaturization of nucleic acid amplification is collapsing the boundary between rapid antigen detection and laboratory-grade molecular diagnostics, enabling portable platforms to capture applications previously reserved for centralized infrastructure.
Isothermal amplification chemistry paired with smartphone-connected readers is supplanting traditional thermal cycler dependence in remote clinic deployments. Community health centers in sub-Saharan Africa and Southeast Asia are adopting these platforms at accelerating pace. The structural consequence is a compression in the addressable market for centralized laboratory polymerase chain reaction contracts in infectious disease screening programs.
The FDA's Emergency Use Authorization framework has normalized accelerated regulatory pathways for novel diagnostic platforms, creating permanent institutional expectations for pandemic-responsive product development timelines. Manufacturers now maintain parallel regulatory track systems to preserve optionality for emergency pathway activation. Molecular rapid test segments have reorganized R&D staffing models around 90-day validation sprint capabilities rather than traditional 18-month submission cycles.
Hospital procurement networks are consolidating vendor relationships around vertically integrated suppliers capable of sustaining supply continuity through manufacturing footprint control. Abbott's captive production of immunoassay consumables has become a reference standard in contract negotiations. German and United States health systems now embed supply resilience clauses into multi-year procurement agreements, penalizing manufacturers dependent on outsourced membrane or conjugate production.
Global Rapid Test Market Segmentation
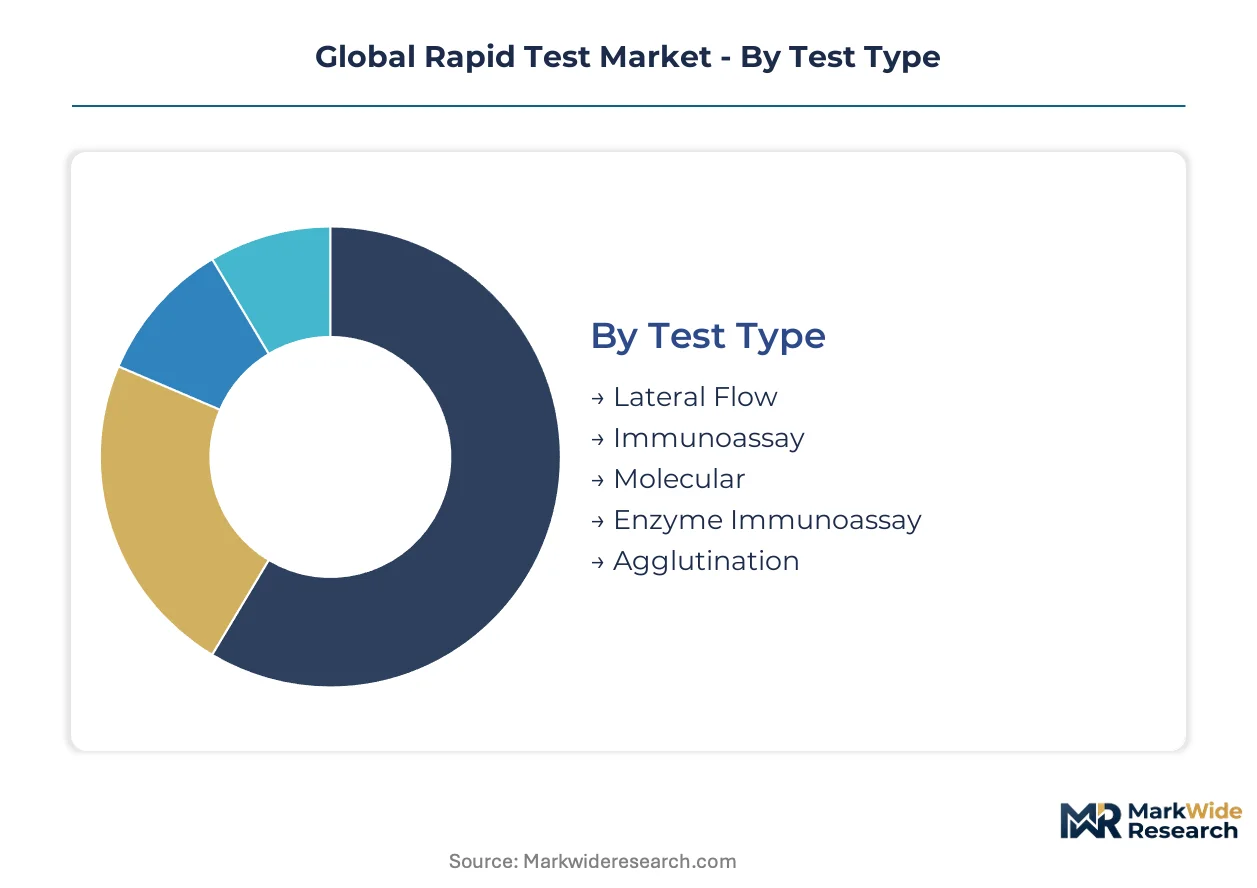
Test format selection determines margin capture and regulatory pathway complexity for manufacturers serving decentralized diagnostic networks. Category boundaries are blurring as molecular miniaturization enables portable platforms to absorb applications previously reserved for laboratory infrastructure.
Test Type:
Immunoassay formats command the largest margin pools in hospital procurement channels where quantitative biomarker thresholds guide treatment protocols.
- Lateral Flow:Cellulose nitrate membranes conjugated with colored nanoparticles enable visual readout at 15-30 nanogram per milliliter sensitivity thresholds. Demand concentrates in India's government screening programs and sub-Saharan African community health centers where cold chain independence is mandatory.
- Immunoassay:Quantitative platforms using enzymatic or chemiluminescent detection achieve picogram-level precision for cardiac marker and hormone panels. Hospital laboratories in Germany and the United States prioritize these formats for emergency department throughput where result turnaround directly affects admission decisions.
- Molecular:Polymerase chain reaction miniaturization enables same-day pathogen identification at remote clinics previously dependent on centralized laboratories.
- Enzyme Immunoassay:Microplate-based detection systems serve blood bank screening protocols requiring documented serological traceability.
- Agglutination:Simple slide or card-based formats persist in resource-limited settings for blood typing and rapid syphilis detection.
The dominant share belongs to Immunoassay, while Molecular is closing the gap fastest.
End User:
Procurement authority is shifting from centralized laboratory directors to point-of-care nursing staff and procurement networks managing decentralized inventory.
- Diagnostic Laboratories:High-throughput facilities in the United States and Germany remain anchor customers for quantitative platforms requiring automated sample handling and LIS integration.
- Point-of-Care Centers:Emergency departments, urgent care clinics, and physician offices in India and Germany are expanding lateral flow adoption for infectious disease screening where technician scarcity constrains laboratory capacity.
- Blood Banks:Serological screening mandates drive demand for agglutination and enzyme immunoassay formats with documented batch traceability.
- Research Institutes:Validation studies for FDA Emergency Use Authorization pathway entry create contract revenue for manufacturers with established clinical trial networks.
- Pharmaceutical Companies:Companion diagnostic development partnerships require molecular rapid test platforms with regulatory submission support capabilities.
Point-of-Care Centers now absorb the steepest volume expansion trajectory, though Diagnostic Laboratories retain pricing power on complex panels.
Application:
Infectious disease screening generates the highest absolute revenue as pandemic-era infrastructure investment persists across health systems.
- Infectious Disease Detection:Respiratory, sexually transmitted, and tropical pathogen panels dominate procurement budgets in India, the United States, and Germany following FDA Emergency Use Authorization normalization.
- Pregnancy Screening:Human chorionic gonadotropin lateral flow devices command stable replacement demand in retail pharmacy and clinic channels across all major markets.
- Drug Abuse Testing:Workplace and forensic applications in the United States drive demand for multi-panel immunoassay cups with adulteration detection features.
- Food Safety:Pathogen and allergen detection kits serve commercial kitchen and processing plant quality assurance protocols.
- Environmental Testing:Water quality and soil contamination assays remain niche applications with concentrated demand from regulatory compliance monitoring programs.
Infectious Disease Detection holds the dominant position, while Drug Abuse Testing is gaining share fastest in workplace screening expansion.
Deployment:
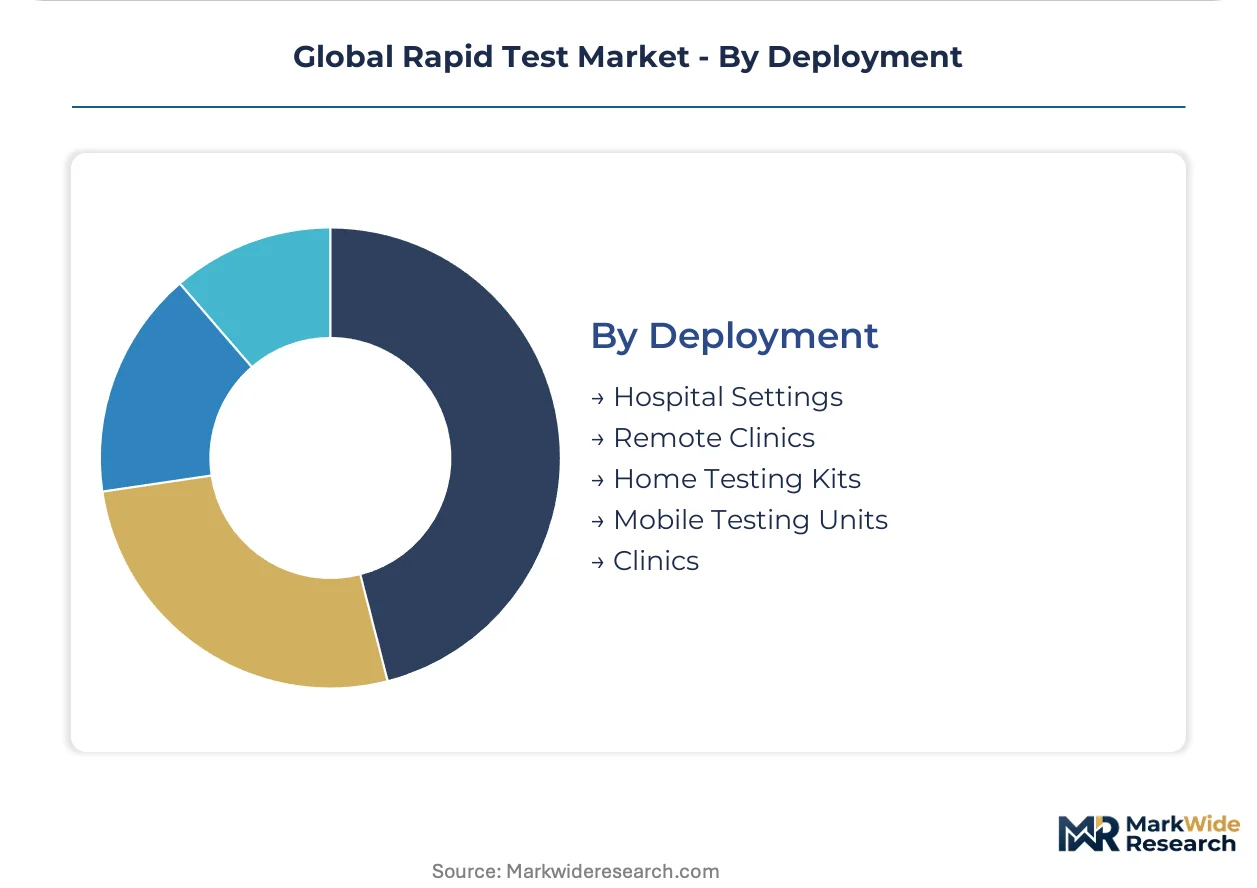
Channel selection determines reimbursement eligibility and regulatory classification under FDA, EMA, and CDSCO frameworks.
- Hospital Settings:Emergency departments and inpatient units in Germany and the United States prioritize quantitative immunoassay platforms integrated with electronic medical record systems.
- Remote Clinics:Community health centers in India and sub-Saharan Africa are adopting isothermal amplification with smartphone-connected readers for same-day pathogen identification.
- Home Testing Kits:Pregnancy, HIV, and COVID-19 self-tests are expanding reimbursed distribution channels as payers recalibrate coverage models between supervised and self-administered encounters.
- Mobile Testing Units:Temporary screening infrastructure deployed for outbreak response and rural health campaigns in India creates surge demand for cold-chain-independent lateral flow stockpiles.
- Clinics:Physician office laboratories in the United States represent a contracting segment as regulatory complexity drives test referral to centralized facilities or point-of-care simplification.
Hospital Settings retain the dominant share, though Remote Clinics are expanding most quickly as PCR miniaturization collapses infrastructure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's Emergency Use Authorization pathway anchors United States market structure, while Germany's EMA CE-IVD marking requirements and India's CDSCO localization mandates shape parallel entry corridors for rapid test manufacturers.
United States
Emergency departments and urgent care clinics drive point-of-care expansion as laboratory technician shortages constrain centralized capacity. The FDA maintains accelerated review pathways established during pandemic-era authorization frameworks. Boston-Cambridge and Research Triangle Park clusters concentrate molecular rapid test development operations for infectious disease screening.
Germany
Hospital procurement networks prioritize quantitative immunoassay platforms with electronic medical record integration for emergency department throughput. EMA CE-IVD marking under IVDR compliance deadlines filters non-compliant devices from European market entry. The Rhine-Ruhr and Baden-Württemberg industrial corridors host specialized distribution relationships between diagnostic manufacturers and decentralized testing infrastructure programs.
India
Government screening programs and community health centers absorb lateral flow volume for tropical pathogen detection without cold chain requirements. CDSCO import licensing mandates and local clinical validation standards protect domestic and regional manufacturers from non-compliant foreign competition. Mumbai-Pune and Bengaluru clusters concentrate manufacturing operations for cellulose nitrate membrane conjugation chemistry at 15-30 nanogram per milliliter sensitivity thresholds.
China
Domestic diagnostic infrastructure investment supports isothermal amplification platform adoption for same-day pathogen identification at remote clinics. NMPA regulatory submission requirements align with international standards while maintaining separate approval timelines for domestic market entry. The Yangtze River Delta and Pearl River Delta manufacturing basins supply smartphone-connected reader components for PCR miniaturization convergence.
Japan
Aging population demographics and rural health access gaps accelerate home testing kit deployment for pregnancy and infectious disease self-screening. PMDA regulatory frameworks emphasize clinical validation standards comparable to FDA and EMA pathways. The Kanto region around Tokyo anchors pharmaceutical company companion diagnostic partnerships requiring molecular rapid test platforms with regulatory submission support capabilities.
Global Rapid Test Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Global Rapid Test Market structure. Vertically integrated manufacturers with captive membrane and conjugate production control supply continuity clauses in multi-year procurement agreements. The competitive landscape organizes around three archetypes: diversified life science conglomerates with diagnostic divisions, pure-play rapid test specialists, and molecular platform innovators. Dominant competitive moves include backward integration into consumables manufacturing and strategic partnerships with hospital procurement networks for decentralized testing infrastructure deployment.
Within the diversified conglomerate tier, Becton, Dickinson and Company and Danaher Corporation represent integrated manufacturers with broad diagnostic portfolios spanning multiple test formats. Thermo Fisher Scientific exemplifies the molecular platform archetype through controlled reagent kit distribution and thermal cycler compatibility positioning. Abbott anchors the vertically integrated specialist category with captive immunoassay consumable production that has become a reference standard in German and United States contract negotiations.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Thermo Fisher Scientific |
| Abbott |
| Quidel Corporation |
| Hologic |
| Roche Diagnostics |
| bioMérieux SA |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
Cellulose nitrate membrane production at 15-30 nanogram per milliliter sensitivity thresholds anchors scale economies in rapid test manufacturing, concentrating supply continuity leverage among manufacturers with captive conjugate chemistry operations while compressing price floors for outsourced competitors.
Pricing Analysis
Price spreads between Germany and India exceed threefold for equivalent lateral flow devices, reflecting divergent reimbursement frameworks and cold chain infrastructure requirements. Three-tier pricing structure across premium, standard, and economy levels separates quantitative immunoassay platforms from visual-readout strips and agglutination formats. Cost compression in economy tiers is intensifying because CDSCO localization mandates filter non-compliant imports from government procurement channels. Diagnostic laboratories in the United States exhibit lowest price sensitivity due to emergency department throughput priorities, while community health centers in sub-Saharan Africa face acute budget constraints.
Supply Chain Analysis
Inventory buffers for thermal cycler-compatible reagent kits extend lead times for molecular rapid test manufacturers dependent on controlled distribution networks. Manufacturing gravity centers on China for smartphone-connected reader components, India for cellulose nitrate membrane conjugation, and Germany for quantitative immunoassay platform assembly. Raw material dependencies span gold nanoparticles, nitrocellulose membranes, and isothermal amplification enzymes. Single-source vulnerability concentrates in polymerase chain reaction reagent supply controlled by dominant life science conglomerates. Distribution runs through hospital procurement networks in developed markets and government tender systems in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of clinical laboratory technicians capable of validating decentralized testing platforms is restructuring procurement authority toward point-of-care nursing staff, creating capability gaps that manufacturers must fill through embedded training and quality assurance services.
For Market Incumbents: Compound supply resilience advantages by deepening backward integration into membrane and conjugate production while embedding supply continuity clauses into multi-year German and United States hospital procurement agreements. Threats from PCR miniaturization convergence demand accelerated R&D staffing models around 90-day validation sprint capabilities. Certification investment in parallel FDA Emergency Use Authorization and EMA CE-IVD marking track systems preserves optionality for emergency pathway activation.
For New Entrants and Emerging Players: FDA Emergency Use Authorization fast-track positioning enables first-mover capture of infectious disease screening segments where multi-site prospective studies exclude mid-scale developers. White-space targets concentrate in isothermal amplification with smartphone-connected readers for remote clinics in sub-Saharan Africa and Southeast Asia, plus home testing reimbursement recalibration opportunities in Japan's aging demographic markets. Go-to-market execution should prioritize specialized channel relationships with decentralized testing infrastructure programs over direct hospital laboratory sales.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with captive consumables production and established clinical trial networks for regulatory submission support. Long-term viability across the analysis window hinges on absorption of training and quality assurance responsibilities previously handled by hospital laboratory staff. Acquisition target archetype: molecular platform innovators with thermal cycler compatibility and parallel regulatory track capabilities. Signal to watch: payer coverage model evolution between supervised and self-administered diagnostic encounters as inflection indicator for home testing kit deployment scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Production | Abbott's captive cellulose nitrate manufacturing secures supply continuity clauses in German hospital procurement networks. |
| Parallel Regulatory Track Systems | Manufacturers preserving FDA Emergency Use Authorization and EMA CE-IVD optionality capture pandemic-responsive product development timelines. |
| Isothermal Amplification Platform Launch | Smartphone-connected readers enable same-day pathogen identification at remote clinics previously dependent on centralized laboratories. |
| Hospital System Partnership | Roche Diagnostics anchors European market access through specialized channel relationships with decentralized testing infrastructure programs. |
| Reimbursement Strategy Recalibration | Payer coverage model evolution between supervised and self-administered encounters opens reimbursed distribution channels for home testing kits. |
Research Methodology
The analysis maps lateral flow, immunoassay, molecular, enzyme immunoassay, and agglutination test formats, each validated through procurement directors at hospital networks, regulatory affairs specialists at diagnostic manufacturers, and biomedical engineers at point-of-care centers. Primary interviews with GPO contracts managers and point-of-care nursing staff combined with secondary validation against FDA Emergency Use Authorization filings, EMA CE-IVD submission databases, CDSCO import licensing records, and hospital procurement contract disclosures. Bottom-up test format demand modeling and top-down health system expenditure analysis underwent triangulation for consistency.
Consistency checks validated volume and value outputs against external benchmarks including diagnostic manufacturer SEC filings, CMS Medicare reimbursement code evolution, and Indian government tender award databases. Segmentation dimensions span test type, end user, application, and deployment channel across the projection horizon. CAGRs derived from test volume trajectories and pricing trend analysis incorporate polymerase chain reaction miniaturization adoption curves and lateral flow sensitivity ceiling constraints as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained FDA Emergency Use Authorization pathway normalization, CDSCO localization mandate enforcement, and EMA IVDR compliance deadline adherence; material deviation in regulatory timeline execution or reimbursement recalibration velocity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Toxicology Testing Services Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
Apoptosis Testing Market
Testing Services
Global CA 125 Test Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Infusion Toxicology Services Market
Testing Services
Anti-Asthma TDM Assay Kits Market
Testing Services
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market
Testing Services
In-Vitro Toxicology Testing Market
Testing Services
Specific Protein Testing Market
Testing Services
Thrombophilia Testing Market
Testing Services
Home Care Testing Market
Testing Services
Global Diagnostic Testing Market
Testing Services
Ovulation Test Kit Market
Testing Services
US Cannabis Testing Market
Testing Services
Calprotectin Testing Market