
 Preclinical Medical Device Testing Services Market | 2026-2036
Preclinical Medical Device Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Preclinical Medical Device Testing Services Market Intelligence
ISO 10993 biocompatibility certification is reorganizing competitive access in preclinical device testing, as sponsors increasingly demand accredited laboratories with full GLP compliance. Charles River Laboratories leverages its integrated safety assessment platform to anchor large-scale implant studies across North America and Europe. Eurofins Scientific competes through decentralized laboratory networks that extend localized sterilization validation services to mid-tier device manufacturers. WUXI APPTEC dominates Asia-Pacific feasibility testing with captive access to rodent and non-rodent model supply chains.
Preclinical medical device testing services encompass biocompatibility evaluation, mechanical characterization, electrical safety verification, and sterilization validation performed under Good Laboratory Practice conditions prior to human clinical trials; these studies typically require histopathological analysis, cytotoxicity screening per ISO 10993-5, and fatigue testing to ASTM F2077 standards to establish device safety profiles for regulatory submission. Biocompatibility testing leads service type revenue due to mandatory ISO 10993 compliance for all implantable and surface-contacting devices, while sterilization validation is accelerating fastest as ethylene oxide alternatives drive requalification cycles. Implants command the largest device type margin pool because of extended study durations and repeated biocompatibility phases, whereas diagnostic devices represent a mature segment with standardized electrical safety protocols.
FDA enforcement of updated ISO 10993-1 biological evaluation frameworks compels device sponsors to justify every omitted test, directly expanding outsourced study volumes to accredited contract research organizations. The EU Medical Device Regulation's heightened clinical evidence requirements, administered by notified bodies under EMA-aligned standards, extend preclinical testing depth for manufacturers seeking CE marking access. Stakeholders must monitor how FDA and EMA convergence on biocompatibility data expectations reshapes laboratory capacity planning and cross-border study placement strategies.
Market Dynamics
ISO 10993-1 biological evaluation frameworks from FDA and EMA are compressing study timelines while expanding test scope, forcing device sponsors to outsource complex biocompatibility matrices to accredited contract research organizations with full histopathological capabilities.
Growth Catalysts
- EU Medical Device Regulation:Heightened clinical evidence requirements under EMA-aligned standards extend preclinical testing depth for manufacturers seeking CE marking access.
- Cardiovascular implant outsourcing:Device sponsors are transferring biocompatibility and sterilization validation studies to specialized contract research organizations to manage capacity constraints.
- Ethylene oxide alternatives:New sterilization chemistries drive requalification cycles that expand validation service volumes across implantable device categories.
Market Restraints
- Specialized talent scarcity:Histopathologists and GLP study directors command premium compensation, inflating fixed cost structures for mid-tier laboratories.
- Non-rodent model supply concentration:Porcine and canine sourcing clusters in specific agricultural regions create geographic vulnerability for large-animal implant studies.
- ISO 10993-18 material characterization:The extractables and leachables testing mandate adds 12-16 week analytical phases that compress sponsor timelines.
Strategic Opportunities
- Asia-Pacific feasibility testing:Early-stage device prototyping in Singapore and South Korea creates localized demand for rapid-turnaround biocompatibility screening.
- Digital pathology integration:AI-assisted histopathological analysis converges with cloud-based data management to accelerate regulatory submission packages.
- MDR notified body backlog:Extended CE marking queues in Europe push sponsors to front-load preclinical evidence, expanding outsourced study volumes.
Industry Challenges
- GLP certification maintenance:OECD-compliant facility audits require continuous capital reinvestment in environmental monitoring and documentation systems.
- Cross-study resource allocation:Extended implant study durations create scheduling conflicts when multiple sponsors demand simultaneous necropsy capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preclinical Medical Device Testing Services Market |
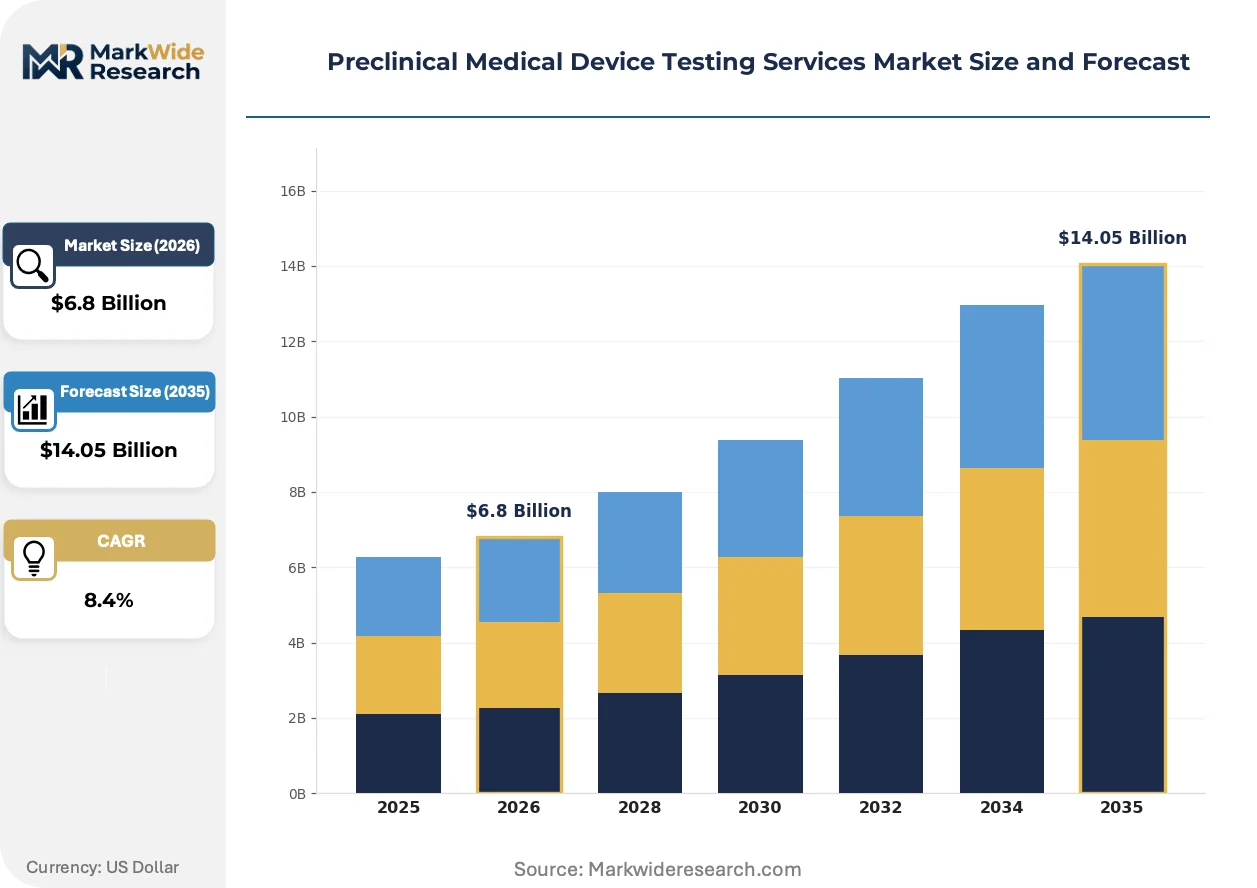
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Biocompatibility Testing, Sterilization Validation, Mechanical Testing, Electrical Safety Testing Device Type: Implants, Diagnostic Devices, Surgical Instruments, Therapeutic Devices Testing Phase: Feasibility Testing, Validation Studies, Preclinical Trials, Risk Assessment End User: Medical Device Manufacturers, Research Institutions, Regulatory Bodies, Biotechnology Firms |
| Companies Covered | Laboratory Corporation of America Holdings, Charles River Laboratories, WUXI APPTEC, Sotera Health, Eurofins Scientific, SGS SA, TÜV SÜD AG, Intertek Group Plc, NAMSA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preclinical Medical Device Testing Services Market Strategic Shifts & Innovations
In silico modeling and computational toxicology are compressing traditional animal study timelines, while sterilization validation protocols adapt to emerging chemical alternatives. These shifts are redistributing value across the preclinical testing value chain.
Computer-based biological evaluation using quantitative structure-activity relationship models is displacing certain in vivo sensitization and irritation studies for select polymer classes. Large orthopedic manufacturers have adopted these methods for material screening phases. The technology is displacing approximately one-third of preliminary rabbit skin irritation protocols in well-characterized polymer families.
FDA's updated ISO 10993-1 guidance requires sponsors to justify every omitted biocompatibility test with scientific rationale. Device companies now commission comprehensive endpoint evaluations rather than selective screening. Cardiovascular and neurological implant categories are most affected, with sponsors expanding study matrices to preempt agency queries.
Consolidated procurement of full-service testing portfolios is replacing discrete study-by-study contracting among mid-cap device manufacturers. Sponsors now prefer single-provider accountability across biocompatibility, sterilization validation, and packaging integrity. This pattern is most visible in the United States, where notified body consultants advise integrated preclinical strategies for simultaneous FDA and CE marking submissions.
Preclinical Medical Device Testing Services Market Segmentation
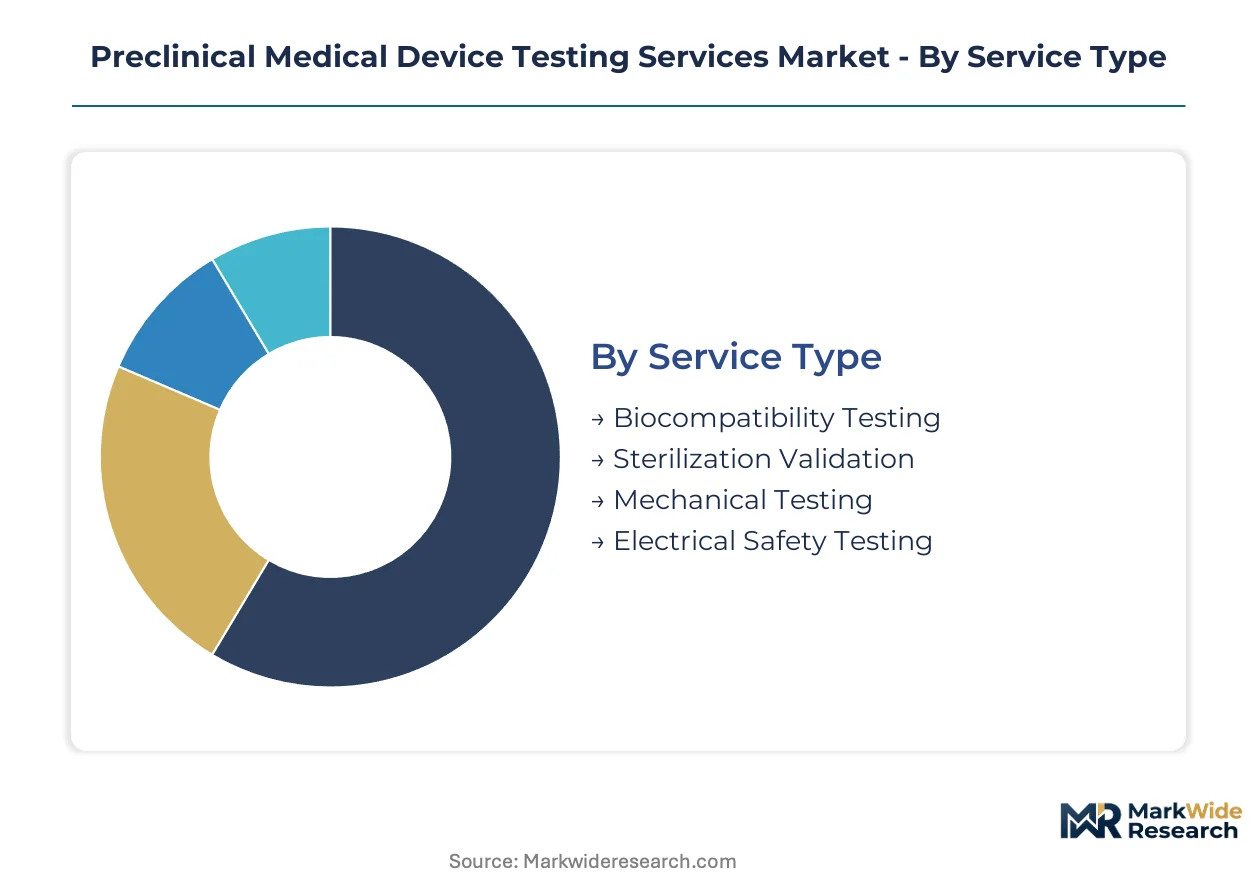
Preclinical medical device testing services fragment across multiple dimensions that determine study design complexity, regulatory pathway selection, and outsourcing economics. Each segmentation axis carries distinct capacity requirements, certification thresholds, and margin structures that shape competitive positioning among contract research organizations.
Service Type:
FDA's updated ISO 10993-1 guidance and EMA's MDR-aligned standards create divergent certification requirements across service categories, with GLP accreditation and histopathological capability serving as primary access filters.
- Biocompatibility Testing:Cytotoxicity screening per ISO 10993-5, sensitization studies, and systemic toxicity evaluations form the core technical stack. Demand concentrates among cardiovascular and neurological implant sponsors in the United States seeking to preempt FDA queries with comprehensive endpoint matrices. The category commands extended study durations and repeated testing phases that inflate revenue per engagement.
- Sterilization Validation:Ethylene oxide alternative qualification, radiation dose verification, and packaging integrity testing address evolving chemistry transitions. European manufacturers facing MDR notified body backlogs front-load validation evidence, accelerating service volumes faster than other categories.
- Mechanical Testing:Fatigue characterization to ASTM F2077 standards and tensile property verification support orthopedic and cardiovascular device submissions. Mid-tier laboratories compete on turnaround speed for standardized protocols.
- Electrical Safety Testing:IEC 60601 compliance verification and electromagnetic compatibility screening serve diagnostic and therapeutic device categories with mature, codified methodologies.
Biocompatibility testing handles the majority of throughput; sterilization validation is the fastest mover on share.
Device Type:
Study economics vary sharply by implantation depth, contact duration, and biological interaction complexity, with margins scaling directly to regulatory scrutiny intensity.
- Implants:Permanent and long-term indwelling devices trigger the full ISO 10993 endpoint battery including carcinogenicity and reproductive toxicity assessments. Sponsors in Germany and Switzerland commission extended large-animal studies that stretch 26-52 weeks. The segment absorbs disproportionate necropsy capacity and specialized histopathologist labor.
- Diagnostic Devices:Electrical safety and electromagnetic compatibility protocols dominate with standardized turnaround times. Japanese manufacturers leverage established JIS-aligned testing frameworks for rapid market access.
- Surgical Instruments:Limited biocompatibility requirements for transient contact devices compress study scope to cytotoxicity and irritation screening. South Korean production clusters generate concentrated regional demand.
- Therapeutic Devices:Drug-device combination products require integrated pharmaceutical and device testing expertise that fragments procurement across multiple vendor relationships.
Implants capture the deepest margin pool; surgical instruments exhibit the most commoditized pricing.
Testing Phase:
Phase-specific resource requirements create scheduling bottlenecks, with validation studies consuming dedicated GLP facility blocks that constrain simultaneous sponsor commitments.
- Feasibility Testing:Early-stage biocompatibility screening and prototype material characterization in Singapore and South Korea support rapid design iteration. WUXI APPTEC's captive rodent supply chains dominate Asia-Pacific throughput.
- Validation Studies:Formal GLP-compliant safety assessments for regulatory submission require OECD-audited facilities and continuous environmental monitoring documentation. Charles River Laboratories anchors North American capacity.
- Preclinical Trials:Large-animal implantation studies with extended follow-up periods concentrate in specific agricultural regions with porcine and canine sourcing advantages.
- Risk Assessment:ISO 14971-aligned biological evaluation planning and gap analysis services support sponsor regulatory strategy development.
Validation studies absorb the majority of fixed facility investment; feasibility testing is expanding most quickly.
End User:
Procurement sophistication varies by organizational scale, with integrated portfolio contracting replacing discrete study-by-study engagement among mid-cap manufacturers.
- Medical Device Manufacturers:Cardiovascular implant sponsors outsource comprehensive biocompatibility and sterilization matrices to manage in-house capacity constraints. United States innovators lead consolidated procurement adoption.
- Research Institutions:Academic medical centers commission mechanistic studies and publication-oriented histopathology with less stringent GLP requirements.
- Regulatory Bodies:Government laboratories and notified body consultants contract reference testing to validate sponsor-submitted data packages.
- Biotechnology Firms:Emerging cell therapy and tissue engineering companies require hybrid pharmaceutical-device testing expertise that crosses traditional service boundaries.
Medical device manufacturers drive the majority of contract value; biotechnology firms are climbing the fastest on engagement growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device sponsors concentrate procurement among laboratories proximate to FDA headquarters and notified body consultants, creating geographic clustering around regulatory decision centers rather than manufacturing footprints.
United States
Cardiovascular and neurological implant innovators in Massachusetts and Minnesota drive biocompatibility outsourcing volumes. FDA's updated ISO 10993-1 guidance compels sponsors to justify every omitted test, expanding study matrices. The Boston-Cambridge corridor anchors North American GLP capacity with dense histopathologist labor pools.
Germany
Orthopedic manufacturers in Baden-Württemberg and Bavaria commission extended large-animal implant studies stretching 26-52 weeks. EU Medical Device Regulation notified body backlogs push sponsors to front-load preclinical evidence. The Tübingen-Stuttgart cluster concentrates necropsy capacity for permanent device evaluations.
Switzerland
Medtech multinationals in Basel and Zurich outsource carcinogenicity and reproductive toxicity assessments for permanent implants. Swissmedic alignment with EMA standards requires comprehensive endpoint batteries. The Basel metropolitan area hosts specialized contract research organizations with OECD-audited facilities.
Singapore
Early-stage device prototyping from South Korean and Japanese manufacturers generates rapid-turnaround feasibility demand. The national pharmaceutical regulator maintains streamlined GLP recognition pathways. One-North and Tuas biomedical parks concentrate biocompatibility screening laboratories serving Asia-Pacific design iteration cycles.
China
Domestic implant manufacturers in Suzhou and Shenzhen expand validation study procurement as NMPA tightens biocompatibility documentation requirements. The national medical products administration converges toward ISO 10993 frameworks. The Suzhou Industrial Park anchors captive rodent and non-rodent model supply chains for feasibility testing.
Preclinical Medical Device Testing Services Market Key Industry Players
Player mix skews toward integrated safety assessment platforms with full GLP compliance and decentralized laboratory networks offering localized sterilization validation. The structure concentrates among North American and European anchors with Asia-Pacific feasibility specialists. Three archetypes dominate: integrated full-service platforms, regional sterilization validators, and Asia-Pacific feasibility specialists. Competitive moves center on portfolio diversification into adjacent pharmaceutical-device combination testing and strategic partnerships with notified body consultants.
Within the integrated platform tier, Charles River Laboratories and Laboratory Corporation of America Holdings exemplify North American anchors with histopathological capabilities spanning multiple therapeutic areas. Eurofins Scientific occupies a position among European decentralized networks extending localized services to mid-tier manufacturers. WUXI APPTEC represents the Asia-Pacific feasibility archetype with captive access to rodent and non-rodent model supply chains.
| Leading Market Players |
|---|
| Laboratory Corporation of America Holdings |
| Charles River Laboratories |
| WUXI APPTEC |
| Sotera Health |
| Eurofins Scientific |
| SGS SA |
| TÜV SÜD AG |
| Intertek Group Plc |
| NAMSA |
| Others |
Cost & Logistics Intelligence
Twelve-to-sixteen-week analytical phases for ISO 10993-18 material characterization compress sponsor timelines while concentrating pricing power among OECD-audited facilities with captive histopathologist labor pools. Device sponsors absorb premium rates for expedited GLP study blocks as necropsy capacity tightens across North America and Europe.
Pricing Analysis
Cost-plus contracts with labor-indexed adjustments dominate large-animal implant studies, with pricing stratifying across ISO 17025-accredited premium tiers, GLP-mid tiers, and non-accredited economy screening levels. Price differentiation hinges on histopathologist certification grade and study director experience depth. Cost compression in mid-tier biocompatibility screening intensifies as Charles River Laboratories and Eurofins Scientific expand automated platform capacity. Mid-cap cardiovascular device manufacturers exhibit highest price sensitivity, while neurological implant sponsors prioritize turnaround speed over unit economics.
Supply Chain Analysis
Porcine sourcing chokepoints in the agricultural Midwest and Danish Jutland Peninsula tether large-animal study scheduling to seasonal breeding cycles and veterinary export clearance timelines. Live model supply draws from United States, Denmark, and New Zealand breeding consortia, while histopathological reagents and specialized fixatives source from German chemical manufacturers and Japanese precision suppliers. Single-source vulnerability concentrates in non-rodent model procurement, where USDA and DAERA health certificate backlogs cascade into study delays. Distribution runs through sponsor-proximate GLP facilities rather than manufacturing footprints, with Boston-Cambridge and Tübingen-Stuttgart anchoring North American and European capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preclinical medical device testing sits in early-cycle expansion as FDA's updated ISO 10993-1 guidance forces sponsors to justify every omitted test, expanding outsourced study matrices beyond traditional selective screening approaches.
For Market Incumbents: Secure necropsy capacity commitments through long-term sponsor contracts before European MDR notified body backlogs peak. Incumbent laboratories must anchor histopathologist retention with specialized compensation tiers as Charles River Laboratories and WUXI APPTEC expand automated pathology platforms. Vertical integration into captive rodent breeding colonies defends margin position against supply volatility in porcine and canine sourcing clusters. For New Entrants and Emerging Players: Rapid-turnaround feasibility testing for South Korean and Japanese device prototyping clusters represents the most penetrable service-layer gap, with Singapore's One-North biomedical park offering regulatory-fast-track positioning. New entrants should target Asia-Pacific feasibility screening with 4-6 week cytotoxicity turnaround guarantees, leveraging cloud-based data management as a go-to-market differentiator against established GLP incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because biocompatibility data requirements will tighten further as FDA and EMA frameworks converge. Acquisition targets should display OECD-audited facilities with underutilized large-animal capacity and established notified body consultant relationships. The signal to watch is MDR notified body queue length, which front-loads preclinical evidence demand and expands outsourced study volumes disproportionately.| Strategic Initiative | Industry Significance |
|---|---|
| GLP Facility Accreditation Expansion | OECD-compliant environmental monitoring systems unlock FDA submission access for cardiovascular implant sponsors. |
| Digital Pathology Platform Integration | AI-assisted histopathological analysis accelerates ISO 10993-5 cytotoxicity screening turnaround for neurological device categories. |
| Notified Body Consultant Partnership | Strategic alliances with MDR-aligned advisors streamline simultaneous FDA and CE marking submission strategies. |
| Asia-Pacific Feasibility Laboratory Buildout | Singapore and South Korea facilities capture rapid prototyping demand from Japanese orthopedic manufacturers. |
| Captive Non-Rodent Model Supply Chain | In-house porcine breeding colonies insulate large-animal implant studies from USDA export certificate delays. |
Research Approach
A standing panel of GLP study directors, regulatory affairs managers at cardiovascular device sponsors, notified body technical reviewers, and hospital biomedical engineers provided ongoing calibration against secondary validation sources. Primary interviews combined with FDA 510(k) submission databases, EMA MDR technical documentation, OECD GLP compliance audit records, and ISO 10993-1 guidance revision trackers enabled bottom-up service-type segmentation and top-down market sizing triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical frameworks modeling service type, device category, testing phase, and end-user sophistication dimensions. CAGRs derived from sponsor procurement pattern analysis and laboratory capacity expansion announcements, incorporating ISO 10993-18 extractables testing mandate adoption curves and ethylene oxide alternative qualification cycle frequencies as industry-specific forecast inputs.
Underlying assumptions cover FDA enforcement continuity, EMA MDR notified body capacity expansion, and porcine model supply stability, with deviation risk concentrated in regulatory framework divergence and large-animal breeding colony disease outbreaks. Practitioners should keep alternative scenarios live as biocompatibility data convergence between FDA and EMA evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Friability Tester Market
Testing Services
IVD Quality Control Market
Testing Services
North America Newborn Screening Market
Testing Services
US Pharmaceutical Sterility Testing Market
Testing Services
Global GI Stool Testing Market
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
Global Homocysteine Testing Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Drug Testing Equipment Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
Global Bioburden Testing Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Pancreatic Stone Protein Testing Market
Testing Services
Aerospace and Life Sciences TIC Market
Testing Services
North America Endotoxin and Pyrogen Testing Market