
 Mycological Testing Market | 2026-2036
Mycological Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Mycological Testing Market Analysis
Germany's expansion of clinical microbiology reference centers is reconfiguring European supply dynamics for fungal diagnostics. Thermo Fisher Scientific leverages its pan-European distribution network to sustain kit availability across hospital chains. bioMérieux anchors its competitive position through specialized blood culture systems for invasive candidiasis detection. Merck KGaA differentiates via reagent portfolios calibrated to EUCAST antifungal susceptibility breakpoints.
Mycological testing encompasses laboratory methods for detecting, identifying, and characterizing fungi in clinical, environmental, and industrial specimens, employing culture-based isolation on Sabouraud dextrose agar, matrix-assisted laser desorption ionization-time of flight mass spectrometry for species identification, and quantitative PCR for fungal load quantification. Molecular Techniques command premium pricing due to same-day turnaround for critically ill patients, while Conventional Methods retain volume dominance in resource-constrained settings where capital equipment procurement remains restricted. Pharmaceutical Testing applications generate concentrated margin pools from sterile manufacturing compliance mandates, whereas Environmental Testing growth accelerates around cleanroom monitoring for cell therapy production facilities.
FDA antifungal susceptibility testing requirements under CLIA shape product validation pathways for US market entry, while EMA's MDR and EU GMP Annex 1 revisions tighten environmental monitoring specifications for aseptic processing. India's CDSCO and BIS frameworks increasingly reference ISO 18416 for cosmetic yeast and mold enumeration, expanding addressable demand for standardized culture media. Stakeholders must weigh regulatory divergence against platform consolidation strategies as regional pharmacopeias update fungal contamination limits without harmonized timelines.
Market Dynamics
Hospital laboratories are consolidating fungal diagnostic workflows around automated platforms that compress turnaround times from days to hours, forcing reagent suppliers to bundle consumables with service contracts rather than sell standalone kits.
Growth Catalysts
- FDA CLIA antifungal susceptibility mandates:Clinical laboratories must validate testing protocols against reference methods, expanding demand for standardized control panels and quality assurance materials.
- Cell therapy manufacturing:GMP-grade cleanrooms require continuous environmental monitoring for fungal contamination, creating dedicated revenue streams for rapid air and surface sampling systems.
- Next-generation sequencing:Metagenomic approaches detect polymicrobial infections missed by culture, with academic medical centers piloting whole-genome fungal identification workflows.
Market Restraints
- Capital equipment concentration:MALDI-TOF mass spectrometry platforms require six-figure investments that constrain adoption in community hospital networks and resource-limited settings.
- Reagent supply fragility:Sabouraud dextrose agar and selective fungal media depend on agricultural commodity inputs vulnerable to climate-induced price volatility.
- Technical substitution pressure:Syndromic molecular panels for respiratory pathogens increasingly include fungal targets, compressing standalone mycology test volumes.
Strategic Opportunities
- India diagnostic expansion:CDSCO reference laboratory accreditation programs and BIS standardization for medical device quality create entry pathways for automated culture systems.
- Companion diagnostic alignment:Antifungal therapeutic development pipelines require coordinated susceptibility testing platforms, opening co-development partnerships with pharmaceutical sponsors.
- Decentralized point-of-care deployment:Lateral flow immunoassays for cryptococcal antigen and Aspergillus galactomannan enable testing outside centralized laboratory infrastructure.
Industry Challenges
- Clinical microbiologist workforce contraction:Fellowship-trained mycology specialists are declining across US academic medical centers, complicating test interpretation and quality oversight.
- Multi-site validation complexity:Hospital networks implementing standardized fungal diagnostics across distributed laboratories face protocol harmonization delays and proficiency testing coordination costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mycological Testing Market |
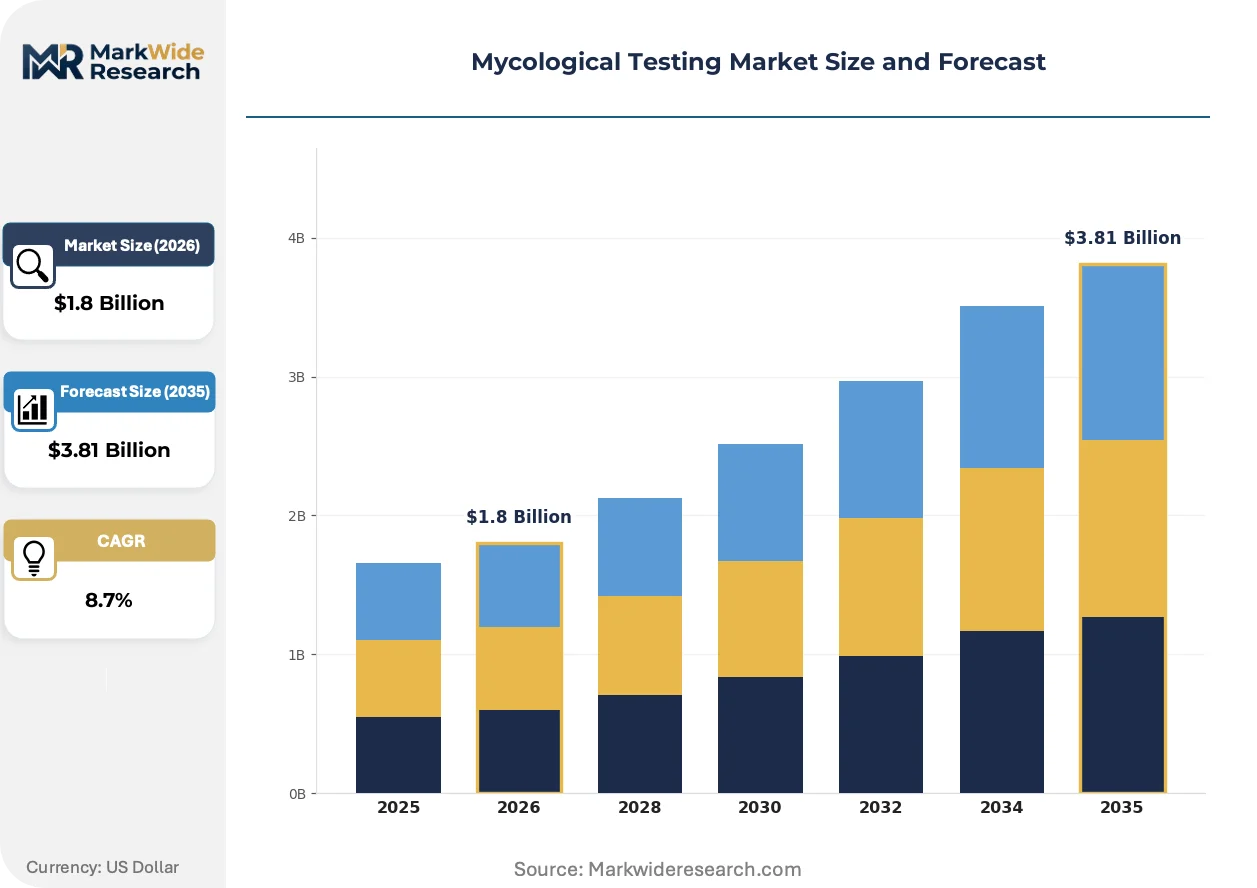
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Culture Media, Reagents, Kits, Instruments Application: Food Testing, Environmental Testing, Pharmaceutical Testing, Clinical Testing End User: Laboratories, Research Institutions, Hospitals, Food Industries Technology: Molecular Techniques, Microscopic Techniques, Immunological Techniques, Conventional Methods |
| Companies Covered | Thermo Fisher Scientific, bioMérieux, Merck KGaA, Becton, Dickinson and Company, Neogen Corporation, Lonza, F. Hoffmann-La Roche Ltd., Charles River Laboratories, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mycological Testing Market Emerging Trajectories
T3 magnetic resonance technology and artificial intelligence-assisted microscopy are compressing diagnostic timelines while regulatory frameworks force integration between environmental monitoring and clinical testing workflows.
T2 Biosystems' magnetic resonance platform detects Candida directly from whole blood without culture amplification, delivering species-level identification in three to five hours. Intensive care units and oncology wards are adopting this capability for neutropenic fever management. The technology is rendering obsolete the forty-eight to seventy-two hour turnaround of conventional blood culture followed by subculture and biochemical identification.
EMA's revised EU GMP Annex 1 mandates continuous viable particle monitoring for Grade A and B cleanrooms, requiring pharmaceutical manufacturers to upgrade from periodic settle plate sampling to active air sampling with real-time alert capabilities. Aseptic processing facilities are responding by integrating environmental monitoring data with manufacturing execution systems for batch release documentation.
Consolidated service contracts now bundle reagent supply, instrument maintenance, and remote technical support into per-test pricing models. Hospital procurement departments favor these arrangements over capital purchase decisions. Germany's university hospital networks have pioneered this transition, with reference laboratories negotiating multi-year partnerships that internalize calibration and competency verification costs.
Mycological Testing Market Segmentation
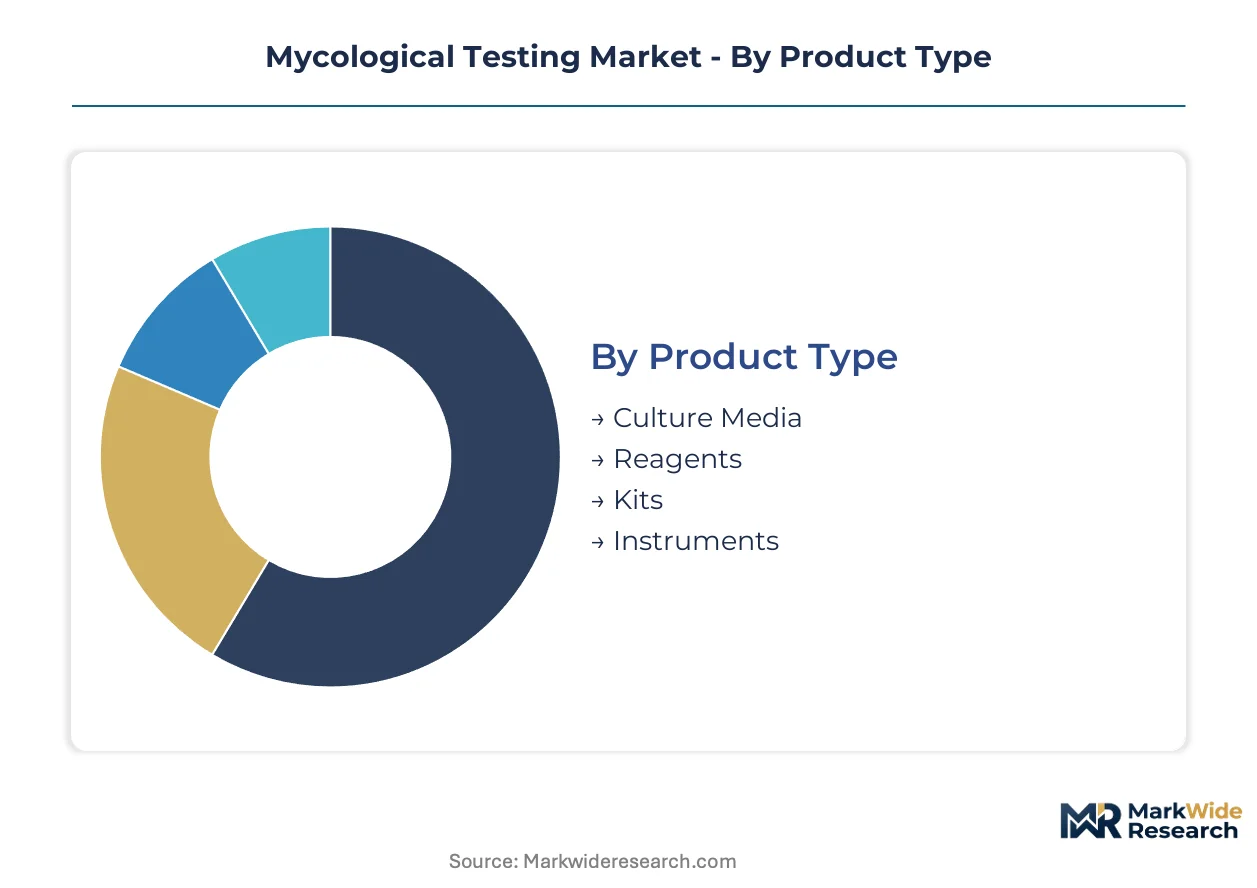
Mycological testing segments diverge sharply in service intensity and capital commitment. Product type determines reagent replenishment cycles, while technology choice locks customers into multi-year platform dependencies that reshape vendor revenue profiles.
Product Type:
After-sales-service intensity varies dramatically across consumable and instrument categories, with recurring revenue models dominating vendor strategies for high-attachment products.
- Culture Media:Sabouraud dextrose agar and selective fungal formulations require cold-chain logistics and lot-specific quality certificates. Hospital laboratories in Germany's university networks negotiate annual supply contracts bundling media with proficiency testing materials.
- Reagents:Antifungal susceptibility panels and staining solutions demand calibration verification and shelf-life monitoring. EUCAST breakpoint updates force reformulation cycles that pharmaceutical testing laboratories absorb through service agreements.
- Kits:Lateral flow immunoassays for cryptococcal antigen and Aspergillus galactomannan enable decentralized deployment with minimal technical support.
- Instruments:MALDI-TOF platforms and automated culture systems carry multi-year maintenance obligations and remote diagnostic connectivity.
By volume, Culture Media leads. By growth pace, Instruments are climbing the fastest.
Application:
Regulatory compliance costs concentrate margin pools in pharmaceutical and food safety verticals where contamination liability drives premium pricing.
- Pharmaceutical Testing:Sterile manufacturing mandates under FDA CLIA and EMA EU GMP Annex 1 require continuous environmental monitoring for fungal contamination. Cell therapy production facilities in Switzerland and Germany deploy active air sampling systems with real-time alert capabilities.
- Environmental Testing:Cleanroom monitoring for aseptic processing and cell therapy manufacturing generates dedicated revenue streams. Grade A and B classified zones require viable particle detection that compresses batch release timelines.
- Clinical Testing:Blood culture and tissue specimen analysis for invasive candidiasis and aspergillosis dominates hospital laboratory workflows.
- Food Testing:ISO 18416 yeast and mold enumeration standards expand demand for standardized culture media in quality control laboratories.
Pharmaceutical Testing commands the highest per-test margins. Environmental Testing is gaining share fastest.
End User:
Procurement sophistication separates centralized reference laboratories from distributed testing sites with limited capital budgets.
- Hospitals:Intensive care units and oncology wards adopt T2 magnetic resonance platforms for neutropenic fever management, compressing turnaround from days to hours. Service contracts bundle reagent supply with remote technical support.
- Laboratories:Clinical microbiology reference centers in Germany consolidate fungal diagnostic workflows around automated platforms requiring competency verification and calibration oversight.
- Research Institutions:Academic medical centers pilot metagenomic sequencing workflows for polymicrobial infection detection.
- Food Industries:Quality control laboratories reference BIS and CDSCO frameworks for standardized enumeration methods.
Hospitals generate the largest absolute demand. Research Institutions are expanding most quickly.
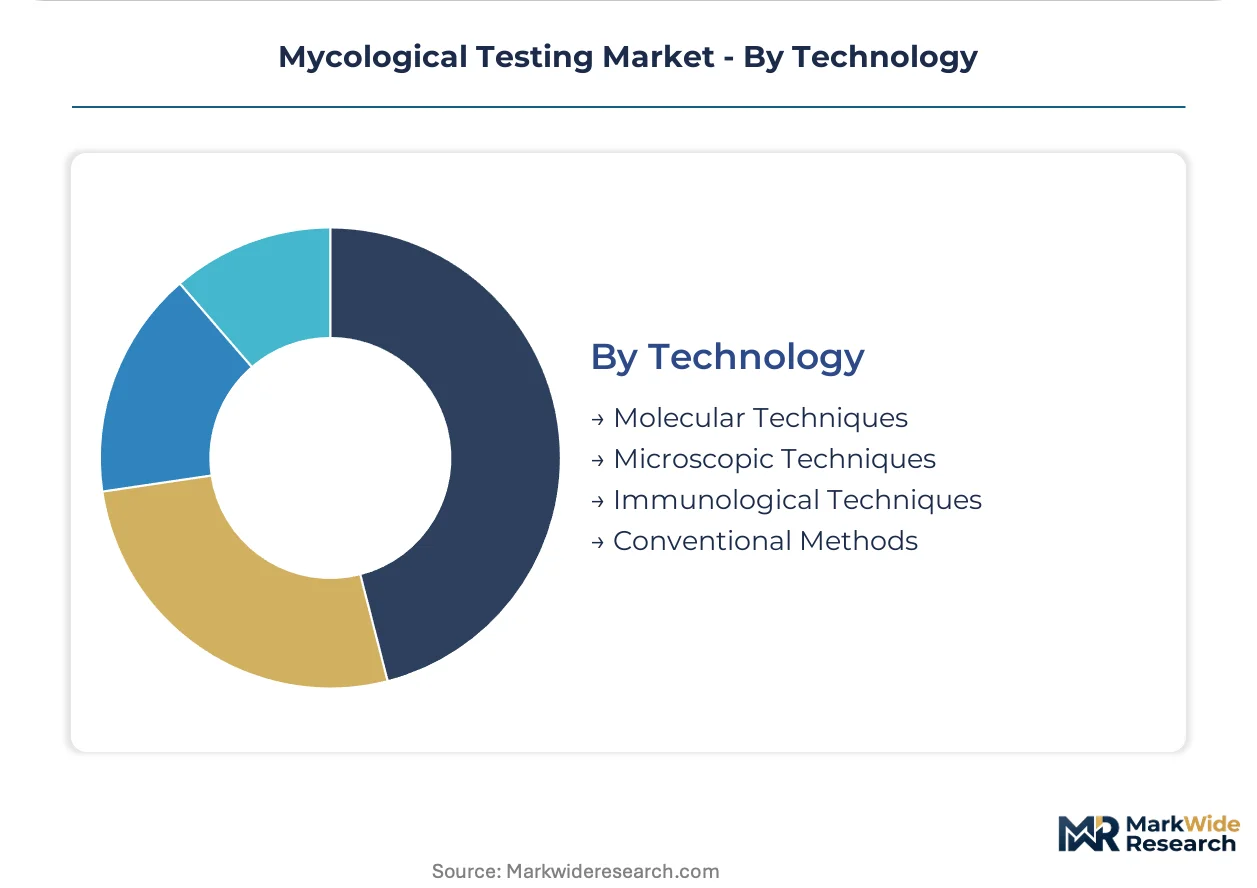
Technology:
Capital requirements and technical substitution pressure fragment adoption patterns between resource-constrained and premium-capacity settings.
- Molecular Techniques:Quantitative PCR and next-generation sequencing deliver same-day species identification for critically ill patients. Thermo Fisher Scientific and bioMérieux compete on panel breadth and turnaround time in US academic medical centers.
- Conventional Methods:Culture-based isolation on selective media retains volume dominance where MALDI-TOF procurement remains restricted. India's CDSCO reference laboratory programs sustain demand for standardized biochemical identification workflows.
- Microscopic Techniques:AI-assisted microscopy compresses diagnostic timelines for direct specimen examination.
- Immunological Techniques:Lateral flow and ELISA formats enable point-of-care deployment outside centralized infrastructure.
Conventional Methods retain volume leadership. Molecular Techniques show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA antifungal susceptibility mandates under CLIA anchor the United States as the dominant geography, with hospital laboratory consolidation and cell therapy manufacturing expansion driving platform adoption across North America, Europe, and Asia-Pacific.
United States
Intensive care units and oncology wards deploy T2 magnetic resonance platforms for neutropenic fever management, compressing diagnostic turnaround from days to hours. FDA CLIA requirements for antifungal susceptibility testing validation expand demand for standardized control panels and quality assurance materials. Boston's academic medical center corridor pilots metagenomic sequencing workflows for polymicrobial infection detection.
Germany
University hospital networks consolidate fungal diagnostic workflows around automated platforms requiring competency verification and calibration oversight. EMA EU GMP Annex 1 revisions mandate continuous viable particle monitoring for Grade A and B cleanrooms, tightening environmental monitoring specifications for aseptic processing. Baden-Württemberg's pharmaceutical manufacturing cluster integrates active air sampling systems with manufacturing execution systems for batch release documentation.
India
CDSCO reference laboratory accreditation programs and BIS standardization for medical device quality create entry pathways for automated culture systems. The country's national pharmaceutical regulator increasingly references ISO 18416 for cosmetic yeast and mold enumeration, expanding addressable demand for standardized culture media. Maharashtra's diagnostic manufacturing corridor sustains demand for conventional biochemical identification workflows where capital equipment procurement remains restricted.
Switzerland
Cell therapy production facilities deploy GMP-grade cleanrooms requiring continuous environmental monitoring for fungal contamination, creating dedicated revenue streams for rapid air and surface sampling systems. Swissmedic oversight of sterile manufacturing maintains stringent contamination liability standards that drive premium pricing for compliance solutions. Basel's biopharmaceutical manufacturing cluster upgrades from periodic settle plate sampling to active air sampling with real-time alert capabilities.
Japan
Academic medical centers pilot whole-genome fungal identification workflows using next-generation sequencing approaches that detect polymicrobial infections missed by culture. PMDA regulatory frameworks for in vitro diagnostics shape product validation pathways for market entry. Tokyo's metropolitan hospital network adopts syndromic molecular panels for respiratory pathogens that increasingly include fungal targets.
Mycological Testing Market Vendor Landscape
Pan-European life science conglomerates and specialized diagnostic platform developers split the market between bundled service contracts and standalone reagent supply. The vendor base concentrates around four strategic archetypes: diversified conglomerates with distribution networks, specialized microbiology platform developers, pharmaceutical-grade reagent manufacturers, and emerging point-of-care assay specialists. Dominant competitive moves include multi-year service partnership negotiations with hospital procurement departments and co-development alliances with antifungal therapeutic sponsors.
Among diversified life science conglomerates, Thermo Fisher Scientific and bioMérieux occupy positions exemplifying platform-bundling strategies, while Merck KGaA represents the pharmaceutical-grade reagent manufacturing archetype. Thermo Fisher Scientific leverages pan-European distribution infrastructure to sustain kit availability across hospital chains. bioMérieux anchors specialized positioning through blood culture system development. Merck KGaA differentiates via reagent portfolios calibrated to EUCAST antifungal susceptibility breakpoints.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| bioMérieux |
| Merck KGaA |
| Becton, Dickinson and Company |
| Neogen Corporation |
| Lonza |
| F. Hoffmann-La Roche Ltd. |
| Charles River Laboratories |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European reagent manufacturing is compressing margins for Sabouraud dextrose agar producers while simultaneously driving bundling strategies that shift revenue toward service contracts. German university hospital networks exploit this utilization slack to negotiate multi-year partnerships that internalize calibration costs and lock in per-test pricing.
Pricing Analysis
Geographic price spreads between North American and Indian diagnostic markets exceed threefold for equivalent MALDI-TOF platforms, reflecting differential regulatory validation burdens and after-sales service intensity. The dominant pricing model is contract-based long-term offtake with bundled reagent supply, where price differentiation rests on EUCAST breakpoint certification and remote technical support tiers. Pricing pressure stems from syndromic molecular panels compressing standalone mycology volumes, with community hospital networks exhibiting highest price sensitivity and pharmaceutical cleanroom operators showing least.
Supply Chain Analysis
Tariff exposure between United States and Chinese agricultural commodity inputs dominates supply chain risk planning for culture media manufacturers. Production concentrates in Germany, United States, and India, with Sabouraud dextrose agar drawing from climate-vulnerable wheat and corn feedstocks. Single-source vulnerability for selective fungal media additives compounds risk exposure. Distribution runs through pan-European life science logistics networks and regional cold-chain specialists serving hospital procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
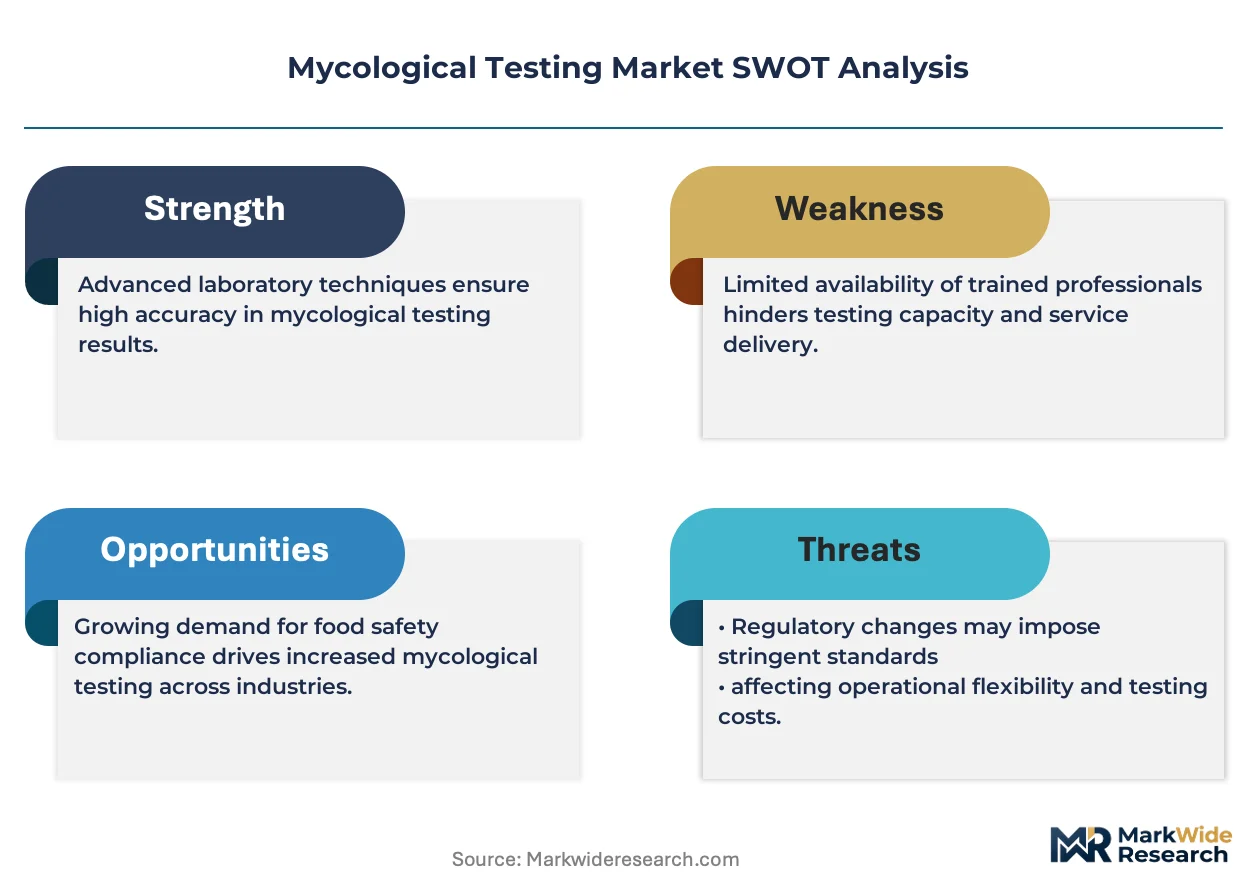
Trained mycology specialists are declining across US academic medical centers, creating a capability gap that threatens quality oversight and test interpretation accuracy. This scarcity reconfigures competitive advantage toward vendors who can automate competency verification and remote calibration support.
For Market Incumbents: Build switching-cost moats through multi-year service contracts that embed competency verification and EUCAST breakpoint update cycles. Deepen backward integration into agricultural commodity inputs for Sabouraud dextrose agar to buffer climate-induced price volatility. Defend against syndromic molecular panel substitution by expanding blood culture system integration with hospital laboratory information systems. For New Entrants and Emerging Players: India's diagnostic manufacturing corridor offers the most penetrable geographic entry point, where CDSCO reference laboratory programs sustain demand for conventional biochemical identification workflows. Target lateral flow immunoassay deployment for cryptococcal antigen and Aspergillus galactomannan in decentralized settings outside centralized laboratory infrastructure. Pursue co-development partnerships with antifungal therapeutic sponsors requiring coordinated susceptibility testing platforms. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated platform developers with bundled reagent supply contracts and remote diagnostic connectivity. Long-term viability favors vendors with exposure to pharmaceutical environmental monitoring mandates rather than clinical testing volumes alone. The acquisition target archetype is specialized microbiology platform developers with EMA-validated cleanroom monitoring systems. Watch FDA antifungal susceptibility testing guidance updates as inflection indicators for control panel demand.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contract Bundling | Hospital procurement departments favor per-test pricing that internalizes calibration and competency verification costs. |
| EUCAST Breakpoint Calibration Investment | Reagent portfolios aligned to antifungal susceptibility standards command premium positioning in European reference laboratories. |
| Point-of-Care Assay Development | Lateral flow formats for cryptococcal antigen enable testing outside centralized infrastructure in resource-limited settings. |
| Environmental Monitoring Integration | Active air sampling systems with real-time alerts satisfy EMA EU GMP Annex 1 mandates for Grade A and B cleanrooms. |
| Companion Diagnostic Alignment | Co-development partnerships with antifungal therapeutic sponsors open dedicated revenue streams from clinical trial testing. |
Methodological Framework
Desk research of FDA guidance documents, EMA regulatory filings, and ISO standardization frameworks preceded structured interviews with clinical microbiology laboratory directors, hospital procurement managers, pharmaceutical quality assurance leads, and diagnostic platform engineers. Primary fieldwork combined with secondary validation against GPO contract databases, CDSCO accreditation records, and BIS standardization circulars. Bottom-up testing volume estimates triangulated against top-down market sizing from instrument installation bases and reagent replenishment cycles.
Assumptions held fixed include regulatory timelines for EUCAST breakpoint updates and FDA CLIA validation requirements, while variables included hospital laboratory consolidation pace and cell therapy manufacturing expansion rates. The analytical framework modeled segmentation across product type, application, end user, and technology dimensions, with additional stratification by regional regulatory cluster and capital equipment procurement capacity. CAGRs derived from instrument placement trajectories and reagent consumption intensity across the projection horizon, incorporating antifungal resistance surveillance data and pharmaceutical manufacturing capacity buildouts as industry-specific inputs.
Practitioners should monitor FDA antifungal susceptibility testing guidance revisions, EMA EU GMP Annex 1 enforcement patterns, and climate-induced agricultural commodity price volatility for early signals of forecast deviation. Forecasts reflect documented assumptions about regulatory harmonization timelines and hospital capital expenditure cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
Urine Testing Cups Market
Testing Services
Industrial Radiography Testing Market
Testing Services
Cholesterol Test Market
Testing Services
Friability Tester Market
Testing Services
Redox Meter Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Radiographic Testing Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Global Terminal Sterilization Services Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Global Extractables and Leachables Testing Services Market
Testing Services
Fecal Calprotectin Test Market
Testing Services
Passive Dosimetry Equipment and Service Market
Testing Services
Germany Testing, Inspection and Certification Market
Testing Services
Endocrine Peptides Test Market