

Employer and Workplace Drug Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Employer and Workplace Drug Testing Market Insights
Buyer concentration among large corporate employers is pivoting as mid-sized construction firms and regional logistics operators adopt standardized testing programs. Quest Diagnostics leverages its national laboratory footprint to anchor institutional contracts across transportation and manufacturing verticals. Laboratory Corporation of America Holdings sustains volume leadership through integrated occupational health networks. Abbott specializes in rapid diagnostic platforms that compete for on-site workplace deployment.
Employer and workplace drug testing encompasses specimen collection, laboratory analysis, and result reporting protocols designed to detect psychoactive substances in biological matrices, typically operating with chain-of-custody documentation and cutoff thresholds measured in nanograms per milliliter. Urine testing occupies the largest share of volume due to established legal precedent and SAMHSA certification requirements, while saliva-based immunoassay methods represent the fastest-expanding segment as point-of-collection screening reduces turnaround time and logistical burden for corporate employers.
The Department of Transportation's 49 CFR Part 40 framework mandates standardized testing procedures for safety-sensitive positions, while FDA oversight of diagnostic platform accuracy shapes product development pathways for device manufacturers. State cannabis legalization creates regulatory fragmentation that forces employers to reconcile federal compliance obligations with evolving employee protections. Stakeholders must monitor how oral fluid testing standards advance through SAMHSA rulemaking and whether laboratory information management systems can integrate real-time compliance updates across multi-state operations.
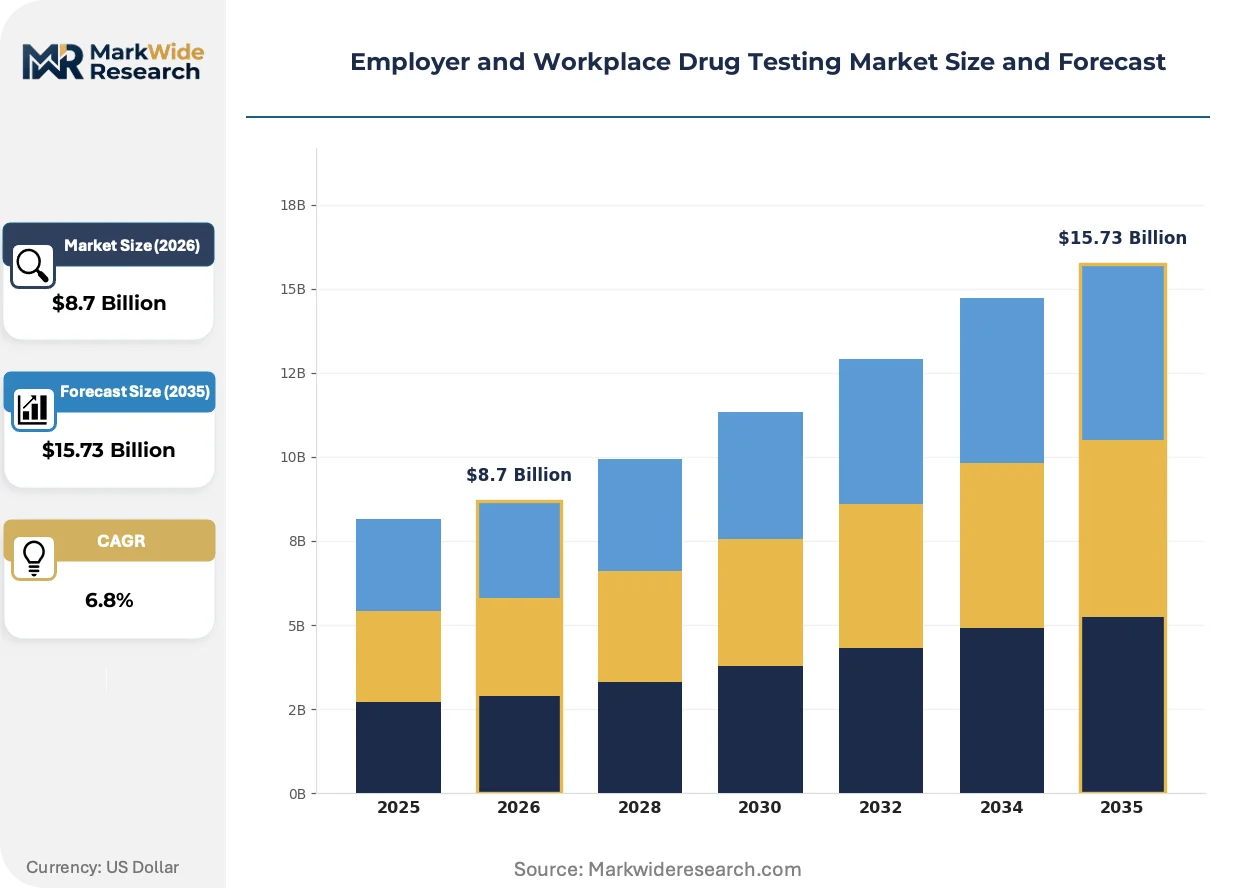
Market Dynamics
The collision between federal 49 CFR Part 40 mandates and proliferating state cannabis protections is fragmenting employer compliance architectures. Corporate legal departments now maintain parallel testing protocols—one for Department of Transportation-covered safety-sensitive roles, another for state-law-aligned general workforce screening.
Growth Catalysts
- Oral fluid immunoassay platforms:Point-of-collection screening eliminates laboratory logistics chains. Construction and logistics operators deploy these devices for same-shift hiring decisions.
- Department of Transportation rulemaking:Proposed amendments to 49 CFR Part 40 would authorize oral fluid as an alternative matrix. This regulatory pathway accelerates device validation investments.
- Mid-sized employer standardization:Regional trucking fleets and manufacturing plants adopt institutional testing programs previously exclusive to Fortune 500 employers. This demand tier expands addressable volume.
Market Restraints
- Laboratory capacity concentration:SAMHSA-certified laboratories cluster in Texas, California, and Illinois. Geographic concentration creates specimen transport bottlenecks for rural employers.
- Cutoff threshold heterogeneity:State cannabis metabolite limits vary from 1 to 50 nanograms per milliliter. This technical fragmentation forces multi-state employers to maintain jurisdiction-specific protocols.
- Chain-of-custody documentation burden:Federal mandates require tamper-evident seals, temperature logs, and courier tracking. These procedural requirements inflate per-test administrative costs.
Strategic Opportunities
- Remote workforce screening networks:Mobile collection services using telehealth supervision address distributed employee bases. Technology and professional services firms with hybrid work models represent underserved demand.
- Real-time compliance software integration:Laboratory information management systems that auto-update state law changes reduce legal exposure. Multi-state operators pay premium pricing for automated regulatory monitoring.
- Hair testing for extended detection windows:This matrix captures substance use patterns across 90-day windows versus urine's 2-4 days. Energy sector employers with rotational offshore schedules value this forensic depth.
Industry Challenges
- Medical Review Officer certification scarcity:Federal regulations require licensed physicians with specialized training to verify positive results. Training program throughput constrains scaling of testing programs.
- Legacy human resource information system integration:Many employers operate on-premise payroll and personnel platforms lacking API connectivity to modern testing result portals. Custom integration projects delay program launches.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Employer and Workplace Drug Testing Market Trends and Innovations
Workplace drug testing is bifurcating into rapid on-site screening and forensic-grade laboratory confirmation. This structural split is compressing the traditional single-vendor model and creating distinct competitive arenas for device manufacturers versus analytical service providers.
Saliva-based biosensor arrays with integrated digital readouts are electrifying point-of-collection workflows. Regional distribution centers and construction site offices deploy these platforms for immediate hiring clearance. The technology is compressing time-to-placement from 48 hours to under 30 minutes for non-DOT positions.
SAMHSA's proposed oral fluid testing guidelines are reshaping validation requirements for device manufacturers. Laboratories must recalibrate mass spectrometry protocols to accommodate alternative matrices. Device makers with pre-submitted FDA 510(k) pathways capture early-mover positioning as the rulemaking advances.
Subscription-based testing program management is displacing per-test purchasing among mid-sized employers. Third-party administrators bundle collection site networks, medical review, and result reporting into flat monthly fees. This model concentrates most visibly in Texas and Florida, where construction and logistics employer density supports route-optimized mobile collection services.
Employer and Workplace Drug Testing Market Segmentation
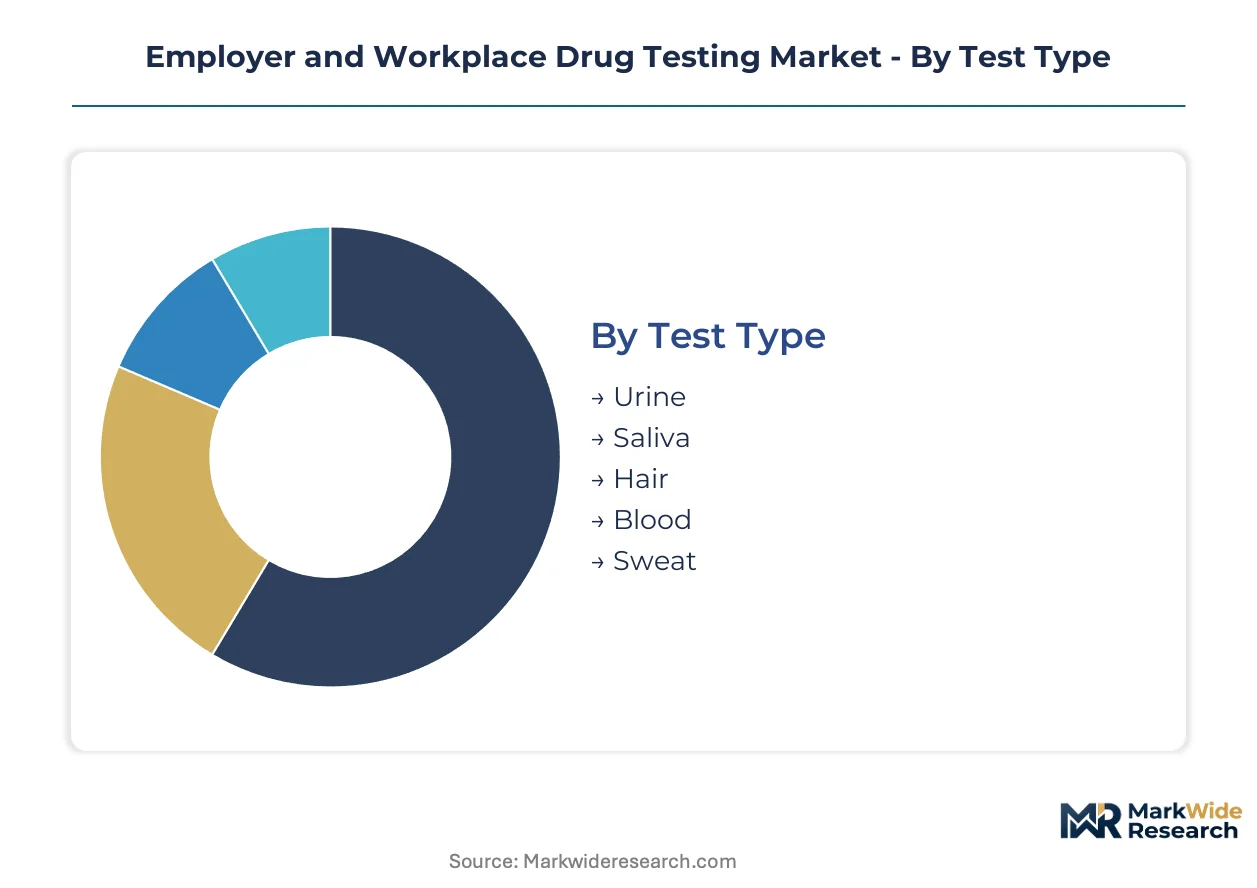
Drug testing segmentation reflects divergent technical requirements between regulatory compliance and operational convenience. Matrix selection, substance panels, and analytical methods each create distinct procurement tiers with varying cost structures and turnaround constraints.
Test Type:
Urine dominates transaction volume while oral fluid commands premium pricing for speed.
- Urine:This matrix delivers metabolite stability across extended collection windows and anchors SAMHSA-certified laboratory workflows. Demand concentrates among Department of Transportation-regulated fleets in Texas and California where legal precedent supports defensible termination decisions.
- Saliva:Point-of-collection immunoassay platforms eliminate courier logistics and enable same-shift hiring clearance. Construction site supervisors and regional distribution centers in Florida and Georgia deploy these devices for immediate workforce placement decisions.
- Hair:Ninety-day detection windows serve energy sector employers with rotational offshore schedules requiring pattern-of-use documentation.
- Blood:Forensic precision for post-incident investigations drives adoption among manufacturing entities with zero-tolerance safety protocols.
- Sweat:Patch-based continuous monitoring addresses rehabilitation program compliance in government agency contracts.
Today's leader: Urine. Tomorrow's challenger: Saliva.
Substance Tested:
Panel composition tracks regulatory mandates against evolving state decriminalization patterns.
- Marijuana:Tetrahydrocannabinol metabolite detection generates the highest test volume across all matrices. Multi-state employers in Illinois and New York maintain parallel cutoff thresholds to reconcile federal DOT mandates with state employee protection statutes.
- Cocaine:Benzoylecgonine screening persists in transportation and logistics sectors where federal mandates override local decriminalization trends.
- Amphetamines:Methamphetamine and prescription stimulant differentiation requires mass spectrometry confirmation in safety-sensitive manufacturing roles.
- Opiates:Expanded semi-synthetic opioid panels address fentanyl analog detection in construction and energy sector protocols.
- Benzodiazepines:Sedative-hypnotic screening concentrates in healthcare employer and government agency pre-placement panels.
- PCP:Phencyclidine retains mandatory status in federal transportation regulations despite declining street prevalence.
Panel standardization favors: Cocaine and amphetamines. Panel expansion targets: Marijuana metabolite thresholds and synthetic opioid analogs.
Testing Method:
Analytical sophistication separates rapid screening from forensic-grade confirmation workflows.
- Immunoassay:Antibody-based competitive binding assays deliver qualitative results at point-of-collection sites. Corporate employers with high-volume hiring in Arizona and Ohio deploy lateral flow devices for preliminary negative clearance.
- Mass Spectrometry:Liquid chromatography-tandem mass spectrometry provides quantitative confirmation with nanogram-per-milliliter precision. SAMHSA-certified laboratories in Texas and Illinois anchor this tier for contested positive results.
- Gas Chromatography:Volatile compound separation supports specialized solvent and inhalant detection in industrial hygiene applications.
- Enzyme Multiplied Immunoassay Technique:EMIT platforms serve high-throughput clinical laboratory environments with automated batch processing capabilities.
- Thin Layer Chromatography:Cost-effective presumptive screening persists in resource-constrained government agency and smaller corporate employer settings.
Screening dominance: Immunoassay. Confirmation gold standard: Mass spectrometry.
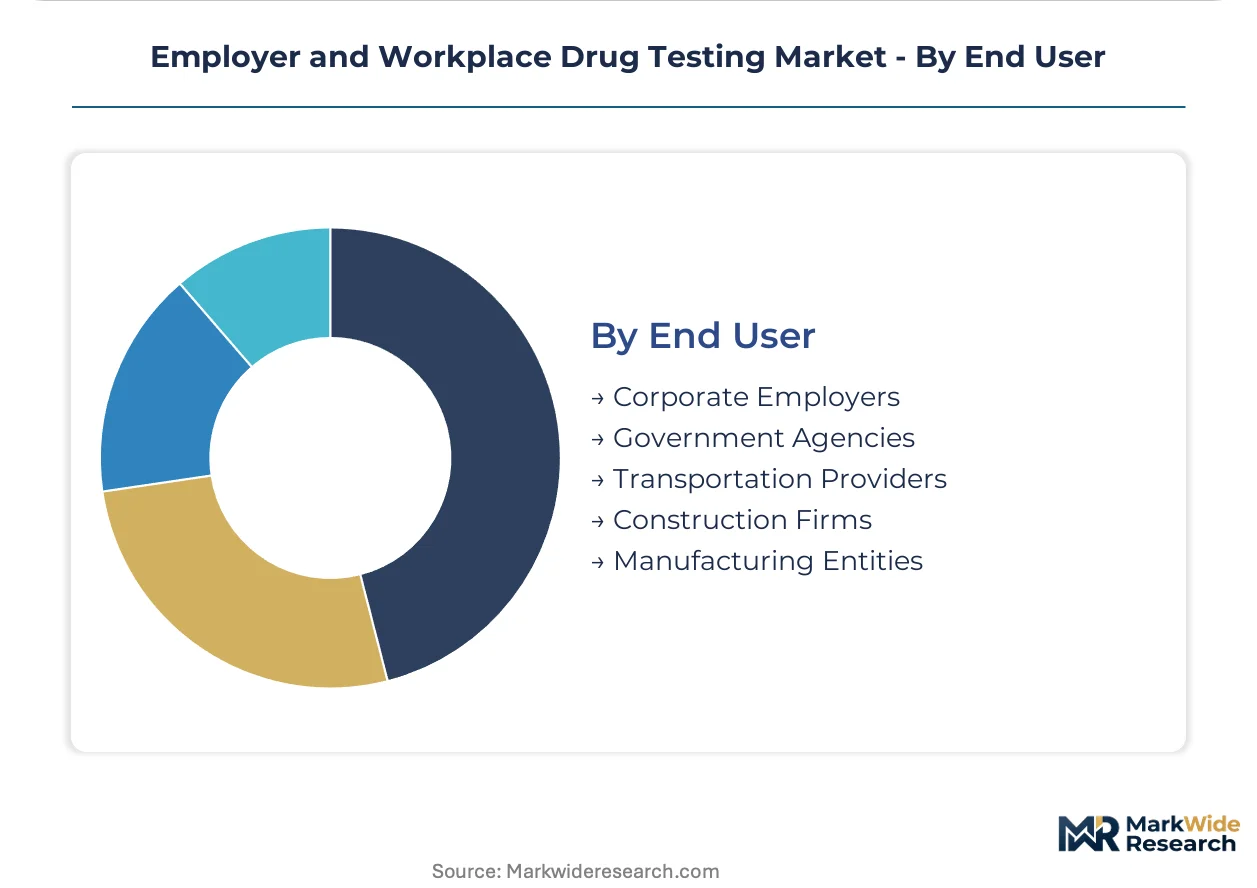
End User:
Procurement sophistication varies sharply between institutional scale and mid-market standardization.
- Corporate Employers:Fortune 500 human resource departments integrate testing workflows with applicant tracking systems and maintain dedicated medical review officer relationships. Technology and professional services firms in Washington and Massachusetts increasingly demand remote workforce screening networks.
- Government Agencies:Federal, state, and municipal procurement operates through competitive bidding with strict chain-of-custody documentation requirements. Correctional and probation programs in Pennsylvania and Ohio sustain volume through monitoring contract renewals.
- Transportation Providers:Trucking fleets, railroad operators, and aviation maintenance contractors operate under immutable 49 CFR Part 40 mandates regardless of state cannabis legislation.
- Construction Firms:Mid-sized regional operators in Texas and Florida adopt subscription-based testing program management to reduce per-test administrative burden.
- Manufacturing Entities:Automotive and chemical plants balance zero-tolerance safety protocols with collective bargaining agreement constraints in Michigan and Indiana.
Institutional anchor: Transportation providers. Expansion frontier: Construction firm standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas anchors workforce concentration in energy and logistics, while California's technology corridor and Illinois manufacturing belt sustain institutional testing demand across distinct regulatory environments.
United States
Department of Transportation mandates drive volume across Texas trucking corridors and California port logistics. OSHA workplace safety guidelines intersect with state cannabis protections in Illinois and New York, forcing parallel compliance protocols. SAMHSA-certified laboratories cluster in Houston, Dallas-Fort Worth, and Chicago metropolitan zones.
Germany
Industrial manufacturing in Bavaria and Baden-Württemberg sustains pre-employment screening demand among automotive and chemical employers. The country's national pharmaceutical regulator oversees diagnostic platform accuracy requirements. Frankfurt and Stuttgart host occupational health service networks integrating testing workflows.
United Kingdom
Financial services and professional services firms in London and Southeast England adopt remote workforce screening for distributed talent. GDPR data protection frameworks shape chain-of-custody documentation standards. Manchester and Birmingham logistics hubs deploy rapid on-site testing for same-day hiring clearance.
Canada
Energy sector employers in Alberta and Saskatchewan utilize hair testing for rotational offshore workforce monitoring. Health Canada regulates diagnostic device performance standards. Toronto and Vancouver technology firms drive demand for telehealth-supervised remote collection services.
Australia
Mining operations in Western Australia and Queensland sustain high-volume testing programs for fly-in-fly-out workforce models. The Therapeutic Goods Administration oversees point-of-collection device registration. Sydney and Melbourne corporate headquarters integrate testing with occupational health management systems.
Employer and Workplace Drug Testing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across laboratory services, diagnostic devices, and third-party administration. National laboratory networks anchor institutional contracts through integrated occupational health platforms. Rapid diagnostic manufacturers capture on-site deployment opportunities. Device makers and service providers pursue FDA 510(k) pre-submission pathways. Subscription-based program management displaces per-test purchasing among mid-market employers.
Within the national laboratory services tier, Quest Diagnostics and Laboratory Corporation of America Holdings occupy positions defined by geographic footprint breadth and institutional contract depth. Abbott exemplifies the rapid diagnostic platform archetype competing for point-of-collection workplace deployment. These three entities represent distinct strategic postures: integrated service networks versus specialized device manufacturing.
| Leading Market Players |
|---|
| First Advantage |
| Laboratory Corporation of America Holdings |
| Quest Diagnostics |
| Abbott |
| Drägerwerk AG & Co. KGaA |
| Bio-Rad Laboratories |
| Clinical Reference Laboratory |
| DISA Global Solutions |
| OraSure Technologies |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between SAMHSA-certified laboratory services and rapid point-of-collection devices manifests in divergent pricing architectures and supply chain configurations. Premium-tier laboratory confirmation commands sustained margins through regulatory compliance bundling, while commoditized immunoassay platforms compete on per-unit cost and distribution velocity across fragmented employer procurement channels.
Pricing Analysis
Capacity additions in Texas and California are reshaping price floors for urine-based laboratory confirmation services. Subscription-based program management displaces per-test transactional purchasing among mid-sized construction and logistics employers. Price differentiation hinges on turnaround speed and Medical Review Officer certification tier, with rural employers exhibiting highest sensitivity due to specimen transport cost burdens. Cost compression in rapid oral fluid devices intensifies as FDA 510(k) pathway competition proliferates.
Supply Chain Analysis
Freight logistics for biological specimens concentrate cost pressure on rural employers distant from SAMHSA-certified laboratory clusters. Manufacturing of collection devices draws from China and Mexico for plastic consumables, while diagnostic reagent production rests on supply from Germany and the United States. Single-source vulnerability in specialized immunoassay antibody supply creates exposure for rapid test manufacturers. Distribution runs through third-party administrator networks that bundle collection site access with result reporting portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between state cannabis regulatory regimes and federal DOT mandates creates compliance cost differentials that reward multi-state operational flexibility. Employers in Illinois and New York face elevated legal exposure compared to Texas and Florida, where regulatory alignment reduces parallel protocol maintenance burdens.
For Market Incumbents: Hedge against oral fluid testing commoditization by deepening vertical integration into telehealth-supervised remote collection services. National laboratory networks should anchor institutional contracts through integrated occupational health platforms that bundle Medical Review Officer services with automated compliance software. Defend margin position by capturing early-mover FDA 510(k) approvals as SAMHSA rulemaking advances.
For New Entrants and Emerging Players: Digital-channel direct-to-employer subscription models offer the most penetrable route for mid-market construction and logistics operators underserved by legacy laboratory networks. Target hybrid-work technology firms in Washington and Massachusetts with remote workforce screening networks that eliminate physical collection site dependency. White-space opportunity concentrates in real-time compliance software that auto-updates state law changes across multi-state employer operations.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized third-party administrators possessing route-optimized mobile collection capabilities in high-employer-density Sun Belt markets. Long-term viability hinges on regulatory fragmentation persistence that sustains demand for compliance automation. Acquisition target archetype: regional occupational health networks with integrated SAMHSA certification and established transportation sector relationships. Watch for SAMHSA oral fluid final rule publication as inflection indicator for device manufacturer valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth-Supervised Remote Collection Launch | Captures hybrid-work employer demand in technology corridors while reducing physical infrastructure requirements. |
| SAMHSA Oral Fluid Certification Investment | Positions device manufacturers for regulatory inflection as 49 CFR Part 40 amendments authorize alternative matrices. |
| Real-Time Compliance Software Integration | Reduces legal exposure for multi-state operators through automated state law monitoring embedded in laboratory information systems. |
| Subscription-Based Program Management Rollout | Consolidates fragmented mid-market demand in Texas and Florida construction sectors through flat-fee bundling. |
| Medical Review Officer Training Pipeline Expansion | Addresses certification scarcity constraining testing program scaling for safety-sensitive employer verticals. |
Research Methodology
Coverage spans the United States, Germany, United Kingdom, Canada, and Australia, with primary inputs from each market cluster. The analysis combines structured interviews with human resource compliance directors, occupational health service managers, diagnostic device regulatory affairs leads, third-party administrator operations executives, and SAMHSA-certified laboratory directors with secondary validation from FDA 510(k) filings, Department of Transportation rulemaking dockets, state legislative tracking databases, and SEC disclosures from publicly traded laboratory services firms. Bottom-up employer procurement pattern analysis triangulates against top-down market sizing across testing volume and service revenue dimensions.
Segmentation-level modeling disaggregates the projection horizon by test type, substance panel composition, analytical method sophistication, and end-user procurement tier. CAGRs derive from employer adoption curve analysis for oral fluid platforms, regulatory compliance cost modeling for multi-state operators, and laboratory capacity expansion tracking in certified hub geographies. Industry-specific forecast inputs include Medical Review Officer certification pipeline throughput and state cannabis legislation velocity indices.
Regulatory rulemaking delays, laboratory certification backlog accumulation, and state-level employee protection statute expansion are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding SAMHSA oral fluid guideline finalization timing and employer litigation exposure tolerance. Stakeholders should weight assumptions against their own operating context and compliance cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.