
 Global Endotoxin and Pyrogen Testing Market | 2026-2036
Global Endotoxin and Pyrogen Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endotoxin and Pyrogen Testing Market Foresight
The gap between premium recombinant Factor C assays and conventional Limulus amebocyte lysate commodities is repositioning procurement strategies across quality control departments. Eurofins Scientific SE leverages its geographic laboratory network to sustain high-throughput testing capacity for biologics manufacturers. Lonza Group Ltd. anchors its position through captive supply of endotoxin detection reagents and associated instrumentation. Charles River Laboratories International, Inc. differentiates via specialized pathogen-free product lines that integrate with downstream pyrogen testing workflows.
Endotoxin and pyrogen testing encompasses analytical methods that detect lipopolysaccharide fragments and fever-inducing substances in parenteral pharmaceuticals, medical devices, and water systems, with Limulus-based assays detecting thresholds down to 0.03 endotoxin units per milliliter. These procedures prevent septic shock responses in patients receiving injectable drugs or implantable devices. Kinetic turbidimetric methods lead the product type landscape due to throughput advantages in high-volume quality control laboratories, while recombinant Factor C assays represent the fastest-expanding segment as pharmaceutical buyers seek alternatives to horseshoe crab-derived reagents. Among applications, biopharmaceuticals command concentrated margin pools because monoclonal antibody and cell therapy processes require extensive in-process and release testing.
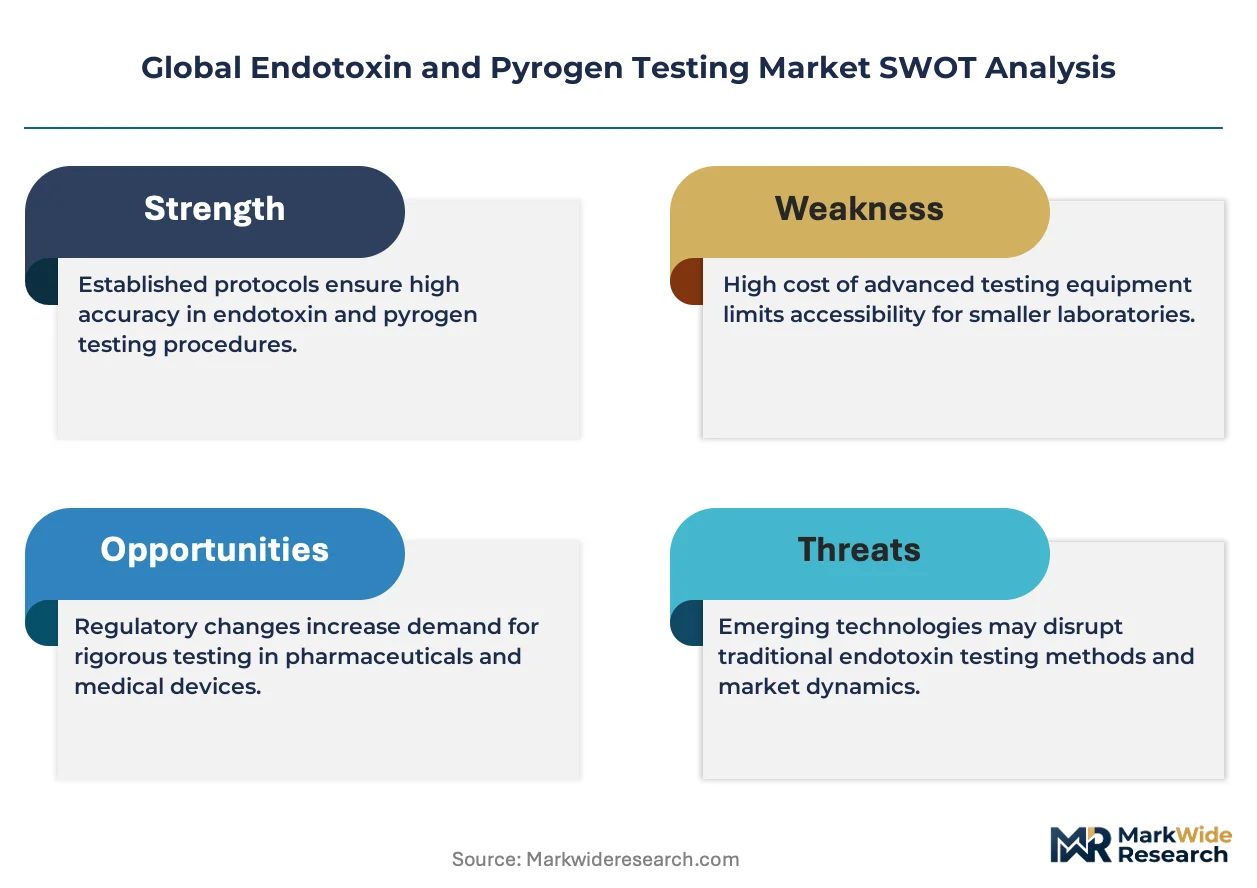
FDA enforces endotoxin limits through the Bacterial Endotoxins Test in United States Pharmacopeia Chapter 85, while EMA aligns parallel requirements via the European Pharmacopoeia 2.6.14, and China's NMPA implements GB standards for biological product purity. These frameworks mandate validated test methods for every injectable drug lot, creating structural demand for compliant assay platforms and certified reference standards. Stakeholders must monitor regulatory acceptance of recombinant alternatives as conservation restrictions on horseshoe crab harvesting tighten across multiple jurisdictions.
Market Dynamics
Conservation-driven substitution of horseshoe crab-derived reagents is restructuring supply relationships between reagent manufacturers and biopharmaceutical quality control departments. FDA draft guidance on recombinant Factor C acceptance has accelerated validation timelines for synthetic alternatives.
Growth Catalysts
- EMA Pharmacopoeia 2.6.14 enforcement:Lot-release mandates for every parenteral drug batch in Europe sustain structural demand for validated endotoxin detection platforms.
- Cell therapy manufacturing expansion:Autologous CAR-T processes require extensive in-process testing, multiplying assay consumption per therapeutic dose.
- mRNA vaccine platform persistence:Lipid nanoparticle formulations demand rigorous endotoxin screening at multiple production stages.
Market Restraints
- Atlantic horseshoe crab population volatility:Delaware Bay harvesting restrictions threaten LAL reagent supply concentration.
- Recombinant Factor C cost premium:Synthetic alternatives command 40-60% price elevation over conventional lysate.
- Validation timeline friction:FDA comparability protocols delay switching from established Limulus methods.
Strategic Opportunities
- India biosimilar manufacturing:CDSCO-aligned facilities lack mature endotoxin testing infrastructure.
- Point-of-use water testing:WFI systems in multi-product facilities create decentralized assay demand.
- ISO 10993-11 harmonization:Medical device pyrogen testing standardization opens cross-border service contracts.
Industry Challenges
- Chromogenic assay specialist scarcity:Kinetic method expertise outpaces turbidimetric training pipelines.
- Legacy LAL inventory stranding:Facilities face write-downs on non-recombinant reagent stockpiles.
- Multi-modal validation complexity:Simultaneous gel-clot, kinetic, and rFC method maintenance strains QC bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endotoxin and Pyrogen Testing Market |
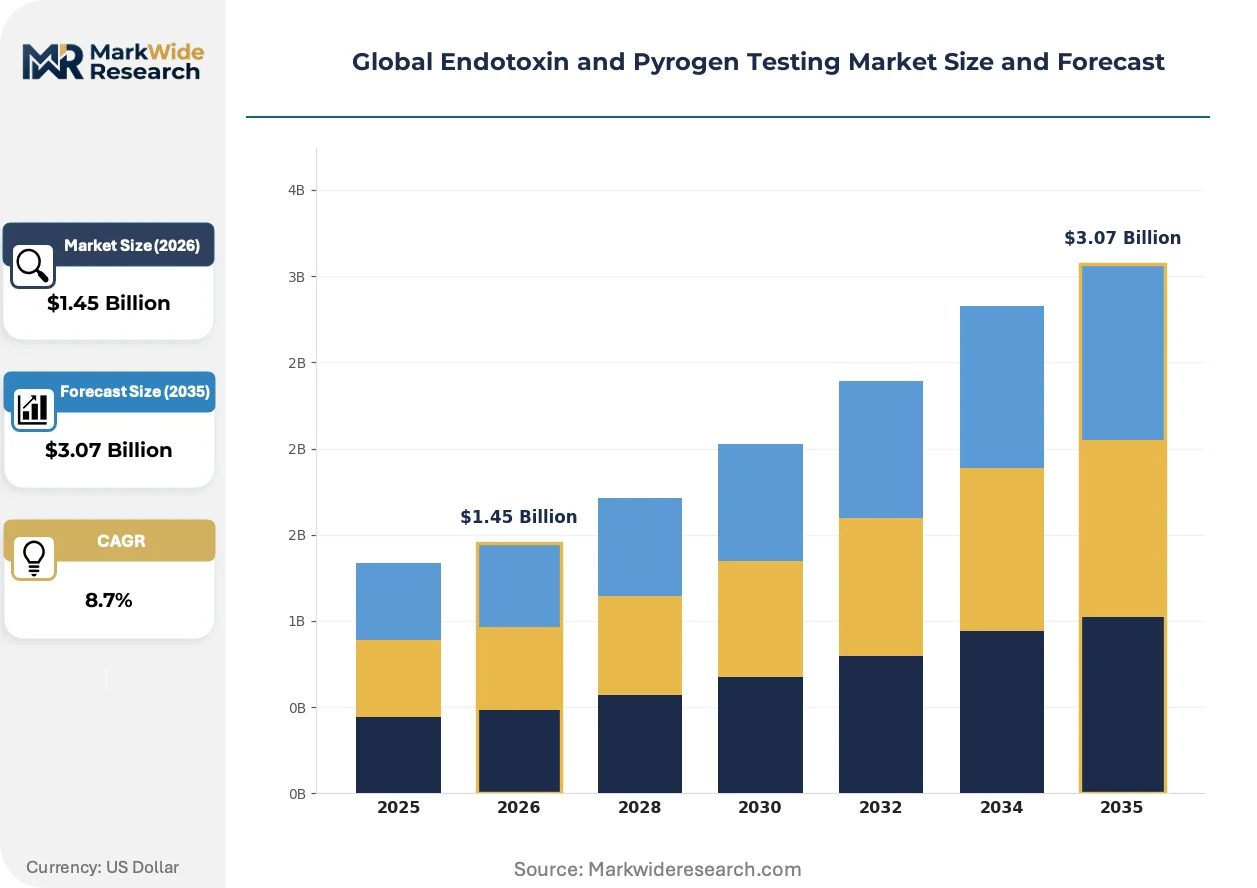
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel Clot Test, Kinetic Turbidimetric, Kinetic Chromogenic, Chromogenic Endpoint, Recombinant Factor C Assay Application: Pharmaceuticals, Biopharmaceuticals, Medical Device Sterilization, Water Testing, Vaccine Manufacturing End User: Contract Research Organizations, Regulatory Agencies, Biotech Firms, Quality Control Laboratories, Academic Institutions Deployment: In-house Testing, Outsourced Testing, On-site Analysis, Central Laboratory Services |
| Companies Covered | Eurofins Scientific SE, bioMérieux SA, Thermo Fisher Scientific Inc., GenScript Biotech Corporation, WuXi AppTec Co., Ltd., Charles River Laboratories International, Inc., Lonza Group Ltd., SGS SA, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endotoxin and Pyrogen Testing Market Shifts & Advancements
Assay platform architecture is fragmenting into componentized systems that separate detection chemistry from instrumentation and data analytics. This decomposition enables hybrid sourcing strategies unthinkable under vertically integrated LAL supply.
Recombinant Factor C technology is modularizing endotoxin detection into discrete functional units: recombinant protein supply, fluorescence readers, and cloud-based kinetic analysis software. Mid-size biologics manufacturers in Germany and Switzerland are adopting this architecture fastest. The shift is compressing capital requirements for in-house testing while expanding third-party reagent sourcing options.
China's NMPA has issued technical guidelines endorsing rFC methods for biological product release testing, creating regulatory parity with LAL-based approaches. Domestic vaccine producers in Shanghai and Suzhou are submitting parallel validation protocols. This alignment is accelerating local recombinant reagent manufacturing investments.
Quality control departments are unbundling instrument ownership from reagent supply contracts, treating detection platforms as consumable-agnostic hardware. Large biopharmaceutical manufacturers in Massachusetts and North Carolina now procure rFC cartridges and LAL vials through separate vendor relationships. This pattern is most pronounced among CDMOs serving multiple sponsor quality systems.
Global Endotoxin and Pyrogen Testing Market Segmentation
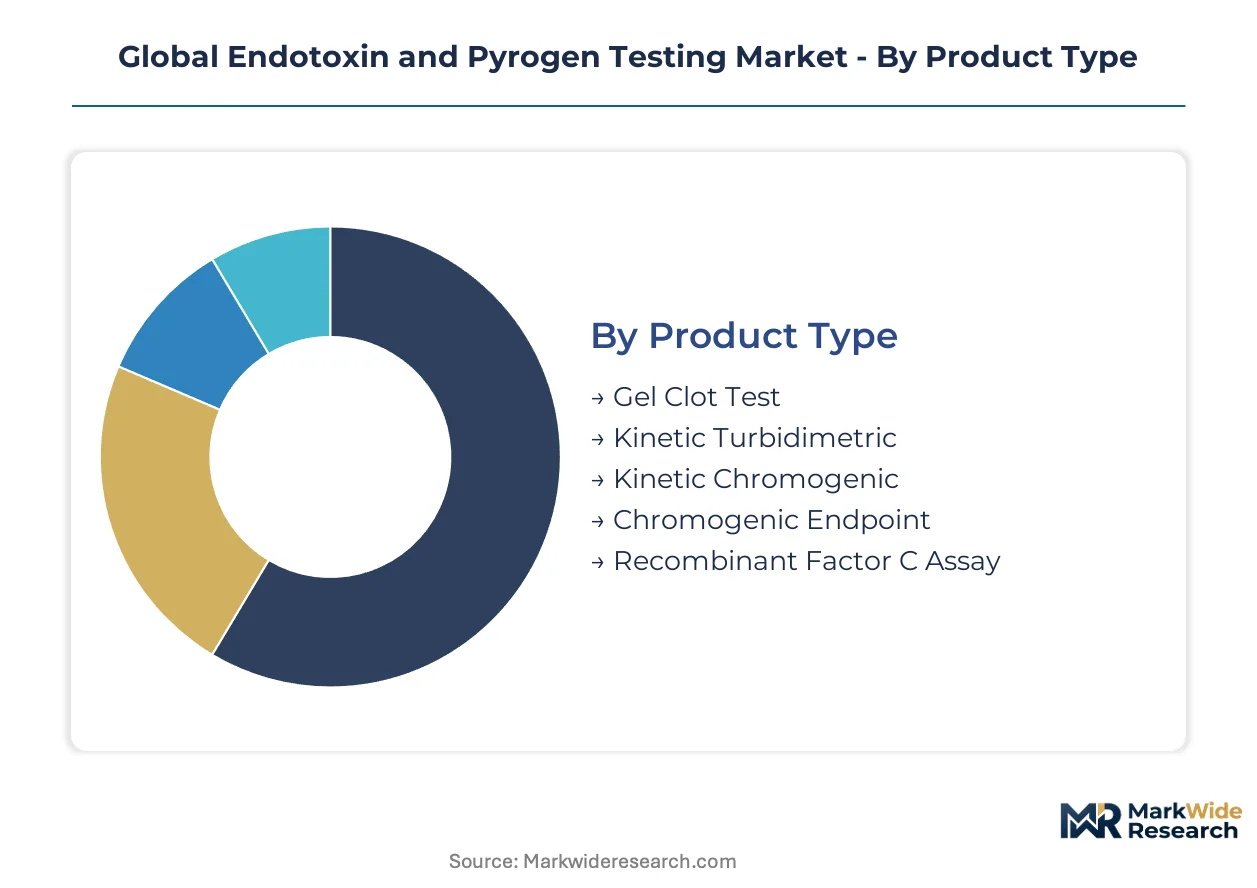
Endotoxin testing procurement divides sharply between standardized high-volume assays and customized validation protocols. Biopharmaceutical manufacturers navigate this spectrum when balancing regulatory compliance against operational flexibility across monoclonal antibody, cell therapy, and vaccine production workflows.
Product Type:
Customization intensity varies from rigid pharmacopeial methods to modular synthetic platforms that permit protocol tailoring.
- Kinetic Turbidimetric:Measures endotoxin concentration through real-time turbidity changes in Limulus amebocyte lysate. High-throughput quality control laboratories in Massachusetts and North Carolina favor this format for batch release testing of parenteral drugs, driven by FDA USP Chapter 85 compliance mandates.
- Recombinant Factor C Assay:Synthetic protein-based detection eliminates horseshoe crab dependency. German and Swiss biologics manufacturers adopt this fastest amid EMA conservation guidelines and supply security concerns, despite 40-60% cost premiums over conventional lysate.
- Gel Clot Test:Manual visual endpoint determination remains specified for certain pharmacopeial validations.
- Kinetic Chromogenic:Colorimetric substrate release enables quantitative measurement with standard spectrophotometers.
- Chromogenic Endpoint:Single-point absorbance reading suits lower-volume testing environments without kinetic instrumentation.
Leading the category by volume: Kinetic Turbidimetric. Expanding most quickly: Recombinant Factor C Assay.
Application:
Margin capture concentrates where regulatory stringency intersects with production complexity and patient risk exposure.
- Biopharmaceuticals:Monoclonal antibody and cell therapy processes demand extensive in-process and release testing. Autologous CAR-T manufacturing in the United States multiplies assay consumption per therapeutic dose through multiple critical control points.
- Vaccine Manufacturing:mRNA lipid nanoparticle formulations require rigorous endotoxin screening at plasmid, mRNA, and formulation stages. Chinese producers in Shanghai and Suzhou scale parallel testing lines under NMPA technical guidelines.
- Pharmaceuticals:Small-molecule parenteral drugs maintain steady assay demand through established manufacturing protocols.
- Medical Device Sterilization:Implantable products face ISO 10993-11 pyrogen testing requirements for biological safety evaluation.
- Water Testing:Water-for-injection systems in multi-product facilities create decentralized assay demand for continuous monitoring.
Highest margin pool: Biopharmaceuticals. Steepest volume climb: Vaccine Manufacturing.
End User:
Capability investment separates centralized validation specialists from distributed routine testing operations.
- Quality Control Laboratories:Captive testing facilities within biopharmaceutical manufacturers maintain validated methods for batch release. These operations in Germany and Switzerland lead recombinant Factor C adoption to secure supply continuity.
- Contract Research Organizations:Multi-client service providers aggregate demand across sponsor programs. CDMOs in Massachusetts and North Carolina now unbundle instrument ownership from reagent contracts to serve diverse quality systems.
- Biotech Firms:Emerging therapeutic developers outsource validation-heavy protocols while building internal screening capacity.
- Regulatory Agencies:Reference laboratories maintain certified standards for pharmacopeial harmonization and enforcement.
- Academic Institutions:Research applications drive method development and comparative validation studies.
Dominant procurement volume: Quality Control Laboratories. Fastest capability buildout: Contract Research Organizations.
Deployment:
Asset ownership models fragment as reagent-agnostic instrumentation enables hybrid sourcing strategies.
- In-house Testing:Direct ownership of detection platforms and validated methods. Large biopharmaceutical manufacturers favor this for proprietary biologics processes requiring rapid turnaround.
- Outsourced Testing:Third-party laboratory services for non-core or overflow capacity. Eurofins leverages geographic networks to sustain high-throughput capacity for manufacturers.
- On-site Analysis:Portable or dedicated equipment positioned at production facilities for immediate screening.
- Central Laboratory Services:Consolidated testing hubs serving multiple manufacturing sites under standardized protocols.
Prevailing model by facility count: In-house Testing. Gaining share fastest: Outsourced Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston-Cambridge anchors global endotoxin testing demand through concentrated biopharmaceutical manufacturing. The region's cell therapy production facilities drive intensive quality control requirements. FDA USP Chapter 85 enforcement sustains structural demand for validated assay platforms.
United States
Massachusetts and North Carolina biologics clusters multiply assay consumption per therapeutic dose through CAR-T manufacturing. FDA draft guidance on recombinant Factor C acceptance accelerates synthetic alternative adoption. Cambridge and Durham facilities lead unbundling of instrument ownership from reagent contracts.
Germany
Bavarian and Swiss-border biologics manufacturers prioritize supply security amid EMA conservation guidelines. EMA Pharmacopoeia 2.6.14 mandates sustain structural demand for validated detection platforms. Munich and Basel-area quality control laboratories lead European recombinant Factor C procurement.
China
Shanghai and Suzhou vaccine producers scale parallel testing lines under NMPA technical guidelines. NMPA endorsement of rFC methods for biological product release creates regulatory parity with LAL approaches. Domestic recombinant reagent manufacturing investments accelerate in Yangtze River Delta clusters.
Switzerland
Swissmedic-aligned facilities in Basel and Zurich adopt modular assay architectures fastest. Conservation pressures on horseshoe crab harvesting tighten procurement strategies. Swiss biologics manufacturers compress capital requirements for in-house testing through componentized platform adoption.
India
CDSCO-aligned biosimilar manufacturing in Maharashtra and Telangana lacks mature endotoxin testing infrastructure. Central Drug Standard Control Organization regulations create compliance gaps for export-oriented facilities. Mumbai and Hyderabad CDMOs build validation-heavy protocols to serve sponsor quality systems.
Global Endotoxin and Pyrogen Testing Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the endotoxin testing landscape. Vertically integrated reagent manufacturers maintain captive supply chains while specialized service providers aggregate demand through geographic laboratory networks. Three archetypes dominate: integrated reagent-instrument platforms, multi-site testing service networks, and modular component suppliers. Consolidation pressure favors M&A between reagent specialists and instrument manufacturers, while strategic partnerships link synthetic biology firms with fluorescence detection platforms.
Among European-headquartered testing service networks, Eurofins Scientific SE exemplifies geographic scale aggregation. Lonza Group Ltd. and Charles River Laboratories International, Inc. occupy positions spanning reagent supply and specialized pathogen-free product lines. These three entities represent contrasting strategic postures: service network expansion, captive reagent production, and integrated workflow specialization.
| Leading Market Players |
|---|
| Eurofins Scientific SE |
| bioMérieux SA |
| Thermo Fisher Scientific Inc. |
| GenScript Biotech Corporation |
| WuXi AppTec Co., Ltd. |
| Charles River Laboratories International, Inc. |
| Lonza Group Ltd. |
| SGS SA |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Chromogenic assay specialists in Bavaria and the Swiss border region command wage premiums that widen spreads between premium recombinant Factor C platforms and economy-grade Limulus lysate commodites. Labor-cost differentials between automated high-throughput facilities and manual gel-clot operations feed directly into three-tier pricing stratification across quality control procurement.
Pricing Analysis
Throughput-linked value capture anchors pricing structures, with kinetic turbidimetric platforms commanding premiums tied to batch-release velocity and regulatory audit confidence. Price differentiation rests on FDA USP Chapter 85 compliance tier and EMA Pharmacopoeia 2.6.14 certification grade, while volume-scale discounts compress margins for high-throughput CDMO contracts. Pricing pressure stems from recombinant Factor C manufacturing scale-up as synthetic biology suppliers expand fermentation capacity. Large biopharmaceutical manufacturers in Massachusetts exhibit lowest price sensitivity due to supply-security mandates, whereas emerging biosimilar producers in India face acute cost constraints.
Supply Chain Analysis
Horseshoe crab hemolymph supply rests on Delaware Bay harvesting operations concentrated in the United States, with secondary processing capacity in Japan and Singapore. Recombinant protein production draws from Chinese contract fermentation facilities and German specialty enzyme manufacturers, while fluorescence detection instrumentation sources from Swiss optics specialists and Japanese precision engineering clusters. Single-source vulnerability concentrates in Atlantic horseshoe crab population management under state-level conservation restrictions. Distribution runs through reagent-agnostic instrument leasing networks that unbundle hardware ownership from consumable supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Atlantic horseshoe crab harvesting quotas constrain raw material throughput, propping lysate pricing and accelerating buyer migration toward synthetic alternatives. This supply-constrained structure favors incumbents with captive recombinant production and entrants with modular platform architectures.
For Market Incumbents: Hedge against conservation-driven substitution by securing recombinant Factor C fermentation capacity in Germany or Switzerland before regulatory acceptance widens. Backward integration into synthetic protein supply reduces exposure to Delaware Bay harvesting volatility, while maintaining legacy LAL inventory buffers against validation timeline friction for conservative buyers. For New Entrants and Emerging Players: CDMO quality control departments in India and Southeast Asia present the most penetrable white-space target, given immature endotoxin testing infrastructure and export-compliance pressures. A modular reagent-agnostic platform architecture lowers capital barriers for facilities unbundling instrument ownership from consumable contracts, enabling rapid deployment without validation-heavy legacy method displacement. For Investors and Strategic Acquirers: Re-rating potential sits with recombinant reagent specialists given FDA draft guidance acceleration and EMA conservation alignment. Long-term viability across the projection horizon favors synthetic biology platforms with pharmacopeial validation dossiers over horseshoe crab-dependent lysate processors. The signal to watch is NMPA technical guideline expansion beyond Shanghai and Suzhou vaccine producers to broader biological product categories.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Factor C Manufacturing Scale-Up | Synthetic fermentation capacity in Germany and Switzerland displaces horseshoe crab dependency for EMA-aligned facilities. |
| Reagent-Agnostic Instrument Platform Launch | Unbundled hardware ownership enables CDMOs to serve multiple sponsor quality systems without method lock-in. |
| Pharmacopeial Validation Dossier Expansion | FDA USP Chapter 85 and EMA 2.6.14 alignment accelerates regulatory acceptance for synthetic alternatives. |
| CDMO Partnership Network Development | Geographic laboratory aggregation in India and Southeast Asia captures biosimilar manufacturing compliance demand. |
| Conservation Certification Program | EMA-aligned sustainability credentials differentiate recombinant platforms from lysate competitors under harvesting restrictions. |
Research Methodology
Independent corroboration across quality control laboratory directors, regulatory affairs specialists at biopharmaceutical manufacturers, reagent procurement managers, and synthetic biology R&D leads underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through FDA guidance documents, EMA Pharmacopoeia revision notices, NMPA technical guidelines, and SEC filings from publicly traded testing service providers. Bottom-up assay consumption modeling triangulated against top-down market value estimates across product type, application, and end-user dimensions.
Historical reference periods anchored volume and value trajectories to pre-pandemic baselines, pandemic surge dynamics, and normalized post-acceleration demand patterns across the analysis window. Segmentation modeling incorporated assay format, therapeutic modality, manufacturing scale tier, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to validated base-year estimates, with recombinant technology adoption curves and conservation policy implementation timelines as key forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen Atlantic horseshoe crab population collapses, abrupt FDA withdrawal of draft recombinant Factor C guidance, and trade restriction impacts on Chinese fermentation capacity. Forecasts reflect stated assumptions about regulatory acceptance trajectories and manufacturing scale-up timelines. A small set of named triggers warrants ongoing watch: NMPA guideline geographic expansion, Delaware Bay harvesting quota revisions, and major biopharmaceutical manufacturer validation protocol completions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Host Cell Protein Testing Market
Testing Services
Global Sterility Testing Market
Testing Services
At-Home Celiac Testing Market
Testing Services
Warfarin Sensitivity Test Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
Medical Device Analytical Testing Outsourcing Market
Testing Services
Pharmaceutical Analytical Testing Market
Testing Services
Global GI Stool Testing Market
Testing Services
Europe Medical Device Testing Market
Testing Services
Solid Tumor Testing Market
Testing Services
Metabolic Biomarker Testing Market
Testing Services
Fungal Testing Kits Market
Testing Services
Hemostasis Testing Systems Market
Testing Services
Radiographic Testing Market
Testing Services
Global Medical Device Testing and Certification Market
Testing Services
Global Extractables and Leachables Testing Services Market