
 Opium Tincture Market | 2026-2036
Opium Tincture Market Size, Share, and Industry Trends Forecast 2026-2036
Opium Tincture Market Analytics
The DEA's enhanced track-and-trace mandates for Schedule II narcotics is recalibrating procurement security requirements across institutional buyers. Hänseler AG leverages its European manufacturing heritage to sustain specialized tincture production for regulated export markets. Macfarlan Smith anchors UK-based alkaloid extraction capabilities that differentiate its supply position for pharmaceutical-grade formulations.
Opium tincture is an alcoholic solution containing approximately 10% w/v powdered opium, standardized to contain morphine and other opium alkaloids, produced through maceration and percolation extraction processes for antidiarrheal and analgesic therapeutic applications. Liquid extracts dominate hospital and rehabilitation center procurement due to dose flexibility and rapid absorption profiles, while oral delivery modes occupy the largest share of clinical protocols across pain management and cough relief applications. Sublingual formulations represent a narrower but growing segment where faster onset requirements justify higher formulation complexity.
The FDA, DEA, and WHO International Narcotics Control Board collectively govern manufacturing quotas, import permits, and distribution licensing that constrain supply elasticity and elevate compliance costs for all market participants. The Controlled Substances Act and 21 CFR Part 1300 series establish chain-of-custody documentation that directly shapes inventory management investments and logistics partner selection. Stakeholders must monitor evolving opioid stewardship guidelines and alkaloid quota allocations to anticipate procurement constraints and qualify alternative therapeutic positioning.
Market Dynamics
The DEA's 2023 enhanced track-and-trace mandates for Schedule II narcotics have recalibrated procurement security requirements across institutional buyers, forcing wholesale distributors and hospital systems to upgrade serialization infrastructure and chain-of-custody documentation systems.
Growth Catalysts
- Hospital formulary expansion:Clinicians in tertiary care centers are reinstating opium tincture for refractory diarrhea cases where first-line antidiarrheals fail, particularly in oncology and HIV/AIDS patient populations.
- 21 CFR Part 1300 compliance investments:The FDA's controlled substance documentation requirements have professionalized distribution channels, filtering out informal suppliers and consolidating volume with qualified institutional buyers.
- Alkaloid extraction process improvements:Advanced percolation and maceration technologies are yielding more consistent morphine standardization, reducing batch rejection rates and stabilizing supply for pharmaceutical-grade formulations.
Market Restraints
- Papaver somniferum cultivation concentration:Raw opium gum sourcing depends on a narrow geographic band spanning Turkey, India, and Australia, exposing processors to climate-driven yield volatility and export quota restrictions.
- DEA manufacturing quota ceilings:The Drug Enforcement Administration's annual morphine alkaloid allocation limits create supply inelasticity that prevents rapid response to demand surges in hospital settings.
- Loperamide substitution threat:Synthetic antidiarrheal alternatives with over-the-counter availability continue displacing opium tincture in primary care protocols, compressing addressable patient populations.
Strategic Opportunities
- Palliative care protocol integration:Hospice programs in Germany and Switzerland are expanding opium tincture use for terminal diarrhea management, creating demand pockets outside traditional hospital channels.
- Compounding pharmacy specialization:The US 503A and 503B facility designations enable customized dosing formulations for patients with swallowing difficulties or opioid tolerance profiles.
- WHO Essential Medicines List positioning:Advocacy for reinstatement of opium tincture on national essential medicines lists in low-income countries could unlock institutional procurement frameworks.
Industry Challenges
- DEA registration renewal complexity:Manufacturers and distributors face 12-18 month reauthorization cycles with enhanced background checks and facility inspections that disrupt operational continuity.
- Cold chain integrity for liquid formulations:Temperature excursions during transport degrade alkaloid potency, requiring validated packaging investments that strain smaller compounding operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Opium Tincture Market |
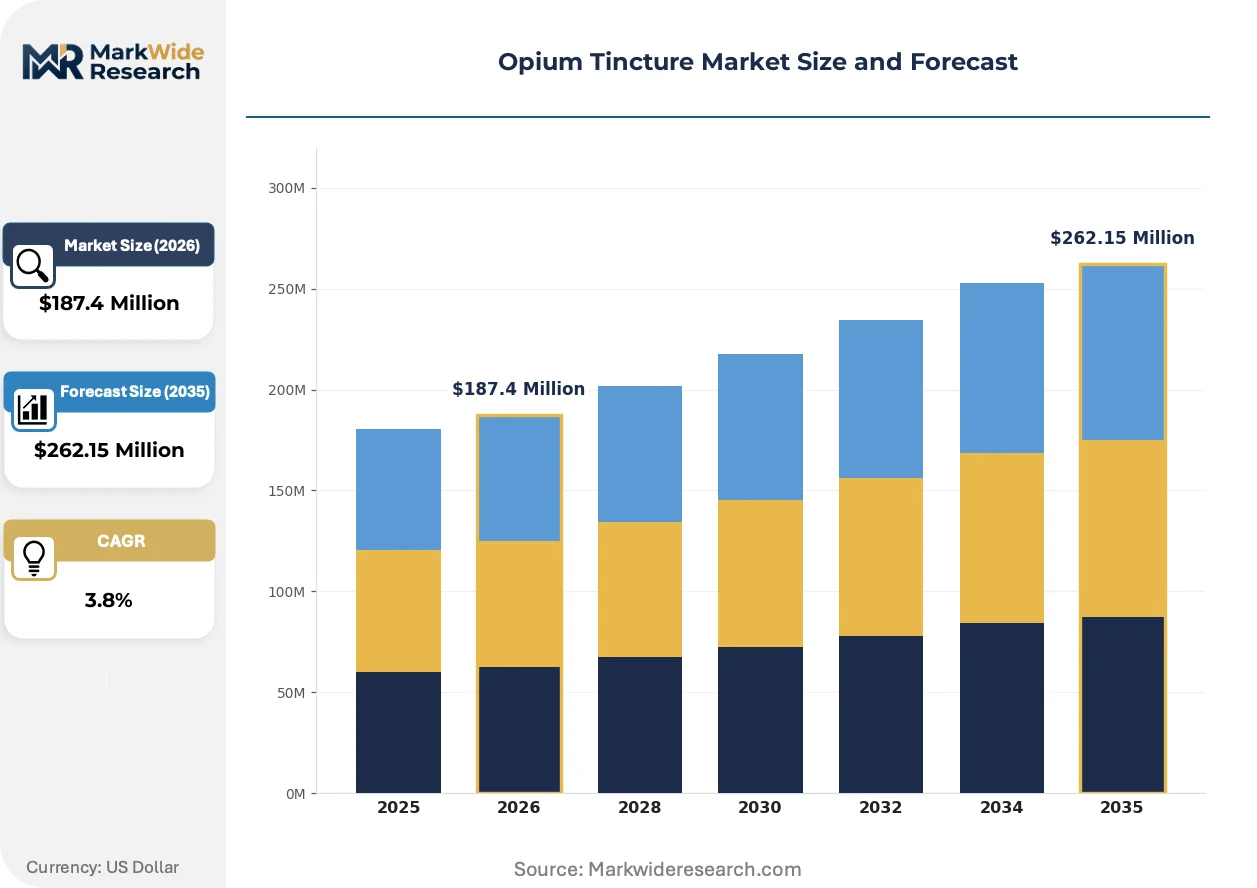
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extracts, Pills, Capsules, Balms Delivery Mode: Intravenous, Oral, Topical, Sublingual End User: Pharmaceuticals, Rehabilitation Centers, Research Institutions, Hospitals Application: Pain Management, Anesthesia, Cough Relief, Sleep Disorders |
| Companies Covered | Hänseler AG, Johnson & Johnson, Temad Co., GlaxoSmithKline, Pfizer, Vonage Pharma, Macfarlan Smith, Sanofi, GMP Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Opium Tincture Market Evolving Landscape
Formulation science and regulatory technology are converging to reshape how opium tincture moves from alkaloid extraction to patient administration. Three developments are altering competitive positioning and procurement patterns.
Microfluidic encapsulation technology is expanding into opium tincture manufacturing, enabling precise droplet-size control for sublingual spray formulations. Pediatric and geriatric care units in academic medical centers are piloting these delivery systems to bypass first-pass metabolism and accelerate onset. The technology is compressing the timeline between prescription and therapeutic effect, creating preference premiums for equipped suppliers.
The FDA's Drug Supply Chain Security Act (DSCSA) serialization requirements are mandating unit-level traceability for all Schedule II products by November 2024. Wholesale distributors must now maintain interoperable data systems that verify product authenticity at each ownership transfer. Hospital pharmacy buyers are prioritizing suppliers with pre-integrated verification infrastructure, disadvantaging smaller compounders lacking IT capital.
Consolidated purchasing cooperatives are displacing individual hospital negotiations for controlled substance procurement. Group Purchasing Organizations (GPOs) representing multi-hospital systems in the US Southeast are standardizing formulary decisions and extracting volume-based pricing commitments. This concentration is most visible in Florida and Texas, where three GPOs now control the majority of institutional opium tincture allocation.
Opium Tincture Market Segmentation
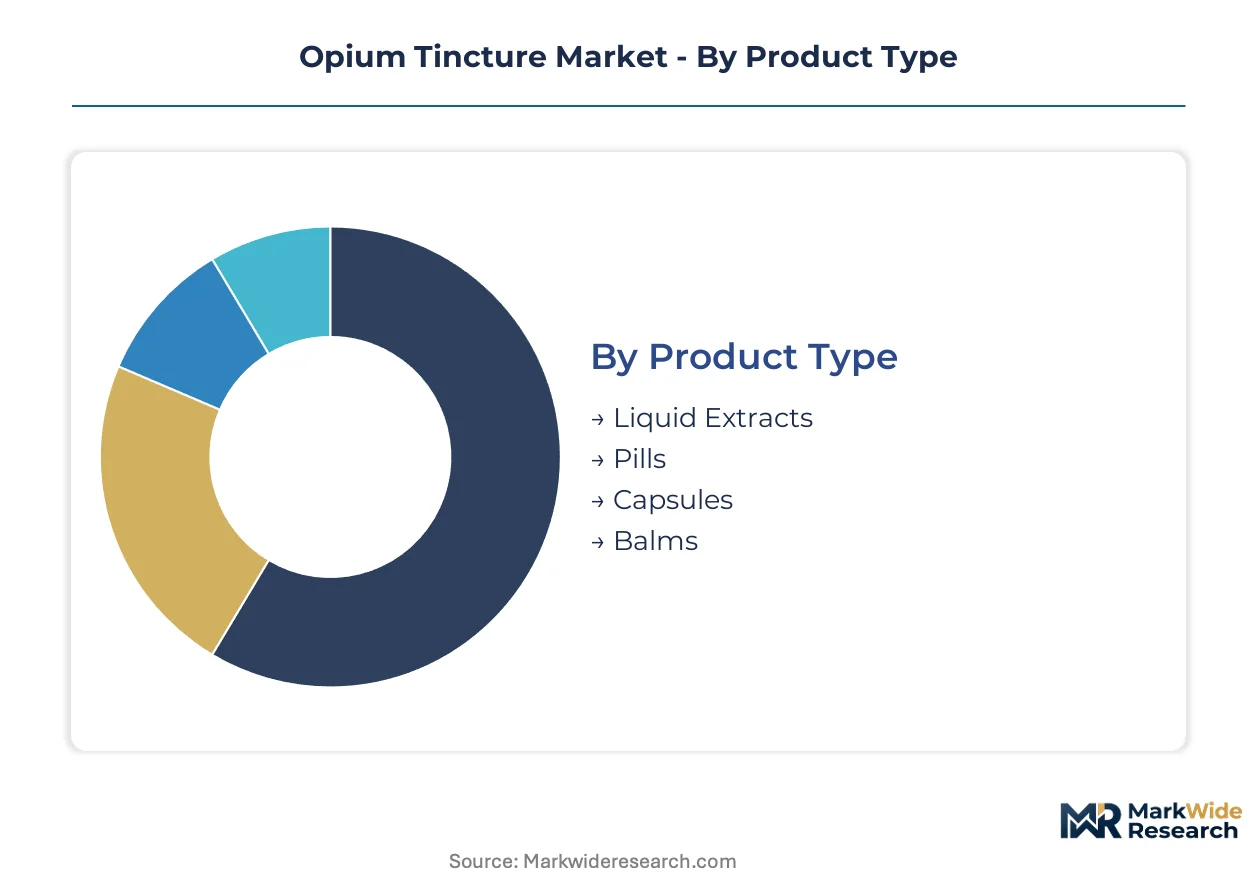
Opium tincture procurement patterns diverge sharply across formulation types and care settings. Regulatory scheduling constraints and clinical protocol requirements create distinct demand profiles that suppliers must navigate separately.
Product Type:
Liquid extracts function as standalone therapeutic agents requiring precise dosing infrastructure, while solid dosage forms embed into broader pharmaceutical manufacturing workflows.
- Liquid Extracts:Alcoholic solutions standardized to 10% w/v powdered opium content enable milliliter-accurate titration in hospital infusion protocols. Demand clusters in US tertiary care centers managing refractory diarrhea, where the FDA's Schedule II documentation requirements favor suppliers with pre-integrated track-and-trace systems.
- Pills:Compressed tablet formulations containing standardized morphine alkaloids support outpatient pain management where portability and shelf stability matter. German hospice programs and Swiss palliative care networks are expanding procurement for terminal symptom control, driven by WHO Essential Medicines List alignment efforts.
- Capsules:Gelatin-encapsulated alkaloid blends suit compounding pharmacy customization for patients with swallowing difficulties or specific tolerance profiles.
- Balms:Topical preparations with reduced systemic absorption target localized discomfort in rehabilitation settings where oral opioid exposure carries dependency concerns.
Volume placements concentrate in Liquid Extracts; the faster expansion belongs to Pills.
Delivery Mode:
Route selection directly shapes DEA custody documentation intensity and cold chain investment requirements.
- Oral:The dominant administration pathway across hospital formularies and outpatient protocols, leveraging established gastric absorption pharmacokinetics. US Group Purchasing Organizations standardize oral tincture procurement across multi-hospital systems, consolidating volume with qualified distributors meeting DSCSA serialization mandates.
- Sublingual:Bypass-first-metabolism delivery accelerates onset for acute pain episodes and breakthrough diarrhea. Microfluidic spray formulations are gaining traction in academic medical center pediatric and geriatric units where rapid effect justifies premium pricing.
- Intravenous:Sterile alkaloid solutions for perioperative and intensive care settings demand aseptic manufacturing capabilities that filter supply to specialized compounding facilities.
- Topical:Dermal absorption routes minimize systemic opioid exposure in rehabilitation protocols, aligning with institutional stewardship guidelines targeting reduced dependency risk.
Procurement gravity centers on Oral formulations; Sublingual delivery is climbing the fastest.
End User:
Customer scale determines quota allocation priority and regulatory inspection frequency.
- Hospitals:Institutional buyers with DEA registration and 21 CFR Part 1300 compliance infrastructure command preferential manufacturing quota access. The 2023 enhanced track-and-trace mandates have professionalized procurement channels, filtering volume toward systems with interoperable verification technology.
- Pharmaceuticals:Bulk alkaloid purchasers for downstream formulation and export face extended DEA reauthorization cycles that disrupt operational continuity.
- Rehabilitation Centers:Specialized facilities integrating tincture into multimodal pain protocols require flexible dosing formats that strain smaller compounding operations.
- Research Institutions:Investigational use permits for clinical trials and pharmacokinetic studies operate under separate regulatory tracks with distinct quota carve-outs.
Quota priority flows to Hospitals; Research Institutions are expanding most quickly.
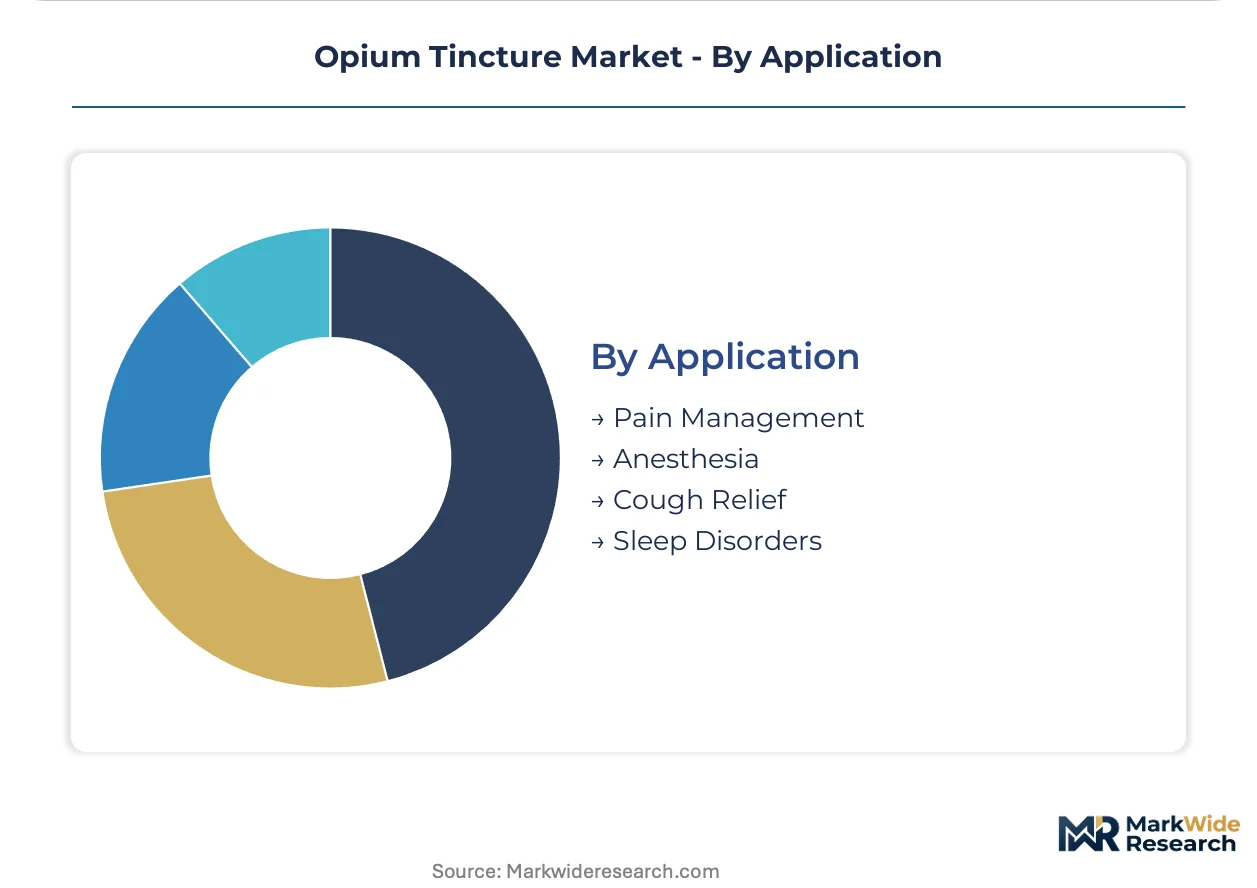
Application:
Therapeutic indication shapes DEA scheduling scrutiny and substitution vulnerability.
- Pain Management:The primary clinical indication spanning acute postoperative care and chronic cancer-related discomfort. US hospital formularies are reinstating tincture for opioid-tolerant patients where synthetic alternatives fail, particularly in oncology units.
- Cough Relief:Antitussive applications face displacement from synthetic dextromethorphan formulations and prescription opioid stewardship restrictions.
- Anesthesia:Perioperative adjunct use in specialized surgical protocols requires precise alkaloid standardization that advanced percolation technologies now stabilize.
- Sleep Disorders:Niche sedative applications in geriatric populations where conventional hypnotics carry fall risk and cognitive side effects.
Clinical volume concentrates in Pain Management; Sleep Disorders show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Philadelphia's specialized pharmaceutical corridor anchors North American opium tincture procurement, with institutional buyers clustering around major tertiary care centers and DEA-registered distribution hubs.
United States
Hospital formulary reinstatements for refractory diarrhea drive procurement volume, particularly in oncology and HIV/AIDS patient populations. The DEA's 2023 enhanced track-and-trace mandates for Schedule II narcotics force wholesale distributors to upgrade serialization infrastructure. Procurement concentrates in Florida and Texas, where three Group Purchasing Organizations now control the majority of institutional allocation.
Germany
Hospice programs expand opium tincture use for terminal diarrhea management, creating demand pockets outside traditional hospital channels. The country's national pharmaceutical regulator maintains strict manufacturing quota oversight aligned with WHO International Narcotics Control Board protocols. Industrial activity clusters in Bavaria, where specialized alkaloid extraction facilities serve regulated export markets.
Switzerland
Palliative care networks drive sublingual formulation adoption for rapid-onset requirements in geriatric populations. Swissmedic enforces cold chain integrity standards that elevate packaging investments for liquid formulations. The Basel pharmaceutical corridor hosts compounding operations specializing in customized dosing for patients with swallowing difficulties.
United Kingdom
Macfarlan Smith anchors UK-based alkaloid extraction capabilities that differentiate supply position for pharmaceutical-grade formulations. The country's national pharmaceutical regulator coordinates with the Home Office on import permit allocation and distribution licensing. Edinburgh and Glasgow maintain concentrated manufacturing infrastructure for downstream pharmaceutical processing.
India
Raw opium gum sourcing from licensed Papaver somniferum cultivation supports global alkaloid supply chains. CDSCO governs manufacturing quotas and export authorization under international narcotics control frameworks. Cultivation concentrates in Madhya Pradesh and Rajasthan, where climate-driven yield volatility exposes processors to supply constraints.
Opium Tincture Market Competitive Landscape
The competitive structure tilts toward vertically integrated alkaloid specialists with captive raw material access. Three to five dominant players control manufacturing quota allocation through DEA and international narcotics board relationships, while mid-tier compounders compete on formulation customization. Two strategic archetypes prevail: heritage European manufacturers with established extraction expertise, and diversified pharmaceutical conglomerates leveraging distribution scale. Consolidation pressure operates through quota-access partnerships and specialized compounding pharmacy acquisitions.
Within the heritage specialist tier, Hänseler AG and Macfarlan Smith exemplify European manufacturers sustaining tincture production through regulated export market positioning. Among diversified pharmaceutical conglomerates, Johnson & Johnson and Pfizer occupy positions leveraging institutional distribution infrastructure for controlled substance logistics. These archetypes represent contrasting approaches to navigating DEA registration complexity and cold chain investment requirements.
| Leading Market Players |
|---|
| Hänseler AG |
| Johnson & Johnson |
| Temad Co. |
| GlaxoSmithKline |
| Pfizer |
| Vonage Pharma |
| Macfarlan Smith |
| Sanofi |
| GMP Pharma |
| Others |
Value Network & Pricing Analysis
DEA Schedule II certification tiers bifurcate opium tincture procurement into pharmaceutical-grade and compounding-grade channels, with pricing power concentrating in manufacturers holding active alkaloid quota allocations while supply chain configurations stratify around cold chain validation capabilities and track-and-trace infrastructure investments.
Pricing Analysis
Value-based pricing anchors to morphine alkaloid standardization consistency and DEA manufacturing quota access. Three-tier pricing structure across pharmaceutical-grade, institutional-grade, and compounding-grade levels reflects FDA 21 CFR Part 1300 compliance depth and DSCSA serialization readiness. Pricing pressure stems from loperamide substitution in primary care protocols compressing addressable volumes. Hospital systems demonstrate lowest price sensitivity due to formulary reinstatement for refractory diarrhea, while independent compounding pharmacies face acute margin compression from cold chain packaging investments.
Supply Chain Analysis
FDA cGMP and DEA registration gating filter supply to qualified manufacturers with validated alkaloid extraction processes. Raw opium gum sourcing draws from Turkey, India, and Australia, with Papaver somniferum cultivation licensing tethered to International Narcotics Control Board quotas. Single-source vulnerability concentrates in Indian Madhya Pradesh and Rajasthan cultivation zones exposed to monsoon-driven yield volatility. Distribution runs through DEA-registered wholesale distributors with interoperable serialization systems serving hospital GPOs and specialized compounding networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Opium tincture procurement operates as a quota-constrained market where DEA manufacturing allocation ceilings prop pricing stability by preventing supply elasticity from matching demand surges in hospital settings.
For Market Incumbents: Acquire specialized compounding pharmacy networks with 503B facility designations to secure downstream channel control against GPO consolidation pressure. Backward integration into Papaver somniferum cultivation licensing in Turkey or Australia reduces raw material exposure to Indian climate volatility. Prioritize microfluidic encapsulation R&D to capture sublingual formulation premiums in academic medical center pediatric and geriatric units. For New Entrants and Emerging Players: Compounding pharmacy partnerships offer the most penetrable entry vector for manufacturers lacking DEA quota history, particularly 503A facilities serving hospice and palliative care networks in Germany and Switzerland. White-space exists in WHO Essential Medicines List advocacy for low-income country institutional procurement frameworks. Lead with cold chain logistics specialization to differentiate from incumbent distributors struggling with temperature excursion liability. For Investors and Strategic Acquirers: Exit pathways concentrate in diversified pharmaceutical conglomerates seeking DEA quota access and alkaloid extraction capabilities. Long-term viability hinges on opioid stewardship guideline evolution rather than demand erosion. The signal to watch is alkaloid quota reallocation hearings, where manufacturing ceiling adjustments would signal inflection in supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| DEA Quota Partnership | Manufacturing allocation agreements with established quota holders unlock Schedule II production capacity for downstream formulation. |
| Cold Chain Infrastructure Investment | Temperature-validated packaging capabilities satisfy FDA DSCSA requirements while reducing batch potency degradation liability. |
| Microfluidic Formulation Development | Sublingual spray technology captures premium positioning in pediatric and geriatric rapid-onst protocols bypassing first-pass metabolism. |
| GPO Contract Consolidation | Multi-hospital system purchasing agreements in Florida and Texas concentrate volume with distributors meeting enhanced track-and-trace mandates. |
| WHO Essential Medicines Advocacy | National formulary reinstatement campaigns in low-income countries unlock institutional procurement frameworks outside saturated US channels. |
Research Methodology
FDA enforcement letters, DEA quota allocation records, and WHO International Narcotics Control Board cultivation estimates formed the secondary backbone, supplemented by primary interviews with hospital formulary directors, DEA-registered wholesale distributors, 503B compounding pharmacy operators, palliative care clinicians, and alkaloid extraction facility managers. Bottom-up demand modeling from hospital procurement databases and GPO contract disclosures triangulated against top-down manufacturing quota and trade flow analysis.
Bottom-up volume projections aggregated across formulation type, delivery mode, and end-user segments, with value outputs derived from pricing stratification across pharmaceutical-grade, institutional-grade, and compounding-grade tiers. CAGRs were computed from baseline market sizing through projection horizon endpoints, incorporating alkaloid quota growth assumptions, formulary reinstatement rates in oncology and HIV/AIDS patient populations, and substitution elasticity parameters for loperamide displacement in primary care protocols.
Caveats apply where DEA manufacturing quota reallocation decisions, International Narcotics Control Board cultivation authorization shifts, or opioid stewardship guideline revisions could materially shift the outlook beyond modeled supply elasticity constraints. A model refresh is warranted upon material change in DEA Schedule II track-and-trace mandate enforcement intensity or WHO Essential Medicines List positioning outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
H1N1 Vaccination Market
Pharmaceuticals
Filgrastim Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Global Immunosuppressant Drugs Market
Pharmaceuticals
Global Acetazolamide Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market
Pharmaceuticals
Global Non-Small Cell Lung Cancer Drugs Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Global Electronic Aspirin Market