
 Pharmaceutical Quality Control Market | 2026-2036
Pharmaceutical Quality Control Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Quality Control Market Outlook
A shortage of trained analytical chemists is unwinding capacity expansion timelines at multiple QC service providers. Thermo Fisher Scientific leverages its chromatography and mass spectrometry portfolio to dominate high-complexity bioanalytical testing. Sartorius AG anchors European demand through bioprocess analytics integration with its filtration and cell-culture platforms. Charles River Laboratories International Inc. competes on endotoxin and microbial detection breadth across contract manufacturing networks.
Pharmaceutical quality control encompasses the analytical and procedural systems used to verify identity, purity, potency, and safety of drug substances and products, employing techniques such as high-performance liquid chromatography with UV or mass detection at sensitivity thresholds of parts per billion. Its primary commercial purpose is to ensure batch-to-batch consistency and regulatory compliance before product release to healthcare markets. Chromatography systems capture the largest equipment spend as legacy HPLC platforms upgrade to ultra-high-performance variants for faster impurity profiling. Bioassays represent the fastest-expanding technology segment, driven by cell-based potency assays for monoclonal antibodies and gene therapies where physicochemical methods cannot predict biological activity. Active Pharmaceutical Ingredients command disproportionate QC investment due to complex synthetic pathways and tightening ICH Q3D elemental impurity limits.
FDA enforces current Good Manufacturing Practice through its Center for Drug Evaluation and Research, mandating validated analytical methods and documented out-of-specification investigations that directly shape instrument procurement cycles. EMA's ICH Q2(R2) guideline revision on analytical procedure validation, alongside REACH chemical safety obligations for reference standards, creates dual compliance burdens for multinational sponsors. ISO 17025 accreditation requirements from national accreditation bodies further filter laboratory eligibility for commercial testing contracts. Stakeholders must weigh capital deployment between in-house analytical infrastructure and outsourced contract laboratory partnerships as regulatory scrutiny intensifies on data integrity and computerized system validation.
Market Dynamics
FDA's updated guidance on analytical procedures validation is compressing instrument replacement cycles as biologics manufacturers race to deploy continuous process verification platforms before batch release deadlines.
Growth Catalysts
- Biologics sterility assurance mandates:Gene therapy and monoclonal antibody manufacturers in Germany are expanding QC budgets to meet national pharmaceutical regulator batch release protocols for exported medicines.
- ICH Q2(R2) guideline revision:EMA's updated analytical procedure validation framework is forcing multinational sponsors to upgrade legacy HPLC platforms to ultra-high-performance variants.
- Elemental impurity limits:Tightening ICH Q3D standards for active pharmaceutical ingredients are driving investment in inductively coupled plasma mass spectrometry across synthetic drug manufacturing networks.
Market Restraints
- Trained analytical chemist shortage:Capacity expansion timelines at contract QC service providers are unwinding as universities fail to graduate sufficient chromatography and mass spectrometry specialists.
- Reference standard supply concentration:REACH chemical safety obligations for certified reference materials have consolidated European supply chains around a handful of accredited producers.
- Dual compliance burdens:Multinational sponsors face overlapping FDA current Good Manufacturing Practice and EMA ICH Q2(R2) requirements that duplicate validation documentation without mutual recognition.
Strategic Opportunities
- Cell-based potency assay expansion:Bioassays for monoclonal antibodies and gene therapies represent white space where physicochemical methods cannot predict biological activity.
- ISO 17025 accreditation arbitrage:National accreditation body requirements are filtering laboratory eligibility for commercial testing contracts, creating tiered service differentiation.
- Bioprocess analytics integration:Convergence of filtration platforms with real-time chromatography monitoring is opening embedded QC service models for cell-culture manufacturing.
Industry Challenges
- Data integrity validation:Regulatory scrutiny on computerized system validation is extending software qualification timelines for electronic laboratory notebook deployments.
- Capital deployment timing:Stakeholders must weigh in-house analytical infrastructure against outsourced contract laboratory partnerships amid uncertain batch volume forecasts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Quality Control Market |
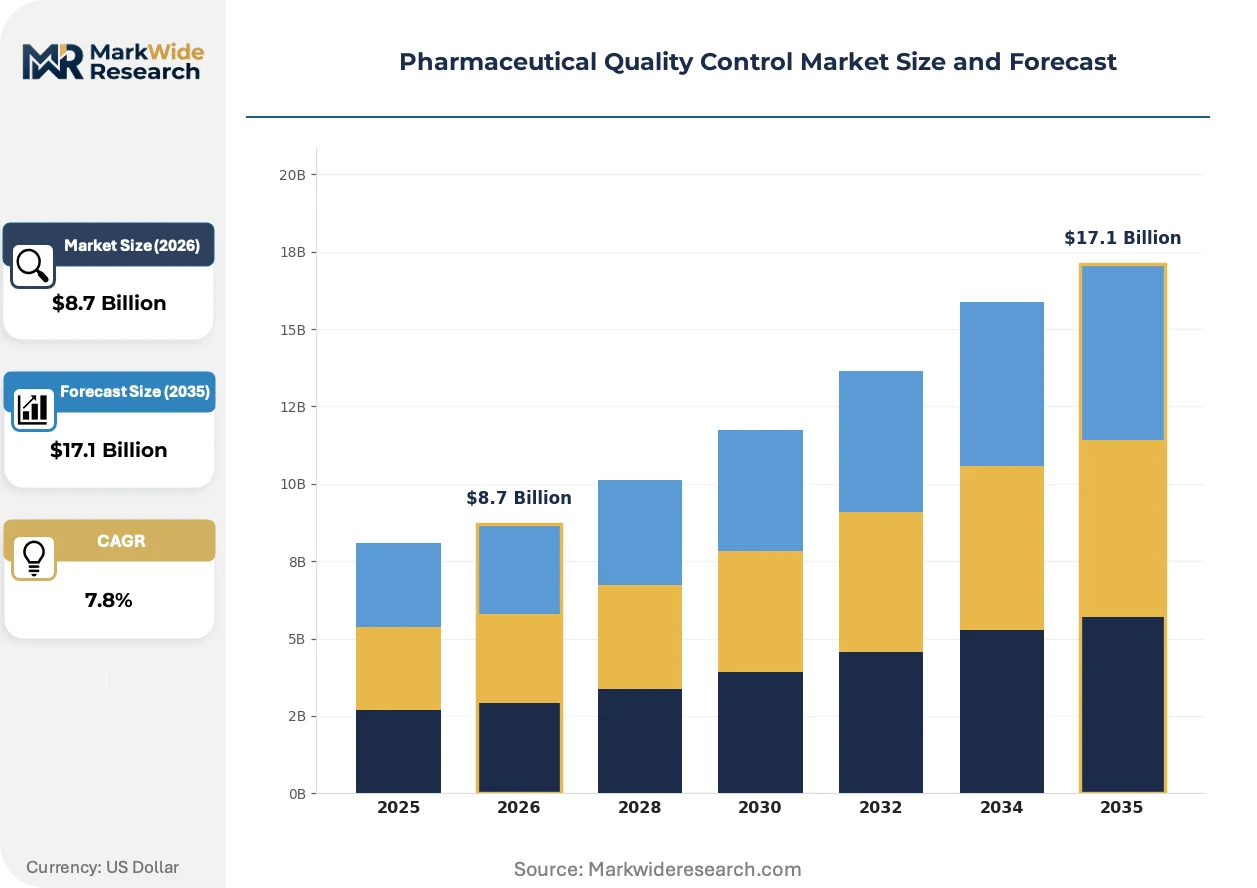
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
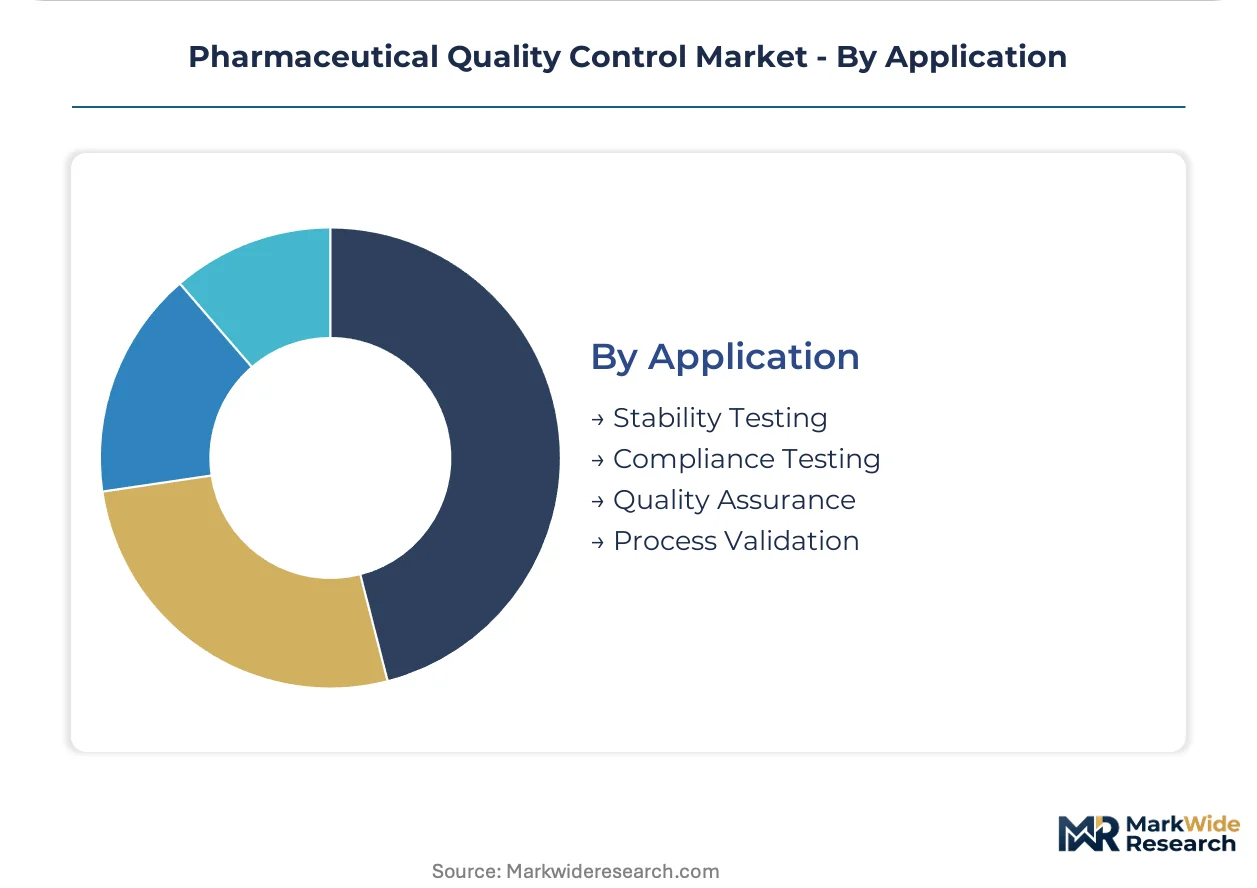
| Segmentation | Product Type: Raw Materials, Finished Products, Intermediate Products, Active Pharmaceutical Ingredients Technology: Chromatography, Spectroscopy, Microbiological Testing, Bioassays End User: Pharmaceutical Manufacturers, Contract Laboratories, Research Institutions, Quality Control Labs Application: Stability Testing, Compliance Testing, Quality Assurance, Process Validation |
| Companies Covered | Mettler Toledo, SGS S.A., Thermo Fisher Scientific Inc., Charles River Laboratories International Inc., Sartorius AG, Danaher Corporation, Waters Corporation, PerkinElmer Inc., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Quality Control Market Strategic Shifts
Continuous manufacturing adoption is dissolving the boundary between production and quality control, forcing instrument vendors to embed analytical sensors directly within bioreactor and purification skid architectures.
Ultra-high-performance liquid chromatography is fragmenting the installed base of legacy HPLC systems as biologics manufacturers pursue faster impurity profiling cycles. Contract development and manufacturing organizations are replacing ten-year-old platforms at twice historical replacement rates. This technology diffusion is compressing service differentiation among regional testing laboratories that cannot justify capital outlays for sub-two-minute separations.
EMA's ICH Q2(R2) guideline revision on analytical procedure validation is mandating enhanced robustness testing and measurement uncertainty quantification. Multinational sponsors must now submit extended method lifecycle documentation alongside marketing applications. Active pharmaceutical ingredient manufacturers with complex synthetic pathways face the steepest compliance ramps as they validate orthogonal techniques for elemental impurity detection.
Service unbundling is separating instrument hardware procurement from method development and regulatory submission support. Biologics manufacturers are contracting specialized consultancies for FDA pre-submission meetings while sourcing chromatography columns and mass spectrometers through distribution channels. This bifurcation is most visible in Germany, where national pharmaceutical regulator enforcement of strict batch release protocols has created a premium tier for integrated validation-to-release service providers.
Pharmaceutical Quality Control Market Segmentation
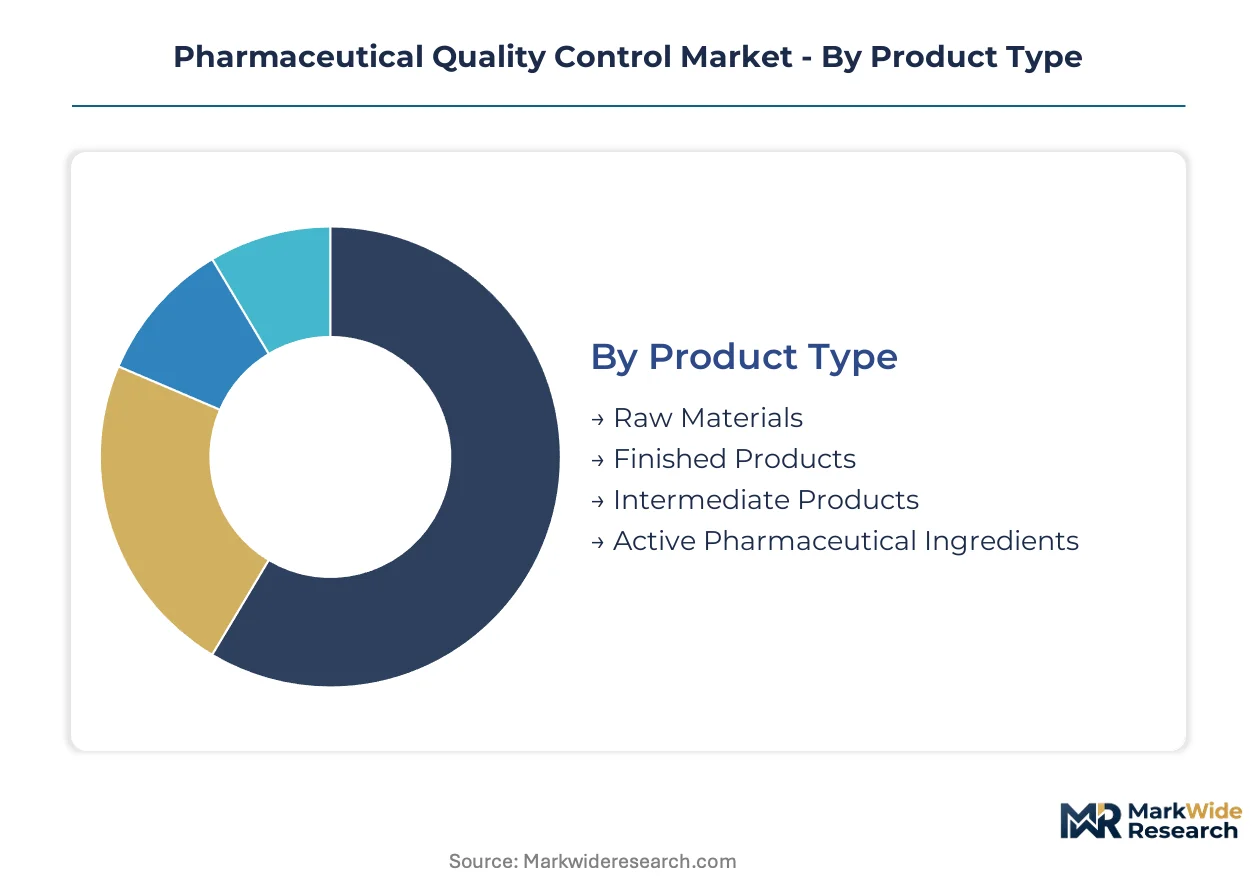
Segmentation in pharmaceutical quality control reveals how capital flows diverge across testing modalities and customer archetypes. Biologics manufacturers prioritize potency verification over legacy chemical assays, while contract laboratories compete on accreditation breadth rather than instrument scale alone.
Product Type:
Margin pools concentrate in high-complexity synthetic pathways where elemental impurity detection demands specialized inductively coupled plasma infrastructure.
- Active Pharmaceutical Ingredients:Complex multi-step synthesis routes require orthogonal validation techniques for ICH Q3D compliance. German manufacturers with export obligations to the FDA face the steepest documentation burdens, driving captive QC investment over outsourced alternatives.
- Finished Products:Batch release protocols for sterile injectables mandate endotoxin and particulate testing at sensitivity thresholds approaching single-digit colony-forming units. Contract manufacturing networks in Switzerland cluster release testing capacity near fill-finish operations to compress logistics timelines.
- Intermediate Products:In-process controls for continuous manufacturing lines embed chromatography sensors within purification skids.
- Raw Materials:Excipient qualification relies on compendial testing against pharmacopeial monographs.
Active Pharmaceutical Ingredients holds installed capacity. Finished Products is rotating up the share rankings.
Technology:
Capital deployment intensity tracks method development complexity, with cell-based assays commanding premium service pricing over physicochemical alternatives.
- Bioassays:Cell-based potency assays for monoclonal antibodies and gene therapies operate where mass spectrometry cannot predict biological activity. CDSCO in India is expanding bioassay requirements for biosimilar registration, pulling method development capacity toward Hyderabad and Bangalore clusters.
- Chromatography:Ultra-high-performance liquid chromatography platforms achieve sub-two-minute impurity separations that legacy HPLC cannot match. Thermo Fisher Scientific and Waters Corporation dominate high-complexity bioanalytical testing through column chemistry intellectual property and mass detector integration.
- Spectroscopy:Inductively coupled plasma mass spectrometry addresses tightening elemental impurity thresholds.
- Microbiological Testing:Rapid microbial detection systems displace growth-based compendial methods.
Chromatography holds installed capacity. Bioassays is climbing the fastest.
End User:
Procurement authority splits between manufacturing organizations with captive laboratories and third-party providers competing on ISO 17025 accreditation portfolios.
- Pharmaceutical Manufacturers:In-house analytical infrastructure anchors sterility assurance for gene therapy production where batch failure costs exceed millions per lot. Sartorius AG integrates bioprocess analytics with filtration platforms to capture embedded QC service contracts.
- Contract Laboratories:Charles River Laboratories International Inc. competes on endotoxin and microbial detection breadth across distributed manufacturing networks. REACH chemical safety obligations for certified reference materials have consolidated European supply chains, advantaging accredited providers with captive standard production.
- Research Institutions:Academic method development supports regulatory submission packages.
- Quality Control Labs:Standalone facilities serve regional generic manufacturers.
Pharmaceutical Manufacturers holds installed capacity. Contract Laboratories is rotating up the share rankings.
Application:
Regulatory filing timelines determine spending priority, with process validation documentation commanding resources ahead of routine release testing.
- Process Validation:Continuous process verification platforms require real-time chromatography monitoring embedded within bioreactor architectures. FDA's updated guidance on analytical procedures validation is compressing instrument replacement cycles as sponsors race to deploy platforms before batch release deadlines.
- Compliance Testing:EMA's ICH Q2(R2) guideline revision mandates enhanced robustness testing and measurement uncertainty quantification for marketing applications. Multinational sponsors must submit extended method lifecycle documentation, extending software qualification timelines for electronic laboratory notebook deployments.
- Stability Testing:ICH Q1A(R2) climatic zone studies dictate protocol design.
- Quality Assurance:Out-of-specification investigations shape instrument procurement cycles.
Compliance Testing holds installed capacity. Process Validation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Center for Drug Evaluation and Research anchors North American demand through current Good Manufacturing Practice enforcement that mandates validated analytical methods and documented out-of-specification investigations. Biologics manufacturers in Germany face the strictest batch release protocols for exported medicines, while CDSCO in India expands bioassay requirements for biosimilar registration.
United States
Gene therapy manufacturers in Massachusetts and California are expanding captive QC laboratories where batch failure costs exceed millions per lot. FDA's updated guidance on analytical procedures validation compresses instrument replacement cycles as sponsors race to deploy continuous process verification platforms. The Greater Boston cluster anchors high-complexity bioanalytical testing capacity for monoclonal antibody development.
Germany
The national pharmaceutical regulator enforces REACH chemical safety obligations for certified reference materials that have consolidated European supply chains. Bavarian and North Rhine-Westphalian manufacturing networks cluster release testing capacity near fill-finish operations to compress logistics timelines. Sartorius AG integrates bioprocess analytics with filtration platforms to capture embedded QC service contracts across synthetic drug manufacturing.
India
CDSCO is expanding bioassay requirements for biosimilar registration, pulling method development capacity toward Hyderabad and Bangalore clusters. Contract QC service providers in these cities face unwinding capacity expansion timelines as universities fail to graduate sufficient chromatography and mass spectrometry specialists. The Telangana-Karnataka corridor concentrates rapid microbial detection system deployment for sterile injectable exports.
Switzerland
Swissmedic enforces dual compliance burdens alongside EMA's ICH Q2(R2) guideline revision that duplicates validation documentation without mutual recognition. Basel and Zurich host contract manufacturing networks that compete on ISO 17025 accreditation portfolios for commercial testing contracts. The country's reference standard producers advantage accredited providers with captive certified material production under REACH obligations.
China
NMPA alignment with ICH Q3D elemental impurity limits drives investment in inductively coupled plasma mass spectrometry across synthetic drug manufacturing networks. The Yangtze River Delta and Pearl River Delta concentrate ultra-high-performance liquid chromatography platform deployment as legacy HPLC systems fragment. Shanghai and Suzhou biologics manufacturers prioritize cell-based potency assay development where physicochemical methods cannot predict biological activity.
Pharmaceutical Quality Control Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the pharmaceutical quality control market. Chromatography and mass spectrometry portfolios dominate high-complexity bioanalytical testing, while bioprocess analytics integration captures embedded service contracts. Strategic archetypes include diversified laboratory conglomerates, precision instrument manufacturers, and contract research organizations with microbial detection breadth. Competitive moves concentrate on portfolio diversification through analytical technology licensing and geographic expansion into regulatory-stringent jurisdictions.
Among diversified laboratory conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation occupy positions spanning chromatography systems through contract testing services. Waters Corporation exemplifies the precision instrument archetype through column chemistry intellectual property. Charles River Laboratories International Inc. represents contract research organization positioning with endotoxin and microbial detection capabilities. Sartorius AG anchors European demand through bioprocess analytics integration with filtration platforms. Merck KGaA sits within the reference materials tier supplying certified standards under REACH obligations.
| Leading Market Players |
|---|
| Mettler Toledo |
| SGS S.A. |
| Thermo Fisher Scientific Inc. |
| Charles River Laboratories International Inc. |
| Sartorius AG |
| Danaher Corporation |
| Waters Corporation |
| PerkinElmer Inc. |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Chromatography platform scale economies at Thermo Fisher Scientific and Waters Corporation anchor price floors for high-complexity bioanalytical testing, while smaller regional laboratories absorb margin compression from ultra-high-performance liquid chromatography upgrade cycles. German biologics manufacturers with FDA export obligations pay premiums for integrated validation-to-release service bundles that compress batch release timelines.
Pricing Analysis
Geographic price spreads separate German integrated service providers from Indian contract laboratories, with three-tier pricing structure across premium, standard, and economy levels driven by ISO 17025 accreditation grade and after-sales method development support. Pricing pressure stems from REACH chemical safety obligations consolidating European reference standard supply chains around accredited producers with captive certified material production. Small molecule generic manufacturers in India exhibit highest price sensitivity, while gene therapy sponsors in Massachusetts and California prioritize batch failure risk mitigation over unit cost.
Supply Chain Analysis
Extended lead times for inductively coupled plasma mass spectrometry systems from Germany and the United States constrain capacity expansion at synthetic drug manufacturers facing ICH Q3D compliance deadlines. Critical component dependencies include high-purity chromatography columns from Waters Corporation, certified reference materials under REACH obligations, and mass detector subassemblies sourced from specialized optics suppliers. Single-source vulnerability concentrates in European reference standard production, with distribution running through accredited contract laboratory networks clustered near fill-finish operations in Switzerland and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous manufacturing adoption represents an early-cycle expansion story, with real-time chromatography sensor deployment dissolving boundaries between production and quality control across biologics manufacturing networks.
For Market Incumbents: Fortify chromatography and mass spectrometry portfolio dominance through column chemistry intellectual property licensing, while embedding bioprocess analytics within filtration platforms to capture embedded QC service contracts. Capacity addition in Hyderabad and Bangalore clusters addresses CDSCO bioassay expansion for biosimilar registration. Vertical integration into certified reference material production under REACH obligations defends margin position against supply chain consolidation.
For New Entrants and Emerging Players: Cell-based potency assay capacity gaps in the Yangtze River Delta and Pearl River Delta offer white space where physicochemical methods cannot predict monoclonal antibody biological activity. ISO 17025 accreditation arbitrage creates tiered service differentiation for regional generic manufacturers underserved by multinational contract laboratory networks. Go-to-market positioning through specialized consultancies for FDA pre-submission meetings while sourcing hardware through distribution channels reduces capital intensity.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision instrument manufacturers with orthogonal validation technique portfolios spanning elemental impurity detection and microbial testing breadth. Long-term viability hinges on continuous process verification platform deployment across synthetic drug and biologics manufacturing networks. Acquisition targets include contract research organizations with endotoxin detection capabilities and distributed manufacturing network coverage. Watch FDA analytical procedures validation guidance updates as inflection indicators for instrument replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA ICH Q2(R2) compliance accelerates ultra-high-performance liquid chromatography platform upgrades at multinational sponsors. |
| Manufacturing Scale-Up | Continuous process verification deployment embeds analytical sensors within bioreactor architectures for real-time release testing. |
| Backward Integration | Captive certified reference material production under REACH obligations insulates against European supply chain consolidation. |
| Strategic Partnership | Sartorius AG bioprocess analytics integration with filtration platforms captures embedded QC service contracts. |
| Geographic Expansion | Hyderabad and Bangalore cluster investment addresses CDSCO bioassay requirements for biosimilar registration. |
Study Parameters
A standing panel of regulatory affairs leads, QC laboratory directors, chromatography platform engineers, and contract manufacturing procurement managers provided ongoing calibration across primary interview programs. Secondary validation drew from FDA Center for Drug Evaluation and Research guidance documents, EMA ICH Q2(R2) guideline revisions, ISO 17025 accreditation body records, and REACH chemical safety obligation filings. Bottom-up instrumentation demand modeling and top-down pharmaceutical R&D expenditure analysis were triangulated for consistency.
External benchmark checks against instrument vendor shipment disclosures and contract laboratory capacity announcements validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user procurement authority, and application workflow, with regional regulatory cluster differentiation for multinational sponsor compliance burdens. CAGRs were derived from instrument replacement cycle compression rates and bioassay capacity expansion timelines, incorporating ICH Q3D elemental impurity limit adoption curves and continuous manufacturing penetration assumptions.
Underlying assumptions cover sterility assurance mandate enforcement consistency, with deviation risk concentrated in trained analytical chemist supply constraints and reference standard production consolidation. Forecasts reflect these conditions without claiming predictive certainty. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Retrovirus Testing Market
Testing Services
Global ADME Toxicology Testing Market
Testing Services
Warfarin Sensitivity Testing Market
Testing Services
Pharmaceutical Analytical Testing Market
Testing Services
Biological Indicator Vials Market
Testing Services
Gastrointestinal Testing Panels Market
Testing Services
Global CA 125 Test Market
Testing Services
Global Thyroid Function Test Market
Testing Services
Americas Sterility Testing Market
Testing Services
Pancreatic Stone Protein Testing Market
Testing Services
Breath Biopsy Testing Market
Testing Services
Global Creatinine Assay Kits Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Global Coagulation Testing Market
Testing Services
Apoptosis Testing Market
Testing Services
Large Molecule Bioanalytical Testing Services Market