
 Global HIV Self Test Kits Market | 2026-2036
Global HIV Self Test Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Global HIV Self Test Kits Market Foresight
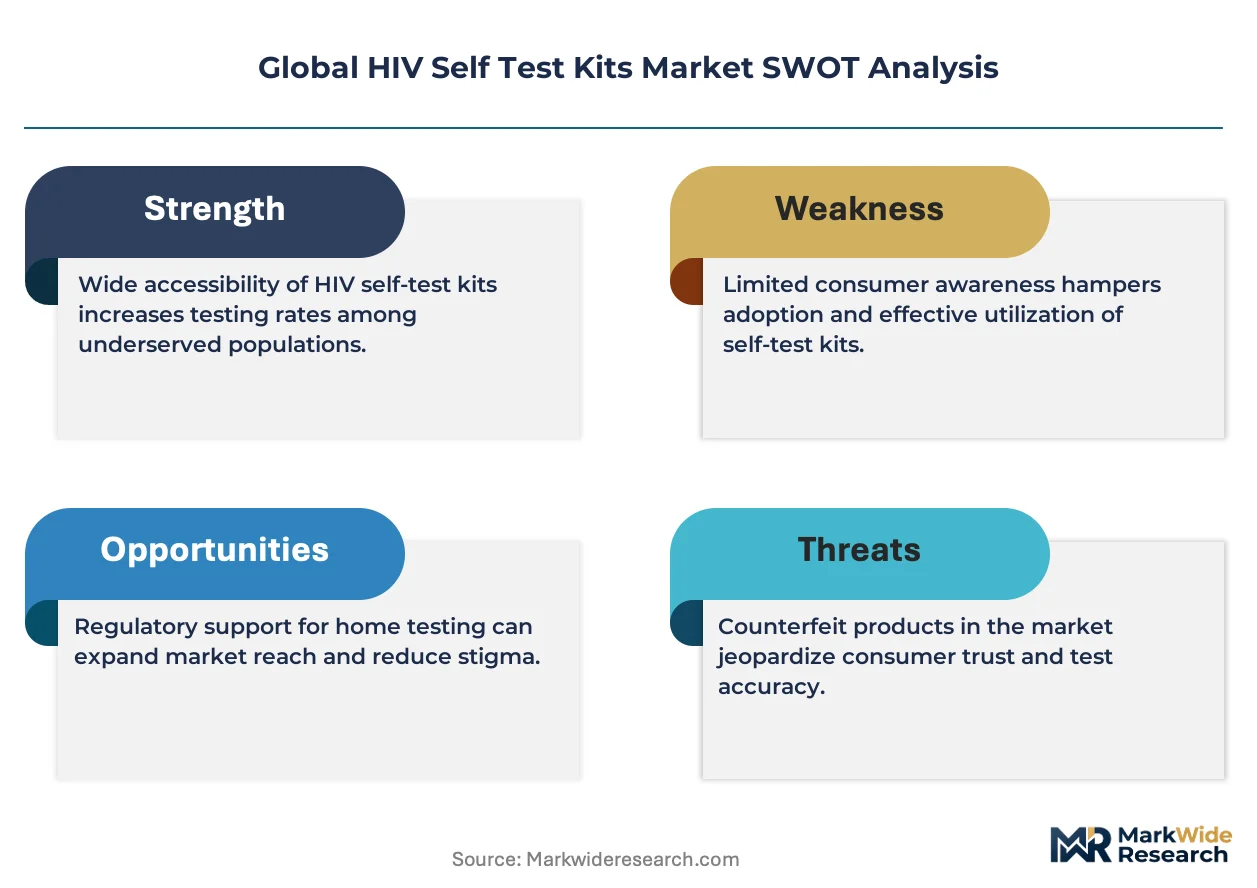
Community health programs is redrawing procurement patterns across the HIV self-testing landscape. Atomo Diagnostics leverages vertical integration to control assay production costs across oral fluid platforms. Abbott Laboratories anchors geographic dominance through WHO-prequalified rapid test portfolios distributed in African markets. OraSure Technologies differentiates via channel control of pharmacy and convenience store networks in North American jurisdictions.
HIV self test kits are diagnostic devices designed for unsupervised detection of HIV antibodies or antigens in oral fluid or whole blood specimens, typically delivering results within 20 minutes through lateral flow immunochromatography. These products serve public health objectives by expanding screening access beyond clinical settings into decentralized community and household environments. Blood-based tests currently occupy the largest margin pool due to superior sensitivity profiles, while oral fluid assays represent the fastest-growing category driven by user preference for non-invasive specimen collection. Among distribution channels, online retailers are gaining structural share as direct-to-consumer platforms bypass traditional pharmacy gatekeepers in regulated markets.
WHO prequalification, FDA emergency use authorization, and EMA CE-IVD marking collectively determine market access trajectories for HIV self test manufacturers seeking multi-jurisdictional commercialization. REACH compliance and EU MDR technical documentation requirements impose additional conformity burdens on European market entrants. Stakeholders must monitor evolving national self-testing policy frameworks and prequalification roster updates to align manufacturing investments with reimbursable procurement channels.
Market Dynamics
Community-based procurement in sub-Saharan Africa is consolidating demand around WHO-prequalified oral fluid platforms, compressing registration timelines and reshaping manufacturer investment priorities toward decentralized distribution infrastructure.
Growth Catalysts
- WHO prequalification pathway:Streamlined assessment protocols accelerate product registration for blood-based and oral fluid assays entering public sector tenders in Kenya and Nigeria.
- Sub-Saharan pharmacy networks:Government outreach programs are embedding self-test distribution into existing retail channels, expanding screening access beyond clinical facilities.
- Lateral flow immunochromatography:Mature manufacturing processes reduce per-unit production costs while maintaining 20-minute result delivery standards.
Market Restraints
- Reagent supply concentration:Nitrocellulose membrane and conjugate pad sourcing clusters in East Asian contract manufacturers, exposing procurement to single-region disruption.
- Cold chain requirements:Blood-based assays with antibody stability constraints demand controlled storage logistics that inflate last-mile distribution costs in tropical climates.
- False positive liability frameworks:National medical device regulations in several jurisdictions impose post-market surveillance burdens that deter market entry by mid-scale manufacturers.
Strategic Opportunities
- Indonesia and Philippines:National HIV programs in these archipelago nations lack established self-testing frameworks, creating first-mover positioning for assay developers with heat-stable formulations.
- Digital result verification:Integration of Bluetooth-enabled readers with smartphone applications enables remote counseling linkages and captures epidemiological data for health ministries.
- EU MDR technical documentation:Early compliance with European medical device regulation creates CE-IVD marking advantages for manufacturers targeting eventual WHO prequalification alignment.
Industry Challenges
- Biostatistician and regulatory affairs talent:Clinical validation study design and dossier preparation require specialized expertise that concentrates in established diagnostic hubs.
- Multi-jurisdictional certification timelines:Parallel FDA emergency use authorization, WHO prequalification, and national registration processes extend time-to-revenue by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HIV Self Test Kits Market |
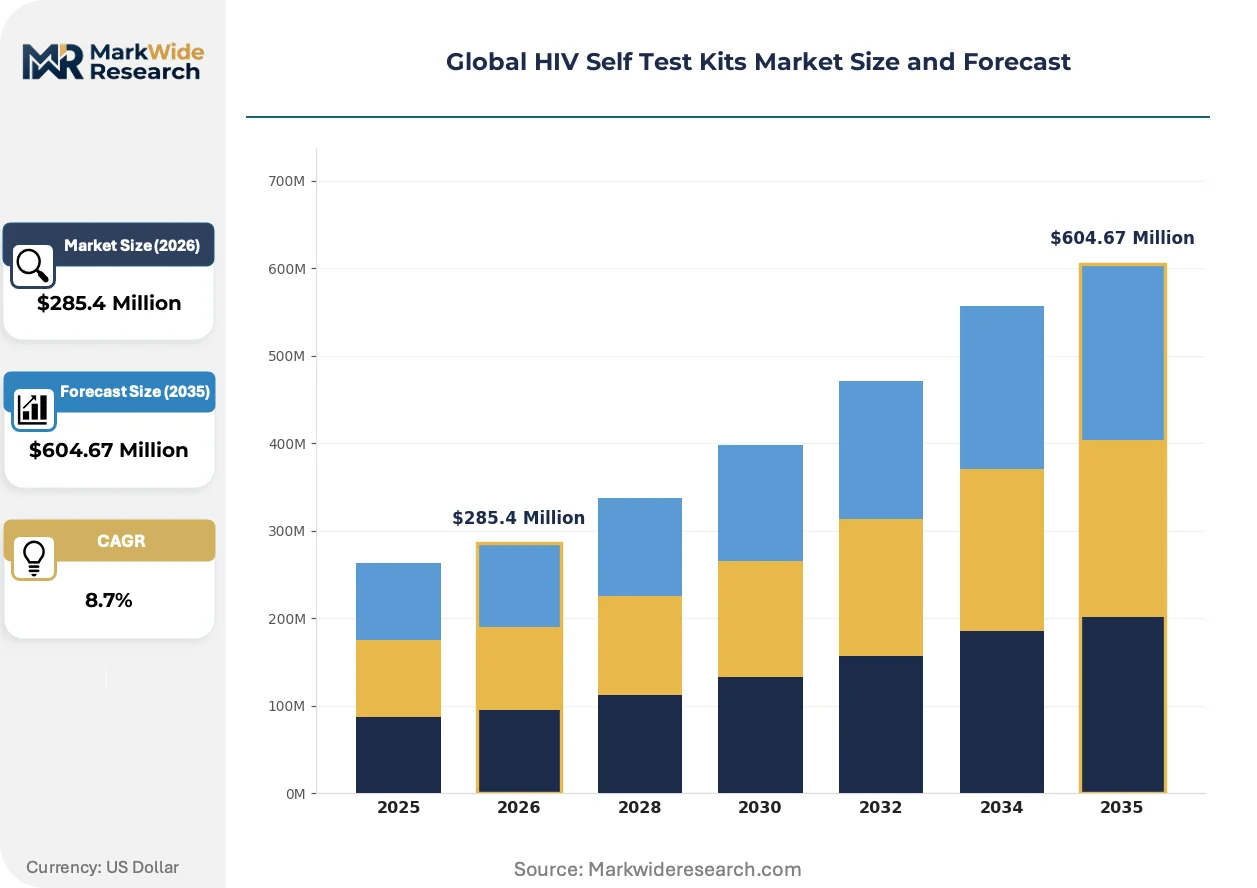
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Fluid Test, Blood-Based Test, Combo Test, Rapid Test Application: Home Testing, Community Testing, Mobile Clinics, Outreach Programs End User: Individual Consumers, Non-Governmental Organizations, Public Health Agencies, Private Clinics Distribution Channel: Pharmacies, Online Retailers, Hospitals, Convenience Stores |
| Companies Covered | Atomo Diagnostics, Roche, OraSure Technologies, SD Biosensor, Bio-Rad Laboratories, Abbott Laboratories, Chembio Diagnostics, Biosynex, bioLytical Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HIV Self Test Kits Market Shifts & Advancements
Diagnostic hardware is converging with connectivity infrastructure and user-centered design principles, compressing the gap between specimen collection and care linkage while enabling real-time public health surveillance.
Microfluidic cartridge technology is miniaturizing sample processing volumes while preserving analytical sensitivity. Public health agencies in South Africa and Brazil are piloting these platforms for dual HIV-syphilis detection. The form factor reduction is enabling integration into wallet-sized packaging that reduces shipping costs and disposal volume.
EMA MDR technical documentation requirements are mandating post-market clinical follow-up systems for all CE-IVD marked self-tests. Manufacturers must establish vigilance procedures capturing adverse event reports across 27 member states. Blood-based assay developers with existing quality management systems are adapting faster than oral fluid specialists with legacy ISO 13485 frameworks.
Direct-to-consumer platforms are bypassing pharmacy gatekeepers in regulated North American and European markets. Subscription models offering quarterly test delivery are displacing one-time purchases through retail channels. This channel migration concentrates most visibly in urban jurisdictions with established telehealth prescribing pathways and same-day courier coverage.
Global HIV Self Test Kits Market Segmentation
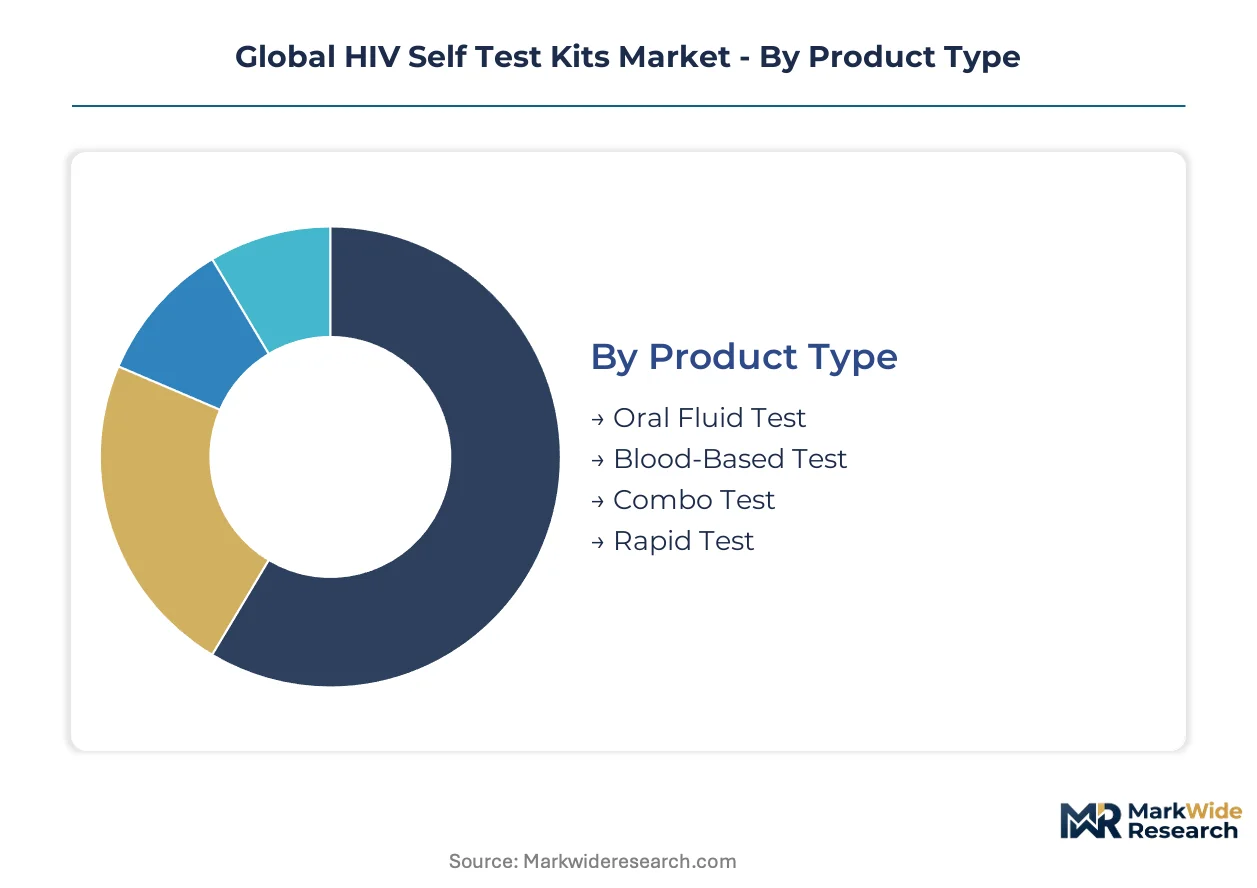
Segmentation in HIV self-testing reveals how procurement authority, specimen preference, and channel access intersect to determine manufacturer strategy. Each dimension carries distinct margin profiles, regulatory pathways, and geographic concentration patterns that shape competitive positioning.
Product Type:
Channel-mix varies sharply across assay formats, with blood-based platforms dominating institutional tenders and oral fluid variants capturing direct-to-consumer pharmacy sales.
- Oral Fluid Test:Non-invasive specimen collection via buccal swab or saliva strip eliminates lancet disposal requirements. Demand concentrates in Kenyan and Nigerian pharmacy networks where community health workers prioritize user acceptance over sensitivity margins.
- Blood-Based Test:Fingerstick whole blood specimens deliver superior analytical sensitivity for early seroconversion detection. Public Health Agencies in South Africa procure these exclusively for outreach programs targeting high-prevalence districts.
- Combo Test:Dual HIV-syphilis detection capability leverages shared lateral flow infrastructure. Brazilian pilot programs are validating these for integrated STI screening.
- Rapid Test:Generic 20-minute immunochromatography format with interchangeable specimen compatibility. Convenience stores in North American urban markets stock these as impulse-purchase items.
By volume, Blood-Based Test leads. By growth pace, Oral Fluid Test is expanding most quickly.
Application:
Cost tier separation runs deepest here, with home testing commanding retail premiums and outreach programs optimizing for per-test procurement economics.
- Home Testing:Unsupervised use in residential settings demands foolproof specimen collection and unambiguous result interpretation. FDA emergency use authorization pathways shape product design for US direct-to-consumer channels.
- Community Testing:Peer-distributor models in sub-Saharan Africa embed testing into social networks. Non-Governmental Organizations in Kenya deploy oral fluid platforms through trained lay counselors.
- Mobile Clinics:Vehicle-based screening requires heat-stable reagents and minimal cold chain dependence. Indonesian archipelago programs are piloting these for island-hopping health teams.
- Outreach Programs:Targeted screening of key populations leverages existing social infrastructure. Nigerian public health agencies integrate these into barber shop and transport hub networks.
By procurement volume, Community Testing leads. By margin expansion, Home Testing is gaining share fastest.
End User:
Customer type determines pricing architecture, with individual consumers facing retail markups and public sector tenders compressing per-unit economics.
- Individual Consumers:Private purchase decisions prioritize discretion and convenience over bulk pricing. Online retailers capture this demand through subscription models in telehealth-enabled US markets.
- Non-Governmental Organizations:Grant-funded procurement concentrates on WHO-prequalified products with established cold chain logistics. These buyers dominate East African distribution.
- Public Health Agencies:National program tenders specify sensitivity thresholds and heat stability requirements. South Africa's Department of Health sets regional benchmark specifications.
- Private Clinics:Fee-for-service screening seeks rapid turnaround with minimal staff training. These outlets in São Paulo and Mexico City prefer combo test formats.
By contract value, Public Health Agencies lead. By procurement flexibility, Individual Consumers are climbing the fastest.
Distribution Channel:
Supply concentration differs markedly, with pharmacy networks requiring established regulatory dossiers and online channels demanding digital marketing infrastructure.
- Pharmacies:Professional counter staff provide counseling linkages and adverse event reporting. Kenya's retail pharmacy association accredits outlets for government-subsidized distribution.
- Online Retailers:Direct-to-consumer platforms bypass geographic constraints but face last-mile temperature control challenges. Same-day courier coverage in US metropolitan areas enables this channel's expansion.
- Hospitals:Institutional procurement integrates with laboratory quality management systems. These buyers in South Africa and Brazil prefer blood-based assays with documented clinical sensitivity.
- Convenience Stores:Impulse-purchase placement requires minimal staff intervention and clear result interpretation. North American chains in urban jurisdictions are testing this placement for oral fluid products.
By transaction volume, Pharmacies lead. By channel shift velocity, Online Retailers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports nitrocellulose membranes and conjugate pads to assay assemblers in Kenya and Nigeria. German manufacturers ship lateral flow readers to Brazilian pilot programs. These trade corridors concentrate procurement authority in specific national tenders.
South Africa
The Department of Health procures blood-based assays exclusively for high-prevalence districts in KwaZulu-Natal and Gauteng. WHO prequalification standards govern all public sector tenders. Cape Town hosts cold chain logistics hubs serving outreach programs across the Western Cape.
Kenya
Pharmacy networks in Nairobi and Mombasa embed oral fluid distribution into retail channels. The national pharmaceutical regulator accredits outlets for government-subsidized sales. Kisumu serves as the Lake Victoria basin distribution node for peer-counselor models.
Nigeria
Barber shops and transport hubs in Lagos and Kano integrate testing into social infrastructure. Federal Ministry of Health guidelines specify heat-stability thresholds for archipelago distribution. Port Harcourt anchors the Niger Delta supply corridor for mobile clinic programs.
United States
FDA emergency use authorization pathways shape direct-to-consumer product design for telehealth-enabled markets. Subscription models concentrate in metropolitan areas with same-day courier coverage. Boston and San Francisco host regulatory affairs consultancies serving prequalification dossier preparation.
Brazil
ANVISA oversees pilot programs validating dual HIV-syphilis combo tests in São Paulo and Rio de Janeiro. Public health agencies seek integrated STI screening platforms. The Campinas corridor clusters diagnostic manufacturing for Latin American export.
Global HIV Self Test Kits Market Competitive Landscape
Player mix skews toward vertically integrated diagnostic conglomerates with WHO-prequalified portfolios. Market structure concentrates around three multinational manufacturers controlling African tender access. Strategic archetypes include: lateral flow platform specialists, blood-based assay developers with cold chain expertise, and oral fluid innovators prioritizing user acceptance. Dominant competitive moves involve geographic expansion into Southeast Asian archipelago markets and portfolio diversification toward combo test formats.
Among the vertically integrated tier, Atomo Diagnostics and Abbott Laboratories exemplify archetypes controlling production costs and geographic dominance respectively. OraSure Technologies occupies a position representing channel control specialists. Roche and SD Biosensor sit within the scale-driven conglomerate category. Bio-Rad Laboratories and Chembio Diagnostics anchor the mid-cap specialist segment. Biosynex and bioLytical Laboratories represent regional European players seeking CE-IVD marking alignment with eventual WHO prequalification pathways.
| Leading Market Players |
|---|
| Atomo Diagnostics |
| Roche |
| OraSure Technologies |
| SD Biosensor |
| Bio-Rad Laboratories |
| Abbott Laboratories |
| Chembio Diagnostics |
| Biosynex |
| bioLytical Laboratories |
| Others |
Supply & Pricing Matrix
Capacity utilization at lateral flow membrane factories in China and South Korea shapes both supply concentration and price floors for assay assemblers in Kenya and Nigeria. WHO prequalification requirements compress margins for oral fluid platforms while blood-based tests command premium positioning through cold chain logistics bundling.
Pricing Analysis
Next-generation Bluetooth-enabled readers carry 40-60% premiums over basic immunochromatography strips, while legacy oral fluid platforms face commoditization in East African tenders. Three-tier pricing structure across WHO-prequalified premium, CE-IVD standard, and unregistered economy levels separates procurement channels. Cost compression in the economy tier is intensifying because Kenyan pharmacy networks now pool demand for volume discounts. Public health agencies in South Africa exhibit lowest price sensitivity due to grant-funded budgets, while individual consumers in North American direct-to-consumer channels prioritize convenience over unit economics.
Supply Chain Analysis
China and South Korea anchor nitrocellulose membrane and conjugate pad production for assay assemblers worldwide. Lateral flow manufacturing draws from East Asian chemical processing clusters for antibody conjugates and plastic molding for cartridge housings. Single-source vulnerability concentrates in nitrocellulose substrate supply, where three contract manufacturers serve 70% of global demand. Distribution runs through cold chain logistics hubs in Cape Town and Nairobi before last-mile deployment to pharmacy networks and outreach programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where WHO prequalification creates switching costs that entrench incumbents. Network effects concentrate in prequalified manufacturer rosters that public health agencies reference for multi-year tenders.
For Market Incumbents: Fortify position by deepening backward integration into nitrocellulose membrane production to offset East Asian supply concentration. Expand capacity in heat-stable formulation R&D before Indonesian and Philippine national programs finalize procurement specifications. Defend against oral fluid commoditization through digital result verification platform lock-in. For New Entrants and Emerging Players: Post-test counseling service gaps in Southeast Asian archipelago markets offer white-space entry points where incumbents under-serve remote island populations. Target mobile clinic distribution in Indonesia with heat-stable blood-based assays bypassing cold chain requirements. Pursue ANVISA pilot program partnerships in Brazil as a WHO prequalification stepping stone. For Investors and Strategic Acquirers: Regional European players with CE-IVD marking and pending WHO prequalification dossiers represent the most defensible acquisition archetype for African market access. Long-term viability hinges on portfolio diversification toward dual HIV-syphilis combo formats as integrated STI screening expands. Watch for Indonesian national HIV program framework announcements as inflection indicators for heat-stable formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Accelerates tender eligibility in Kenyan and Nigerian public sector procurement cycles. |
| Heat-Stable Formulation Development | Enables archipelago distribution for Indonesian mobile clinic programs without cold chain. |
| Digital Companion Platform Launch | Captures epidemiological data for health ministries while locking in result verification workflows. |
| Dual HIV-Syphilis Combo Test CE Marking | Positions manufacturers for Brazilian ANVISA integrated STI screening pilot expansions. |
| Direct-to-Consumer Channel Expansion | Bypasses pharmacy gatekeepers in US telehealth-enabled metropolitan markets. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with diagnostic industry stakeholders and secondary validation across regulatory and trade databases. Interview sources included regulatory affairs directors at lateral flow manufacturers, procurement managers at Kenyan pharmacy network associations, and biomedical engineers at South African cold chain logistics providers. Secondary sources encompassed WHO prequalification rosters, FDA emergency use authorization filings, and East Asian customs export records for nitrocellulose substrates. Bottom-up demand modeling from national HIV program tenders triangulated against top-down market sizing from manufacturer capacity disclosures.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type, application setting, end-user archetype, and distribution channel. CAGRs derived from segment-level growth rate convergence analysis incorporating procurement volume trends, regulatory approval timelines, and channel migration patterns. Heat stability specifications and digital connectivity integration served as technology-generation forecast inputs.
Forecasts assume regulatory continuity in WHO prequalification standards and FDA emergency use authorization pathways; material policy shifts would require re-modeling. Specific risks include nitrocellulose supply disruption from East Asian manufacturing concentration and archipelago distribution framework delays in Indonesia. Recalibration cycles align with material shifts in national self-testing policy adoptions and prequalification roster updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Testing and Analysis Services Market
Testing Services
Global Rapid Test Market
Testing Services
South America Endotoxin and Pyrogen Testing Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
Asia Pacific Pregnancy and Ovulation Testing Market
Testing Services
Home DNA Testing Market
Testing Services
Tablet Hardness Testers Market
Testing Services
Arbovirus Testing Market
Testing Services
Global Efficacy Testing Market
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
Thailand Point-Of-Care Testing (POCT) Market
Testing Services
Large Molecule Bioanalytical Testing Services Market
Testing Services
Vials Leak Testing Market
Testing Services
Calprotectin Testing Market
Testing Services
Global Terminal Sterilization Services Market
Testing Services
CRO Mass Spectroscopy Services Market