
 US Cannabis Market | 2026-2036
US Cannabis Market Size, Share, and Industry Trends Forecast 2026-2036
US Cannabis Market Intelligence
Pharmaceutical-grade extraction standards is bifurcating the competitive landscape between craft operators and scaled producers. Curaleaf leverages multi-state vertical integration to sustain pricing power across dispensary networks. Green Thumb Industries anchors market presence through manufacturing scale in Illinois and Pennsylvania. Trulieve Cannabis dominates Florida's medical channel with controlled retail density.
Cannabis comprises dried flower, concentrated extracts, and infused formulations containing cannabinoids such as THC and CBD, typically processed through CO2 or hydrocarbon extraction methods for therapeutic and recreational consumption. Flower retains volume leadership across retail channels despite margin compression from commoditization. Concentrates capture premium pricing through potency standardization and solventless processing innovation. Edibles accelerate within recreational segments as precise dosing technology improves batch consistency.
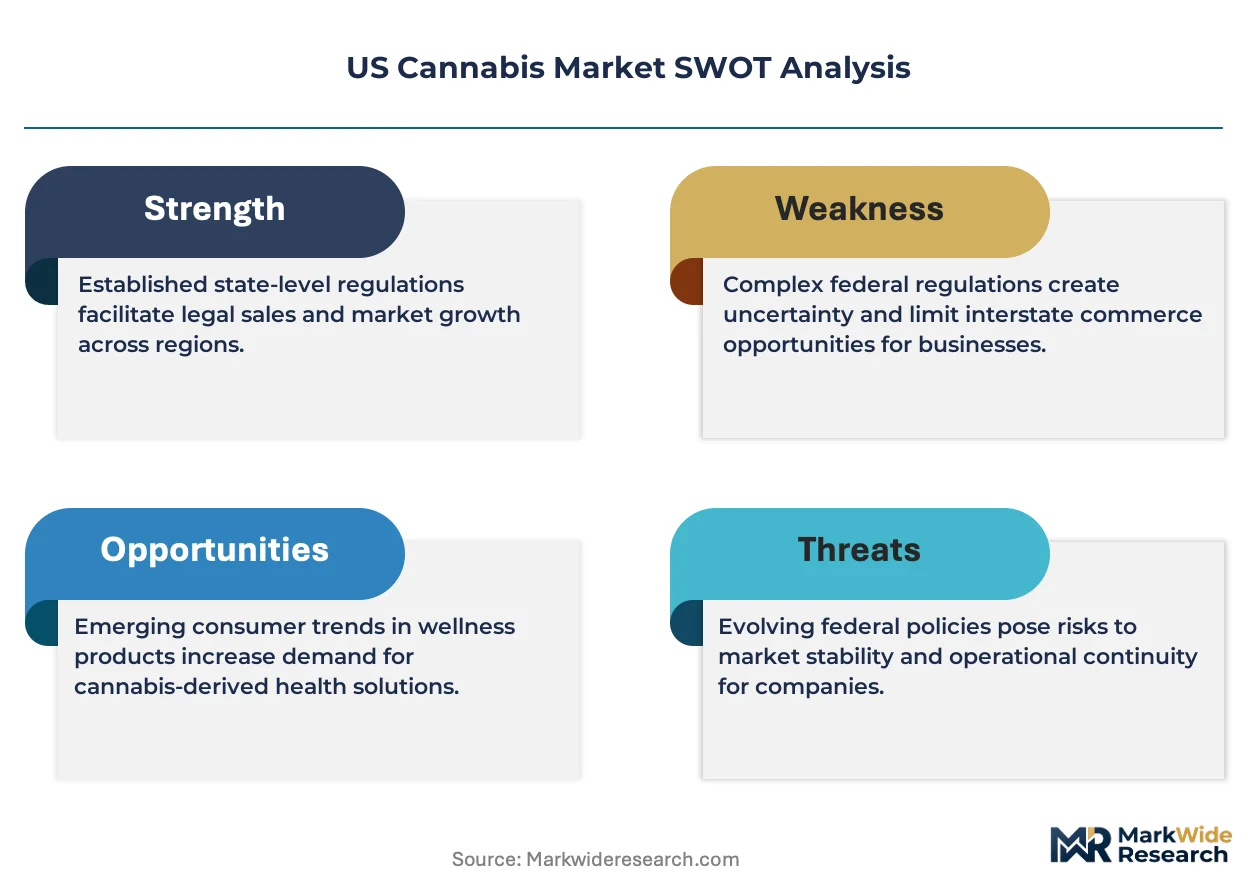
FDA maintains oversight of cannabis-derived pharmaceuticals and dietary supplement claims, while state-level regulators including Colorado's Marijuana Enforcement Division and California's Department of Cannabis Control govern product testing, packaging, and track-and-trace compliance. The Internal Revenue Code Section 280E constrains deductibility of ordinary business expenses, forcing operators to optimize cost structures against punitive effective tax rates. Stakeholders must monitor federal rescheduling proceedings and corresponding shifts in banking access, as these determinations will recalibrate capital formation and interstate commerce feasibility.
Market Dynamics
The US cannabis market operates under a structural tension between state-level legalization momentum and federal prohibition, with Internal Revenue Code Section 280E imposing punitive tax burdens that force operators to optimize cost structures while awaiting potential rescheduling proceedings that would recalibrate capital formation and interstate commerce feasibility.
Growth Catalysts
- State Program Expansion:Medical qualifying conditions broaden across state programs, expanding the patient base and normalizing therapeutic use.
- SAFE Banking Act Progression:Federal legislative movement toward banking access reduces cash-intensive operations and attracts institutional capital.
- Solventless Extraction Methods:Rosin and ice-water hash technologies capture premium consumer segments demanding chemical-free processing.
Market Restraints
- Section 280E Tax Burden:Disallowance of ordinary business expense deductions forces effective tax rates exceeding 70% for compliant operators.
- Input Cost Volatility:Energy-intensive indoor cultivation faces electricity price spikes, compressing margins in legacy markets.
- Interstate Commerce Barriers:Federal prohibition prevents cross-border supply optimization, trapping inventory within state boundaries.
Strategic Opportunities
- Federal Rescheduling Pathway:DEA review of cannabis scheduling could unlock pharmaceutical research partnerships and normalized banking.
- Minor Cannabinoid Formulations:CBN, CBG, and THCV isolates target sleep, inflammation, and appetite modulation applications.
- Beverage Channel Penetration:Cannabis-infused drinks leverage existing alcohol distribution infrastructure in recreational states.
Industry Challenges
- Track-and-Trace System Integration:State-mandated seed-to-sale platforms like Metrc require significant IT investment and operational retraining.
- Quality Control Talent Scarcity:Analytical chemistry and pharmaceutical manufacturing expertise remains concentrated in traditional industries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cannabis Market |
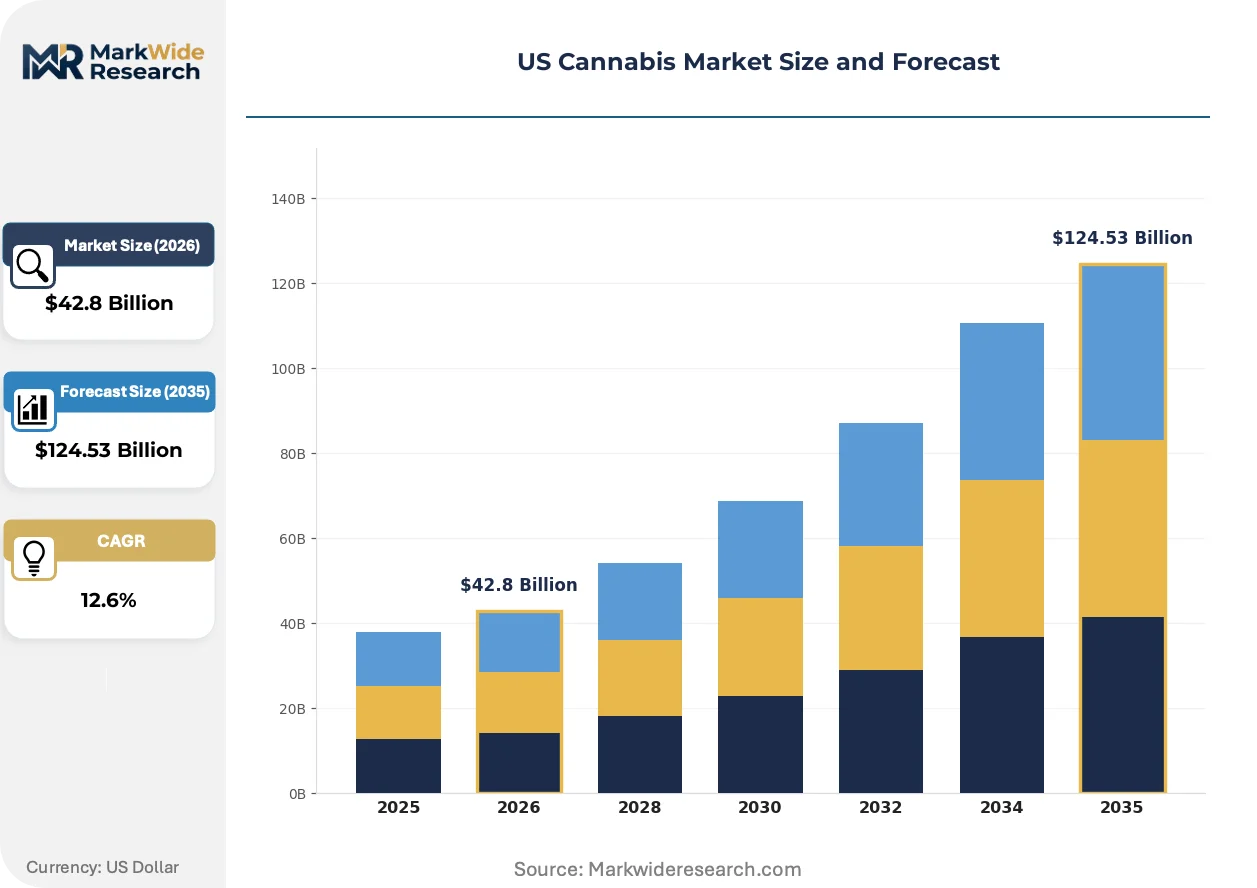
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $124.53 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flower, Edibles, Concentrates, Topicals End User: Medical Patients, Recreational Users, Dispensaries, Manufacturers Distribution Channel: Retail Stores, Online, Dispensary Networks, Wholesale Form: Dry, Liquid, Capsules, Infused Products |
| Companies Covered | Curaleaf, Green Thumb Industries, Trulieve Cannabis, Cresco Labs, Tilray Brands, Verano Holdings, Ascend Wellness Holdings, Ayr Wellness, Jushi Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cannabis Market Strategic Shifts & Innovations
Technological differentiation and regulatory adaptation are compressing competitive timelines across the US cannabis sector, with operators racing to establish defensible positions before federal policy clarity arrives.
Live resin and solventless extraction methods are bifurcating the concentrates category, with craft operators commanding premium pricing through small-batch hydrocarbon processing while scaled producers deploy automated hydrocarbon systems for volume. Medical patients and connoisseur recreational consumers drive adoption of full-spectrum products that preserve native terpene profiles. This technology is bifurcating market structure between heritage craft positioning and pharmaceutical-grade standardization.
FDA guidance on cannabidiol enforcement priorities continues evolving, creating compliance uncertainty for ingestible products while allowing topical and cosmetic applications greater operational latitude. Manufacturers face reformulation costs and label revision cycles as the agency clarifies permissible health claims. The dietary supplement channel responds most aggressively, with brands pivoting toward cosmetic positioning to avoid pharmaceutical classification.
Direct-to-consumer delivery platforms are displacing traditional dispensary foot traffic in mature recreational markets, with mobile ordering and curbside pickup becoming baseline expectations. Urban consumers in California and Colorado demonstrate strongest platform loyalty, while suburban and rural markets retain higher in-store browsing rates. Dispensary operators invest in proprietary apps and loyalty programs to defend against third-party marketplace intermediation.
US Cannabis Market Segmentation
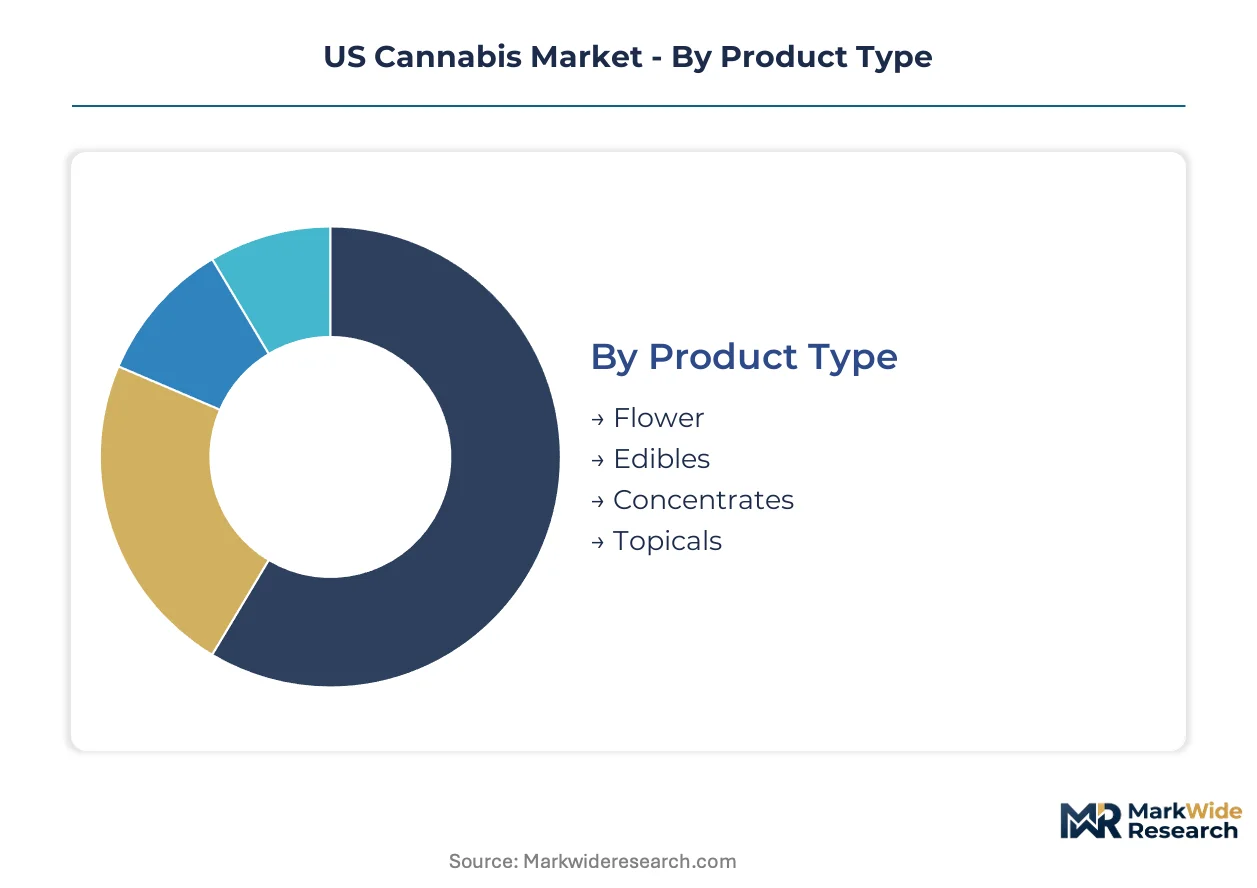
Segmentation in the US cannabis market determines regulatory compliance pathways, margin structures, and capital intensity requirements. Product form factors and distribution channels face divergent state-level restrictions that reshape competitive positioning.
Product Type:
Flower moves through dispensary retail and wholesale channels, while concentrates and edibles penetrate both medical and recreational segments with distinct packaging mandates.
- Flower:Dried cannabis bud containing full cannabinoid and terpene profiles in smokable form. California and Colorado dispensaries move the highest volumes, though commoditization compresses margins as cultivation scales.
- Edibles:Cannabis-infused food and beverage products requiring precise homogenization for consistent dosing. Illinois and Michigan recreational markets show strongest demand concentration as precise dosing technology improves batch consistency.
- Concentrates:Extracted cannabinoid products including oils, waxes, and shatter processed through CO2 or hydrocarbon methods.
- Topicals:Non-psychoactive creams, balms, and transdermal patches applied externally for localized relief.
Flower dominates installed base. Concentrates is where expansion concentrates.
End User:
Cost tier stratification separates premium therapeutic formulations from mass-market recreational products, with medical patients absorbing higher per-unit prices for consistent dosing.
- Medical Patients:State-registered consumers with qualifying conditions accessing tax-advantaged products through physician recommendations. Florida and Pennsylvania patient registries expand fastest as qualifying condition lists broaden under state health department oversight.
- Recreational Users:Adult consumers purchasing from licensed retailers in legalization states without medical documentation. Colorado and Washington mature markets exhibit stable per-capita consumption patterns.
- Dispensaries:Licensed retail operators serving as primary customer touchpoints for both medical and adult-use segments.
- Manufacturers:Processing facilities converting raw biomass into extracted and infused products for downstream distribution.
Medical Patients anchor revenue per transaction. Recreational Users is where volume scaling concentrates.
Distribution Channel:
Geographic concentration in coastal and Great Lakes states shapes channel viability, with urban density supporting delivery platforms and suburban markets sustaining brick-and-mortar footprints.
- Retail Stores:Physical dispensary locations with controlled entry and on-site product consultation. California's Department of Cannabis Control mandates specific security and zoning requirements that concentrate storefronts in Los Angeles and San Francisco metro corridors.
- Online:Digital ordering platforms with in-store pickup or delivery fulfillment. Colorado's Marijuana Enforcement Division permits delivery expansion into suburban Denver and Boulder counties where platform loyalty runs highest.
- Dispensary Networks:Multi-location retail chains operating under unified branding and inventory management.
- Wholesale:Business-to-business transactions between cultivators, processors, and retail operators within state boundaries.
Retail Stores dominate transaction volume. Online is where channel innovation concentrates.
Form:
Application method determines shelf stability, onset timing, and dosing precision requirements that segment manufacturing equipment investments and quality control protocols.
- Dry:Unprocessed or minimally cured plant material in traditional smokable or vaporizable formats. Arizona and Nevada desert climates support sun-cured processing that commands premium positioning in connoisseur segments.
- Liquid:Oil-based formulations including tinctures, vape cartridges, and beverage emulsions. Massachusetts and New York regulators impose specific testing thresholds for residual solvents and heavy metals.
- Capsules:Encapsulated cannabinoid oils providing precise milligram dosing for medical adherence.
- Infused Products:Cannabis incorporated into non-cannabis base materials including foods, beverages, and personal care items.
Dry dominates cultivation output. Liquid is where formulation R&D concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian licensed producers supply biomass and extracted inputs to US state-legal markets through limited cross-border partnerships, while domestic cultivation concentrates in coastal and mountain states with established regulatory frameworks.
California
Adult-use dispensary density and craft cultivation heritage drive premium flower demand in Los Angeles and Bay Area corridors. The Department of Cannabis Control enforces track-and-trace compliance through Metrc integration. Emerald Triangle legacy operators transition into licensed frameworks, preserving solventless extraction expertise.
Colorado
Mature per-capita consumption patterns and tourism-related purchasing stabilize revenue across Denver and Boulder retail networks. The Marijuana Enforcement Division regulates testing protocols for residual solvents and potency variance. Pueblo County outdoor cultivation leverages high-altitude sun exposure for cost-competitive biomass.
Florida
Medical patient registry expansion and vertical licensing requirements concentrate market power among integrated operators. The Department of Health Office of Medical Marijuana Use oversees dispensary cap allocations and product form approvals. Trulieve Cannabis anchors retail density across Tampa and Orlando metro corridors.
Illinois
Social equity licensing rounds and limited retail permits create scarcity value for storefront operations in Chicago and Cook County. The Department of Financial and Professional Regulation governs craft grower and infuser tier classifications. Green Thumb Industries maintains manufacturing scale through Rock Island processing infrastructure.
Pennsylvania
Medical program growth and restrictive licensing sustain pricing premiums across Philadelphia and Pittsburgh patient bases. The Department of Health Medical Marijuana Program mandates vertical integration for permit holders. Scranton and Allentown industrial zones host processing facilities serving mid-Atlantic distribution.
US Cannabis Market Key Industry Players
Listed leaders compete with private specialists across capital access and geographic footprint dimensions, producing a tiered structure where multi-state operators with public listings attract institutional investment while private holdings retain operational flexibility. Three archetypes dominate: vertically integrated retail-heavy networks, manufacturing-centric processors, and single-state density specialists. Competitive moves concentrate on license acquisition in limited-permit states and backward integration into cultivation capacity.
Within the multi-state operator tier, Curaleaf and Green Thumb Industries exemplify scale-driven positioning across fragmented state markets, while Trulieve Cannabis occupies a single-state density specialist role. These entities represent contrasting strategic bets on geographic diversification versus regulatory depth.
| Leading Market Players |
|---|
| Curaleaf |
| Green Thumb Industries |
| Trulieve Cannabis |
| Cresco Labs |
| Tilray Brands |
| Verano Holdings |
| Ascend Wellness Holdings |
| Ayr Wellness |
| Jushi Holdings |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between multi-state operators and legacy cultivators lock in biomass supply visibility while insulating processors from spot-market volatility in California and Colorado. These contracts tether pricing power to controlled retail density, forcing craft operators toward premium positioning or scale-driven cost absorption.
Pricing Analysis
Solventless extraction methods command generational premiums over hydrocarbon-processed concentrates, with rosin and ice-water hash products capturing connoisseur segments while automated CO2 systems drive standard-tier commoditization. Price differentiation hinges on terpene preservation certification and batch-specific potency variance rather than brand equity alone. Cost compression in flower tiers intensifies as desert-climate outdoor cultivation scales in Arizona and Nevada. Medical patients in Florida and Pennsylvania exhibit lowest price sensitivity due to tax-advantaged access and physician-directed purchasing.
Supply Chain Analysis
California and Colorado anchor domestic cultivation output, while Canadian licensed producers supply limited extracted inputs through restricted cross-border partnerships. The supply chain draws from energy-intensive indoor grow operations, pharmaceutical-grade extraction equipment, and state-mandated track-and-trace packaging. Single-source vulnerability concentrates in electricity-dependent cultivation zones facing grid instability risks. Distribution runs through vertically integrated dispensary networks and direct-to-consumer delivery platforms in urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dispensary network consolidation across Illinois and Pennsylvania shifts procurement leverage toward retail buyers, fragmenting supplier pricing power as limited-license states expand permit allocations.
For Market Incumbents: Shield margin structures by securing controlled retail density in Florida and Pennsylvania before social equity licensing dilutes permit scarcity. Backward integration into solventless extraction capacity captures premium-tier pricing power as hydrocarbon commoditization accelerates. Counter the threat of direct-to-consumer platform intermediation through proprietary app development and loyalty program lock-in.
For New Entrants and Emerging Players: Anchor in beverage formulation partnerships that leverage existing alcohol distribution infrastructure in Colorado and Michigan recreational markets. White-space concentration sits in minor cannabinoid isolates targeting sleep and inflammation applications underserved by THC-dominant incumbents. Pursue craft positioning through small-batch live resin production with native terpene preservation as the core go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward single-state density specialists with vertical integration depth rather than geographically diversified operators facing 280E tax drag across multiple jurisdictions. Long-term viability favors entities with captive cultivation and controlled retail footprints in limited-license states. Monitor DEA rescheduling proceedings as the primary inflection signal for normalized banking access and interstate commerce feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Social Equity Licensing Pursuit | Illinois and New York programs unlock scarce retail permits for qualified applicants. |
| Solventless Extraction Scale-Up | Rosin and ice-water hash capacity commands premium positioning against hydrocarbon commoditization. |
| Direct-to-Consumer Platform Launch | Proprietary delivery apps defend against third-party marketplace intermediation in California urban corridors. |
| Minor Cannabinoid Formulation Development | CBN and CBG isolates target medical patient segments with specific therapeutic applications. |
| Multi-State Retail Network Expansion | Geographic diversification hedges against single-state regulatory reversal risks under federal prohibition. |
Research Approach
Two parallel data streams informed the analysis: structured conversations with cannabis cultivation directors, dispensary operations managers, state regulatory compliance officers, and extraction facility engineers; alongside secondary validation through state department of cannabis control filings, FDA guidance documents, Metrc track-and-trace system disclosures, and IRS Section 280E enforcement records. Bottom-up and top-down triangulation cross-referenced individual operator cost structures against aggregate state-level market sizing.
Across the projection horizon, the analytical framework modeled segmentation across product form, end-user category, distribution channel, and state regulatory cluster. CAGRs were derived from patient registry growth trajectories, per-capita consumption stabilization patterns in mature markets, and federal policy scenario weighting. Forecast inputs incorporated electricity price volatility for indoor cultivation and evolving FDA enforcement priorities on ingestible cannabidiol products.
Underlying assumptions cover state program expansion continuity, banking access legislative progression, and rescheduling timeline uncertainty, with deviation risk concentrated in federal enforcement shifts and interstate commerce liberalization. Recalibration cycles align with material shifts in DEA scheduling determinations and corresponding capital formation access changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
US Cannabinoids Market
Cannabis/Marijuana
Europe Cannabidiol (CBD) Market
Cannabis/Marijuana
Missouri Legal Cannabis Market
Cannabis/Marijuana
Biometric Cannabis Storage Boxes Market
Cannabis/Marijuana
Marijuana Sensors Market
Cannabis/Marijuana
Legal Cannabis Market
Cannabis/Marijuana
Thailand Medical Cannabis Market
Cannabis/Marijuana
Europe CBD Oil Market
Cannabis/Marijuana
Electric Cannabis Grinders Market
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
Cannabis Pharmaceuticals Market
Cannabis/Marijuana
CBD Hemp Oil Market
Cannabis/Marijuana
Asia-Pacific CBD Patch Market
Cannabis/Marijuana
Medical Cannabis Market
Cannabis/Marijuana
Australia Medicinal Cannabis Testing Market