
 Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market | 2026-2036
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market Insights
Specialized optics manufacturers in Germany and Japan is realigning production priorities toward pharmaceutical-grade particle characterization systems. Malvern Panalytical leverages its long-standing laser diffraction heritage to dominate high-precision zeta potential workflows for gene therapy developers. HORIBA sustains competitive pressure through integrated dynamic light scattering platforms that span academic and industrial laboratories. Anton Paar anchors its position in European markets with compact, GMP-compliant instruments designed for continuous process monitoring.
Nanoparticle drug delivery size and zeta potential measurement instruments employ laser-based detection methods to quantify hydrodynamic diameter, typically from 0.3 nanometers to 10 micrometers, and electrophoretic mobility to derive surface charge critical for colloidal stability in injectable formulations. Dynamic light scattering systems occupy the largest installed base due to their speed and minimal sample requirements, though nanoparticle tracking analysis is gaining share where single-particle resolution matters for polydisperse biological samples. Pharmaceutical companies represent the most concentrated end-user segment, with contract research organizations representing the fastest-growing procurement channel as outsourcing of nanomedicine development accelerates.
FDA guidance on nanotechnology-enabled products shapes instrument validation protocols, while EMA's quality guidelines for liposomal and nanoparticle medicines drive European laboratories toward multi-technique platforms that combine size and zeta potential in single workflows. ISO 22412 for dynamic light scattering and ICH Q2(R1) validation standards further constrain acceptable measurement ranges and reproducibility thresholds for regulatory submissions. Stakeholders must monitor how evolving pharmacopeial chapters on subvisible particle enumeration begin to overlap with traditional nanoparticle sizing domains, potentially forcing platform consolidation decisions.
Market Dynamics
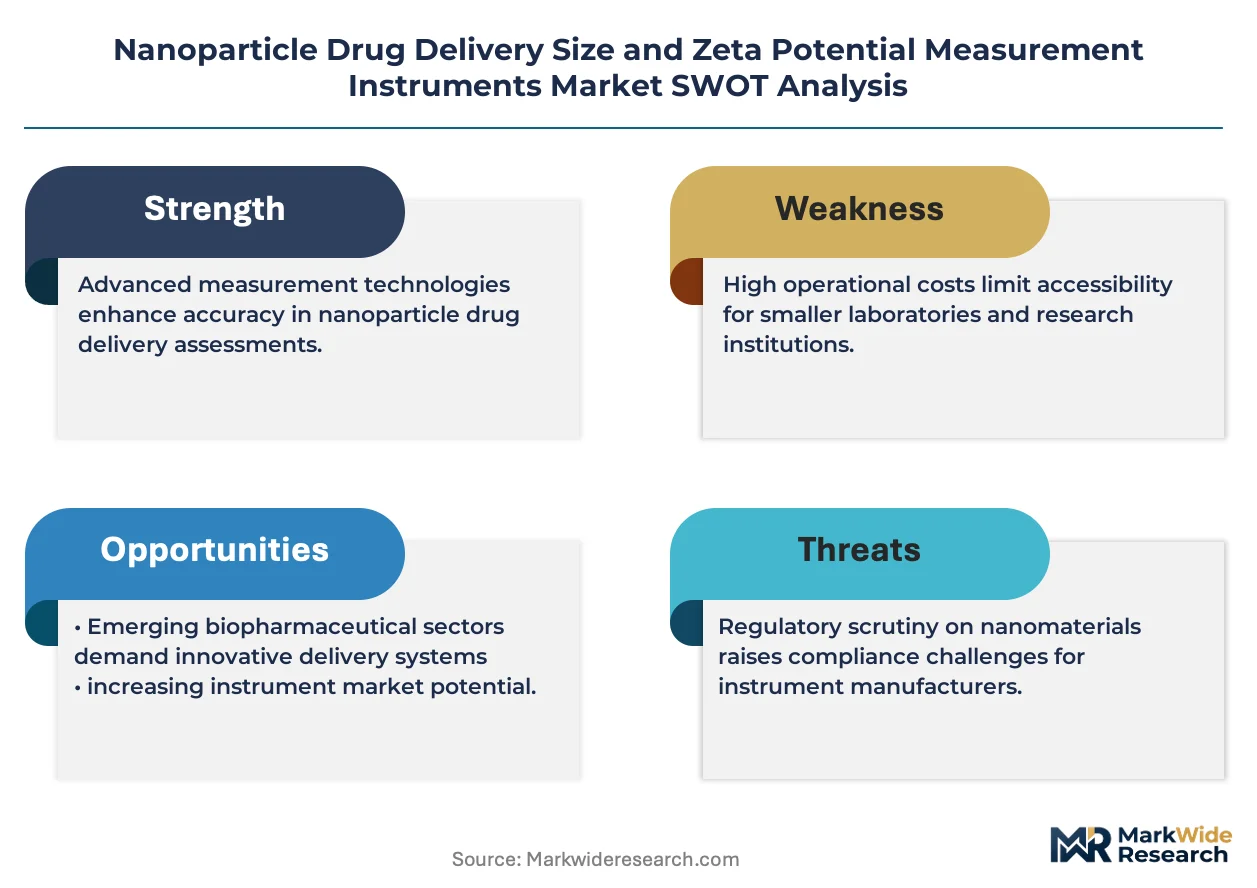
The FDA's tightening nanomaterial characterization requirements are forcing pharmaceutical manufacturers to upgrade from basic particle sizing to multi-parameter analytical platforms that simultaneously capture hydrodynamic diameter, zeta potential, and polydispersity indices for regulatory submissions.
Growth Catalysts
- EMA Quality Guidelines for Liposomal Medicines:European laboratories must now validate size distribution across multiple orthogonal techniques, driving replacement cycles for legacy single-method instruments.
- mRNA Vaccine Manufacturing Scale-Up:Lipid nanoparticle quality control workflows at commercial fill-finish facilities require continuous in-process monitoring systems with GMP-compliant data integrity.
- ISO 22412 Standardization:Harmonized dynamic light scattering protocols enable cross-laboratory reproducibility, reducing method transfer friction between contract research organizations and sponsor companies.
Market Restraints
- High-Purity Laser Component Costs:German and Japanese optics suppliers command premium pricing for stabilized diode lasers essential for sub-nanometer resolution, compressing instrument margins.
- Single-Vendor Reference Material Dependency:NIST-traceable polystyrene bead standards originate from concentrated US and UK sources, creating supply vulnerability for calibration-dependent workflows.
- Technique Incompatibility with Viscous Biologics:Dynamic light scattering suffers accuracy degradation in protein-concentrated formulations above 100 mg/mL, limiting addressable sample types.
Strategic Opportunities
- India's PLI Scheme for Pharmaceutical Manufacturing:Domestic formulation facilities expanding into nanomedicine require localized instrument service infrastructure currently served only by imports.
- Continuous Manufacturing Integration:Process analytical technology deployments at commercial biologics sites create demand for at-line zeta potential sensors with real-time release testing capability.
- Multi-Technique Platform Consolidation:Combined dynamic light scattering and nanoparticle tracking analysis systems reduce bench space requirements and operator training burden for resource-constrained quality control labs.
Industry Challenges
- Specialized Colloid Scientist Shortage:Interpretation of electrophoretic mobility data and polydispersity indices requires expertise scarce in routine pharmaceutical analytical departments.
- IQ/OQ/PQ Validation Timeline Compression:Instrument qualification protocols for GMP environments extend deployment cycles by 4-6 months, delaying revenue recognition for equipment vendors.
- Legacy LIMS Integration Complexity:Modern particle characterization software requires middleware development to connect with established laboratory information management systems at mature pharmaceutical sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market |
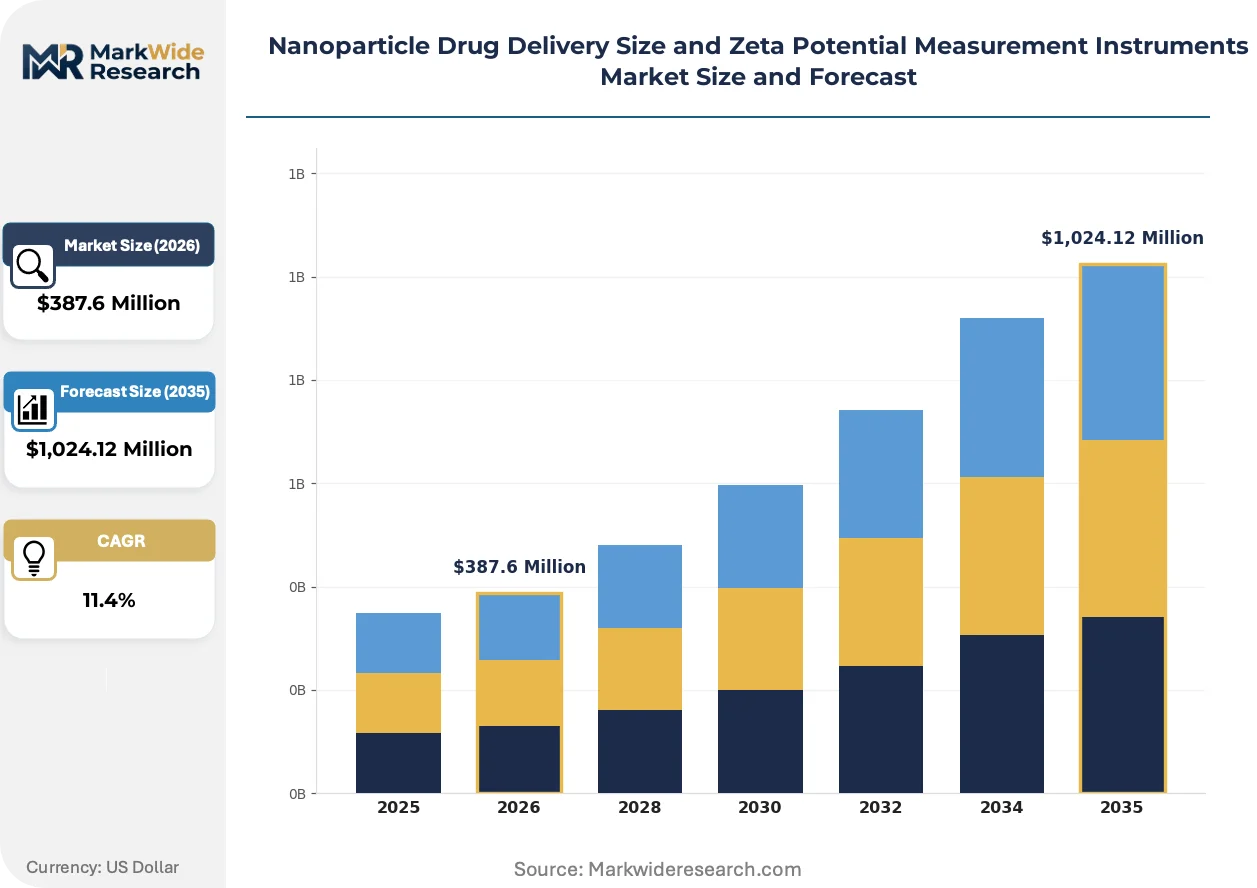
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dynamic Light Scattering, Electrophoretic Light Scattering, Nanoparticle Tracking Analysis, Centrifugal Sedimentation Technology: Laser Doppler Velocimetry, Photon Correlation Spectroscopy, Microelectrophoresis, Atomic Force Microscopy Application: Targeted Therapeutics, Gene Delivery, Vaccine Development, Anticancer Agents End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Laboratories |
| Companies Covered | Malvern Panalytical, HORIBA, Anton Paar, Shimadzu Corporation, Agilent Technologies, Bruker, Thermo Fisher Scientific, Beckman Coulter, Microtrac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market Trends and Innovations
Instrument architectures are fragmenting between high-throughput screening configurations for early-stage formulation development and dedicated at-line systems for commercial manufacturing control. This bifurcation is reshaping vendor R&D priorities and service model structures.
Multi-angle dynamic light scattering is modularizing into compact benchtop units that separate optical detection modules from sample handling stations. Gene therapy developers at US and European CDMOs are adopting these configurations to flexibly redeploy detection assets across multiple formulation suites. The architecture is compressing capital deployment timelines by enabling phased procurement where laboratories acquire core optics first and add automated sample changers later.
REACH registration requirements for nanomaterial-containing drug products are compelling European manufacturers to document particle stability across shelf-life conditions with validated analytical methods. The regulation is forcing instrument vendors to enhance software audit trails and electronic signature compliance. Pharmaceutical quality control departments in Germany and Switzerland are responding by consolidating vendor relationships to reduce validation documentation burden.
Service contract unbundling is accelerating as large pharmaceutical buyers separate hardware maintenance from application support and regulatory consulting. This pattern is most visible among mRNA vaccine manufacturers in the United States who now source metrology expertise from specialized analytical service firms rather than instrument OEMs. The disintermediation is compressing OEM service margins while expanding third-party validation consultancy markets.
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market Segmentation
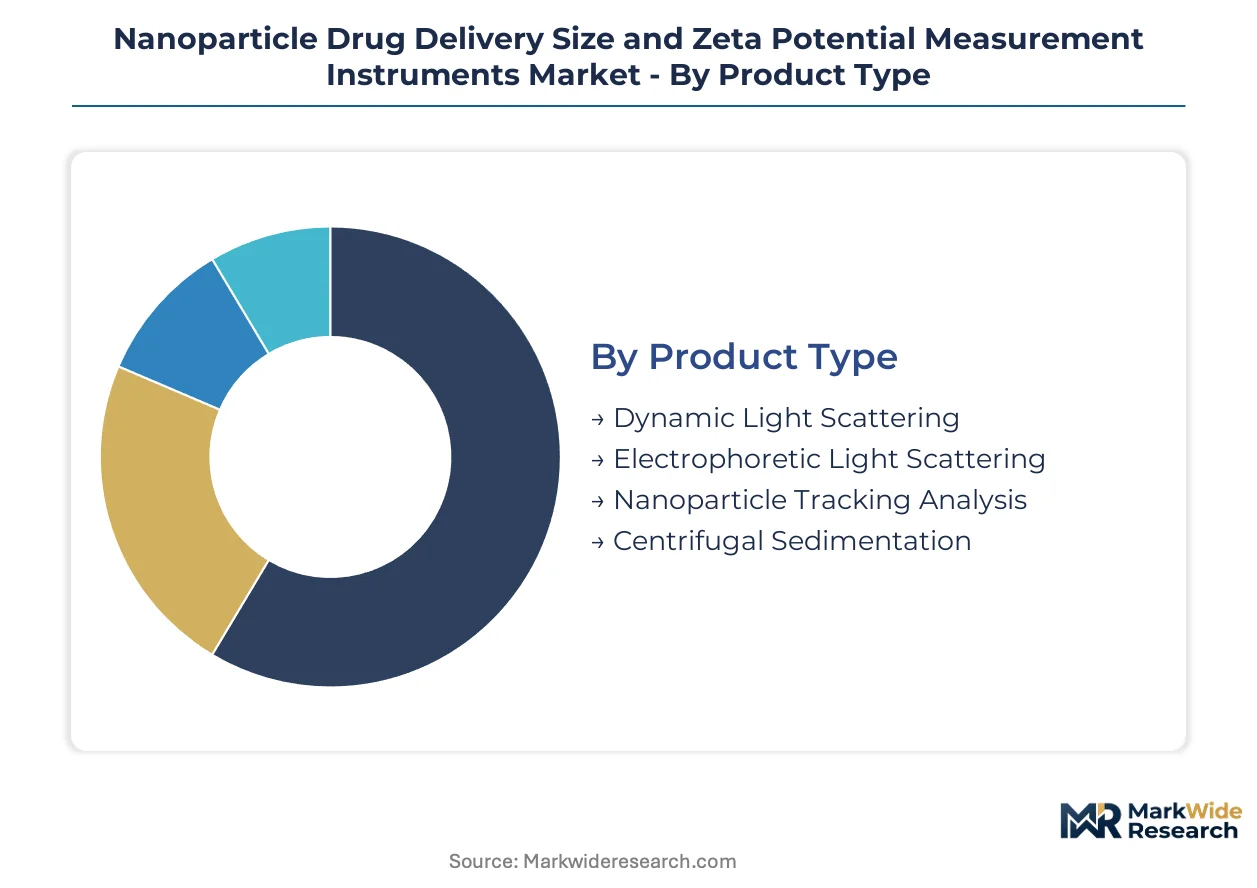
Segmentation in nanoparticle characterization instruments reflects divergent technical requirements between early-stage formulation screening and regulated quality control. Instrument vendors configure optical architectures, software compliance modules, and service models around these distinct use cases.
Product Type:
Standalone benchtop systems dominate pharmaceutical quality control workflows, while modular configurations serve multi-site research operations requiring flexible redeployment.
- Dynamic Light Scattering:Measures hydrodynamic diameter through intensity fluctuations of scattered laser light, achieving sub-nanometer resolution for monodisperse samples. Pharmaceutical companies in the United States deploy these systems for lipid nanoparticle lot release testing under FDA nanomaterial guidance.
- Electrophoretic Light Scattering:Quantifies zeta potential via Doppler shift of scattered light under applied electric field, critical for predicting colloidal stability in injectable formulations. Demand concentrates at European CDMOs responding to EMA quality guidelines for liposomal medicines.
- Nanoparticle Tracking Analysis:Tracks individual particle Brownian motion through video microscopy, resolving polydisperse biological samples incompatible with ensemble averaging.
- Centrifugal Sedimentation:Separates particles by density and size through controlled centrifugal force, serving high-concentration protein formulations where light scattering fails.
Dynamic Light Scattering leads volumes today; Nanoparticle Tracking Analysis is gaining share fastest.
Technology:
Detection methodologies split between velocity-based electrophoretic techniques favored for zeta potential accuracy and correlation-based photon counting systems optimized for rapid sizing.
- Laser Doppler Velocimetry:Industry standard for electrophoretic mobility measurement, converting frequency shifts into zeta potential values through Smoluchowski or Hückel models. German instrument manufacturers anchor supply chains for stabilized diode laser components.
- Photon Correlation Spectroscopy:Computes particle size from autocorrelation of scattered light intensity, enabling sub-second measurements with minimal sample volume. Academic laboratories across Japan leverage these systems for high-throughput formulation screening.
- Microelectrophoresis:Direct visualization of particle migration in capillary cells, offering absolute mobility measurements independent of model assumptions.
- Atomic Force Microscopy:Resolves surface topography at atomic resolution, serving specialized applications requiring morphological validation beyond hydrodynamic diameter.
Laser Doppler Velocimetry commands the largest installed base; Photon Correlation Spectroscopy shows the steepest expansion trajectory.
Application:
Therapeutic modality dictates instrument specification, with nucleic acid delivery systems demanding simultaneous size and zeta potential validation that small-molecule nanoparticles often bypass.
- Targeted Therapeutics:Functionalized nanoparticles with surface ligands require validated surface charge characterization to ensure conjugation efficiency and stealth properties. Contract research organizations in Switzerland specialize in these analytical workflows.
- Gene Delivery:Viral and non-viral vectors demand tight polydispersity control to achieve regulatory batch consistency. mRNA vaccine developers in the United States drive procurement of multi-parameter platforms combining dynamic light scattering with electrophoretic detection.
- Vaccine Development:Adjuvant nanoparticles and antigen delivery systems require stability monitoring across temperature stress conditions.
- Anticancer Agents:Liposomal doxorubicin and similar formulations depend on size distribution control to optimize tumor penetration and minimize RES clearance.
Gene Delivery dominates current procurement; Targeted Therapeutics is climbing the fastest.
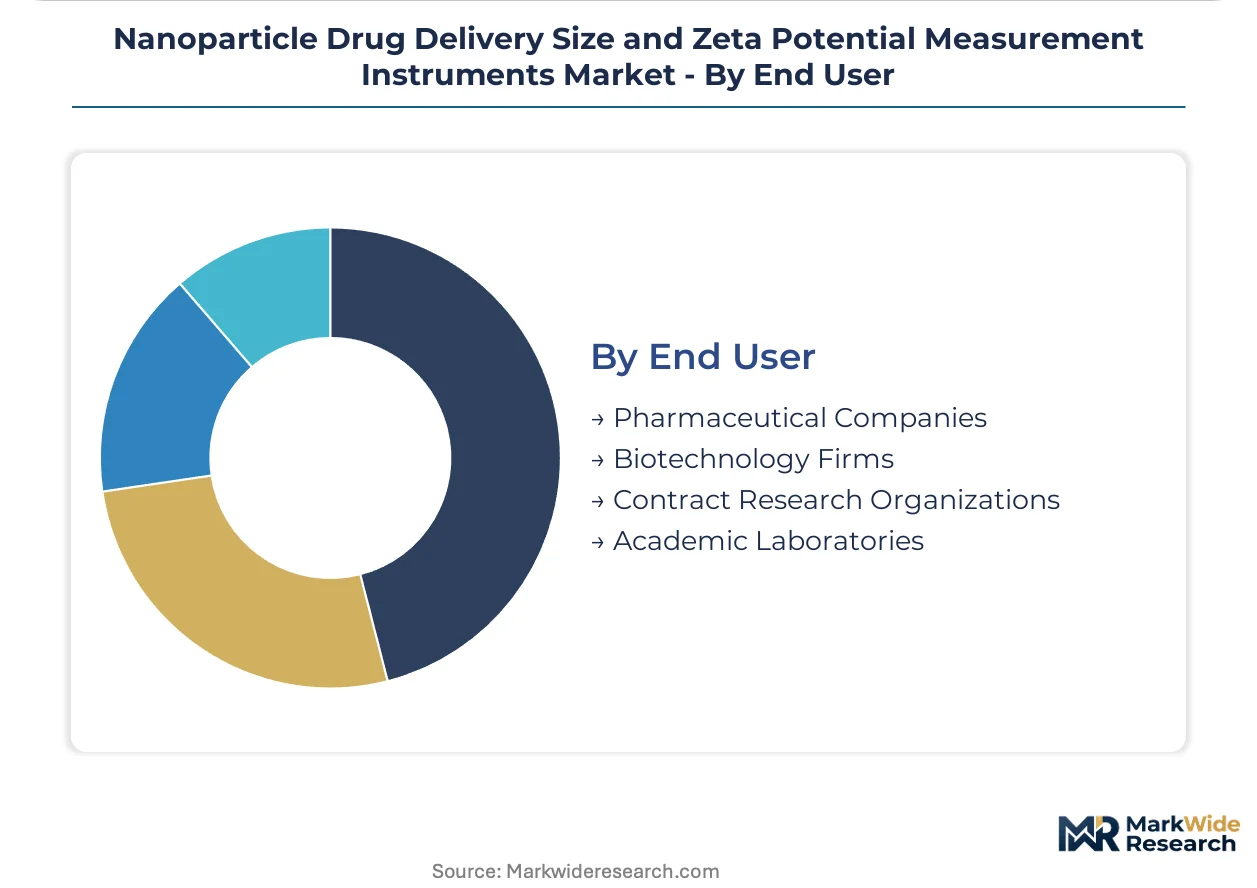
End User:
Customer type determines purchasing authority, validation requirements, and service contract structures, with outsourced development creating fragmented decision-making across sponsor and service provider organizations.
- Pharmaceutical Companies:Internal quality control departments specify GMP-compliant instruments with 21 CFR Part 11 software and comprehensive IQ/OQ/PQ documentation. Large manufacturers in Germany consolidate vendor relationships to reduce validation burden under REACH nanomaterial registration.
- Contract Research Organizations:Rapid method transfer and cross-laboratory reproducibility drive demand for ISO 22412 standardized platforms. CDMOs serving United States gene therapy developers represent the most dynamic procurement channel.
- Biotechnology Firms:Venture-funded developers prioritize capital efficiency, favoring multi-technique platforms that eliminate redundant instrumentation.
- Academic Laboratories:Grant-funded researchers prioritize publication-grade data and open software architectures over regulatory compliance features.
Pharmaceutical Companies account for the largest revenue share; Contract Research Organizations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement patterns as pharmaceutical manufacturers migrate analytical validation workflows toward jurisdictions with harmonized standards but lower operational overhead. Cost-of-compliance gaps between established and emerging markets are accelerating service infrastructure buildouts.
United States
FDA nanomaterial characterization guidance drives lipid nanoparticle quality control instrument procurement at commercial mRNA manufacturing sites. The agency's evolving submission requirements for gene therapy vectors mandate validated multi-parameter platforms. Massachusetts and North Carolina biomanufacturing clusters concentrate demand for GMP-compliant systems with 21 CFR Part 11 software.
Germany
REACH nanomaterial registration obligations compel pharmaceutical quality departments to document particle stability with audit-trail-equipped instrumentation. EMA quality guidelines for liposomal medicines tighten validation protocols across Baden-Württemberg and Bavaria formulation facilities. Stuttgart-area CDMOs are consolidating vendor relationships to reduce documentation burden.
Switzerland
Swissmedic's stringent batch-release standards for nanomedicines elevate demand for orthogonal measurement techniques. Basel's contract research organizations specialize in surface charge characterization for functionalized therapeutic nanoparticles. The country's precision optics heritage supports localized service infrastructure for laser-based detection systems.
Japan
PMDA's convergence with ICH Q2(R1) validation standards accelerates replacement of legacy single-method instruments at Osaka and Tokyo pharmaceutical sites. METI funding for advanced biomanufacturing creates procurement channels for continuous process monitoring equipment. Kansai-region academic laboratories drive early-stage formulation screening demand.
India
PLI scheme incentives for domestic pharmaceutical manufacturing expand nanomedicine formulation capacity requiring localized instrument service networks. CDSCO's alignment with international nanomaterial characterization standards elevates quality control expectations at Maharashtra and Gujarat facilities. Hyderabad and Mumbai CDMOs represent the fastest-growing procurement channel.
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market Competitive Landscape
German and Japanese producers anchor one tier of precision optics supply; Anglo-Dutch and Austrian specialists hold adjacent positions in integrated platform design. The vendor structure concentrates around three to four dominant systems manufacturers with decades of laser diffraction heritage, while smaller modular specialists fragment the mid-market. Two strategic archetypes prevail: full-stack platform vendors bundling hardware with regulatory consulting, and component-focused suppliers enabling phased laboratory buildouts. Capacity expansion into pharmaceutical-grade service infrastructure and technology licensing for GMP-compliant software modules constitute the dominant competitive moves.
Within the precision optics tier, Malvern Panalytical and HORIBA occupy positions defined by laser heritage and integrated platform breadth respectively. Anton Paar exemplifies the compact, compliance-focused archetype serving European continuous manufacturing deployments. These three entities collectively represent the spectrum from high-throughput research configurations to at-line process analytical technology systems.
| Leading Market Players |
|---|
| Malvern Panalytical |
| HORIBA |
| Anton Paar |
| Shimadzu Corporation |
| Agilent Technologies |
| Bruker |
| Thermo Fisher Scientific |
| Beckman Coulter |
| Microtrac |
| Others |
Pricing and Supply Chain Analysis
REACH registration requirements for nanomaterial-containing drug products gate qualified supply and premium-tier pricing access for European pharmaceutical manufacturers, forcing instrument vendors to absorb compliance documentation costs or cede market position to certified competitors. German and Japanese optics suppliers leverage this regulatory barrier to sustain margin premiums on stabilized diode lasers essential for sub-nanometer resolution, while buyers in lower-compliance jurisdictions face restricted access to GMP-validated platforms.
Pricing Analysis
Distributor margins on pharmaceutical-grade particle characterization systems typically range between 15% and 25%, with direct-to-OEM procurement channels commanding steeper discounts tied to multi-unit commitments and bundled service contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by software compliance grade—21 CFR Part 11 validation and comprehensive IQ/OQ/PQ documentation anchor premium positioning—while volume scale and after-sales service bundling differentiate mid-tier offerings. Cost compression in economy-tier benchtop units is intensifying because contract research organizations prioritize capital efficiency over regulatory feature sets. Academic laboratories exhibit highest price sensitivity due to grant-funded procurement constraints; commercial mRNA vaccine manufacturers demonstrate lowest sensitivity given GMP compliance imperatives.
Supply Chain Analysis
Freight costs for stabilized laser components from German and Japanese precision optics manufacturers add 8% to 12% to landed instrument costs for North American buyers, compressing vendor margins or inflating end-user pricing depending on contract terms. Geographic supply concentrates in Germany, Japan, and the United States for high-purity laser diodes, photodetector arrays, and precision optical cells. Raw material dependencies rest on rare-earth doped laser crystals, specialized fused silica for sample cells, and NIST-traceable polystyrene bead calibration standards. Single-source vulnerability characterizes the polystyrene bead supply, with concentrated US and UK origin points creating disruption risk for calibration-dependent workflows. Distribution runs through authorized distributor networks for pharmaceutical end-users, while academic and biotechnology segments increasingly source through direct vendor portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where cost-of-compliance gaps between European REACH-mandated documentation requirements and emerging-market regulatory alignment create service infrastructure buildout opportunities. The 4-6 month IQ/OQ/PQ validation timeline compression in Germany versus 12+ month equivalent processes in India illustrates the differential.
For Market Incumbents: Anchor market position through captive supply of GMP-compliant software modules and localized service infrastructure in high-growth jurisdictions. Vertical integration into precision laser component manufacturing mitigates margin compression from German and Japanese optics suppliers. Capacity addition in India addresses PLI scheme-driven pharmaceutical manufacturing expansion while competitors rely on import-dependent service models. For New Entrants and Emerging Players: The price-point gap between premium-tier multi-parameter platforms and economy-tier single-technique instruments creates white-space opportunity in mid-market contract research organizations. India's CDMO sector represents the most penetrable geography given localized service infrastructure scarcity. Modular platform configurations enabling phased capital deployment offer distinct go-to-market positioning against full-stack incumbents. For Investors and Strategic Acquirers: Roll-up economics work for specialized analytical service firms because instrument OEM service contract unbundling among mRNA vaccine manufacturers fragments technical expertise across third-party consultancies. Long-term viability over the 5-10 year horizon rests on regulatory consulting capabilities rather than hardware margins. Acquisition target archetype: regional validation consultancies with established FDA and EMA submission track records. The signal to watch is CDSCO alignment pace with international nanomaterial characterization standards, which would trigger infrastructure investment cycles at Indian formulation facilities.| Strategic Initiative | Industry Significance |
|---|---|
| GMP-Compliant Software Module Development | 21 CFR Part 11 validation capabilities differentiate vendors for FDA-regulated mRNA manufacturing sites. |
| Localized Service Infrastructure Buildout | India's PLI scheme creates demand for domestic instrument calibration and maintenance capabilities. |
| Multi-Technique Platform Consolidation | Combined dynamic light scattering and nanoparticle tracking analysis reduces bench space requirements for quality control labs. |
| Continuous Manufacturing Integration | At-line zeta potential sensors enable real-time release testing under EMA quality guidelines. |
| Third-Party Validation Consultancy Acquisition | Metrology expertise disintermediation from OEMs expands addressable service market for specialized analytical firms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with instrument vendor product managers, pharmaceutical quality control directors, contract research organization analytical leads, and regulatory affairs specialists with secondary validation against FDA nanomaterial guidance documents, EMA quality guidelines for liposomal medicines, ISO 22412 standards, ICH Q2(R1) validation protocols, and instrument vendor SEC filings. Bottom-up triangulation across end-user procurement patterns and top-down reconciliation against reported vendor revenue streams ensured cross-verified demand estimates.
Comparable-period anchoring tied projection assumptions to historical instrument replacement cycles observed during prior regulatory guidance transitions, particularly the FDA's 2017 nanotechnology framework evolution. Segmentation dimensions modeled include product type, detection technology, therapeutic application, and end-user organizational archetype, with additional granularity on regional regulatory cluster alignment. CAGRs were derived from fitted growth curves applied to validated baseline estimates, incorporating mRNA vaccine manufacturing scale-up trajectories and continuous manufacturing adoption curves as industry-specific demand drivers.
The model assumes a particular technology adoption path; alternative pathways for single-particle resolution techniques displacing ensemble-averaging methods would alter the outlook for dynamic light scattering platform demand. Forecasts reflect assumptions regarding regulatory harmonization pace and pharmaceutical outsourcing trends. A model refresh is warranted upon material change in FDA nanomaterial characterization guidance or CDSCO standards alignment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Specimen Validity Testing Market
Testing Services
Biological Indicator Incubators Market
Testing Services
United States Hospital Acquired Disease Testing Market
Testing Services
Solid Tumor Testing Market
Testing Services
Toxicology Drug Screening Market
Testing Services
Helicobacter Pylori Testing Market
Testing Services
Thailand Point-Of-Care Testing (POCT) Market
Testing Services
Global Efficacy Testing Market
Testing Services
Alcohol Breathalyzer and Drug Testing Equipment Market
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Biomarker Testing Services Market
Testing Services
Platelet Function Test Market
Testing Services
Tablet Hardness Testers Market
Testing Services
Special Coagulation Tests Market
Testing Services
Infusion Toxicology Services Market
Testing Services
North America Testing Inspection and Certification (TIC) Market