
 Cannabis Testing Services Market | 2026-2036
Cannabis Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Testing Services Market Intelligence
Residual solvent screening revenue is fragmenting across regional laboratories and multi-state analytical chains. Eurofins Scientific leverages its North American food-safety infrastructure to anchor cannabis contaminant workflows in multiple jurisdictions. Thermo Fisher Scientific Inc. dominates instrument supply to third-party testing facilities, while SC Labs specializes in California's terpene profiling and heavy-metal compliance panels.
Cannabis testing services encompass analytical verification of cannabinoid potency, terpene content, and contaminant thresholds using high-performance liquid chromatography and quantitative polymerase chain reaction methods. Chromatography systems process the highest sample volumes for THC and CBD quantification, though mass spectrometry adoption accelerates where states mandate sub-part-per-billion pesticide detection limits. Microbial testing commands premium pricing in markets with living-organism specifications, while residual solvent analysis matures as standard operating procedure across recreational jurisdictions.
FDA guidance on cannabis-derived pharmaceutical ingredients and state-level departments of agriculture shape laboratory accreditation requirements and method-validation standards. EPA pesticide tolerance frameworks influence which analyte panels laboratories must maintain, with ISO 17025 certification serving as the baseline credential for market access. Stakeholders must track evolving state-by-state contaminant lists and invest in flexible analytical platforms that accommodate regulatory scope expansion without complete workflow replacement.
Market Dynamics
State-level mandates for Aspergillus species screening and residual solvent detection are compressing batch-release timelines while forcing cultivators to absorb higher analytical costs per harvest cycle.
Growth Catalysts
- California Department of Cannabis Control batch-release protocols:Mandatory microbial panels for living-organism specifications now cover 15+ Aspergillus strains, expanding laboratory service contracts.
- High-performance liquid chromatography (HPLC) throughput gains:Multi-channel UV detection systems process 200+ samples daily, cutting per-test costs for high-volume cultivators.
- Colorado Marijuana Enforcement Division rulemaking:Heavy-metal testing for cadmium and arsenic now applies to inhalable products, adding compliance panels to standard service agreements.
Market Restraints
- Helium supply volatility:Gas chromatography-mass spectrometry operations depend on constrained noble gas sourcing, with price spikes hitting mid-sized regional laboratories hardest.
- ISO 17025 accreditation timelines:Method validation for novel matrices stretches 18-24 months, delaying market entry for new testing facilities.
- Mass spectrometry instrument concentration:Thermo Fisher and Agilent control 70%+ of installed base, limiting price negotiation leverage for independent laboratories.
Strategic Opportunities
- Terpenoid profiling for craft cultivators:Boutique growers in Oregon and Washington seek differentiation through full-spectrum analytical certificates.
- Quantitative PCR (qPCR) for hemp-derived CBD:THC threshold verification at 0.3% dry weight opens agricultural testing contracts outside recreational cannabis frameworks.
- Blockchain-anchored certificates of analysis:Dispensaries and distributors in Nevada now demand immutable batch records for supply chain transparency.
Industry Challenges
- Analytical chemist talent scarcity:Method development for novel cannabinoids requires PhD-level chromatography expertise that competes with pharmaceutical salaries.
- Multi-jurisdictional method harmonization:California's 12-pesticide panel diverges from Colorado's 24-analyte requirement, forcing redundant standard maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Testing Services Market |
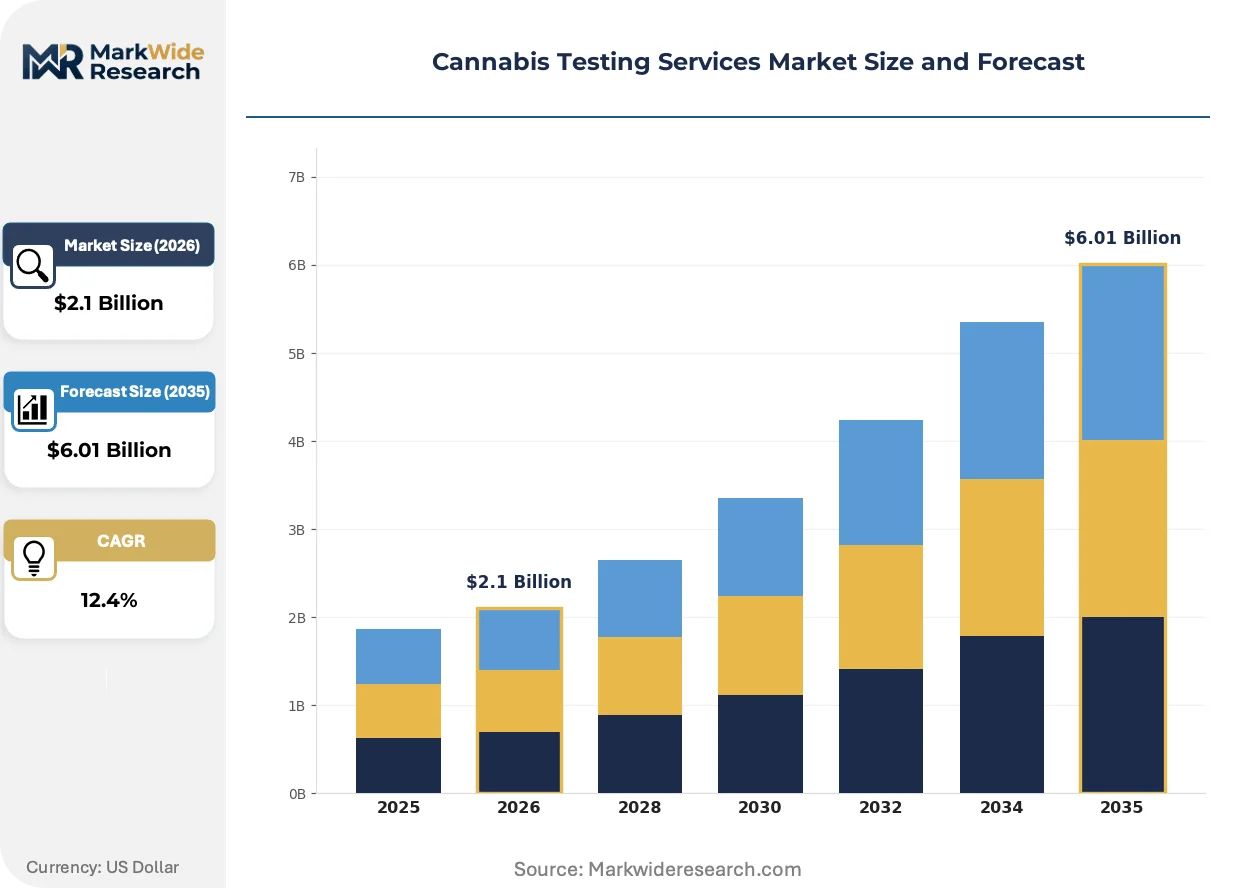
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.01 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Potency Testing, Residual Solvent Analysis, Microbial Testing, Pesticide Screening Technology: Chromatography, Spectroscopy, Molecular Biology, Mass Spectrometry End User: Growers, Retailers, Dispensaries, Laboratories Application: Product Testing, Quality Assurance, Compliance Testing, Research & Development |
| Companies Covered | SC Labs, Steep Hill, Inc., CW Analytical, Thermo Fisher Scientific Inc., Encore Labs, Eurofins Scientific, SGS Canada Inc., Anresco Laboratories, Green Leaf Lab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Testing Services Market Strategic Shifts & Innovations
Laboratory workflows are converging around automation and data integrity as cultivators demand faster turnaround times and regulators enforce stricter chain-of-custody documentation.
High-resolution mass spectrometry is hybridizing with traditional LC-UV workflows to enable simultaneous potency, pesticide, and mycotoxin screening in single injection protocols. Third-party laboratories serving Nevada and Massachusetts cultivators are adopting these platforms to consolidate multi-panel contracts. The technology is hybridizing previously separate instrument investments into unified capital expenditure decisions that favor larger multi-state operators over regional competitors.
EPA pesticide tolerance frameworks are expanding analyte lists for cannabis matrices beyond conventional agricultural crops, forcing laboratories to add quaternary ammonium compounds and pyrethroids to standard panels. Colorado and California departments of agriculture now reference these tolerances in enforcement actions. Testing facilities are responding by subscribing to real-time regulatory tracking services and building flexible liquid chromatography methods that accommodate quarterly scope expansions without hardware replacement.
Dispensary procurement is consolidating around preferred laboratory partnerships with guaranteed 72-hour turnaround and digital certificate delivery. Multi-location retailers in Illinois and Michigan now require API-integrated laboratory information management systems that push results directly into point-of-sale inventory locks. This consolidation is most visible in vertically integrated markets where retail chains operate captive cultivation and demand uniform analytical standards across internal and external supply sources.
Cannabis Testing Services Market Segmentation
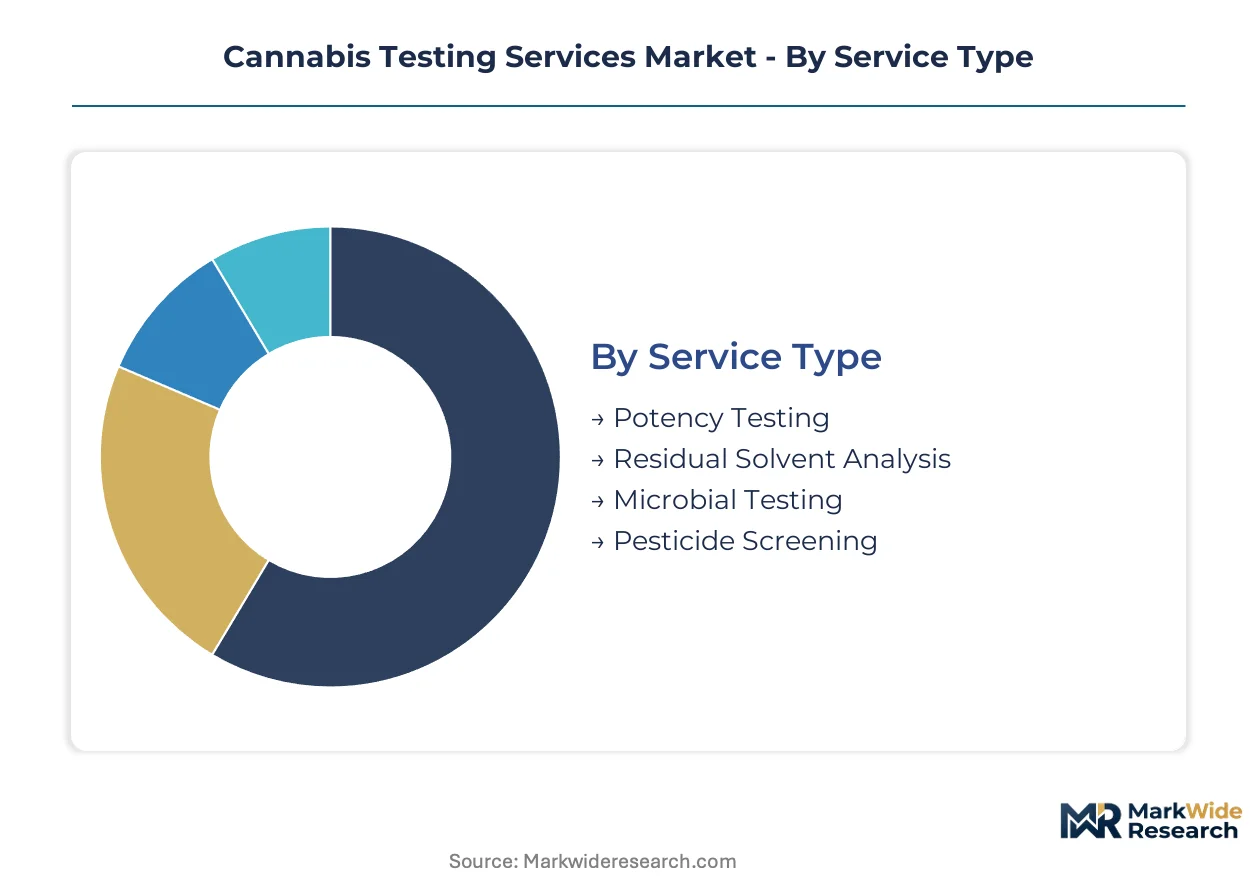
Cannabis testing services fragment across analytical methods, regulatory requirements, and customer sophistication levels. Segmentation reveals where capital concentrates versus where new entrants find footholds.
Service Type:
Mature panels dominate revenue while emerging categories reshape laboratory capacity planning.
- Potency Testing:HPLC-based quantification of THC, CBD, and minor cannabinoids forms the baseline service contract. California and Colorado cultivators require potency verification for every harvest batch, driving daily sample volumes above 200 per instrument.
- Microbial Testing:qPCR and culture-based methods detect Aspergillus species, Salmonella, and E. coli in living-organism specifications. State mandates for 15+ Aspergillus strains in inhalable products compress turnaround times and command premium pricing.
- Residual Solvent Analysis:Gas chromatography quantifies butane, propane, and ethanol remnants in extracted products. Standardization across recreational jurisdictions has commoditized per-test pricing.
- Pesticide Screening:LC-MS/MS detection of organophosphates, pyrethroids, and quaternary ammonium compounds addresses expanding state analyte lists. Sub-part-per-billion detection limits favor laboratories with high-resolution mass spectrometry platforms.
Potency Testing retains volume leadership; Microbial Testing holds the steepest expansion curve.
Technology:
Cost tier separation runs from capital-intensive reference platforms to rapid field methods.
- Chromatography:HPLC and GC systems process the highest sample volumes with UV or FID detection. Multi-channel configurations enable 200+ daily potency determinations, anchoring high-throughput laboratory economics.
- Mass Spectrometry:LC-MS and GC-MS deliver sub-ppb sensitivity for pesticide and mycotoxin panels. Instrument concentration among two dominant suppliers limits price negotiation leverage for independent laboratories.
- Spectroscopy:FTIR and NIR methods enable rapid cannabinoid screening with minimal sample preparation. Portable units serve cultivators seeking in-house monitoring before third-party submission.
- Molecular Biology:qPCR platforms target specific microbial DNA sequences for living-organism compliance. Adoption accelerates where states mandate DNA-based detection over culture methods.
Chromatography retains volume leadership; Mass Spectrometry holds the steepest expansion curve.
End User:
Customer type determines contract structure, from annual service agreements to per-batch spot testing.
- Growers:Licensed cultivators require comprehensive panels covering potency, contaminants, and terpenes. California's Department of Cannabis Control mandates batch-release documentation before product transfer to distribution.
- Laboratories:Third-party analytical facilities subcontract specialized assays or seek ISO 17025 accreditation support. Reference laboratories in Nevada and Massachusetts consolidate multi-panel contracts through high-resolution platforms.
- Dispensaries:Retail procurement teams demand API-integrated certificate delivery with 72-hour turnaround guarantees. Multi-location operators in Illinois require uniform analytical standards across internal and external supply sources.
- Retailers:Chain buyers perform vendor qualification audits and reserve testing rights for quality disputes. Blockchain-anchored certificates of analysis now feature in Nevada supply chain transparency requirements.
Growers retain volume leadership; Laboratories hold the steepest expansion curve.
Application:
Application scope separates mandatory compliance from discretionary quality investment.
- Compliance Testing:State-mandated panels for potency, microbes, heavy metals, and residual solvents enable market access. EPA pesticide tolerance frameworks and state agriculture departments define analyte scope and method validation requirements.
- Quality Assurance:In-process monitoring and stability testing support brand consistency and shelf-life claims. Craft cultivators in Oregon and Washington differentiate through full-spectrum analytical certificates.
- Product Testing:Final release verification covers novel delivery formats including beverages, topicals, and inhalable concentrates. Matrix complexity drives method development costs for emerging product categories.
- Research & Development:Analytical support for breeding programs and extraction optimization serves licensed producers developing proprietary genetics. PhD-level chromatography expertise competes with pharmaceutical salaries for talent acquisition.
Compliance Testing retains volume leadership; Quality Assurance holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
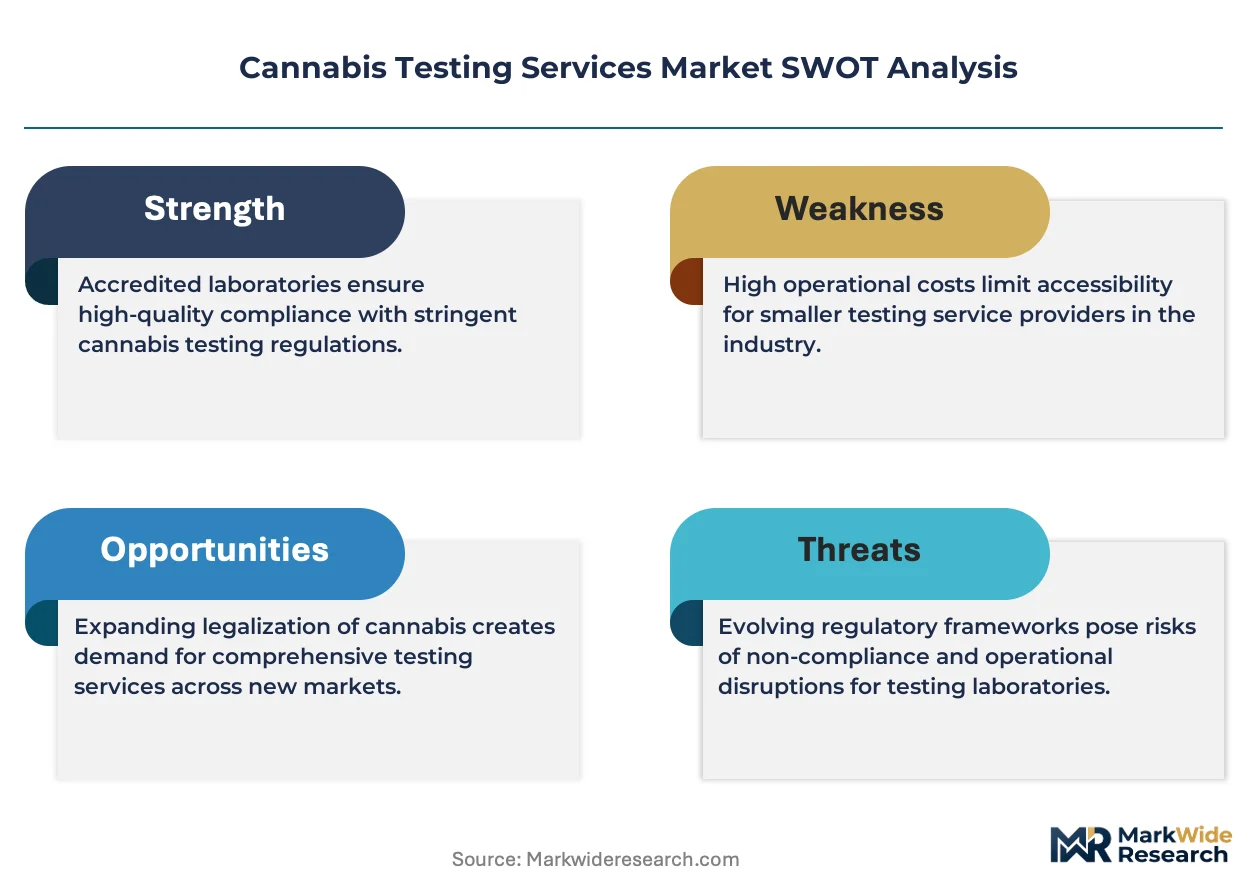
California and Colorado treat cannabis testing as mandatory gatekeeping infrastructure, while Canada and Germany embed it within pharmaceutical-grade frameworks for medical markets.
United States
California's Department of Cannabis Control mandates 15-strain Aspergillus panels and heavy-metal screening for inhalable products, compressing batch-release timelines. Colorado's Marijuana Enforcement Division expanded cadmium and arsenic testing rules in 2024. Denver and Los Angeles host the densest laboratory clusters, where multi-state operators consolidate high-throughput HPLC contracts.
Canada
Health Canada and the Pest Management Regulatory Agency enforce pesticide tolerance frameworks that exceed US state requirements for medical cannabis. Licensed producers in British Columbia and Ontario face mandatory microbial and solvent screening under the Cannabis Act. Toronto's analytical facilities now serve both domestic cultivators and US exporters seeking ISO 17025 certification alignment.
Germany
The Federal Institute for Drugs and Medical Devices regulates cannabis-derived pharmaceuticals under AMG and BfArM frameworks, requiring GMP-compliant testing for medical flower imports. Bavaria and North Rhine-Westphalia concentrate the country's cannabis distribution infrastructure. Cologne-based laboratories now process validation protocols for Canadian and Dutch exporters entering the 2024 medical market expansion.
Netherlands
The Office of Medicinal Cannabis operates Europe's longest-running government-controlled cannabis program, with mandatory potency and contaminant screening for domestic and imported flower. Rotterdam and The Hague anchor the country's analytical services corridor. Dutch laboratories increasingly validate methods for German medical market entry as cross-border supply agreements formalize.
Switzerland
Swissmedic oversees pilot programs for recreational cannabis sales in Basel, Zurich, and Geneva, requiring THC content verification below 1% for legal distribution. The country's pharmaceutical testing heritage supports rapid method deployment for novel cannabinoid matrices. Basel's life sciences cluster now hosts specialized facilities serving both domestic retailers and EU medical exporters.
Cannabis Testing Services Market Key Industry Players
Capability concentration sits with instrument manufacturers; scale advantage sits with multi-jurisdictional laboratory networks. The market structures around three tiers: global analytical conglomerates with food-safety infrastructure, specialized cannabis-only laboratories with state-level regulatory depth, and instrument suppliers controlling the underlying detection technology. Consolidation is accelerating through laboratory acquisitions and multi-state operating license transfers.
Within the specialized testing tier, SC Labs and Steep Hill exemplify state-focused regulatory expertise, while Eurofins Scientific represents the food-safety conglomerate archetype applying cross-industry quality systems to cannabis matrices. Thermo Fisher Scientific anchors the instrument supply tier that underpins independent laboratory operations.
| Leading Market Players |
|---|
| SC Labs |
| Steep Hill, Inc. |
| CW Analytical |
| Thermo Fisher Scientific Inc. |
| Encore Labs |
| Eurofins Scientific |
| SGS Canada Inc. |
| Anresco Laboratories |
| Green Leaf Lab |
| Others |
Cost & Logistics Intelligence
Helium supply volatility between the United States and Qatar determines both the widening spread between high-throughput chromatography contracts and commodity residual solvent panels and the geographic clustering of multi-state laboratory networks around domestic gas sourcing infrastructure.
Pricing Analysis
Long-term service agreements with annual minimums dominate cultivator-laboratory relationships, though spot testing persists for failed-batch reanalysis and new market entrants. Three-tier pricing structure across ISO 17025-accredited reference laboratories, state-certified regional facilities, and unaccredited screening operations reflects certification grade and instrument platform depth. Cost compression in residual solvent analysis is intensifying because method standardization has eliminated technical differentiation. Craft cultivators in Oregon and Washington exhibit highest price sensitivity, while multi-state operators in Illinois prioritize turnaround guarantees over per-test economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates instrument procurement risk for independent laboratories building LC-MS/MS capacity. HPLC and mass spectrometry systems draw from concentrated manufacturing in Massachusetts, California, and Germany, with consumables sourcing fragmented across chromatography column suppliers in Pennsylvania and detector component specialists in Japan. Single-source vulnerability sits with Thermo Fisher and Agilent controlling the installed base of high-resolution platforms. Distribution runs through direct manufacturer sales for capital equipment and regional distributors for consumables and certified reference materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-house testing adoption by vertically integrated multi-state operators threatens third-party laboratory volume, forcing incumbent service providers to defend substitution through irreplaceable regulatory expertise and accreditation depth.
For Market Incumbents: Harden defensibility by acquiring ISO 17025-accredited facilities in states with tightening Aspergillus mandates, particularly California and Colorado where batch-release protocols are expanding. Build backward integration into helium recovery systems to offset noble gas price volatility and secure chromatography uptime guarantees that commodity competitors cannot match. For New Entrants and Emerging Players: Establish a beachhead in terpenoid profiling for craft cultivators in Oregon and Washington, where differentiation demand outpaces accredited laboratory supply. Pursue qPCR method validation for hemp-derived CBD testing at 0.3% THC thresholds, opening agricultural contracts outside recreational cannabis frameworks with lower capital barriers. For Investors and Strategic Acquirers: FDA guidance on cannabis-derived pharmaceutical ingredients reshapes the acquisition landscape toward GMP-compliant testing infrastructure. Target facilities with dual pharmaceutical-cannabis accreditation and existing relationships with Health Canada or EMA-aligned regulators. Watch for DEA rescheduling proceedings as the signal indicating expanded pharmaceutical channel demand and corresponding method validation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Expansion | ISO 17025 certification in emerging state markets captures batch-release mandate growth before competitors establish presence. |
| Platform Hybridization | High-resolution mass spectrometry integration consolidates multi-panel contracts that single-method laboratories cannot service. |
| Blockchain Integration | Immutable certificate delivery meets Nevada dispensary procurement requirements and differentiates service tier positioning. |
| Helium Recovery Infrastructure | On-site noble gas recycling insulates GC-MS operations from supply volatility that threatens regional competitor viability. |
| Pharmaceutical Method Validation | GMP-compliant testing capability opens Health Canada and EMA-aligned export channels for domestic cultivators. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laboratory directors, state regulatory compliance officers, cultivator operations managers, and chromatography instrument specialists. Secondary validation drew from state department of agriculture rulemaking dockets, EPA pesticide tolerance determinations, ISO 17025 accreditation registries, and customs data on analytical instrument imports. Bottom-up service revenue estimates were triangulated against top-down state licensing counts and mandatory testing frequency requirements.
Calibration against historical state mandate implementation timelines anchored the projection framework across the analysis window. Segmentation modeling covered service type, technology platform, end-user category, and application purpose with geographic regulatory cluster as an additional dimension. CAGRs were derived from instrument installation rates correlated with state licensing expansion and testing panel complexity indices including analyte count and detection limit stringency.
Sensitivities concentrate around DEA rescheduling decisions, state-level living-organism specification expansions, and helium supply chain disruptions. Forecasts reflect assumptions regarding regulatory enforcement consistency and laboratory accreditation processing timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pneumococcal Testing Market
Testing Services
Diagnostic Shipper Market
Testing Services
Leukocyte Count Testing Market
Testing Services
Global Sleep Testing Services Market
Testing Services
CRO Mass Spectroscopy Services Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
Hemostasis Testing Systems Market
Testing Services
Global Specimen Validity Testing Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
Blood Testing Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Infusion Toxicology Services Market
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
US Independent Diagnostic Testing Facility Market