
 Global Cholesterol Testing Products and Services Market | 2026-2036
Global Cholesterol Testing Products and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cholesterol Testing Products and Services Market Foresight
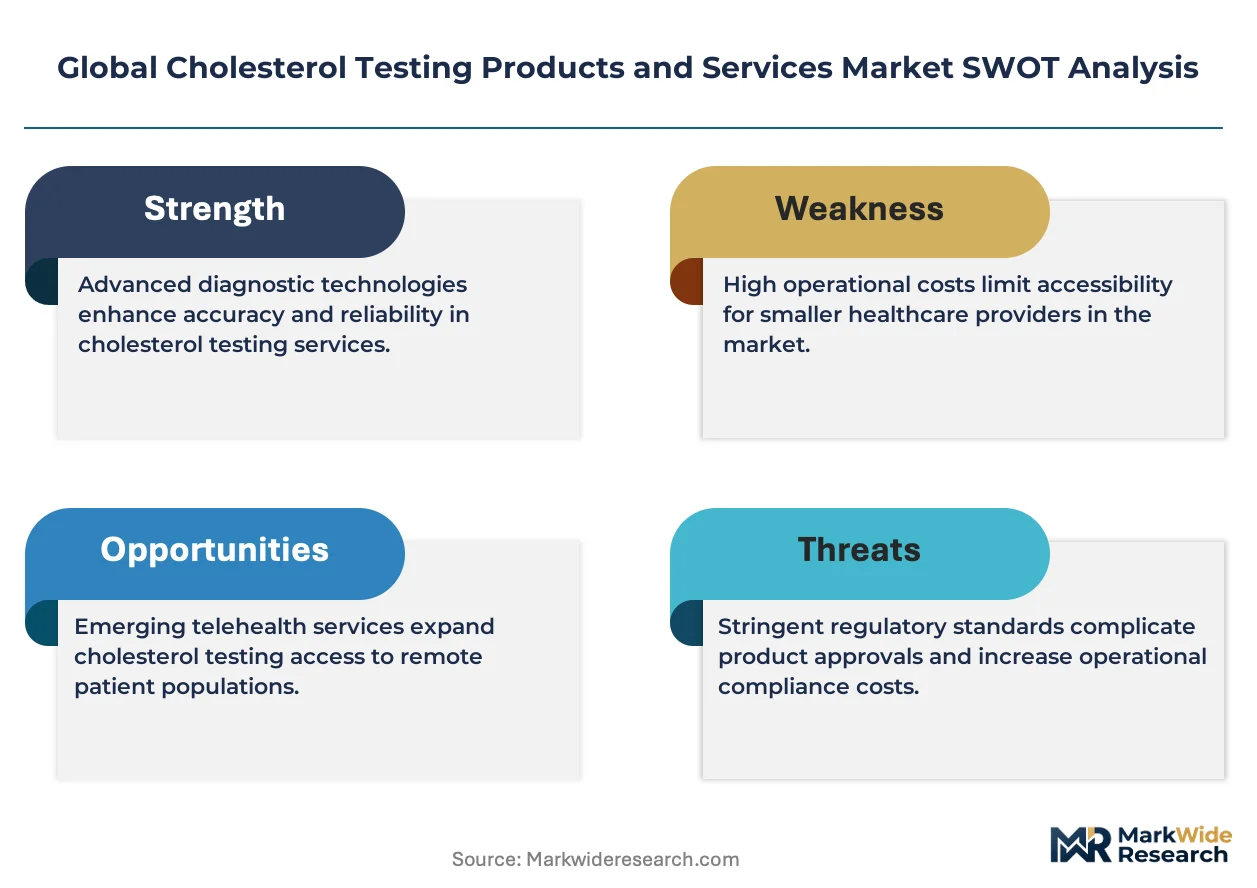
The cholesterol testing landscape is restructuring around a sharp split between premium laboratory analyzers and commoditized home-use strips. Abbott Laboratories leverages its vertically integrated diagnostics pipeline to dominate high-throughput hospital lab placements. Randox Laboratories specializes in multiplexed enzymatic assays that command premium positioning in reference laboratories. Siemens Healthineers anchors its position through integrated informatics that tie lipid results directly into cardiovascular risk scoring workflows.
Cholesterol testing products and services encompass analytical systems, reagents, and professional services that quantify total cholesterol, LDL, HDL, and triglyceride concentrations in blood specimens, typically employing enzymatic colorimetric methods with spectrophotometric detection at 500-700 nm for clinical diagnostic purposes. Point-of-care devices lead volume growth due to their deployment in pharmacy clinics and employer wellness sites, while enzymatic assays retain the largest margin pool through recurring reagent consumption in centralized labs. Immunoassays compete for advanced lipoprotein subfractionation where cardiovascular risk stratification demands higher specificity.
FDA premarket review and CLIA complexity categorization shape which devices qualify for waived testing in physician offices, directly influencing manufacturer R&D priorities and channel strategy. The EU In Vitro Diagnostic Regulation and Japan's PMDA quality management requirements impose additional conformity burdens that favor established multinationals with dedicated regulatory affairs infrastructure. Stakeholders must monitor how decentralized testing reimbursement policies evolve against laboratory-based standard-of-care economics.
Market Dynamics
Point-of-care lipid testing is compressing the traditional centralized laboratory model as pharmacy chains and employer wellness programs deploy waived CLIA devices at scale, fragmenting volume away from hospital core labs.
Growth Catalysts
- Cardiovascular disease screening mandates:Employer wellness programs in the United States now incorporate annual lipid panels as a condition for premium discounts, expanding test volumes beyond clinical settings.
- FDA 510(k) clearance pathways:Streamlined premarket review for moderate-complexity devices accelerates commercialization timelines for enzymatic assay manufacturers targeting physician office laboratories.
- Japan's metabolic syndrome prevention initiative:Government-funded health checkups for adults aged 40-74 drive consistent demand for HDL and triglyceride quantification in municipal clinics.
Market Restraints
- Enzyme reagent supply concentration:Cholesterol esterase and oxidase production clusters in Chinese contract manufacturers, exposing assay producers to input volatility and customs delays.
- EU In Vitro Diagnostic Regulation compliance costs:Small-to-mid-size assay developers face capital requirements for notified body conformity assessments that exceed annual R&D budgets.
- Direct-to-consumer genetic testing substitution:Polygenic risk scores for cardiovascular disease from 23andMe and similar platforms divert preventive screening spending away from biochemical lipid panels.
Strategic Opportunities
- Rural India diagnostic penetration:Underdeveloped primary health center infrastructure creates whitespace for portable reflectance photometry devices operated by auxiliary nurse midwives.
- Artificial intelligence-enhanced risk stratification:Machine learning algorithms trained on lipoprotein subfraction data integrate with electronic health records to personalize statin therapy decisions.
- Germany's Digital Healthcare Act reimbursement:Telemedicine-linked home testing kits for chronic disease monitoring qualify for statutory health insurance coverage, opening direct-to-patient channels.
Industry Challenges
- CLIA personnel qualification gaps:Laboratory directors with specific enzymology expertise command premium compensation, constraining expansion of moderate-complexity testing sites.
- Legacy analyzer interoperability:Proprietary data formats from installed base systems resist integration with modern laboratory information management platforms, complicating workflow consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cholesterol Testing Products and Services Market |
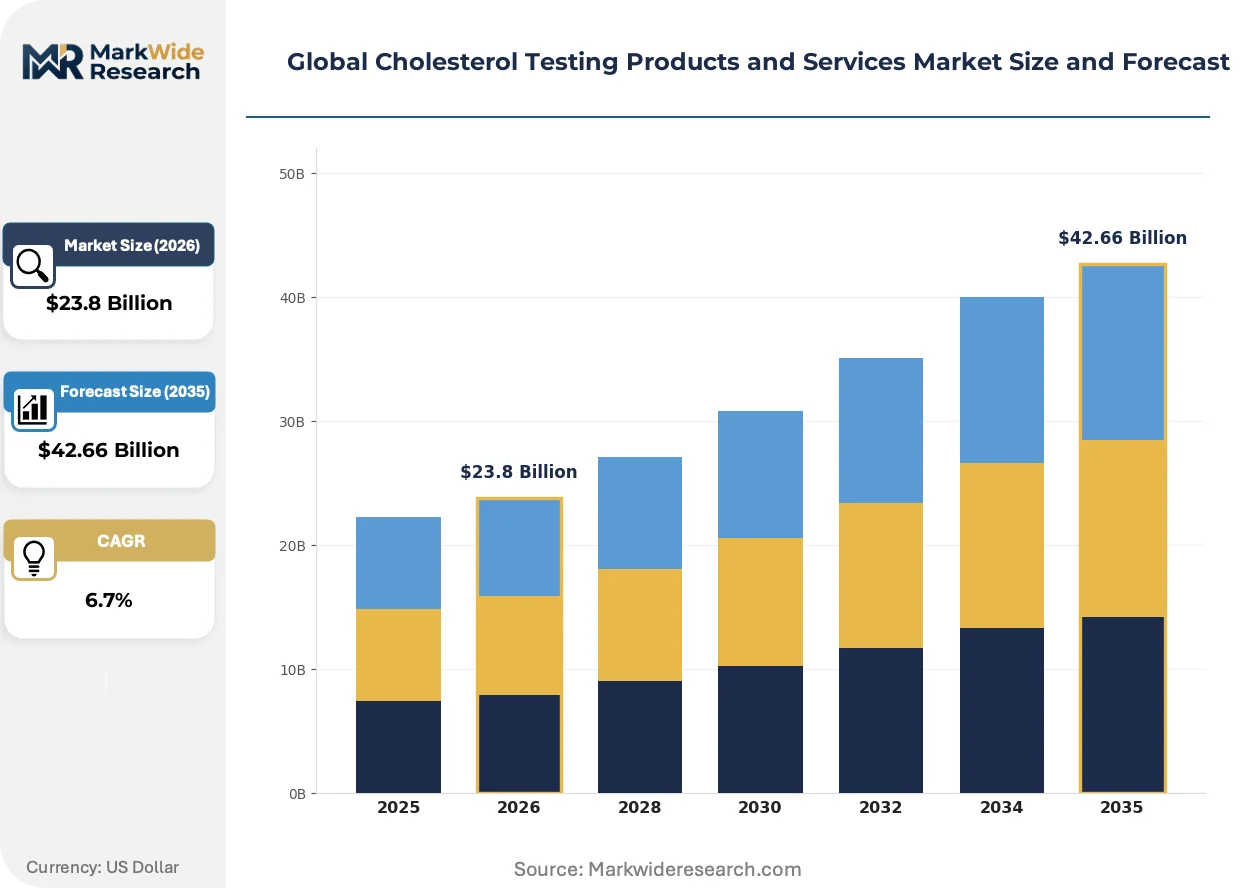
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $42.66 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Test Kits, Enzymatic Assays, Immunoassays, Point-of-Care Devices Testing Technology: Electrochemical, Fluorometric, Photometric, Chromatographic, Nephelometric Application: Cardiovascular Risk, Diabetes Management, Nutritional Assessment, Preventive Health Screening End User: Diagnostic Laboratories, Research Institutes, Specialty Clinics, Wellness Centers |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Thermo Fisher Scientific, Danaher Corporation, Quest Diagnostics, Ortho Clinical Diagnostics, Randox Laboratories, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cholesterol Testing Products and Services Market Shifts & Advancements
Multiplexed assay platforms and artificial intelligence-enhanced result interpretation are compressing turnaround times while elevating the clinical utility of lipid testing beyond simple concentration reporting toward integrated cardiovascular risk assessment.
Microfluidic cartridge technology is integrating sample preparation, enzymatic reaction, and optical detection into single-use disposables that require no pipetting or calibration. Retail clinic operators in the United States deploy these devices in pharmacy-based health hubs, enabling same-visit prescribing decisions. This convergence is integrating diagnostic and therapeutic workflows into unified patient encounters that bypass traditional laboratory intermediaries.
Japan's PMDA revised quality management system requirements for in vitro diagnostics now mandate post-market surveillance data submission every two years, elevating documentation burdens for foreign manufacturers. Domestic reference laboratories have responded by consolidating supplier relationships toward established multinationals with dedicated regulatory affairs infrastructure in Tokyo. Smaller enzymatic assay developers face exclusion from this channel without local quality representation.
Hospital procurement committees now unbundle reagent contracts from analyzer placements, reversing historical capital-equipment bundling models. This shift compresses manufacturer margins on installed base systems while elevating price transparency for recurring consumables. Germany's university hospital networks have pioneered this approach, with purchasing cooperatives negotiating multi-year reagent supply agreements independent of hardware vendors.
Global Cholesterol Testing Products and Services Market Segmentation
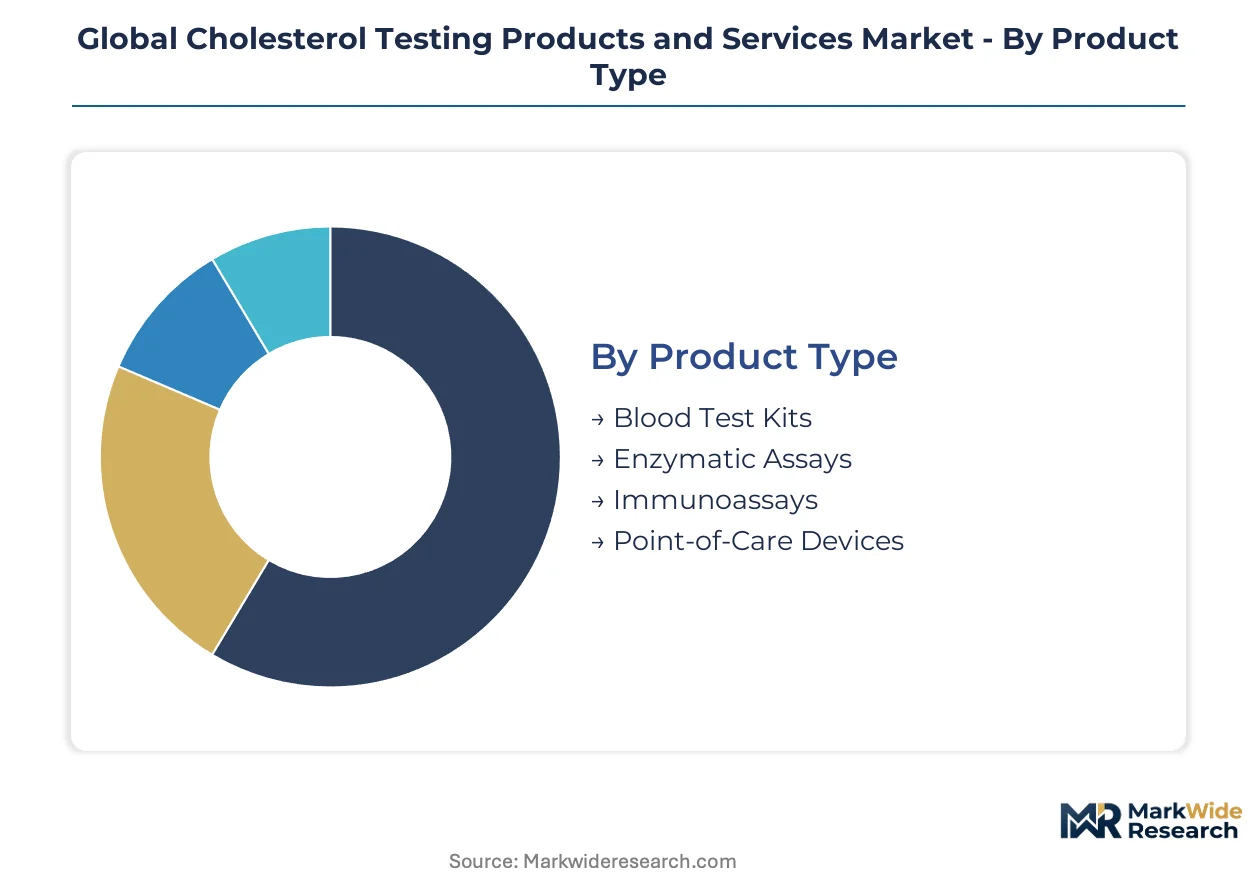
Segmentation in cholesterol testing reveals how technology choices, clinical settings, and reimbursement pathways fragment purchasing decisions. Manufacturers must align product architectures with distinct workflow requirements across centralized laboratories and decentralized care sites.
Product Type:
Volume concentrates in consumable reagents while premium margins accrue to integrated systems with proprietary assay menus.
- Enzymatic Assays:Colorimetric methods using cholesterol esterase and oxidase enzymes dominate hospital core laboratories with high-throughput spectrophotometric analysis. Demand clusters in United States reference laboratories where CLIA moderate-complexity certification supports statin therapy monitoring volumes.
- Point-of-Care Devices:Handheld analyzers with solid-state electrodes enable whole-blood testing without centrifugation. Pharmacy clinics in Germany deploy these for same-visit cardiovascular risk assessments under statutory health insurance reimbursement.
- Blood Test Kits:Consumer-grade lancet and strip combinations for home monitoring lack clinical diagnostic certification but capture wellness program spending.
- Immunoassays:Antibody-based detection methods quantify lipoprotein subfractions for advanced risk stratification in academic medical centers.
Today's leader: Enzymatic Assays. Tomorrow's challenger: Point-of-Care Devices.
Testing Technology:
Optical detection methods retain installed base dominance while electrochemical platforms gain share in battery-powered portable systems.
- Photometric:Spectrophotometric measurement at 500-700 nm wavelength remains the analytical reference standard for total cholesterol quantification in centralized laboratories. Japanese clinical chemistry analyzers from Hitachi and Olympus embed these optics as core subsystems.
- Electrochemical:Amperometric biosensors with screen-printed electrodes eliminate optical path alignment requirements. Indian primary health centers favor these for auxiliary nurse midwife operation without laboratory infrastructure.
- Fluorometric:Enzyme-linked fluorescence detection enhances sensitivity for low-density lipoprotein particle counting in research applications.
- Chromatographic:High-performance liquid chromatography separates cholesterol esters by molecular weight for forensic and research laboratories.
- Nephelometric:Light-scattering quantification of lipoprotein aggregates supports apolipoprotein B measurement in specialized lipid clinics.
Photometric systems anchor current laboratory economics. Electrochemical architectures are climbing the fastest as point-of-care deployment accelerates.
Application:
Reimbursement coding and clinical guideline placement determine which applications sustain premium pricing versus commodity competition.
- Cardiovascular Risk:Framingham-based and pooled cohort equations drive lipid panel ordering for primary prevention. United States employer wellness mandates now require annual screening as a condition for premium discounts.
- Preventive Health Screening:Municipal health checkups in Japan's metabolic syndrome initiative generate predictable demand for HDL and triglyceride quantification in adults aged 40-74.
- Diabetes Management:Dyslipidemia monitoring accompanies glycemic control in integrated chronic disease protocols.
- Nutritional Assessment:Lifestyle medicine clinics order panels to validate dietary intervention efficacy without insurance reimbursement.
Cardiovascular Risk commands current procedure volumes. Preventive Health Screening represents the steepest expansion trajectory as government-funded wellness programs proliferate.
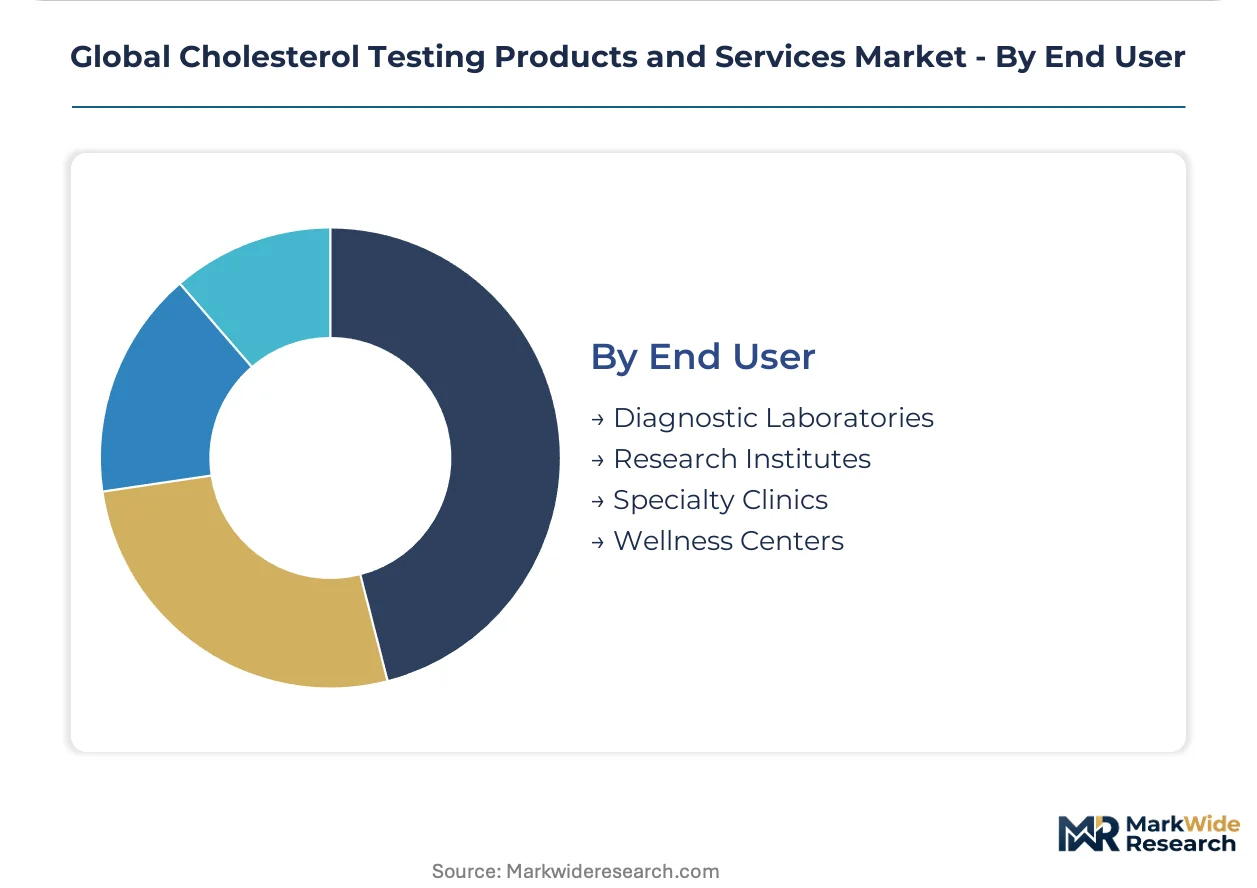
End User:
Purchasing authority and reagent contract structures differ sharply between hospital-owned laboratories and independent diagnostic chains.
- Diagnostic Laboratories:High-throughput core facilities process thousands of samples daily with automated track systems and integrated laboratory information management platforms. Germany's university hospital purchasing cooperatives now unbundle reagent contracts from analyzer placements.
- Specialty Clinics:Cardiology and endocrinology practices with CLIA-waived certification perform point-of-care testing during patient encounters. United States physician office laboratories favor waived complexity devices to avoid personnel qualification requirements.
- Research Institutes:Academic centers demand lipoprotein subfractionation capabilities for cardiovascular mechanistic studies.
- Wellness Centers:Corporate and retail health hubs prioritize rapid turnaround over analytical specificity for screening populations.
Diagnostic Laboratories retain volume concentration. Specialty Clinics are gaining share fastest as site-of-care testing reimbursement expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Laboratory technologists and clinical chemists cluster in established diagnostic hubs across five countries that generate disproportionate cholesterol testing demand. These workforce concentrations anchor procurement authority and shape technology adoption trajectories.
United States
Employer wellness mandates and pharmacy clinic expansion drive point-of-care lipid panel volumes. FDA 510(k) clearance pathways accelerate commercialization for moderate-complexity enzymatic assay manufacturers. Hospital procurement committees in the Northeast Corridor unbundle reagent contracts from analyzer placements, compressing hardware margins.
Germany
Statutory health insurance reimbursement for telemedicine-linked home testing kits opens direct-to-patient channels. The EU In Vitro Diagnostic Regulation imposes conformity assessment burdens favoring established multinationals with dedicated regulatory affairs infrastructure. University hospital purchasing cooperatives in Bavaria and North Rhine-Westphalia negotiate multi-year reagent supply agreements independent of hardware vendors.
Japan
Government-funded metabolic syndrome health checkups for adults aged 40-74 sustain predictable demand for HDL and triglyceride quantification. PMDA revised quality management system requirements mandate biennial post-market surveillance data submission, elevating documentation burdens for foreign manufacturers. Domestic reference laboratories in Tokyo and Osaka consolidate supplier relationships toward multinationals with local quality representation.
India
Underdeveloped primary health center infrastructure creates whitespace for portable reflectance photometry devices operated by auxiliary nurse midwives. CDSCO medical device regulations classify cholesterol analyzers based on risk, determining conformity assessment pathways. Diagnostic chains in Maharashtra and Karnataka deploy electrochemical biosensors in tier-2 cities without laboratory infrastructure.
United Kingdom
NHS cardiovascular disease prevention programs incorporate lipid screening into primary care contracts. MHRA post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment requirements for IVD manufacturers. Private diagnostic laboratories in London and the Southeast expand employer wellness service lines with rapid turnaround lipid panels.
Global Cholesterol Testing Products and Services Market Competitive Landscape
Top-tier vendors anchor high-throughput hospital laboratory placements, while mid-tier specialists compete on multiplexed assay menus and point-of-care portability. The vendor base stratifies across three archetypes: vertically integrated diagnostics conglomerates with global reagent supply chains, regional enzymatic assay specialists with premium positioning in reference laboratories, and portable device manufacturers targeting pharmacy clinic deployment. Competitive moves concentrate on strategic partnerships for artificial intelligence-enhanced risk stratification and geographic expansion into underpenetrated primary health center networks.
Among vertically integrated diagnostics conglomerates, Abbott Laboratories and Roche Diagnostics occupy positions that exemplify scale-driven reagent economics and installed base lock-in. Siemens Healthineers anchors the integrated informatics tier, representing how lipid results tie directly into cardiovascular risk scoring workflows. Randox Laboratories sits within the specialist camp, exemplifying premium positioning through multiplexed enzymatic assay portfolios targeted at reference laboratories demanding higher analytical specificity.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Quest Diagnostics |
| Ortho Clinical Diagnostics |
| Randox Laboratories |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Cholesterol esterase and oxidase enzyme procurement from Chinese contract manufacturers flows through three distinct pricing tiers before reaching end users, with CLIA-waived point-of-care strips commanding premium positioning against commoditized hospital reagent contracts in Germany and Japan.
Pricing Analysis
Bundled analyzer-reagent contracts versus unbundled consumable-only agreements define the pricing architecture across hospital procurement committees. Three-tier pricing structure across premium, standard, and economy levels separates integrated informatics systems from standalone enzymatic assays and basic photometric devices. Price differentiation rests on FDA 510(k) clearance tier and installed base lock-in effects. Cost compression in economy-tier strips is intensifying because pharmacy clinic volume aggregation concentrates buyer leverage. Employer wellness programs exhibit lowest price sensitivity, while Indian primary health centers demonstrate acute cost responsiveness.
Supply Chain Analysis
India's phased manufacturing program and local-content mandates for medical devices are reshaping sourcing patterns for electrochemical biosensor assembly. Enzyme production concentrates in China, reagent formulation clusters in Germany and the United States, while finished device assembly feeds from Malaysia and Mexico. Raw material dependencies span cholesterol oxidase biocatalysts, screen-printed electrode substrates, and optical filter components. Single-source vulnerability in Chinese enzyme supply exposes assay producers to customs disruption. Distribution runs through diagnostic laboratory GPOs in the United States, university hospital purchasing cooperatives in Germany, and municipal clinic tenders in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cholesterol testing market represents a late-cycle quality story as cardiovascular risk stratification demands shift toward lipoprotein subfractionation specificity and AI-integrated result interpretation.
For Market Incumbents: Anchor high-throughput laboratory placements through backward integration into proprietary reagent supply chains. Defend against point-of-care volume fragmentation by embedding lipid results directly into electronic health record cardiovascular risk scoring workflows. Prioritize FDA 510(k) clearance maintenance for moderate-complexity devices as CLIA personnel qualification gaps constrain competitor site expansion.
For New Entrants and Emerging Players: Capture whitespace in rural Indian primary health centers through portable reflectance photometry devices operable by auxiliary nurse midwives without laboratory infrastructure. Penetrate Germany's telemedicine-linked home testing channel under statutory health insurance reimbursement. Pursue white-label partnerships with pharmacy clinic chains rather than direct hospital sales.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory documentation burdens exceed annual R&D budgets for mid-size enzymatic assay developers. Long-term viability favors established multinationals with dedicated Tokyo regulatory affairs infrastructure under PMDA biennial surveillance mandates. Target acquisition archetype: regional specialists with multiplexed assay menus and premium reference laboratory positioning. Monitor EU In Vitro Diagnostic Regulation notified body capacity constraints as inflection signal for distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced Risk Stratification Partnership | Machine learning integration with Epic and Cerner EHRs personalizes statin therapy decisions. |
| CLIA-Waived Device Expansion | Pharmacy clinic deployment accelerates volume capture away from hospital core laboratories. |
| Reagent Contract Unbundling | German purchasing cooperatives negotiate consumable supply independent of analyzer vendors. |
| PMDA Local Quality Representation | Tokyo-based regulatory infrastructure secures supplier status in consolidated reference labs. |
| Rural India Diagnostic Penetration | Portable electrochemical devices address auxiliary nurse midwife-operated primary health centers. |
Research Methodology
Multiple input streams — regulatory filing databases, hospital procurement contract records, and enzyme supplier customs data — were reconciled against primary interviews with CLIA laboratory directors, diagnostic chain procurement executives, IVD regulatory affairs leads, and point-of-care device product managers. Secondary validation drew from FDA 510(k) clearances, PMDA quality management system submissions, EU MDR notified body assessments, and GPO contract disclosure filings. Bottom-up test volume modeling and top-down market sizing triangulated across the analysis window.
Historical reimbursement trajectory cross-referenced against panel input from purchasing cooperative negotiators and wellness program administrators shaped the analytical framework. Segmentation dimensions spanned product architecture, testing technology, application setting, and end-user procurement authority across the projection horizon. CAGRs derived from installed base erosion rates in centralized laboratories and point-of-care penetration curves in pharmacy clinics. Forecast inputs incorporated CLIA complexity categorization shifts and statutory insurance coverage expansion timelines.
Regulatory approval delays, enzyme supply disruption, and reimbursement code consolidation are the dominant revision risks to volume assumptions. Forecasts reflect documented policy trajectories without speculative regulatory acceleration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Forensic Testing Services Market
Testing Services
Mono Rapid Testing Market
Testing Services
In-Vitro Toxicology Testing Market
Testing Services
Asia Pacific Pregnancy and Ovulation Testing Market
Testing Services
Toxicology Testing Services Market
Testing Services
Mycological Testing Market
Testing Services
Toxicology Drug Screening Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
Global Terminal Sterilization Services Market
Testing Services
Global Vitamin D Testing Market
Testing Services
Esoteric Testing Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
Global Direct to Consumer Laboratory Testing Market
Testing Services
Platelet Function Test Market
Testing Services
STD Testing Devices Market