
 US Bowie Dick Test Pack Market | 2026-2036
US Bowie Dick Test Pack Market Size, Share, and Industry Trends Forecast 2026-2036
US Bowie Dick Test Pack Market Insights
US domestic production of sterilization consumables is pivoting toward higher-throughput manufacturing to serve hospital supply chains. STERIS leverages its installed base of sterilization equipment to anchor recurring test pack demand. Getinge AB sustains competitive pressure through integrated sterile processing workflows. Propper Manufacturing Co. Inc. specializes in indicator chemistry that meets ANSI/AAMI ST79 requirements.
A Bowie Dick test pack is a standardized challenge device containing a chemical indicator sheet placed within a defined pack configuration to detect air leaks and non-condensable gases in pre-vacuum steam sterilizers. The pack typically uses 100% cotton surgical towels arranged in a specific folded stack to create a standardized air removal barrier, with the indicator changing color when steam penetration is adequate. Chemical indicators and integrators command the majority of product type revenue due to their lower per-unit cost and higher testing frequency. Hospitals dominate end user demand, though ambulatory surgical centers represent the fastest-expanding segment as outpatient procedure volumes rise.
FDA oversight through 21 CFR Part 820 quality system regulations and AAMI ST79 guidelines shape product design and facility compliance obligations for test pack manufacturers. The Joint Commission's survey processes reinforce routine steam sterilization validation as a non-negotiable operational requirement. Stakeholders must monitor whether proposed updates to ANSI/AAMI sterilization standards will mandate more frequent Bowie Dick testing intervals or require enhanced indicator sensitivity specifications.
Market Dynamics
FDA's updated guidance on steam sterilization validation is tightening documentation requirements across healthcare facilities, forcing manufacturers to redesign indicator chemistry and hospitals to expand compliance budgets for routine Bowie Dick testing protocols.
Growth Catalysts
- ANSI/AAMI ST79 Compliance Mandates:The Joint Commission's survey processes reinforce routine steam sterilization validation as a non-negotiable operational requirement, driving consistent replacement demand for test packs in hospital sterile processing departments.
- Ambulatory Surgical Center Expansion:ASCs across the Midwest and Southeast are expanding sterilization compliance budgets as outpatient procedure volumes rise, creating new end-user segments beyond traditional hospital systems.
- Pre-Vacuum Steam Sterilizer Installation:Hospital construction activity concentrates in Texas, California, and Florida, each new sterilizer requiring standardized challenge devices for daily air removal verification.
Market Restraints
- Cotton Textile Input Volatility:Test packs rely on 100% cotton surgical towels arranged in standardized folded stacks, exposing manufacturers to fluctuations in medical-grade textile supply chains.
- Indicator Chemistry Concentration:Specialized chemical indicator production concentrates among limited suppliers capable of meeting FDA 21 CFR Part 820 quality system regulations for color-change reliability.
- Single-Use Disposable Economics:Each Bowie Dick test represents a consumable expense with no reusable alternative, creating budget friction for facilities managing high-throughput sterilization cycles.
Strategic Opportunities
- Southeast ASC Consolidation:Ambulatory surgical center roll-ups in Florida and Georgia create centralized procurement leverage, favoring suppliers offering integrated sterile processing workflow solutions.
- Enhanced Indicator Sensitivity Specifications:Proposed updates to ANSI/AAMI sterilization standards may mandate more frequent testing intervals or advanced detection thresholds, expanding per-facility consumption rates.
- Digital Documentation Integration:Test packs with scannable lot codes and automated result logging are expanding into hospital information systems, capturing compliance data for regulatory audits.
Industry Challenges
- Sterile Processing Technician Certification:Proper Bowie Dick test interpretation requires trained personnel, and workforce shortages in sterile processing departments delay validation protocols.
- Legacy Sterilizer Compatibility:Older pre-vacuum steam sterilizers in rural hospitals lack standardized pack dimensions, forcing manufacturers to maintain multiple product configurations.
- Documentation Burden Escalation:FDA's emphasis on traceable quality records extends beyond the test itself to storage conditions, expiration tracking, and corrective action logs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Bowie Dick Test Pack Market |
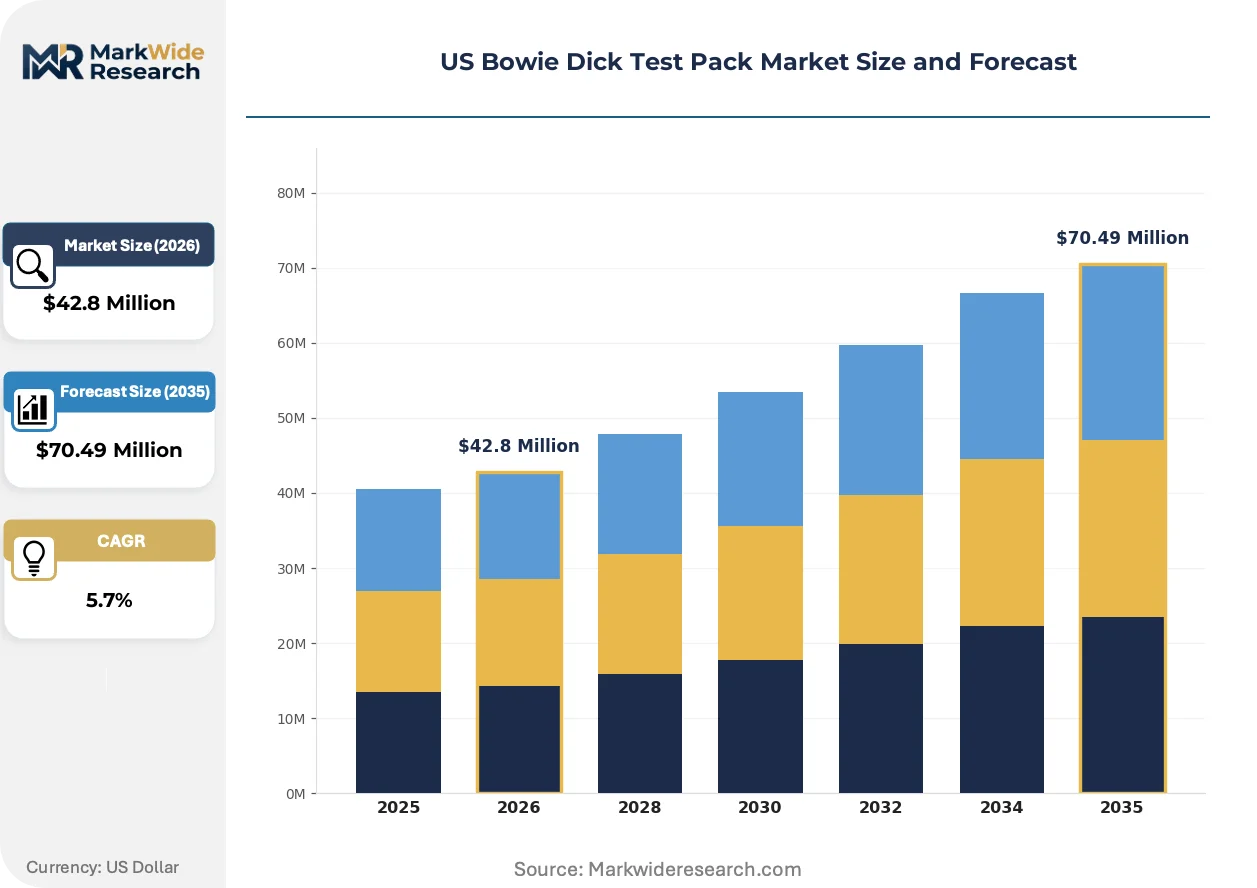
| Market Size in 2026 | $42.8 Million |
| Market Size in 2035 | $70.49 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Indicator, Integrator, Mechanical Monitor, Biological Indicator, Multi-Parameter Indicator End User: Hospitals, Ambulatory Surgical Centers, Dental Clinics, Diagnostic Laboratories, Research Centers Application: Steam Sterilization Validation, Quality Control, Autoclave Performance Testing, Sterilizer Leak Detection, Routine Monitoring Distribution Channel: Direct Sales, Medical Distributors, Online Marketplaces, Group Purchasing Organizations, Specialty Retailers |
| Companies Covered | Getinge AB, Propper Manufacturing Co. Inc., Medline Industries, Inc., Terragene, Mesa Labs, Inc., STERIS, Crosstex International, Inc., PMS Healthcare Technologies, 3M, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Bowie Dick Test Pack Market Trends and Innovations
Digital integration and materials science are converging to transform how sterile processing departments validate steam sterilization efficacy, moving beyond visual indicator interpretation toward automated compliance capture.
Self-interpreting chemical indicators with embedded RFID tags are expanding into hospital supply chains. These smart test packs transmit pass/fail results directly to sterile processing information management systems. Large health systems in California and Texas are piloting this technology to eliminate manual documentation errors. The shift is expanding into mid-tier hospitals seeking Joint Commission survey readiness.
FDA's 21 CFR Part 820 quality system regulations now explicitly address software validation for automated test result interpretation. This policy shift requires manufacturers to submit enhanced design control documentation for digitally-enabled indicators. Hospital systems with enterprise resource planning integration capabilities are most affected, prioritizing vendors with pre-validated data exchange protocols.
Bulk purchasing consortia among ASC networks are compressing traditional distributor relationships. These buying groups negotiate direct manufacturer contracts, unbundling test packs from broader sterilization supply agreements. The pattern is most visible in Florida's consolidated outpatient surgery market, where multi-site operators standardize across dozens of locations.
US Bowie Dick Test Pack Market Segmentation
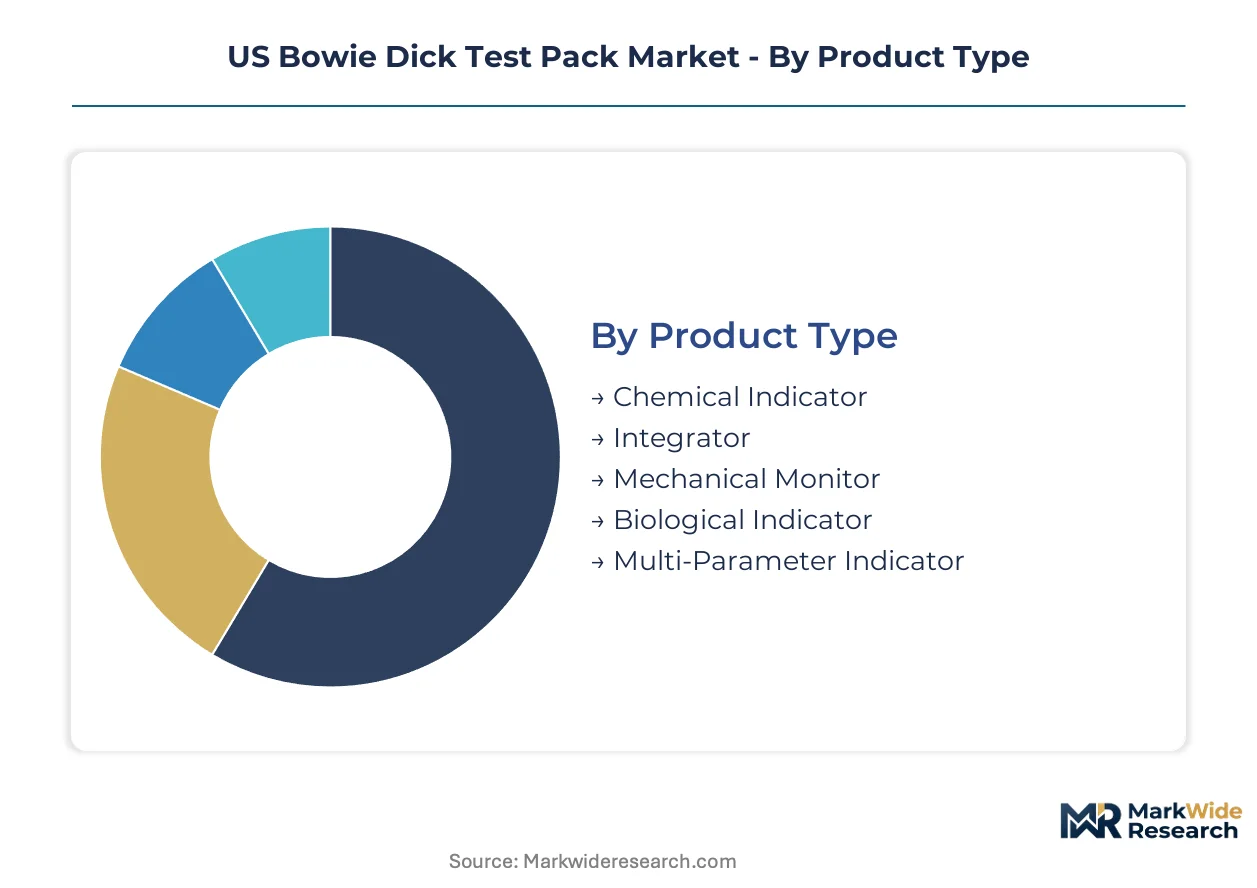
Segmentation in the US Bowie Dick test pack market reveals how sterilization validation requirements diverge across facility types and testing protocols. Product chemistry, end-user scale, and procurement channel each create distinct competitive battlegrounds with specialized margin structures.
Product Type:
Supply concentration in indicator chemistry manufacturing shapes competitive dynamics across product categories.
- Chemical Indicator:Color-change sheets embedded within standardized cotton towel stacks provide immediate visual confirmation of steam penetration adequacy. Texas and Florida hospitals consume the majority of volume as construction expands sterile processing capacity in these states. FDA 21 CFR Part 820 documentation requirements force manufacturers to validate each lot for color reliability under varying steam conditions.
- Integrator:Multi-parameter devices combine time, temperature, and steam saturation into a single cumulative response, offering higher confidence than basic indicators. ASC consolidation across the Southeast is accelerating integrator adoption as multi-site operators standardize on more sophisticated validation protocols to satisfy Joint Commission surveyors. The per-unit cost premium limits penetration in budget-constrained rural facilities.
- Mechanical Monitor:Pressure-temperature recording devices that document sterilizer cycle parameters independently of chemical confirmation. These units serve legacy sterilizer installations requiring redundant validation documentation.
- Biological Indicator:Spore-based challenge devices incubated post-cycle to confirm lethality, representing the gold standard for quarterly sterilizer efficacy verification. Long turnaround times restrict use to validation rather than routine monitoring.
- Multi-Parameter Indicator:Hybrid devices combining chemical response with digital data capture capabilities. Emerging specifications from ANSI/AAMI ST79 working groups are expanding addressable demand for these advanced formats.
Today's leader: Chemical Indicator. Tomorrow's challenger: Integrator.
End User:
Customer scale and procedure volume determine testing frequency and pack consumption economics.
- Hospitals:Large acute-care facilities with centralized sterile processing departments execute daily Bowie Dick cycles across multiple pre-vacuum sterilizers. California health systems lead in digital documentation integration, piloting RFID-enabled test packs that transmit results directly to information management systems. The installed base of aging sterilizers in rural Midwest hospitals creates compatibility challenges for standardized pack dimensions.
- Ambulatory Surgical Centers:Outpatient facilities with limited sterilizer counts represent the steepest expansion trajectory as procedure volumes shift from inpatient settings. ASC roll-ups in Florida and Georgia are consolidating procurement through direct manufacturer contracts, bypassing traditional distributor markups. Sterile processing technician certification gaps in smaller facilities delay proper test interpretation and documentation compliance.
- Dental Clinics:Smaller-scale steam sterilization operations with intermittent testing requirements and price-sensitive purchasing patterns. Group purchasing organization participation remains limited in this fragmented segment.
- Diagnostic Laboratories:Specialized facilities requiring sterilization validation for culture media and contaminated specimen processing. Testing protocols vary significantly by laboratory certification type.
- Research Centers:Academic and pharmaceutical research facilities with non-standard sterilization loads requiring customized challenge device configurations. Volume concentration remains minimal relative to clinical healthcare settings.
Hospitals anchor current revenue. ASC networks are climbing the fastest.
Application:
Regulatory mandate intensity varies sharply across testing purpose, creating tiered compliance investment requirements.
- Steam Sterilization Validation:Mandatory daily air removal verification for pre-vacuum sterilizers under ANSI/AAMI ST79 guidelines. The Joint Commission survey process treats documentation gaps as immediate deficiencies, compelling consistent replacement demand regardless of budget pressures.
- Quality Control:Lot release testing and incoming material sterilization validation in pharmaceutical manufacturing. FDA's updated guidance on steam sterilization validation is tightening documentation requirements for manufacturers serving this segment.
- Autoclave Performance Testing:Commissioning and annual requalification protocols for new and refurbished sterilizer installations. Hospital construction activity in Texas and California directly correlates with cyclical demand spikes in this category.
- Sterilizer Leak Detection:Diagnostic applications identifying mechanical failures in vacuum pumps or door seals. Testing frequency accelerates when preventive maintenance schedules slip.
- Routine Monitoring:Shift-level confirmation of sterilizer readiness in high-throughput departments. Budget friction emerges in facilities processing dozens of cycles daily with single-use economics.
Steam Sterilization Validation dominates volume. Quality Control is gaining share fastest.
Distribution Channel:
Channel economics reflect customer scale and procurement sophistication fragmentation.
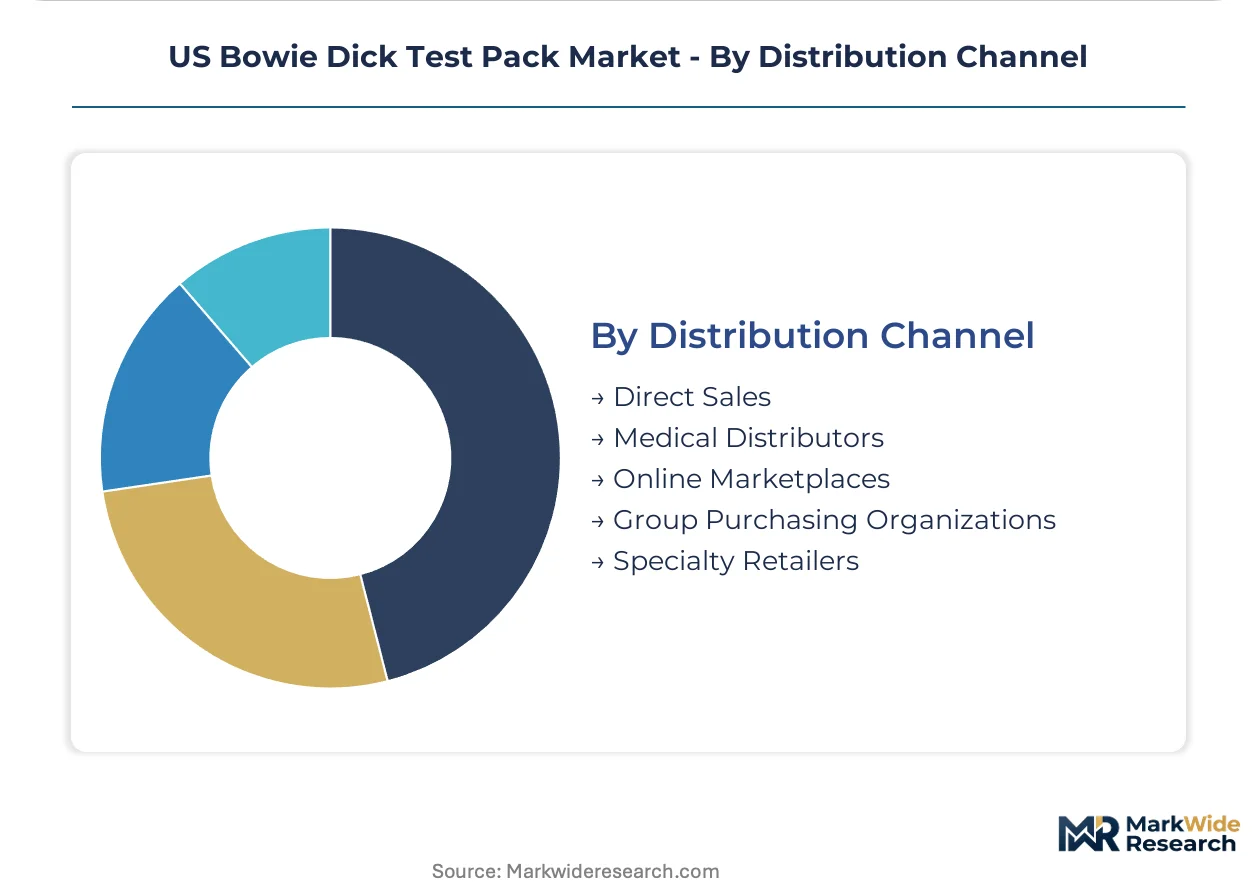
- Direct Sales:Manufacturer relationships with large health systems and ASC networks enabling customized lot sizing and consignment inventory arrangements. Bulk purchasing consortia in Florida's consolidated outpatient surgery market are compressing traditional distributor relationships through direct contracting.
- Medical Distributors:Regional and national distributors serving mid-tier hospitals and independent ASCs with bundled sterilization supply offerings. Value-added services include expiration date tracking and emergency stock rotation.
- Online Marketplaces:E-commerce platforms capturing price-sensitive smaller facilities and emergency replenishment orders. Product authenticity verification concerns limit penetration in regulated healthcare settings.
- Group Purchasing Organizations:Negotiated contracts aggregating demand across hospital networks and multi-site ASC operators. GPO compliance requirements favor suppliers with validated quality management systems.
- Specialty Retailers:Niche distributors serving dental and veterinary markets with smaller pack quantities and alternative product configurations. Geographic coverage concentrates in metropolitan dental corridor clusters.
Medical Distributors hold position. Direct Sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of Bowie Dick test packs migrates toward states with lower cost-of-compliance frameworks for medical textile processing, while demand concentrates where hospital construction and ASC consolidation accelerate sterilization validation requirements.
Texas
Hospital construction in Houston and Dallas-Fort Worth drives sterilizer commissioning demand, with new pre-vacuum installations requiring daily air removal verification. Texas Health and Human Services enforces sterilization documentation standards aligned with Joint Commission survey protocols. The Texas Medical Center in Houston anchors the largest concentration of sterile processing capacity in the southern United States.
California
Health systems in Los Angeles and San Francisco pilot RFID-enabled test packs with automated documentation integration into electronic health records. California's Office of Statewide Health Planning and Development mandates construction standards for central sterile supply departments in new hospital builds. Stanford Health Care and Cedars-Sinai Medical Center represent early adopters of digital sterilization validation workflows.
Florida
ASC roll-ups across Miami, Tampa, and Orlando consolidate procurement through direct manufacturer contracts, bypassing traditional distributor channels. Florida's Agency for Health Care Administration inspects outpatient surgical facilities for ANSI/AAMI ST79 compliance during licensure renewals. The I-4 corridor between Tampa and Orlando hosts the densest cluster of multi-site ambulatory surgery operators in the Southeast.
Illinois
Chicago-area health systems manage aging sterilizer fleets requiring legacy-compatible pack configurations and enhanced leak detection protocols. Illinois Department of Public Health surveys enforce documentation requirements for corrective action logs when Bowie Dick tests fail. Rush University Medical Center and Northwestern Memorial Hospital anchor sterile processing training programs addressing technician certification gaps.
Georgia
Atlanta's expanding ASC networks standardize integrator adoption across consolidated platforms to satisfy Joint Commission survey readiness. Georgia Department of Community Health regulates ambulatory surgery centers through facility licensure and Medicare certification surveys. Piedmont Healthcare and Emory Healthcare systems drive standardization of sterile processing protocols across their metropolitan networks.
US Bowie Dick Test Pack Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital documentation integration and smart indicator technologies. The market structures around three player tiers: integrated sterilization equipment manufacturers with captive test pack demand; specialized indicator chemistry producers serving multi-vendor equipment bases; and regional textile converters assembling standardized cotton towel configurations. Dominant competitive moves include strategic partnerships with health information system vendors and capacity expansion in high-throughput manufacturing to serve ASC procurement consortia.
Among Sweden-based multinationals, Getinge AB exemplifies the integrated equipment-captive archetype, leveraging sterilizer installed bases to anchor recurring consumable demand. Propper Manufacturing Co. Inc. represents specialized indicator chemistry capability, occupying a position within the compliance-focused supplier tier. STERIS anchors the North American integrated platform segment, with its equipment-service-consumable bundling creating procurement stickiness in hospital systems. These three patterns—equipment integration, chemistry specialization, and platform bundling—define competitive positioning across procurement channels.
| Leading Market Players |
|---|
| Getinge AB |
| Propper Manufacturing Co. Inc. |
| Medline Industries, Inc. |
| Terragene |
| Mesa Labs, Inc. |
| STERIS |
| Crosstex International, Inc. |
| PMS Healthcare Technologies |
| 3M |
| Others |
Pricing and Supply Chain Analysis
Captive integration into indicator chemistry manufacturing anchors both supply security and margin control for test pack producers serving FDA-regulated healthcare facilities. STERIS and Getinge AB leverage in-house production of color-change reagents to buffer against raw material volatility while commanding premium positioning in hospital procurement channels.
Pricing Analysis
Distributor margin compression is reshaping how test packs reach end users as bulk purchasing consortia among ASC networks negotiate direct manufacturer contracts. Three-tier pricing structure across premium integrator, standard chemical indicator, and economy mechanical monitor levels reflects certification grade and digital documentation capabilities. Cost compression in the economy tier is intensifying because cotton textile input volatility squeezes converters with limited backward integration. Ambulatory surgical centers exhibit highest price sensitivity due to single-use disposable economics, while integrated health systems prioritize compliance-grade premiums over per-unit cost.
Supply Chain Analysis
Single-source vulnerability sits with medical-grade cotton textile suppliers concentrated in India, Pakistan, and the United States for surgical towel production. Indicator chemistry production draws from specialized reagent manufacturers in Germany, Japan, and the United States capable of meeting FDA 21 CFR Part 820 quality system regulations. Tariff exposure on imported cotton textiles threatens margin stability for domestic pack assemblers. Distribution runs through medical distributors serving mid-tier hospitals, direct sales for large health systems, and group purchasing organizations aggregating ASC network demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in digital documentation integration as RFID-enabled test packs capture compliance data premiums while reducing manual labor costs for sterile processing departments.
For Market Incumbents: Deploy GPO contract leverage to lock out emerging competitors before ASC consolidation completes in Florida and Georgia. Expand indicator chemistry capacity in low-cost manufacturing zones to offset cotton textile volatility. Digital documentation integration from California health systems threatens equipment-captive bundling advantages; pre-empt with validated data exchange protocols. For New Entrants and Emerging Players: Direct-to-ASC digital channels offer the lowest barrier to procurement access as multi-site operators standardize across dozens of locations. Target rural Midwest hospitals with legacy sterilizer compatibility packs where incumbents maintain minimal SKU diversity. Partner with sterile processing information management system vendors for pre-integrated validation workflows. For Investors and Strategic Acquirers: Roll-up economics work for specialized indicator chemistry producers because FDA quality system documentation creates regulatory moats that scale across acquired platforms. Five-to-ten year viability hinges on ANSI/AAMI ST79 standard updates mandating enhanced sensitivity specifications. Watch for proposed testing interval changes as the inflection signal for per-facility consumption rate expansion.| Strategic Initiative | Industry Significance |
|---|---|
| RFID-Enabled Test Pack Development | Stanford Health Care pilots automated compliance capture eliminating manual documentation errors in sterile processing departments. |
| Indicator Chemistry Capacity Expansion | Low-cost manufacturing zones buffer FDA-validated producers against cotton textile input volatility from South Asian suppliers. |
| Direct ASC Network Contracting | Florida's I-4 corridor consolidation favors suppliers bypassing traditional distributor markups through multi-site procurement standardization. |
| Legacy Sterilizer Compatibility Programs | Rural Midwest hospital demand for non-standard pack dimensions creates defensible niche against equipment-integrated competitors. |
| Software Validation Documentation Investment | FDA 21 CFR Part 820 updates for automated result interpretation require enhanced design control submissions from digital indicator developers. |
Research Methodology
Multiple input streams — sterile processing department managers, biomedical equipment technicians, GPO contracts managers, and FDA regulatory consultants — were reconciled against hospital procurement databases, FDA 510(k) filings, ANSI/AAMI standards documentation, and state health department inspection records. Primary interviews with sterile processing directors at Texas Medical Center and Cedars-Sinai Medical Center informed digital adoption timelines. Bottom-up facility-level testing frequency estimates were triangulated with top-down manufacturer shipment data.
Historical consumption patterns were cross-referenced against panel input from sterilization equipment manufacturers and indicator chemistry suppliers to build the analytical framework. Segmentation dimensions modeled include product chemistry tier, end-user facility scale, application purpose, and distribution channel structure across the projection horizon. CAGRs were derived from sterilizer installation forecasts correlated with Joint Commission survey compliance mandates. Industry-specific inputs incorporated FDA guidance update timelines and ASC construction permit data from Texas, California, and Florida.
The model assumes a particular technology adoption path; alternative pathways for RFID-enabled documentation integration would alter the outlook if health system ERP integration costs prove prohibitive. Forecasts reflect assumptions about ANSI/AAMI standards evolution and sterile processing technician certification pipeline recovery. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Vials Leak Testing Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Endocrine Peptides Test Market
Testing Services
Faecal Calprotectin Testing Market
Testing Services
Testing and Analysis Services Market
Testing Services
Global Extractables and Leachables Testing Services Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Bimetallic Thermometer Market
Testing Services
Vaginal Panel Testing Market
Testing Services
D-Dimer Testing Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Radiographic Testing Market
Testing Services
Nicotine Testing Market
Testing Services
Fungal Testing Kits Market
Testing Services
United States Testing, Inspection, and Certification (TIC) Market