
 Nucleic Acid Testing Market | 2026-2036
Nucleic Acid Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Nucleic Acid Testing Market Analysis
North American reagent manufacturers is restructuring supply chains to secure polymerase enzyme feedstocks amid raw material constraints. Danaher Corporation anchors its position through integrated consumables-instrument workflows that lock in recurring revenue streams. Thermo Fisher Scientific leverages its distribution density across diagnostic laboratories to sustain volume leadership in PCR-based platforms. Abbott Laboratories differentiates through point-of-care nucleic acid systems that reduce turnaround times in hospital emergency departments.
Nucleic acid testing encompasses molecular diagnostic methods that detect and amplify specific DNA or RNA sequences through enzymatic processes, typically operating at picogram sensitivity thresholds for pathogen identification or genetic variation analysis. Polymerase Chain Reaction dominates installed base volumes but faces margin compression as commoditization spreads across thermal cycler hardware. Next-Generation Sequencing captures the fastest expansion trajectory in oncology companion diagnostics, where tumor profiling depth justifies premium pricing. Infectious disease applications retain the largest revenue pool, though genetic testing segments show the steepest reagent consumption growth curves.
FDA premarket review pathways and CLIA laboratory certification standards shape product development timelines and commercial access for US manufacturers. EMA's In Vitro Diagnostic Regulation in Europe imposes stricter clinical evidence requirements that favor established players with robust quality management systems. WHO prequalification programs for tuberculosis and HIV nucleic acid assays direct procurement flows in low-resource settings. Stakeholders must weigh regulatory capital requirements against the defensive moats that complex compliance creates for incumbent suppliers.
Market Dynamics
Polymerase enzyme feedstock scarcity is forcing reagent manufacturers to restructure supply chains and lock in long-term enzyme sourcing contracts, compressing margins for non-integrated players while securing volume commitments for vertically anchored suppliers.
Growth Catalysts
- CLIA laboratory certification expansion:US clinical diagnostic laboratories are broadening molecular testing menus to meet tightening FDA premarket review standards for assay validation, driving platform refresh cycles.
- Oncology companion diagnostic depth:Tumor profiling applications justify premium pricing for next-generation sequencing workflows, accelerating reagent consumption in cancer centers.
- India:Diagnostic laboratory networks in Mumbai and Bangalore are absorbing PCR kit volumes at accelerating rates as healthcare infrastructure scales.
Market Restraints
- Polymerase supply concentration:Thermal-stable enzyme production concentrates among specialized fermentation facilities, exposing reagent manufacturers to input bottlenecks.
- PCR hardware commoditization:Thermal cycler margins compress as open-platform instruments proliferate, eroding instrument revenue pools.
- WHO prequalification timelines:Stringent evidentiary requirements for tuberculosis and HIV nucleic acid assays delay market access in low-resource procurement channels.
Strategic Opportunities
- Point-of-care emergency deployment:Hospital emergency departments in the United States are adopting rapid nucleic acid systems that reduce turnaround times below one hour.
- Integrated consumables-instrument workflows:Closed-system platforms lock in recurring revenue streams through proprietary cartridge formats.
- EMA In Vitro Diagnostic Regulation:Stricter clinical evidence requirements in Europe favor established manufacturers with robust quality management systems, creating defensive moats.
Industry Challenges
- Bioinformatics talent scarcity:Next-generation sequencing data interpretation requires specialized computational biology expertise that outpaces current training pipelines.
- Legacy LIS integration:Molecular diagnostic platforms must interface with entrenched laboratory information systems, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nucleic Acid Testing Market |
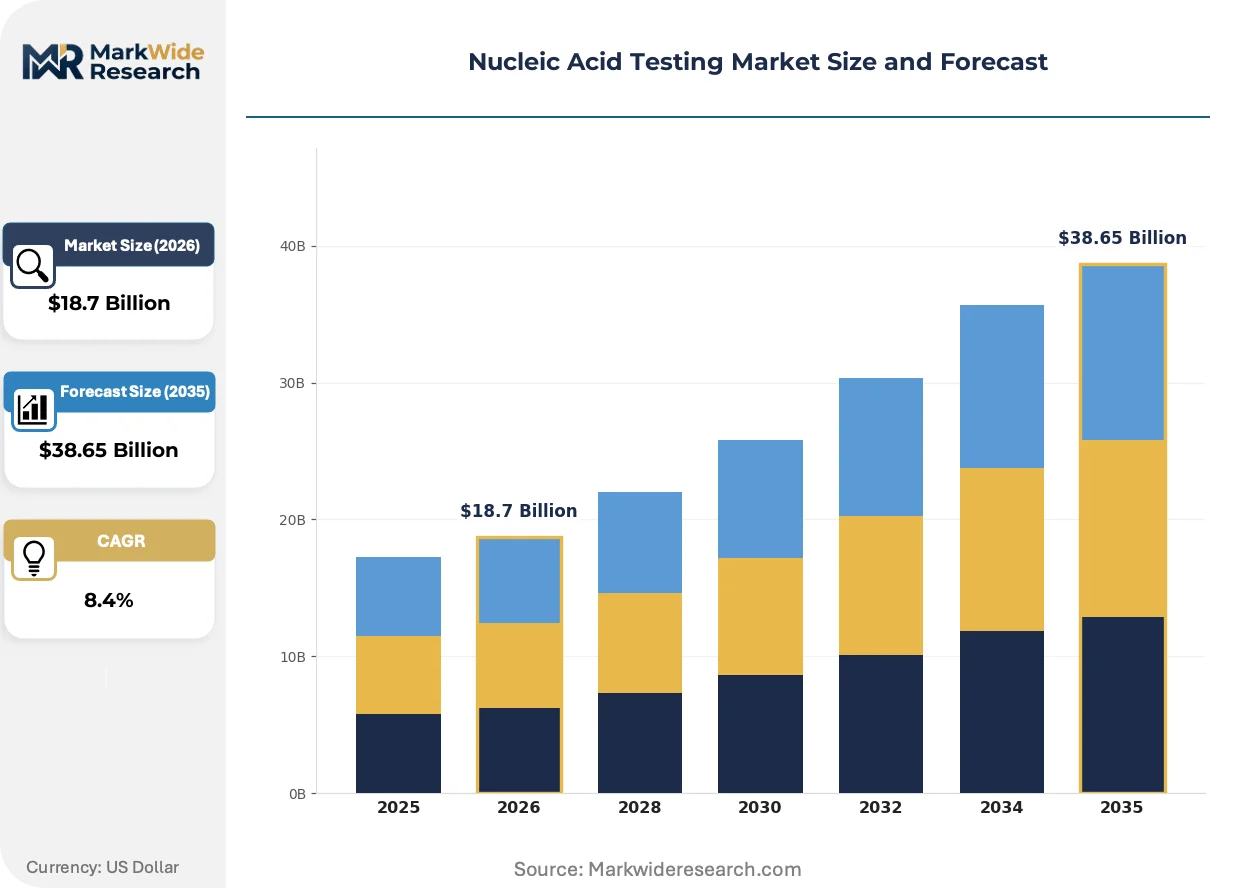
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Polymerase Chain Reaction, Next-Generation Sequencing, CRISPR, Microarray Product Type: Reagents, Kits, Instruments, Software Application: Infectious Diseases, Cancer Research, Genetic Testing, Forensic Testing End User: Hospitals, Diagnostic Laboratories, Contract Research Organizations, Academic Institutions |
| Companies Covered | Danaher Corporation, Thermo Fisher Scientific, Abbott Laboratories, F. Hoffmann-La Roche, Merck KGaA, Becton Dickinson, Illumina, Siemens Healthineers, bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nucleic Acid Testing Market Emerging Trajectories
Digital PCR and isothermal amplification methods are fragmenting the installed base away from traditional thermal cycling, while regulatory premarket pathways reshape product development timelines and commercial access strategies.
CRISPR-based diagnostic platforms are unifying nucleic acid detection with gene editing infrastructure, enabling programmable pathogen identification without thermal cycling hardware. Veterinary diagnostics laboratories in Germany and academic medical centers in Japan are piloting these systems for point-of-care infectious disease screening. The technology is unifying previously separate amplification and detection steps into single-reaction workflows, compressing assay development timelines for emerging pathogens.
REACH chemical registration requirements in Europe are imposing substance documentation burdens on polymerase stabilizer formulations and fluorescent probe chemistries used in nucleic acid kits. Manufacturers must submit toxicity dossiers for reagent components previously exempt from chemical safety scrutiny. In vitro diagnostic firms with established regulatory affairs teams in Basel and Amsterdam are absorbing compliance costs faster than mid-scale competitors, shifting competitive position in the European reagent market.
Diagnostic procurement committees now mandate total cost-of-ownership analyses that weight consumable pricing against throughput capacity and service response times. Hospital laboratory networks in Texas and California are consolidating vendor relationships around integrated platform providers, displacing best-of-breed instrument-reagent combinations. This concentration pattern is most visible in United States health system purchasing cooperatives, where multi-hospital contracts favor suppliers with captive reagent supply and field service density.
Nucleic Acid Testing Market Segmentation
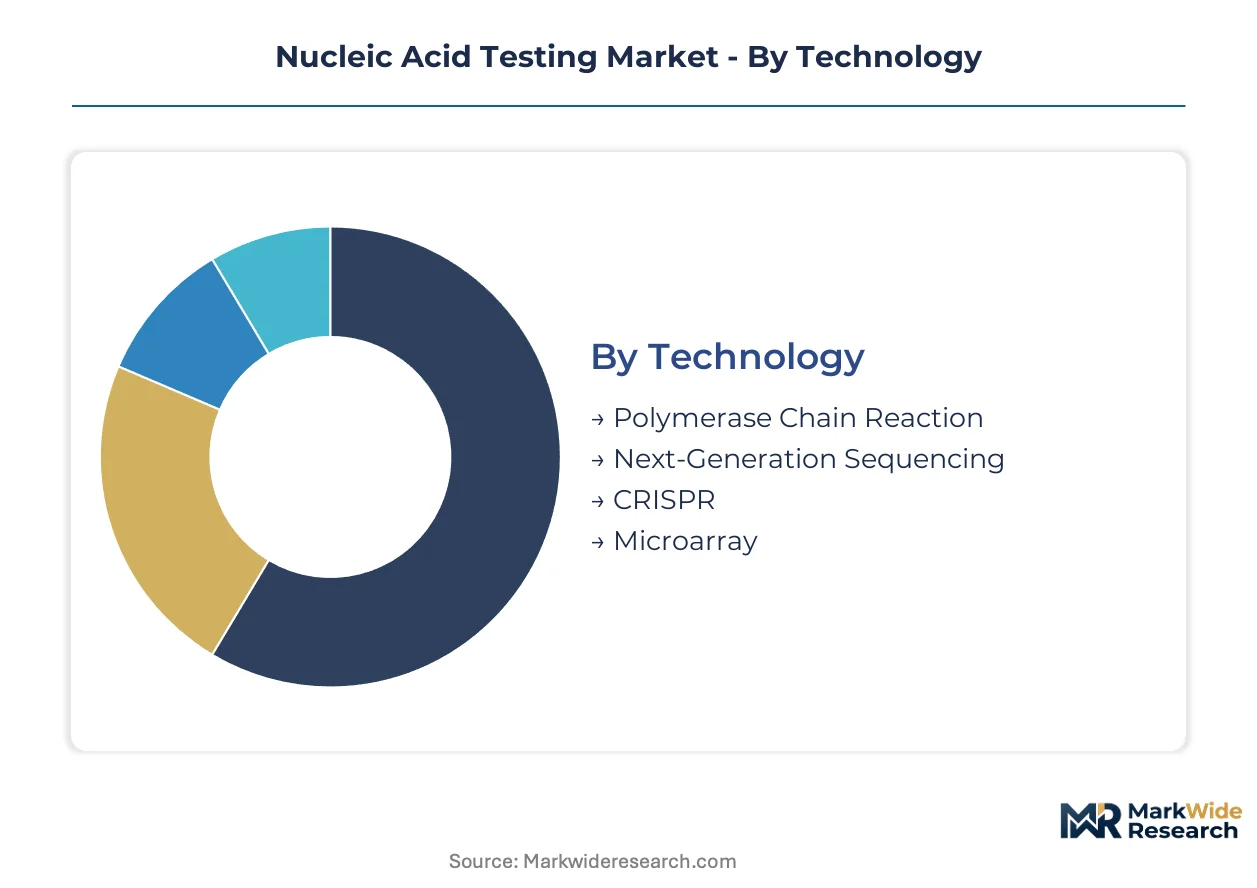
Nucleic acid testing markets fragment along technology maturity curves and workflow integration depth. Segment boundaries increasingly blur as platform providers bundle reagents, instruments, and analytics into unified offerings.
Technology:
Standalone thermal cycling platforms dominate installed base economics, while embedded molecular detection systems reshape point-of-care deployment models.
- Polymerase Chain Reaction:Enzymatic amplification of DNA/RNA targets through temperature cycling achieves picogram sensitivity thresholds. Hospital laboratories in the United States absorb thermal cycler refreshes as CLIA certification standards tighten assay validation requirements.
- Next-Generation Sequencing:Massively parallel readout technologies enable tumor profiling depth that justifies premium reagent pricing in oncology companion diagnostics. Cancer centers in Germany and Japan are expanding sequencing capacity to capture somatic mutation panels.
- CRISPR:Programmable nucleic acid detection unifies amplification and identification into single-reaction workflows without thermal hardware. Veterinary diagnostics laboratories pilot these systems for rapid pathogen screening.
- Microarray:Solid-phase hybridization platforms support high-plex genetic variation analysis in academic research settings.
Volume placements concentrate in Polymerase Chain Reaction; the faster expansion belongs to Next-Generation Sequencing.
Product Type:
Margin structures diverge sharply between recurring consumable revenue and capital-intensive instrument sales.
- Reagents:Polymerase enzymes, primers, and fluorescent probes constitute the largest recurring revenue pool. Manufacturers face feedstock scarcity as thermal-stable enzyme production concentrates among specialized fermentation facilities.
- Kits:Pre-formulated assay panels reduce laboratory preparation time and standardize workflow outputs. Diagnostic networks in Mumbai and Bangalore scale PCR kit procurement as molecular testing menus broaden.
- Instruments:Thermal cyclers and sequencing platforms face hardware commoditization as open-system architectures proliferate.
- Software:Bioinformatics pipelines for variant calling and pathogen identification require specialized computational biology expertise that outpaces training pipelines.
Reagent volumes anchor manufacturer profitability; kit standardization is gaining share fastest among mid-scale laboratories.
Application:
Disease-area economics range from high-volume infectious disease screening to precision oncology with premium pricing power.
- Infectious Diseases:Pathogen identification for tuberculosis and HIV directs procurement flows through WHO prequalification programs. Low-resource settings depend on nucleic acid assays for antimicrobial resistance surveillance.
- Cancer Research:Tumor profiling and liquid biopsy applications drive reagent consumption in academic medical centers. Companion diagnostic development creates regulatory complexity that favors established assay manufacturers.
- Genetic Testing:Carrier screening and pharmacogenomic analysis expand in direct-to-consumer and clinical channels.
- Forensic Testing:DNA profiling for criminal justice and paternity applications operates under strict chain-of-custody protocols.
Infectious disease applications retain volume leadership; genetic testing climbs the fastest as reimbursement frameworks mature.
End User:
Procurement authority and workflow integration requirements shape vendor selection across institutional categories.
- Diagnostic Laboratories:High-throughput facilities in Texas and California consolidate vendor relationships around integrated platform providers. Multi-hospital purchasing cooperatives favor suppliers with captive reagent supply and field service density.
- Hospitals:Emergency departments in the United States deploy point-of-care nucleic acid systems to compress turnaround times below one hour. Rapid influenza and respiratory pathogen detection drives capital allocation.
- Contract Research Organizations:Outsourced clinical trial support demands flexible assay validation and regulatory documentation capabilities.
- Academic Institutions:Research laboratories pilot CRISPR-based diagnostics and isothermal amplification methods before commercial translation.
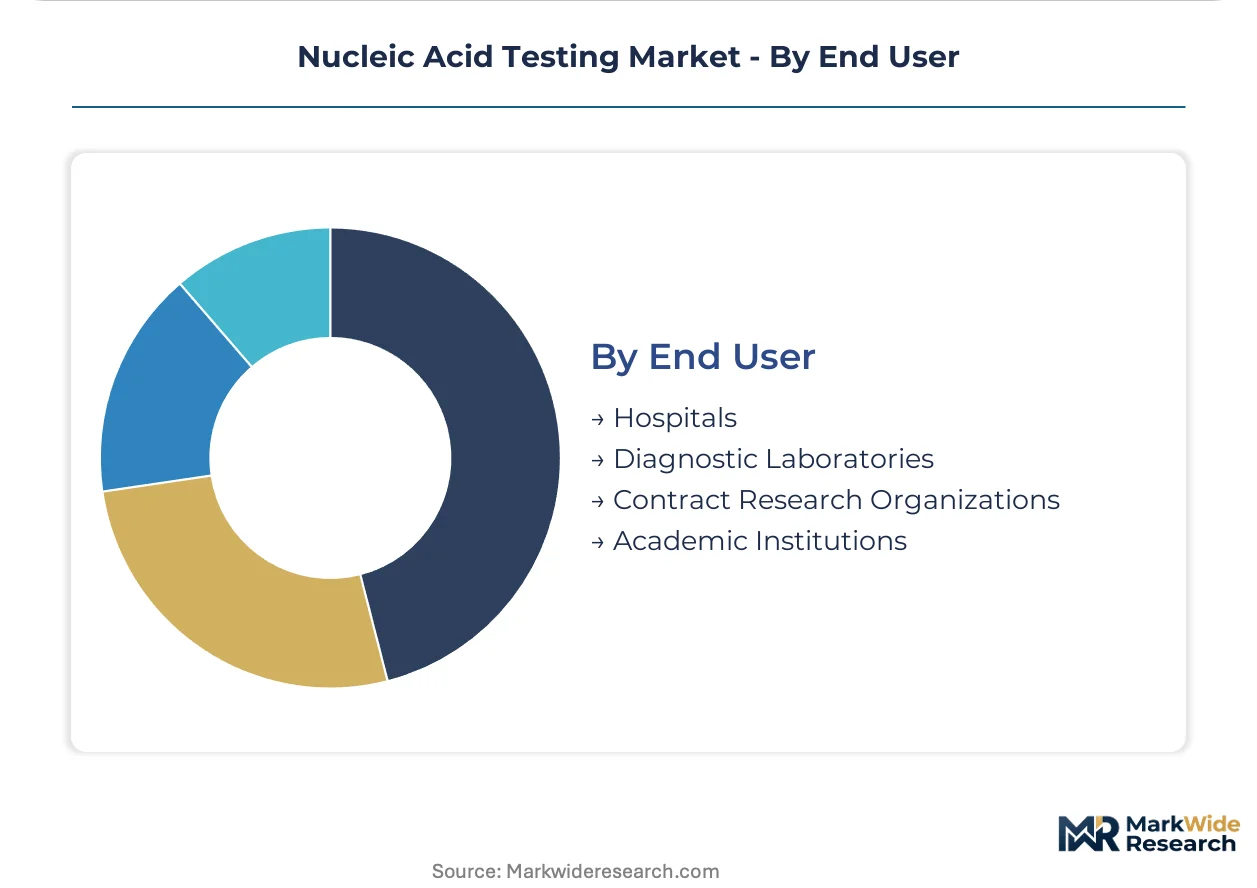
Diagnostic laboratories command the largest procurement volumes; hospital point-of-care adoption shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fermentation facilities in Denmark and the Netherlands anchor polymerase enzyme feedstock supply, concentrating upstream reagent production capacity in Northern Europe while downstream testing demand fragments across diagnostic laboratory networks in multiple countries.
United States
Hospital emergency departments in Texas and California are deploying rapid nucleic acid systems to compress pathogen detection turnaround times below sixty minutes. FDA premarket review pathways and CLIA laboratory certification standards shape assay validation timelines for domestic manufacturers. Multi-hospital purchasing cooperatives in the Southwest are consolidating vendor relationships around integrated platform providers with captive reagent supply.
Germany
Cancer centers in Munich and Heidelberg are expanding next-generation sequencing capacity to capture somatic mutation panels for oncology companion diagnostics. EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements that favor established manufacturers with robust quality management systems. Veterinary diagnostics laboratories in Bavaria are piloting CRISPR-based diagnostic platforms for rapid pathogen screening.
China
Diagnostic laboratory networks in Shanghai and Beijing are absorbing PCR kit volumes at accelerating rates as molecular testing menus broaden across tertiary hospitals. NMPA regulatory pathways for in vitro diagnostics are tightening assay validation standards. Yangtze River Delta bioclusters are scaling fermentation capacity for thermal-stable enzyme production to reduce import dependence.
India
Diagnostic networks in Mumbai and Bangalore are scaling PCR kit procurement as private healthcare infrastructure expands molecular testing capabilities. CDSCO regulatory frameworks are aligning with international standards for nucleic acid assay approval. Maharashtra's diagnostic laboratory corridors are consolidating around integrated reagent-instrument workflows to reduce total cost-of-ownership.
Japan
Academic medical centers in Tokyo and Osaka are piloting isothermal amplification methods and CRISPR-based diagnostics before commercial translation. PMDA regulatory review maintains rigorous clinical evidence standards for novel nucleic acid platforms. Kanto region research institutes are advancing digital PCR applications for liquid biopsy oncology workflows.
Nucleic Acid Testing Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue point-of-care miniaturization and CRISPR-based detection architectures. The vendor base concentrates around integrated consumables-instrument workflows that lock in recurring revenue through proprietary cartridge formats. Three archetypes dominate: vertically anchored suppliers controlling polymerase feedstocks, distribution-dense platform providers sustaining volume leadership, and rapid-turnaround point-of-care specialists. Competitive moves center on backward integration into enzyme fermentation capacity and multi-hospital purchasing cooperative consolidation.
Among diversified life science conglomerates, Danaher Corporation, Thermo Fisher Scientific, and Abbott Laboratories exemplify contrasting strategic positions. Danaher anchors the integrated workflow archetype through consumables-instrument combinations. Thermo Fisher Scientific represents distribution density advantages across diagnostic laboratory networks. Abbott Laboratories occupies the point-of-care rapid deployment tier with emergency department-focused systems. These three entities collectively illustrate how feedstock control, channel reach, and turnaround speed differentiate competitive positioning in nucleic acid testing.
| Leading Market Players |
|---|
| Danaher Corporation |
| Thermo Fisher Scientific |
| Abbott Laboratories |
| F. Hoffmann-La Roche |
| Merck KGaA |
| Becton Dickinson |
| Illumina |
| Siemens Healthineers |
| bioMérieux |
| Others |
Supply Flow & Price Mechanics
CRISPR-based diagnostic platforms are compressing traditional thermal cycler economics while concentrating polymerase enzyme production among Northern European fermentation specialists. This dual shift simultaneously erodes hardware margins and elevates feedstock pricing power for integrated reagent manufacturers.
Pricing Analysis
Extended warranty and field service bundling separates premium platform providers from unbundled instrument vendors in procurement evaluations. Three-tier pricing structure across premium, standard, and economy levels reflects CLIA certification grade and throughput capacity. Cost compression in open-system thermal cyclers is intensifying because hardware commoditization spreads across Asian manufacturers. Mid-scale diagnostic laboratories in India and Brazil exhibit highest price sensitivity; cancer centers in Germany and Japan show least sensitivity due to companion diagnostic reimbursement frameworks.
Supply Chain Analysis
Direct-to-laboratory channels handle high-throughput reagent demand from consolidated diagnostic networks in Texas and California. Upstream polymerase enzyme production concentrates in Denmark, the Netherlands, and emerging Yangtze River Delta bioclusters in China. Thermal-stable enzyme fermentation, fluorescent probe chemistries, and specialized plastic consumables constitute critical input dependencies. Single-source vulnerability runs through Danish fermentation facilities supplying Taq polymerase variants. Distribution runs through multi-hospital purchasing cooperatives and GPO contracts in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nucleic acid testing sector is transitioning from thermal cycling hardware to enzymatic detection methods that eliminate capital-intensive instrumentation. Isothermal amplification and CRISPR-based platforms are displacing legacy PCR workflows across point-of-care and research applications.
For Market Incumbents: Acquire polymerase fermentation capacity to secure enzyme feedstock supply against raw material scarcity. Lock in multi-year reagent supply contracts with diagnostic laboratory networks in Texas and California before CLIA certification standards tighten further. Integrate consumables-instrument workflows into closed-system platforms to defend recurring revenue streams against open-system commoditization. For New Entrants and Emerging Players: Telehealth-integrated diagnostic platforms offer direct-to-patient nucleic acid testing routes that bypass consolidated hospital procurement committees. Target veterinary diagnostics laboratories in Germany and academic medical centers in Japan as white-space segments with lower regulatory barriers than human clinical applications. Pursue CRISPR-based point-of-care systems for rapid pathogen screening in emergency departments. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified life science conglomerates seeking point-of-care molecular capabilities. Long-term viability favors vertically anchored suppliers controlling polymerase feedstocks and integrated workflow providers with captive reagent supply. Watch FDA premarket review pathway expansions for CRISPR-based diagnostics as inflection indicator for platform transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Polymerase Fermentation Capacity Acquisition | Secures enzyme feedstock supply against Northern European production concentration. |
| CLIA Laboratory Certification Investment | Enables assay validation for high-complexity molecular testing menus in United States. |
| Point-of-Care Platform Miniaturization | Compresses turnaround times below sixty minutes in hospital emergency departments. |
| Companion Diagnostic Reimbursement Strategy | Captures premium pricing for oncology sequencing workflows in German cancer centers. |
| CRISPR-Based Assay Development Partnership | Accelerates commercial translation from academic medical centers in Japan. |
Methodological Framework
Document review covered FDA premarket submissions, EMA In Vitro Diagnostic Regulation guidance documents, WHO prequalification assay listings, and hospital procurement database records, complemented by interviews with molecular diagnostics laboratory directors, reagent manufacturing supply chain managers, regulatory affairs specialists, and GPO contracts administrators. Secondary validation drew from CLIA certification registries, NMPA approval databases, CDSCO assay listings, and polymerase enzyme trade flow data. Bottom-up segment sizing and top-down market triangulation were cross-referenced for consistency.
Segment-level projections across technology, product type, application, and end-user categories were generated through adoption curve modeling and replacement cycle analysis. CAGRs were derived from volume trajectory fitting against historical platform refresh patterns and regulatory approval timelines. Forecast inputs incorporated CLIA laboratory expansion rates, companion diagnostic reimbursement framework maturation, and polymerase enzyme production capacity announcements.
The model holds under stable regulatory premarket review timelines and continued polymerase feedstock availability; deviation in FDA premarket pathway restructuring or Danish fermentation facility disruptions would shift trajectory assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Efficacy Testing Market
Testing Services
United States Esoteric Testing Market
Testing Services
Healthcare Analytical Testing Services Market
Testing Services
Global Specimen Validity Testing Market
Testing Services
Hbsag Testing Market
Testing Services
Global Endocrine Testing Market
Testing Services
At-Home Testing Market
Testing Services
Global Creatinine Assay Kits Market
Testing Services
Fecal Calprotectin Test Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Industrial Radiography Testing Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
Phenytoin Testing Market
Testing Services
Warfarin Sensitivity Testing Market
Testing Services
Blood Pressure Test Market