
 Global Women Health Rehabilitation Products Market | 2026-2036
Global Women Health Rehabilitation Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Women Health Rehabilitation Products Market Foresight
Manufacturing capacity expansion across East Asian medical device clusters is realigning supply availability for women's health rehabilitation products. GE HealthCare leverages its imaging-to-therapy continuum to anchor hospital system contracts in North America. Essity Aktiebolag sustains brand strength in absorbent and support products through direct-to-patient channels. Zynex Inc. competes in electrotherapy segments with prescription-based home delivery models.
Women health rehabilitation products encompass pelvic floor trainers, postnatal supports, incontinence aids, physiotherapy devices, and massage tools engineered with medical-grade silicones, adjustable compression textiles, and programmable neuromuscular electrical stimulation parameters. These products restore muscular function, manage tissue healing, and reduce pain following obstetric events, surgical interventions, or age-related degeneration. Pelvic floor trainers and postnatal supports command the largest revenue share due to reimbursed clinical protocols and direct consumer accessibility. Incontinence aids generate recurring revenue through disposable consumption patterns, while physiotherapy devices attract premium pricing in institutional procurement.
FDA 510(k) clearance requirements, EU MDR technical documentation obligations, and Japan PMDA quality management system inspections shape product development timelines and market entry costs for manufacturers. ISO 13485 certification has become a baseline qualifier for supplier qualification by gynecological clinics and rehabilitation institutes across regulated markets. Stakeholders must monitor reimbursement code expansions for remote pelvic floor monitoring and home-based electrotherapy to capture shifting site-of-care economics.
Market Dynamics
Hospital outpatient departments in the United States, Germany, and Japan are consolidating procurement around reimbursed pelvic floor rehabilitation protocols, compressing vendor qualification timelines and privileging suppliers with ISO 13485 certification and established clinical evidence packages.
Growth Catalysts
- EU MDR technical documentation mandates:Manufacturers investing in clinical evaluation reports and post-market surveillance systems are securing preferential placement in European hospital tenders. This regulatory alignment accelerates market access for compliant suppliers.
- Silicone elastomer advances:Medical-grade platinum-cured silicones with Shore 00-20 durometer ratings enable next-generation pelvic floor trainers with superior biocompatibility and durability profiles. Material science innovation is expanding addressable patient populations.
- Postpartum recovery infrastructure:Dedicated women's health rehabilitation centers in Tokyo, Munich, and Chicago are standardizing pelvic floor electrotherapy into obstetric discharge protocols. Institutional adoption is creating predictable demand cycles.
Market Restraints
- Medical-grade textile input volatility:Compression garment manufacturers face nylon 6,6 and spandex price swings tied to petrochemical feedstock markets. Input cost unpredictability compresses margin visibility for mid-tier suppliers.
- East Asian supply concentration:Programmable neuromuscular stimulator PCBs and lithium polymer cells concentrate in Shenzhen and Dongguan manufacturing clusters. Geographic single-point-of-failure risk elevates working capital requirements for inventory hedging.
- Class II device regulatory friction:FDA 510(k) substantial equivalence determinations for novel pelvic floor biofeedback devices average 180-day review cycles. Extended timelines delay revenue recognition for product line extensions.
Strategic Opportunities
- Remote patient monitoring reimbursement:United States CMS evaluation of CPT code expansions for home-based pelvic floor biofeedback creates service revenue potential beyond device sales. Policy tailwinds favor connected hardware platforms.
- Menopausal rehabilitation protocols:Underpenetrated applications for vaginal atrophy laser therapy and pelvic organ prolapse prevention in women aged 50-65 represent white space distinct from obstetric recovery. Demographic aging in Japan and Germany amplifies addressable need.
- Direct-to-patient subscription models:Disposable incontinence pad and support garment replenishment programs bypass traditional durable medical equipment distribution. Channel innovation captures lifetime value through recurring revenue architecture.
Industry Challenges
- Clinical evidence generation capacity:Randomized controlled trial design and pelvic floor physiotherapist recruitment for device efficacy studies require specialized contract research organization relationships. Talent scarcity in women's health clinical operations extends study timelines.
- Legacy hospital IT integration:Home-use electrotherapy devices must interface with Epic and Cerner electronic health record systems for remote monitoring reimbursement. Interoperability certification demands specialized software engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Women Health Rehabilitation Products Market |
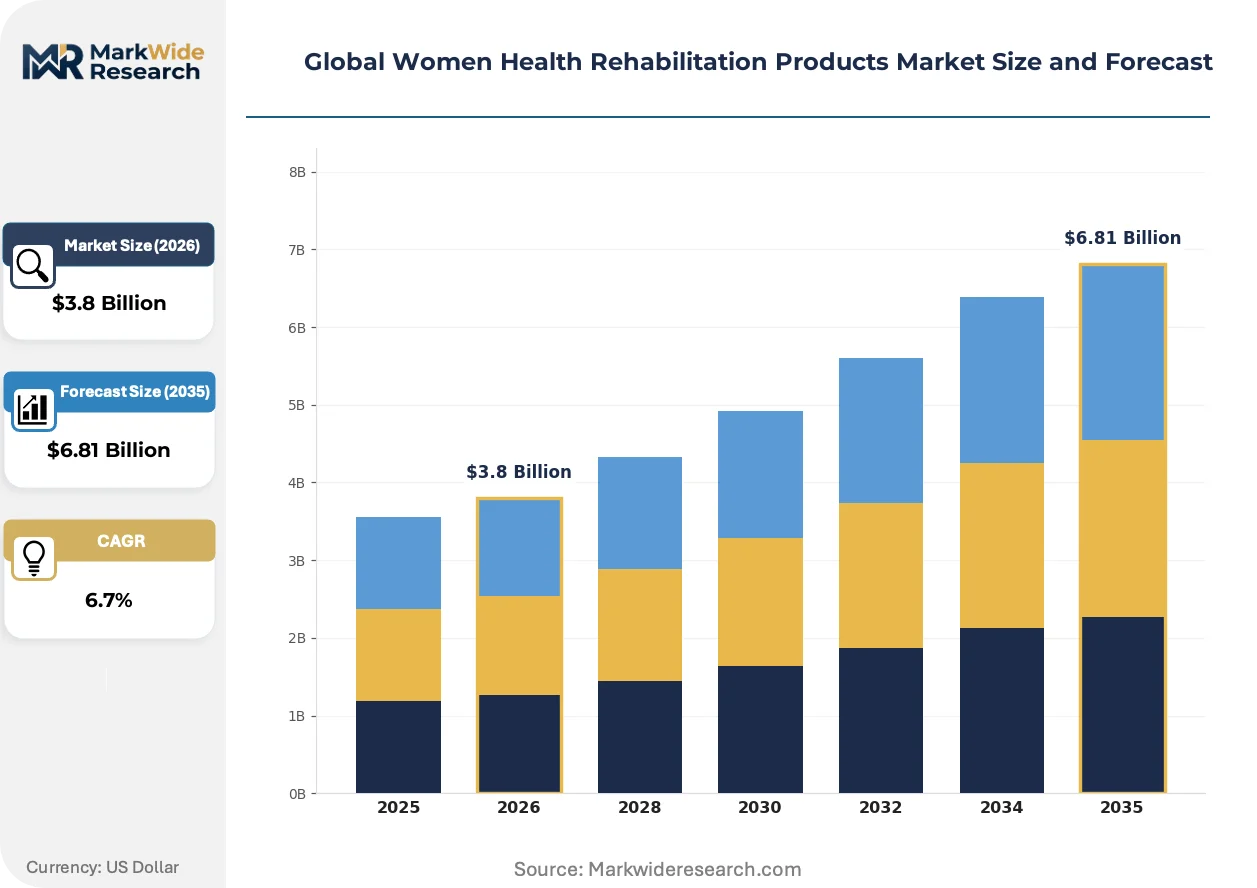
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pelvic Floor Trainers, Postnatal Supports, Incontinence Aids, Physiotherapy Devices, Massage Tools Application: Postpartum Recovery, Menopause Management, Urinary Incontinence, Pelvic Pain Relief, Osteoporosis Care End User: Gynecological Clinics, Physical Therapy Centers, Home Care Patients, Rehabilitation Institutes, Fitness Studios Distribution Channel: Online Retailers, Specialty Pharmacies, Medical Supply Stores, Healthcare Providers, Wellness Centers |
| Companies Covered | GE HealthCare, Access Health International, DeRoyal Industries, AliMed Inc., GPC Medical Ltd, Win Health Medical Ltd, Zynex Inc., Essity Aktiebolag, Meyer Physical Therapy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Women Health Rehabilitation Products Market Shifts & Advancements
Connected pelvic floor rehabilitation hardware is compressing the traditional separation between clinical and home-based care settings, with sensor-enabled trainers and cloud-based progress tracking redefining patient engagement models and reimbursement pathways.
Neuromuscular electrical stimulation with app-controlled amplitude modulation and real-time pressure biofeedback is electrifying the transition from passive support garments to active muscle retraining protocols. Outpatient physiotherapy departments in the United States are adopting these platforms at accelerated pace to reduce in-person visit burdens. The technology is compressing rehabilitation timelines and enabling outcome-based contracting with payers.
Japan PMDA quality management system inspections for foreign manufacturers have intensified documentation requirements for software as a medical device components in connected pelvic floor trainers. Industrial consequence includes mandatory cybersecurity risk management files and post-market software update protocols. European manufacturers with legacy hardware-only portfolios face compliance gap closure costs to maintain Japan market access.
Hospital procurement committees are consolidating vendor panels around single-source contracts for comprehensive pelvic floor rehabilitation ecosystems. Independent durable medical equipment suppliers lose shelf space to integrated device-and-service providers with clinical training capabilities. This concentration is most visible in German Krankenhaus procurement, where Essen and Berlin hospital systems have reduced qualified suppliers from twelve to four across pelvic floor and incontinence product categories.
Global Women Health Rehabilitation Products Market Segmentation
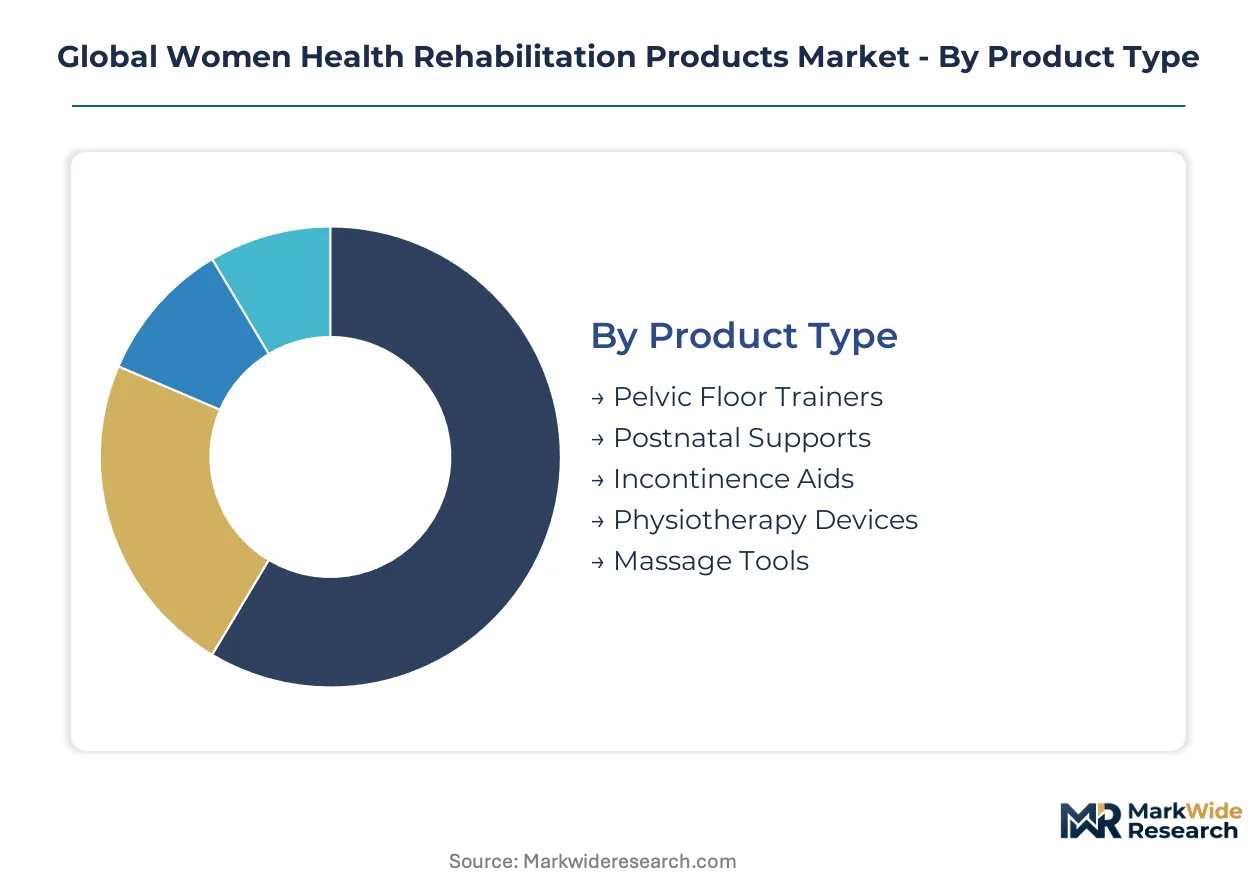
Segmentation in women's health rehabilitation products reveals distinct procurement patterns across clinical and consumer channels. Product type and end-user configuration determine reimbursement eligibility, regulatory pathway, and margin structure for manufacturers.
Product Type:
Pelvic floor trainers command premium pricing through reimbursed clinical protocols, while incontinence aids generate volume through disposable replenishment cycles.
- Pelvic Floor Trainers:Medical-grade silicone devices with pressure biofeedback sensors and app connectivity enable neuromuscular retraining. Hospital outpatient departments in the United States and Germany are standardizing these into postpartum discharge protocols, driving institutional procurement consolidation.
- Postnatal Supports:Adjustable compression garments utilizing nylon 6,6 and spandex blends provide abdominal wall stabilization following cesarean delivery. Demand concentrates in Japan's dedicated women's health rehabilitation centers, where obstetric discharge guidelines increasingly mandate supportive wear.
- Incontinence Aids:Disposable absorbent products with superabsorbent polymer cores address stress and urge incontinence across age demographics. Direct-to-patient subscription models in Germany bypass traditional durable medical equipment distribution.
- Physiotherapy Devices:Programmable electrotherapy units with lithium polymer power cells deliver neuromuscular stimulation for pelvic floor rehabilitation. FDA 510(k) clearance requirements extend development timelines for novel biofeedback features.
- Massage Tools:Percussion and vibration devices with medical-grade silicones target myofascial release and pain modulation. Wellness centers in Tokyo and Chicago are expanding retail placement for non-reimbursed consumer purchase.
Mature deployment sits with incontinence aids. Newer deployment is concentrated in connected pelvic floor trainers.
Application:
Postpartum recovery applications anchor institutional reimbursement, while menopause management represents emerging white space with limited protocol standardization.
- Postpartum Recovery:Pelvic floor rehabilitation and abdominal support protocols address tissue healing following vaginal and cesarean delivery. Munich and Chicago hospital systems have reduced qualified suppliers from twelve to four across product categories.
- Menopause Management:Vaginal atrophy laser therapy and pelvic organ prolapse prevention target women aged 50-65 with underpenetrated clinical pathways. Demographic aging in Japan and Germany amplifies addressable need for preventive interventions.
- Urinary Incontinence:Stress, urge, and mixed incontinence protocols combine behavioral therapy with device-based muscle retraining. CMS evaluation of CPT code expansions for home-based biofeedback creates service revenue potential.
- Pelvic Pain Relief:Myofascial dysfunction and dyspareunia interventions utilize electrotherapy and manual therapy devices. Physical therapy centers in Berlin are adopting sensor-enabled platforms to reduce in-person visit burdens.
- Osteoporosis Care:Bone density maintenance and fracture prevention programs incorporate weighted support garments and vibration platforms. Rehabilitation institutes in Tokyo are integrating these into comprehensive women's health protocols.
Volume concentration remains in postpartum recovery. Steepest expansion trajectory is emerging in menopause management applications.
End User:
Gynecological clinics privilege ISO 13485-certified suppliers, while home care channels favor direct-to-patient accessibility over clinical training requirements.
- Gynecological Clinics:Specialized diagnostic and treatment facilities require device interoperability with Epic and Cerner electronic health record systems. Interoperability certification demands specialized software engineering resources for market access.
- Physical Therapy Centers:Outpatient rehabilitation facilities adopt app-controlled electrotherapy platforms to compress treatment timelines and enable outcome-based contracting with payers.
- Home Care Patients:Self-directed users purchase pelvic floor trainers and support garments through online retailers with prescription-based home delivery models. Cybersecurity risk management files are mandatory for connected devices under Japan PMDA inspections.
- Rehabilitation Institutes:Comprehensive women's health centers in Essen and Berlin consolidate vendor panels around single-source contracts for integrated device-and-service ecosystems.
- Fitness Studios:Wellness-oriented facilities retail massage tools and non-medical support garments outside reimbursement frameworks. Consumer accessibility drives placement but limits price realization.
Procurement standardization is most advanced in gynecological clinics. Channel innovation is concentrating in home care patient segments.
Distribution Channel:
Healthcare providers capture reimbursed device sales, while online retailers enable subscription-based replenishment for disposable products.
- Online Retailers:E-commerce platforms facilitate direct-to-patient subscription models for incontinence pad and support garment replenishment. Recurring revenue architecture captures lifetime value beyond single-transaction device sales.
- Specialty Pharmacies:Compounding and durable medical equipment suppliers with clinical training capabilities are displacing independent distributors in German Krankenhaus procurement.
- Medical Supply Stores:Brick-and-mortar retailers with certified fitters provide compression garment sizing and pelvic floor trainer demonstration. Nylon 6,6 and spandex price volatility compresses margin visibility for mid-tier suppliers.
- Healthcare Providers:Hospital outpatient departments and physician practices consolidate procurement around reimbursed pelvic floor rehabilitation protocols. Vendor qualification timelines compress for suppliers with established clinical evidence packages.
- Wellness Centers:Non-clinical facilities retail massage tools and consumer-grade support products outside FDA 510(k) and EU MDR regulatory pathways. Lower compliance burden enables faster product iteration.
Established volume flows through healthcare providers. Fastest channel expansion is occurring in online retail formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone feedstock production in Germany's Ruhr industrial corridor anchors European supply security for pelvic floor trainer manufacturers serving reimbursed hospital protocols.
United States
Postpartum recovery infrastructure expansion in Chicago and Minneapolis hospital systems drives institutional procurement of connected pelvic floor trainers. FDA 510(k) clearance pathways for Class II biofeedback devices compress vendor qualification timelines. The Boston medical device cluster concentrates software engineering talent for Epic and Cerner interoperability certification.
Germany
Krankenhaus procurement consolidation in Essen and Berlin reduces qualified suppliers across pelvic floor and incontinence categories. EU MDR technical documentation mandates for clinical evaluation reports shape manufacturer compliance investments. The Munich metropolitan area anchors dedicated women's health rehabilitation center expansion with standardized electrotherapy protocols.
Japan
PMDA quality management system inspections intensify cybersecurity documentation for connected trainer software components. Tokyo's women's health rehabilitation centers standardize pelvic floor electrotherapy into obstetric discharge pathways. The Osaka-Kobe manufacturing belt concentrates compression textile production utilizing nylon 6,6 and spandex blends.
China
Shenzhen and Dongguan electronics clusters concentrate programmable neuromuscular stimulator PCB and lithium polymer cell production. NMPA medical device registration requirements for imported pelvic floor trainers extend market entry timelines. Shanghai's hospital procurement committees evaluate domestic electrotherapy platforms against reimbursed clinical protocols.
United Kingdom
NHS pelvic floor rehabilitation service specifications in London and Manchester prioritize ISO 13485-certified suppliers with established clinical evidence packages. MHRA post-market surveillance requirements for Class II devices align with EU MDR transition timelines. The Cambridge medical technology corridor hosts biofeedback sensor development for next-generation trainer connectivity.
Global Women Health Rehabilitation Products Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue connected hardware platforms and direct-to-patient subscription models. The vendor base stratifies across imaging-to-therapy continuum integrators, absorbent product specialists, and electrotherapy prescription platforms. Three archetypes dominate: hospital system contract anchors, brand-driven direct-to-patient channels, and prescription-based home delivery operators. Competitive moves concentrate on clinical evidence generation capacity and EHR interoperability certification.
Within the imaging-to-therapy integrator tier, GE HealthCare occupies a position exemplifying hospital system contract consolidation. Among electrotherapy specialists, Zynex Inc. and Essity Aktiebolag represent divergent channel strategies—prescription-based home delivery versus direct-to-patient absorbent product subscription architecture. These three entities anchor the competitive structure without exhausting its variation.
| Leading Market Players |
|---|
| GE HealthCare |
| Access Health International |
| DeRoyal Industries |
| AliMed Inc. |
| GPC Medical Ltd |
| Win Health Medical Ltd |
| Zynex Inc. |
| Essity Aktiebolag |
| Meyer Physical Therapy |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists in German medical textile manufacturing anchor pricing discipline through captive silicone compounding operations, compressing margin volatility for pelvic floor trainer producers while forcing Asian contract manufacturers toward unbundled service offerings.
Pricing Analysis
Warranty and clinical training bundling separates premium-tier suppliers from economy-positioned competitors in institutional procurement. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and FDA 510(k) clearance documentation depth. Cost compression in mid-tier electrotherapy devices is intensifying because lithium polymer cell suppliers in Shenzhen demand upfront payment terms. Home care patients exhibit highest price sensitivity; hospital outpatient departments privilege total-cost-of-ownership over unit pricing.
Supply Chain Analysis
Japan's PMDA-mandated local software testing requirements are reshaping sourcing patterns for connected trainer firmware development, forcing European manufacturers toward domestic engineering partnerships. Medical-grade silicone feedstock concentrates in Germany's Ruhr corridor and Japan's Osaka-Kobe belt; programmable neuromuscular stimulator PCBs and lithium polymer cells draw from Shenzhen and Dongguan clusters. Single-source vulnerability in East Asian electronics manufacturing elevates working capital requirements for inventory hedging. Distribution runs through hospital procurement committees consolidating vendor panels, with specialty pharmacies displacing independent durable medical equipment suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected pelvic floor rehabilitation hardware with app-controlled biofeedback is displacing passive support garments, compressing rehabilitation timelines and enabling outcome-based contracting that legacy electrotherapy platforms cannot match.
For Market Incumbents: Anchor hospital system contracts through Epic and Cerner interoperability certification, defending against prescription-based home delivery entrants. Secure backward integration into medical-grade silicone compounding to offset nylon 6,6 and spandex price volatility. Prioritize clinical evidence generation capacity through specialized contract research organization relationships to extend FDA 510(k) clearance advantages. For New Entrants and Emerging Players: Capture menopause management white space in Japan and Germany, where vaginal atrophy laser therapy and pelvic organ prolapse prevention protocols remain underpenetrated. Target direct-to-patient subscription models for disposable incontinence pad replenishment, bypassing consolidated German Krankenhaus procurement. Pursue reimbursement code expansion lobbying for remote pelvic floor monitoring to unlock service revenue streams. For Investors and Strategic Acquirers: Distressed-cycle entries favor electrotherapy prescription platforms with established home delivery infrastructure in the United States, where CMS evaluation of CPT code expansions creates policy tailwinds. Five-to-ten year viability hinges on software-as-a-medical-device compliance capabilities. Monitor Japan PMDA cybersecurity documentation enforcement as inflection indicator for connected hardware platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerated review cycles for biofeedback-enabled trainers secure preferential placement in US hospital tenders. |
| EU MDR Technical Documentation | Clinical evaluation report investments secure placement in German Krankenhaus procurement consolidation. |
| Hospital System Partnership | Single-source contracts with Chicago and Munich systems reduce qualified suppliers from twelve to four. |
| Software Companion Development | Epic and Cerner interoperability certification enables remote monitoring reimbursement in US outpatient settings. |
| Reimbursement Strategy | CMS CPT code expansion lobbying for home-based biofeedback creates service revenue beyond device sales. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across hospital purchasing committees, pelvic floor physiotherapists, biomedical engineers, GPO contracts managers, and medical device regulatory affairs leads. FDA 510(k) substantial equivalence determinations, EU MDR technical documentation databases, Japan PMDA quality management system inspection records, and hospital procurement databases supplied validation layers. Bottom-up product-type demand modeling and top-down macroeconomic factor reconciliation ensured coverage integrity.
Shipment volume reconciliation against reimbursed procedure codes and electrotherapy device installation bases anchored the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, application, end user, and distribution channel, with regulatory pathway cluster and connectivity capability as industry-specific overlays. CAGRs derived from logistic adoption curve fitting against postpartum recovery protocol standardization timelines and menopause management demographic shifts.
The model holds under stable reimbursement code frameworks and continued silicone elastomer supply security; deviation in FDA 510(k) review timeline extensions or East Asian electronics manufacturing disruption would shift volume recognition patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Portable Postpartum Rehabilitation Instrument Market
Rehabilitation Services
Physiotherapy Services Market
Rehabilitation Services
US Assisted Living Facility and Neurorehabilitation Market
Rehabilitation Services
Global Outpatient Rehabilitation Centers Market
Rehabilitation Services
Smart Portable Rehabilitation Devices Market
Rehabilitation Services
Speech Therapy Services Market
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
Motion Stimulation Therapy Market
Rehabilitation Services
Rehabilitation Equipment Market
Rehabilitation Services
Behavioral Rehabilitation Market
Rehabilitation Services
Outpatient Rehabilitation Services Market
Rehabilitation Services
United States Behavioral Rehabilitation Market
Rehabilitation Services
Global Robotic Rehabilitation and Assistive Technologies Market
Rehabilitation Services
Occupational and Physical Therapy Services Market
Rehabilitation Services
Global Neurorehabilitation Devices Market
Rehabilitation Services
Brachial Plexus Injury Market