
 Home Rehabilitation Services Market | 2026-2036
Home Rehabilitation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Home Rehabilitation Services Market Foresight
CMS reimbursement restructuring is rewriting the cost-of-entry calculus for home rehabilitation providers across the United States. Encompass Health sustains geographic dominance through its integrated inpatient-to-home health continuum. Stryker Corporation leverages its medical equipment portfolio to anchor technology leadership in mobility-assisted recovery protocols. Invacare Corporation specializes in durable medical equipment distribution that supports provider scale in residential settings.
Home rehabilitation services encompass skilled therapeutic interventions delivered in residential settings to restore functional independence following acute medical events, using equipment ranging from continuous passive motion devices to neuromuscular electrical stimulators with prescribed pulse frequencies of 35-50 Hz. The primary commercial purpose centers on reducing institutional readmission penalties while extending care continuity beyond hospital discharge. Physical therapy commands the largest service type share as orthopedic procedure volumes rise, while telehealth sessions represent the fastest-expanding delivery method as synchronous video platforms gain payer acceptance. Post-surgical patients generate concentrated margin pools due to predictable episode durations and standardized outcome metrics that streamline reimbursement documentation.
The US CMS, state-level departments of health, and the Joint Commission accreditation standards collectively shape provider licensing requirements, staffing ratios, and clinical documentation protocols that determine market access eligibility. OSHA workplace safety rules and HIPAA privacy frameworks impose operational compliance costs that favor larger platforms with dedicated regulatory infrastructure. Stakeholders must monitor evolving state-level scope-of-practice expansions for nurse practitioners and physical therapist assistants that could reshape labor economics and competitive density in metropolitan service territories.
Market Dynamics
Hospital length-of-stay compression is forcing post-acute care migration into residential settings, restructuring provider economics around episode-based reimbursement rather than fee-for-service volume.
Growth Catalysts
- CMS reimbursement expansion:The US Centers for Medicare & Medicaid Services has broadened provider eligibility for home health services, lowering capital barriers for new market entrants.
- Orthopedic procedure volumes:Rising joint replacement surgeries generate predictable rehabilitation episodes with standardized outcome metrics that streamline documentation.
- Telehealth platform maturation:Synchronous video delivery methods are gaining payer acceptance, extending service reach into rural territories previously excluded from specialist access.
Market Restraints
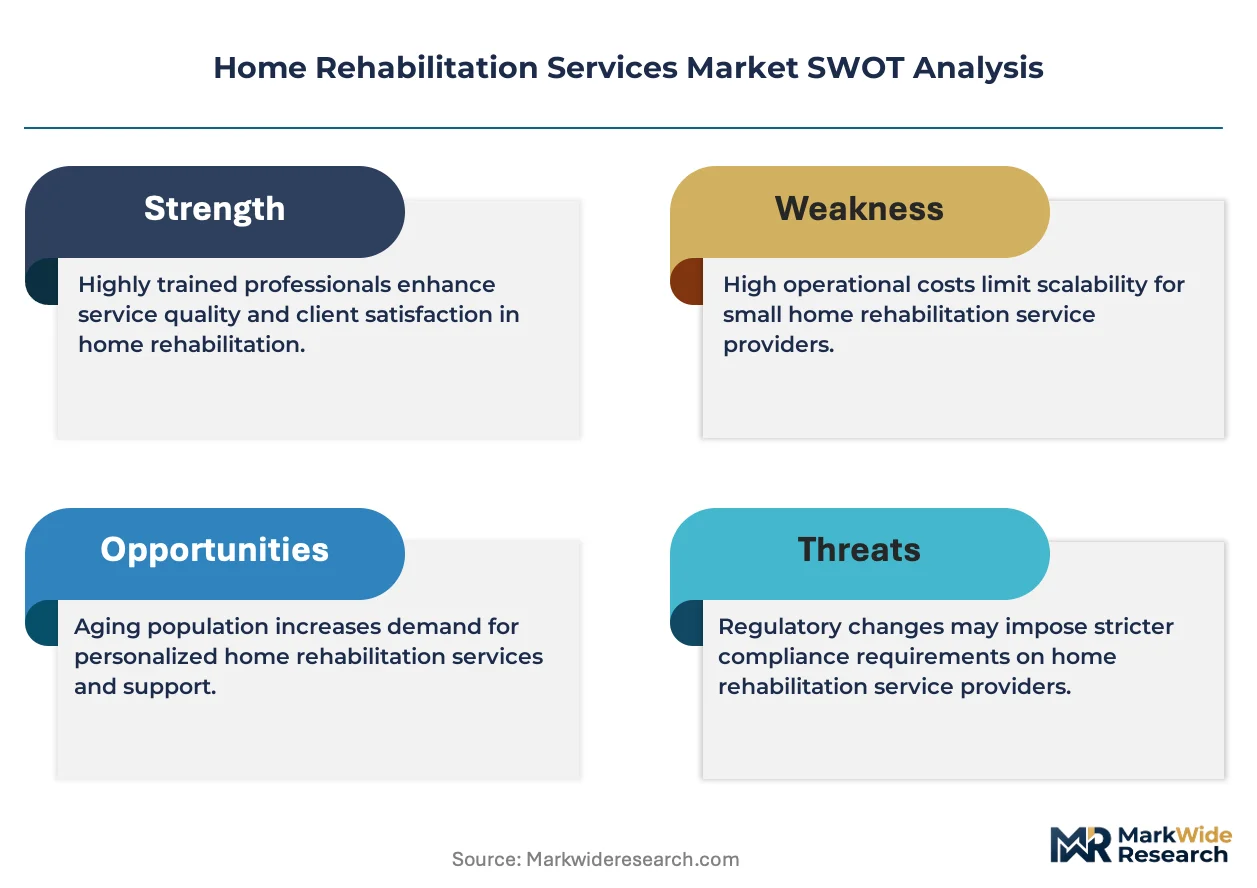
- Skilled labor scarcity:Licensed physical therapists and registered nurses command premium wages that compress margins on standardized episode payments.
- Equipment depreciation cycles:Continuous passive motion devices and neuromuscular electrical stimulators require capital refresh every 4-6 years.
- HIPAA compliance infrastructure:Privacy framework mandates impose fixed operational costs that disadvantage smaller regional platforms lacking dedicated regulatory staff.
Strategic Opportunities
- Scope-of-practice expansion:State-level licensing reforms for nurse practitioners and physical therapist assistants could reshape labor economics in metropolitan service territories.
- Remote patient monitoring convergence:Wearable biosensors paired with AI-driven analytics platforms enable real-time functional assessment between scheduled visits.
- Chronic condition management:Heart failure and COPD populations represent underpenetrated segments beyond the current post-surgical focus.
Industry Challenges
- Interoperability friction:Electronic health record integration with hospital discharge systems requires costly API development and maintenance.
- Outcome measurement standardization:Competing functional assessment protocols create documentation complexity that delays reimbursement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Rehabilitation Services Market |
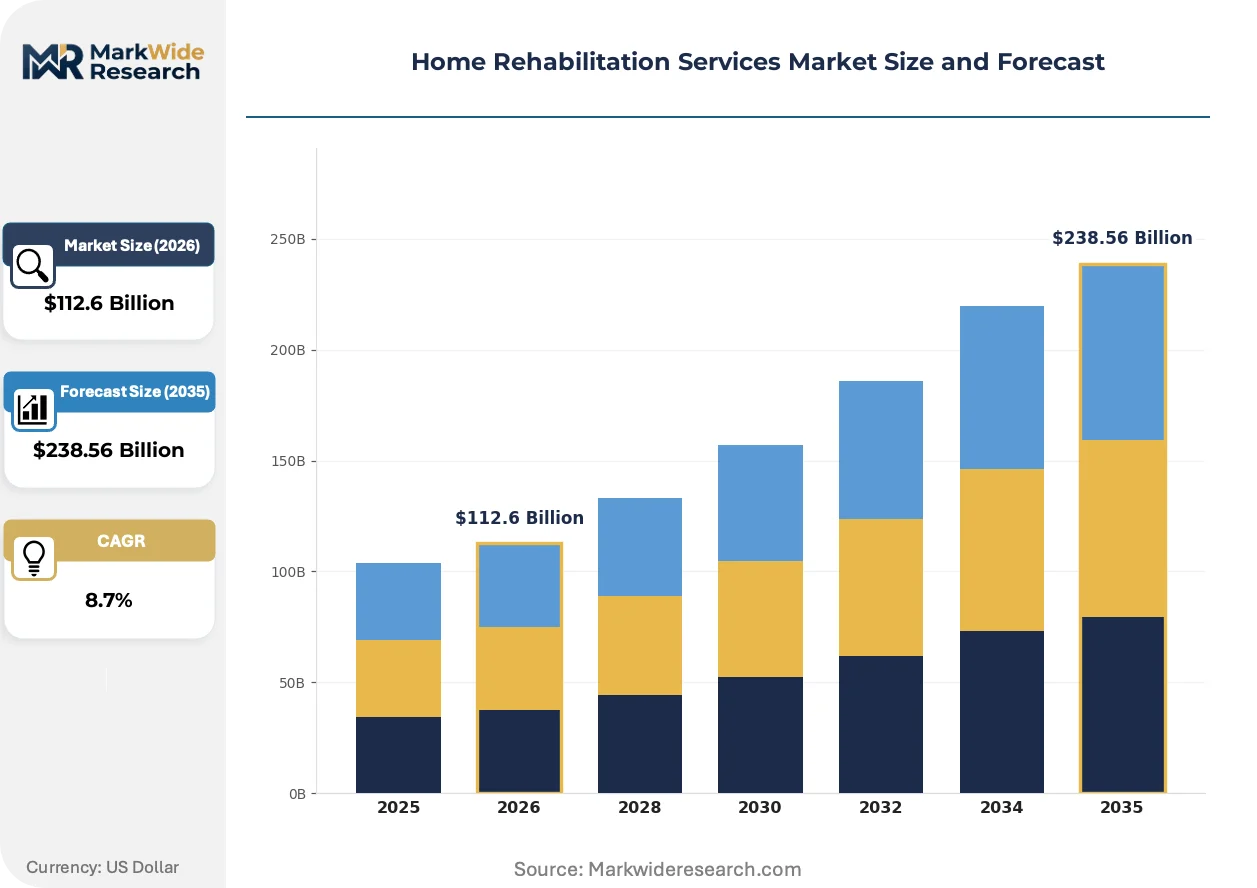
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $238.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Physical Therapy, Occupational Therapy, Speech Therapy, Home Health Aide Patient Type: Senior Citizens, Post-Surgical Patients, Stroke Survivors, Disabled Individuals Payment Model: Insurance, Out-of-Pocket, Government Programs, Charitable Funding Delivery Method: In-Home Visits, Telehealth Sessions, Community-Based Programs, Residential Facilities |
| Companies Covered | RehabCare Group, Invacare Corporation, Stryker Corporation, Medline Industries, Encompass Health, Infinity Rehab, PTS Rehab, Aveanna Healthcare Holdings, DispatchHealth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Rehabilitation Services Market Shifts & Advancements
Digital health infrastructure is compressing the distance between acute discharge and functional recovery, enabling real-time clinical oversight without physical co-location.
Remote therapeutic monitoring systems combine wearable motion sensors with cloud-based analytics platforms to capture range-of-motion metrics and adherence data outside scheduled sessions. Post-surgical orthopedic patients are adopting these tools fastest, driven by surgeon demand for objective recovery documentation. The technology is rewriting the traditional visit-based revenue model by enabling continuous data streams that justify expanded reimbursement codes.
The US CMS has finalized reimbursement codes for remote therapeutic monitoring, creating payment parity between virtual and in-person functional assessment. This policy shift accelerates capital deployment into digital infrastructure by providers seeking episode efficiency gains. Home health agencies in competitive Medicare Advantage markets are responding fastest, using the codes to differentiate bundled service offerings.
Episode-based procurement is displacing per-visit contracting as payers seek guaranteed outcomes for defined post-acute periods. Health systems operating narrow networks are consolidating vendor relationships around platforms that assume readmission risk. This concentration is most visible in Medicare Advantage penetration markets, where star ratings tie directly to functional recovery metrics.
Home Rehabilitation Services Market Segmentation
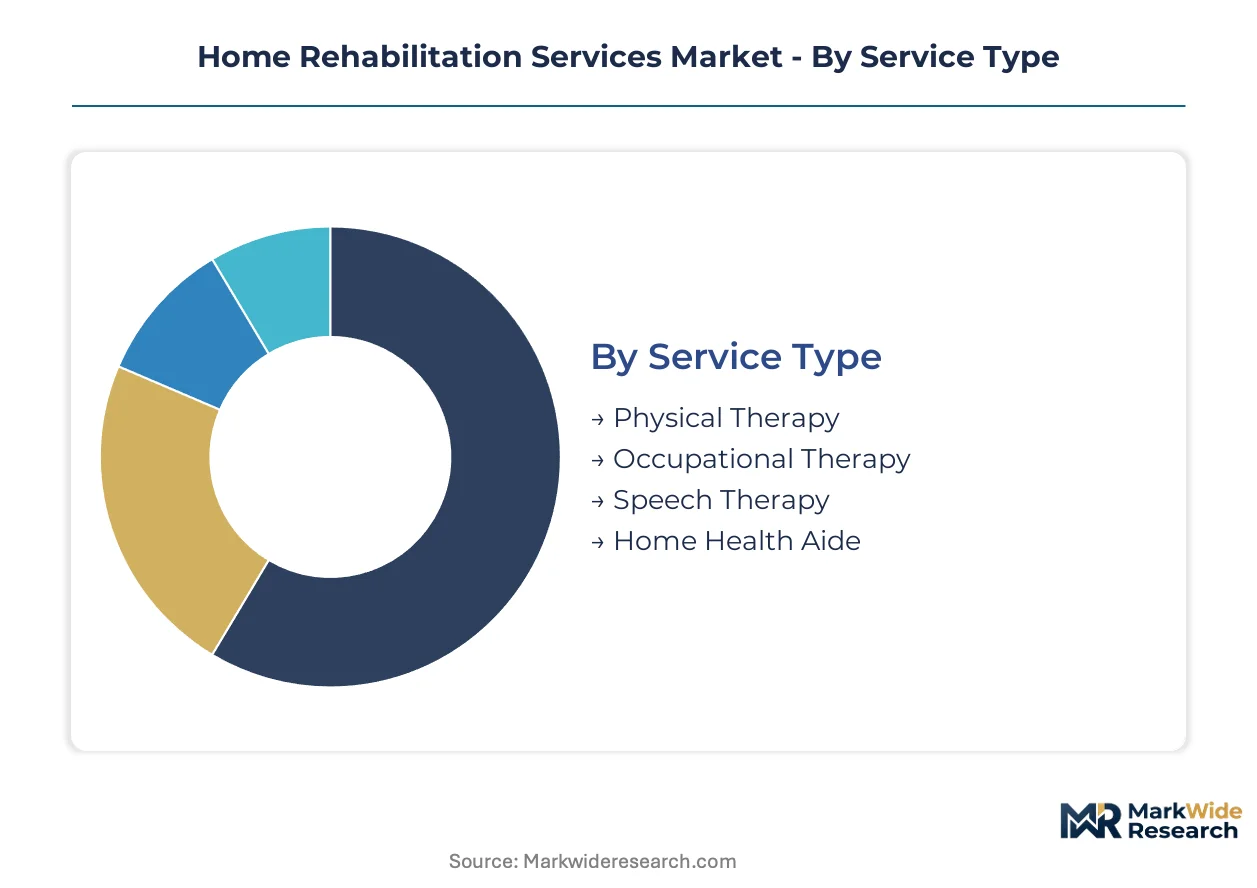
Segmentation in home rehabilitation services determines reimbursement pathways, staffing requirements, and technology deployment strategies. Each dimension shapes capital allocation decisions and competitive positioning differently.
Service Type:
Technical complexity and reimbursement intensity vary sharply across therapeutic modalities, driving divergent margin structures and platform specialization.
- Physical Therapy:Mobility restoration protocols deploy continuous passive motion devices with prescribed 35-50 Hz pulse frequencies for joint rehabilitation. Post-surgical orthopedic episodes in the United States generate concentrated demand due to standardized Medicare documentation pathways and predictable episode durations.
- Occupational Therapy:Activities-of-daily-living training focuses on adaptive equipment integration and home environment modification. Stroke survivors in metropolitan service territories drive adoption as narrow-network health systems seek functional independence metrics for bundled payment contracts.
- Speech Therapy:Cognitive-linguistic rehabilitation addresses aphasia and swallowing disorders following neurological events.
- Home Health Aide:Personal care assistance supports medication adherence and basic mobility without skilled clinical intervention.
Physical therapy leads on scale; occupational therapy leads on momentum.
Patient Type:
Clinical acuity and episode predictability create distinct operational economics across beneficiary populations.
- Post-Surgical Patients:Predictable recovery trajectories following joint replacement or cardiac procedures enable standardized outcome metrics that streamline CMS reimbursement documentation. These episodes command premium margins due to defined duration windows and surgeon-directed referral patterns.
- Senior Citizens:Medicare-eligible beneficiaries with multiple chronic conditions require longitudinal care coordination. CMS home health eligibility expansion in the United States is redirecting skilled nursing facility volume into residential settings for this population.
- Stroke Survivors:Neurological rehabilitation demands interdisciplinary coordination between physical, occupational, and speech therapists.
- Disabled Individuals:Congenital or acquired functional limitations require durable medical equipment integration and environmental modification services.
Post-surgical patients lead on scale; senior citizens lead on momentum.
Payment Model:
Revenue cycle complexity and collection risk vary substantially across payer categories, influencing platform scale requirements and geographic targeting.
- Insurance:Commercial payers and Medicare Advantage plans are consolidating vendor relationships around episode-based contracting with readmission risk assumption. United States markets with high Medicare Advantage penetration show fastest procurement concentration.
- Government Programs:Traditional Medicare fee-for-service and Medicaid home health benefits provide volume stability but impose documentation intensity and prior authorization requirements.
- Out-of-Pocket:Direct consumer payment for concierge rehabilitation services escapes payer utilization management but limits addressable market.
- Charitable Funding:Nonprofit subsidy programs support uninsured or underinsured populations in select metropolitan markets.
Insurance leads on scale; government programs lead on momentum.
Delivery Method:
Channel economics and regulatory scope determine competitive entry barriers and technology capital requirements.
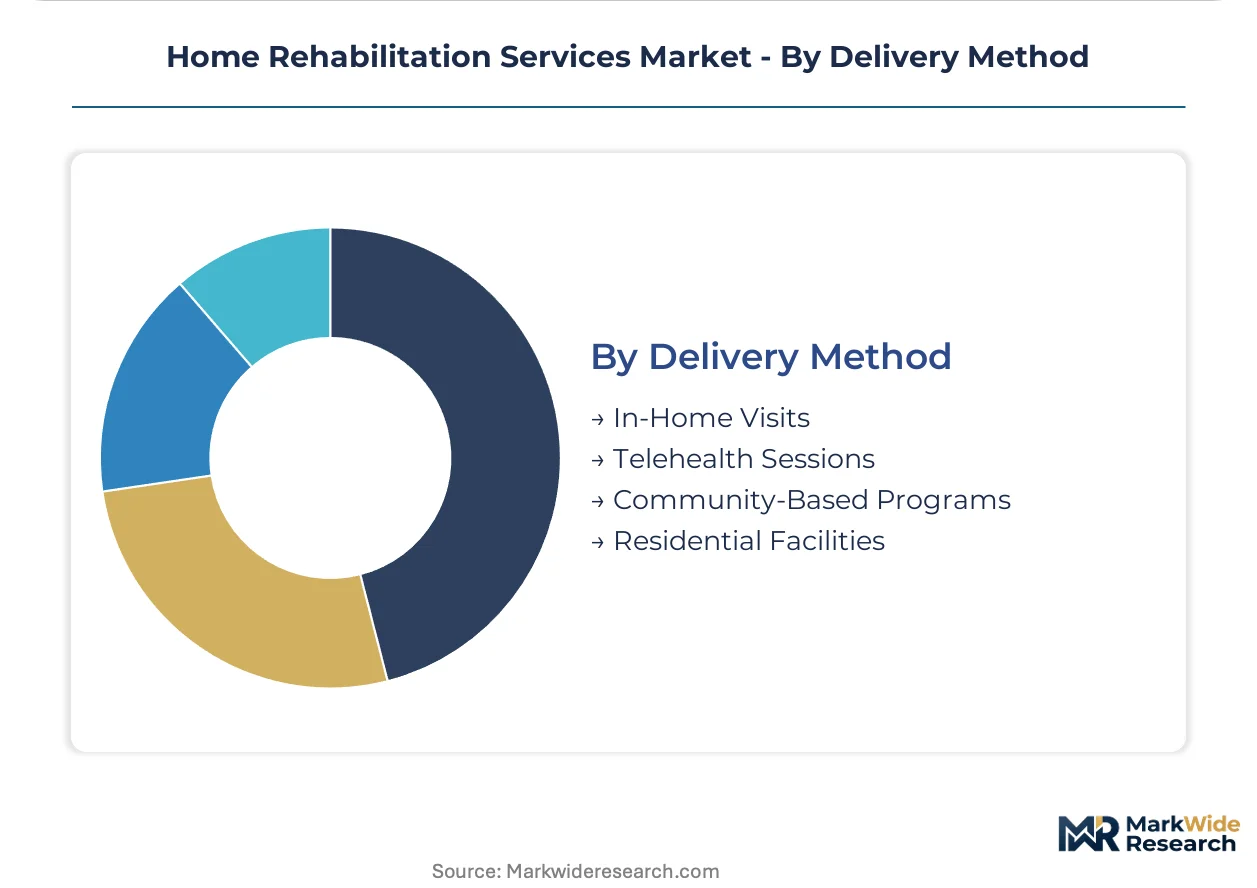
- In-Home Visits:Traditional face-to-face therapeutic delivery requires licensed clinician deployment with durable medical equipment logistics. Labor scarcity and travel time inefficiency are compressing margins on standardized episode payments.
- Telehealth Sessions:Synchronous video platforms with remote therapeutic monitoring integration are gaining CMS reimbursement parity. Rural territories previously excluded from specialist access represent the steepest expansion trajectory as connectivity infrastructure improves.
- Community-Based Programs:Group rehabilitation in senior centers or outpatient satellites reduces per-capita labor cost but sacrifices care continuity.
- Residential Facilities:Skilled nursing facility and assisted living co-location enables 24-hour oversight for high-acuity cases.
In-home visits lead on scale; telehealth sessions lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed physical therapists and registered nurses concentrate disproportionately in metropolitan corridors with academic medical centers and narrow-network health systems. This workforce clustering shapes where episode-based contracts achieve critical density and where telehealth platforms can substitute for in-person specialist access.
United States
Post-surgical orthopedic volumes and Medicare Advantage penetration drive demand concentration in Sun Belt retirement corridors and Midwest manufacturing cities. CMS reimbursement code expansion for remote therapeutic monitoring is redirecting skilled nursing facility volume into residential settings. Dallas-Fort Worth and Phoenix anchor the fastest-expanding service territories as hospital systems consolidate post-acute vendor relationships.
Germany
Aging demographics and statutory health insurance integration create predictable reimbursement pathways for in-home therapeutic interventions. The country's national health regulator maintains stringent licensing requirements for outpatient rehabilitation providers that favor established platforms with dedicated compliance infrastructure. The Rhine-Ruhr metropolitan region concentrates the highest density of integrated home health networks serving post-surgical cardiac and orthopedic episodes.
Japan
Super-aged population dynamics and hospital bed reduction policies are accelerating post-acute migration into residential settings. METI guidelines on digital health platform interoperability are shaping capital deployment into remote monitoring infrastructure. The Kanto region surrounding Tokyo anchors specialist therapist availability, while telehealth platforms extend reach into Tohoku and rural Honshu territories.
United Kingdom
NHS Integrated Care Systems are consolidating rehabilitation procurement around episode-based contracts with readmission risk assumption. NICE clinical guidelines on post-stroke recovery are standardizing outcome measurement protocols that streamline documentation requirements. Greater Manchester and West Midlands health systems are piloting the most advanced remote monitoring integration between hospital discharge and home-based functional recovery.
Canada
Provincial health authority restructuring is expanding home care eligibility for post-surgical and chronic condition populations. Health Canada regulatory frameworks on medical device software are shaping platform certification requirements for AI-driven functional assessment tools. Ontario's Local Health Integration Networks and British Columbia's regional health authorities are deploying the most concentrated remote therapeutic monitoring pilots.
Home Rehabilitation Services Market Competitive Landscape
The competitive structure tilts toward integrated health systems with inpatient-to-home health continuums. Consolidation pressure from payer risk-shifting is concentrating vendor relationships around platforms that assume episode accountability. Three archetypes dominate: national post-acute chains with geographic density, medical equipment manufacturers with technology-anchored service models, and regional specialists with narrow-network health system alignment. M&A activity targets metropolitan service territories with Medicare Advantage penetration, while strategic partnerships between equipment suppliers and service platforms are accelerating.
Within the integrated post-acute tier, Encompass Health and Aveanna Healthcare Holdings occupy positions as scale-driven national platforms with regulatory infrastructure advantages. Stryker Corporation exemplifies the equipment-anchored archetype, leveraging durable medical equipment portfolios to anchor technology leadership in mobility-assisted recovery protocols. Invacare Corporation sits within the specialized equipment distribution segment, supporting provider scale in residential settings through capital equipment logistics.
| Leading Market Players |
|---|
| RehabCare Group |
| Invacare Corporation |
| Stryker Corporation |
| Medline Industries |
| Encompass Health |
| Infinity Rehab |
| PTS Rehab |
| Aveanna Healthcare Holdings |
| DispatchHealth |
| Others |
Supply & Pricing Matrix
Medical-grade polymer price indices and semiconductor component benchmarks cascade through durable medical equipment manufacturing into tiered service pricing across home rehabilitation markets. CMS episode-based reimbursement compression at the buyer level feeds backward into equipment procurement cycles, shortening capital refresh timelines and favoring leasing structures over ownership.
Pricing Analysis
Bundled episode contracts dominate Medicare Advantage markets while unbundled per-visit billing persists in traditional fee-for-service channels. Pricing stratifies across technology-integrated premium tiers, standard licensed-clinician services, and economy telehealth-only offerings. Cost compression in standard tiers is intensifying because skilled labor scarcity commands wage premiums that outpace reimbursement rate adjustments. Post-surgical orthopedic episodes show least price sensitivity due to surgeon-directed referral capture, while senior chronic care segments exhibit highest sensitivity to out-of-pocket cost exposure.
Supply Chain Analysis
Direct-to-provider channels handle hyperscale health system demand while durable medical equipment distributors serve fragmented regional agency networks. Manufacturing concentrates in China for consumer-grade rehabilitation devices, Germany for precision motion control systems, and the United States for FDA-cleared therapeutic electronics. Supply chains draw from lithium-ion battery cells, medical-grade polymers, and custom sensor arrays. Single-source vulnerability concentrates in semiconductor components for remote monitoring platforms. Distribution runs through third-party logistics providers with cold-chain capabilities for sensitive electronic inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home rehabilitation services function as a geographic-arbitrage play where CMS reimbursement rate differentials between high-cost metropolitan corridors and rural wage markets create margin expansion opportunities for platforms with distributed workforce models.
For Market Incumbents: Hedge against telehealth platform commoditization by deepening clinical outcome data assets that secure narrow-network exclusivity. Acquire physical therapist assistant training pipelines to preempt scope-of-practice expansion labor competition. Anchor defensive positioning in episode-based risk contracts that lock out regional specialists from Medicare Advantage procurement. For New Entrants and Emerging Players: AI-driven remote therapeutic monitoring platforms offer technology-first wedge into rural territories excluded from specialist density. Target heart failure and COPD chronic populations as underpenetrated segments beyond orthopedic post-surgical saturation. Pursue direct-to-employer contracting channels that bypass traditional payer utilization management. For Investors and Strategic Acquirers: Consolidation pressure builds where Medicare Advantage penetration exceeds threshold density for episode-based contracting viability. Five-to-ten year viability favors platforms with integrated inpatient-to-home health continuums and proprietary outcome measurement protocols. Monitor state-level scope-of-practice legislation as inflection signal for labor cost restructuring and competitive density shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Therapeutic Monitoring Platform Deployment | CMS reimbursement parity enables continuous data revenue streams beyond visit-based models. |
| Physical Therapist Assistant Training Pipeline Acquisition | Scope-of-practice expansion preparedness secures labor cost advantage in metropolitan markets. |
| Narrow-Network Health System Partnership | Episode-based risk assumption locks in referral volume and readmission penalty protection. |
| AI-Driven Functional Assessment Tool Certification | FDA clearance for software companion devices differentiates bundled service offerings. |
| Rural Territory Telehealth Infrastructure Buildout | Connectivity investment captures CMS-reimbursable specialist access in underserved regions. |
Research Methodology
Multiple input streams — executive interviews with home health agency operators, regulatory affairs specialists at CMS contractors, and biomedical equipment procurement managers — were reconciled against secondary validation from CMS Medicare claims databases, state health department licensing records, and hospital discharge data systems. Primary fieldwork captured episode-based contracting terms and workforce deployment patterns. Bottom-up service volume estimates triangulated against top-down reimbursement expenditure flows.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, patient clinical acuity, payment model archetype, and delivery method technology intensity. CAGRs derived from historical episode volume trajectories and reimbursement rate adjustment schedules. Forecast inputs incorporated orthopedic procedure volume projections and Medicare Advantage penetration curves by metropolitan statistical area.
The model holds under stable CMS reimbursement rulemaking and gradual scope-of-practice liberalization; deviation in federal payment parity policy or abrupt regulatory restriction on telehealth delivery would shift volume and value trajectories. Periodic stress-testing of base assumptions against state-level legislative calendars and Medicare Advantage star rating methodology updates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market
Rehabilitation Services
Global Medical Rehabilitation Services Market
Rehabilitation Services
Outpatient Rehabilitation Services Market
Rehabilitation Services
Home Rehabilitation Products Market
Rehabilitation Services
Global Outpatient Rehabilitation Centers Market
Rehabilitation Services
Global Robotic Rehabilitation and Assistive Technologies Market
Rehabilitation Services
Global Neurorehabilitation Devices Market
Rehabilitation Services
Veterinary Rehabilitation Services Market
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
United States Behavioral Rehabilitation Market
Rehabilitation Services
Speech Pathology Services Market
Rehabilitation Services
Behavioral Rehabilitation Market
Rehabilitation Services
VR Stroke Rehabilitation Market
Rehabilitation Services
Massage Therapy Services Market
Rehabilitation Services
Rehabilitation Products Market
Rehabilitation Services
Global Gait Trainer Market