
 Global Gait Trainer Market | 2026-2036
Global Gait Trainer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gait Trainer Market Foresight
CE-marked Class IIa certification is reorganizing competitive dynamics across the European rehabilitation equipment sector. Ekso Bionics leverages its FDA and CE dual-certification portfolio to anchor premium positioning in North American and European hospital networks. Tyromotion GmbH sustains engineering intensity in sensor-integrated treadmill systems, while Ottobock dominates prosthetics-adjacent gait training through its clinical distribution infrastructure.
A gait trainer is an electromechanical or body-weight-supported ambulation device engineered with adjustable harness systems, motorized treadmill bases, or robotic exoskeleton actuators to restore locomotor patterns in patients with neurological or musculoskeletal impairments. Robotic-assisted configurations command the highest unit economics due to servo-motor complexity and real-time kinematic feedback integration. Treadmill-based systems retain the largest installed base across rehabilitation centers, though mobile gait systems are gaining fastest in home-based deployment segments where space constraints and reimbursement flexibility reshape procurement criteria. Body weight support architectures occupy the mid-tier margin pool as hospitals balance clinical efficacy against capital expenditure limits.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access barriers for gait trainer manufacturers. Japan's PMDA enforces stringent clinical evidence standards for robotic rehabilitation devices that filter out lower-capability entrants. Germany's KBA-equivalent medical device surveillance and ISO 13485 quality management mandates further elevate compliance costs across the supply base. Stakeholders must monitor reimbursement code expansions for tele-rehabilitation platforms as payers reassess remote neurological therapy protocols.
Market Dynamics
EU MDR Class IIa certification requirements are compressing vendor timelines and elevating compliance expenditure for electromechanical gait systems, forcing manufacturers to consolidate technical documentation resources ahead of notified body audits.
Growth Catalysts
- Japan METI Funding Streams:Subsidies for aging-in-place neurological technologies accelerate procurement of mobile gait systems for home-based rehabilitation, expanding addressable patient populations beyond institutional settings.
- Sensor-Integrated Treadmill Architectures:Real-time kinematic feedback loops improve locomotor pattern restoration outcomes, driving replacement cycles in German rehabilitation centers seeking measurable therapy metrics.
- FDA 510(k) Pathway Clarity:Streamlined predicate device referencing for robotic exoskeleton submissions reduces regulatory uncertainty, enabling faster commercialization timelines for servo-motor gait platforms.
Market Restraints
- Servo-Motor Input Cost Volatility:Rare earth magnet supply concentration in Chinese processing facilities creates margin pressure for robotic-assisted gait trainer manufacturers dependent on high-torque actuator assemblies.
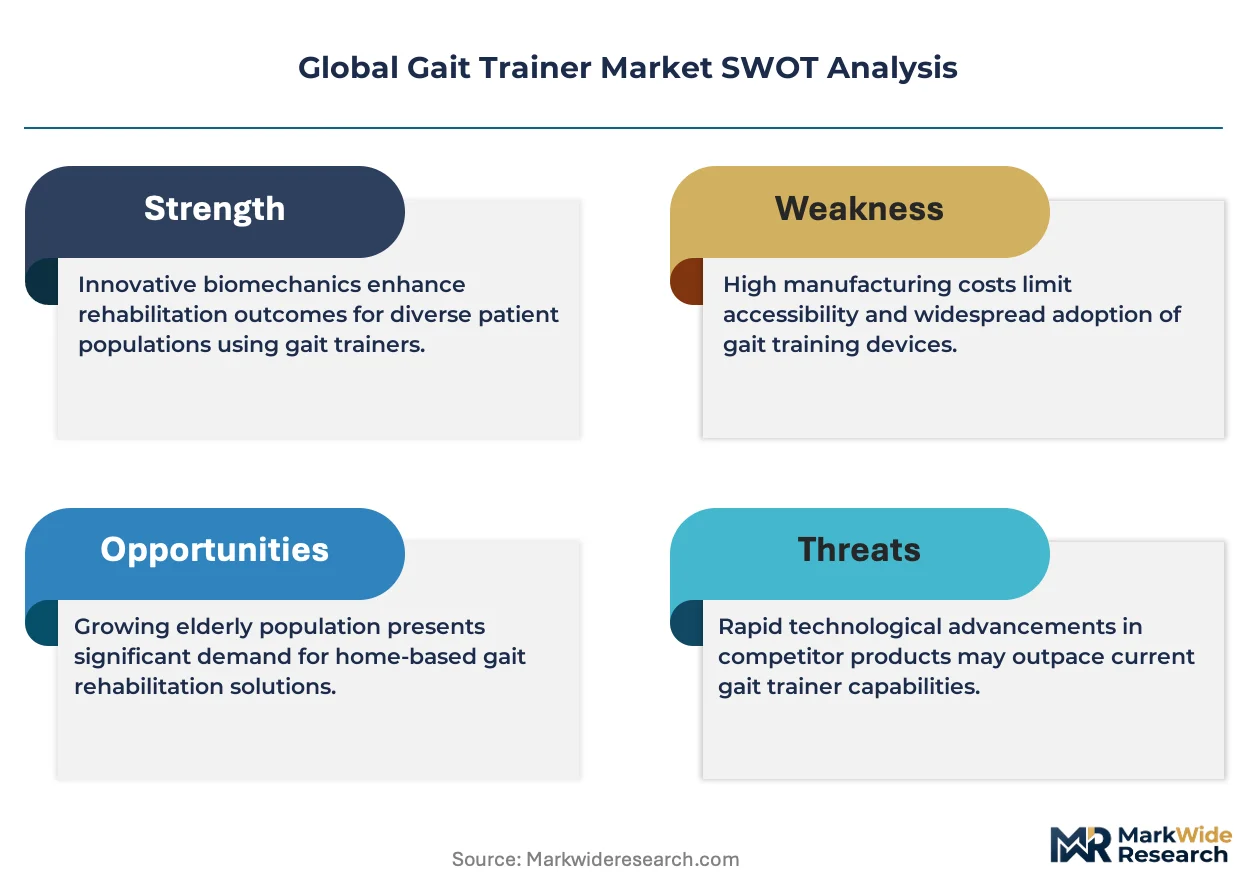
- EU MDR Technical Documentation Burden:Clinical evidence requirements for Class IIa electromechanical devices extend product development cycles by 18-24 months, filtering out mid-cap engineering firms from European market entry.
- Body-Weight-Support System Substitution:Lower-cost harness-based treadmill configurations capture price-sensitive procurement in emerging markets, compressing unit economics for premium robotic platforms.
Strategic Opportunities
- Tele-Rehabilitation Platform Convergence:Integration of gait trainers with remote monitoring software creates subscription revenue streams as US payers reassess reimbursement codes for home-based neurological therapy.
- German KBA-Equivalent Surveillance Gaps:Post-market vigilance requirements for electromechanical medical devices create service contract opportunities for ISO 13485-certified maintenance providers.
- India PLI Scheme Alignment:Domestic manufacturing incentives for medical electronics attract joint venture partnerships targeting cost-optimized gait system production for South Asian rehabilitation networks.
Industry Challenges
- Biomechanical Engineer Talent Scarcity:Cross-disciplinary expertise spanning robotics, neurology, and clinical validation remains concentrated in Swiss and German research clusters, constraining R&D scaling for new market entrants.
- Legacy Hospital IT Integration Friction:Electromechanical gait systems require HL7 FHIR-compliant data architecture upgrades to connect with existing electronic health record infrastructures, extending sales-to-implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gait Trainer Market |
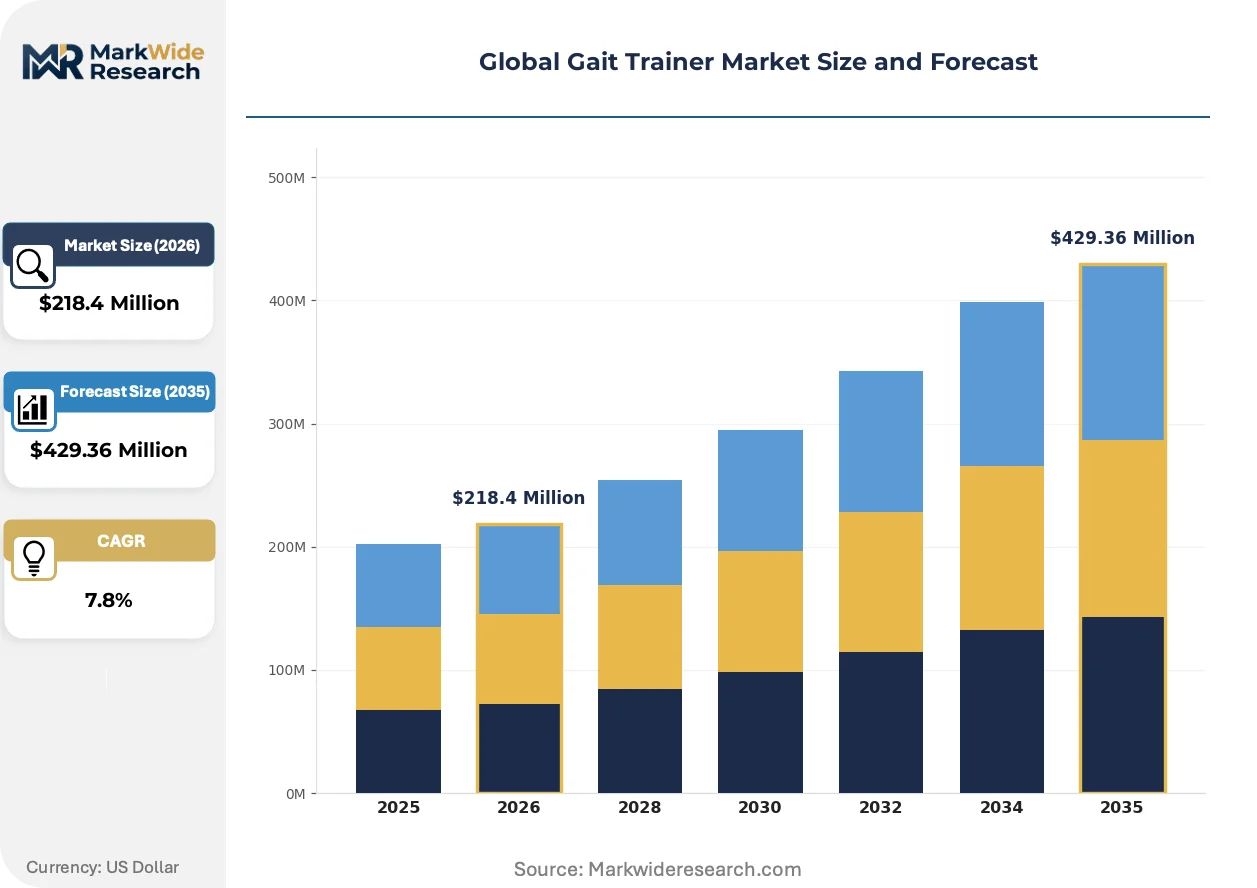
| Market Size in 2026 | $218.4 Million |
| Market Size in 2035 | $429.36 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Weight Support, Overground Trainers, Treadmill-Based, Robotic-Assisted, Mobile Gait Systems Application: Stroke Rehabilitation, Spinal Cord Injury Therapy, Parkinson’s Disease Intervention, Cerebral Palsy Management, Multiple Sclerosis Support End User: Rehabilitation Centers, Physical Therapy Clinics, Neurological Institutes, Research Organizations, Assisted Living Facilities Deployment: In-Clinic, Home-Based, Outpatient Facilities, Mobile Therapy Units, Tele-rehabilitation Platforms |
| Companies Covered | DIH Medical Group, Rex Bionics Ltd., Ekso Bionics, Zebris Medical GmbH, Tyromotion GmbH, Ottobock, Rifton Equipment, Biodex Medical Systems, Lifeward, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gait Trainer Market Shifts & Advancements
Real-time kinematic sensing and actuator miniaturization are compressing form factors and expanding deployment settings for gait rehabilitation technologies. Regulatory frameworks are accelerating certification differentiation. Procurement behaviors are fragmenting across institutional and home-based care models.
Soft exoskeleton actuators incorporating textile-integrated force sensors are miniaturizing drive mechanisms while maintaining torque output sufficient for hemiparetic gait assistance. Japanese rehabilitation hospitals are piloting these systems for outpatient stroke recovery programs. The technology is miniaturizing equipment footprints, enabling deployment in space-constrained urban clinics previously excluded from robotic gait therapy.
EU MDR post-market surveillance mandates require systematic clinical follow-up data collection for Class IIa electromechanical devices, compelling manufacturers to invest in patient registry infrastructure. This regulatory load disproportionately affects mid-tier treadmill-based system suppliers lacking dedicated post-market teams. German rehabilitation networks are consolidating vendor relationships to reduce compliance fragmentation across device portfolios.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, creating standalone maintenance revenue pools. Third-party ISO 13485-certified service providers are capturing calibration and preventive maintenance workflows previously captive to original equipment manufacturers. This pattern is most visible in North American acute care networks seeking operational expenditure predictability.
Global Gait Trainer Market Segmentation
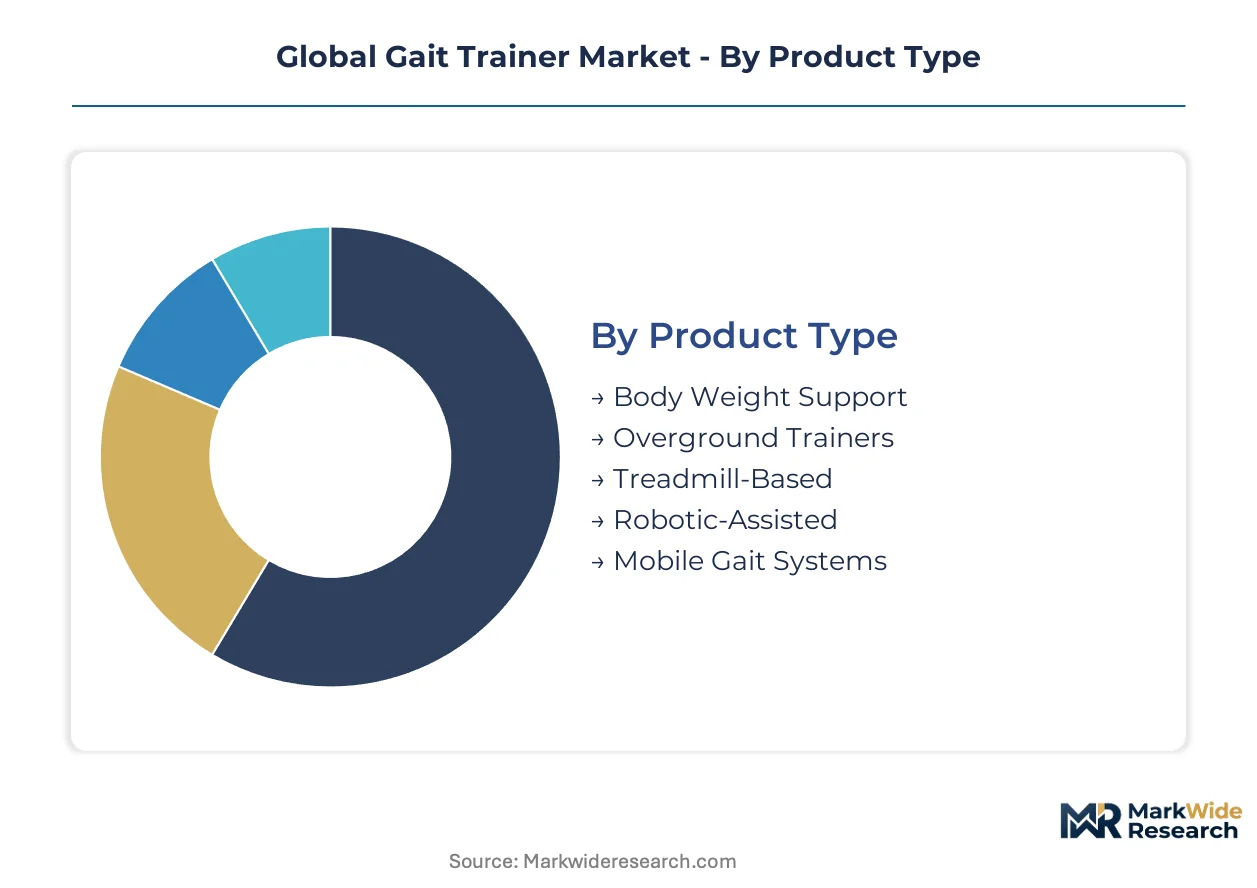
Segmentation reveals how procurement criteria fragment across clinical settings, reimbursement models, and patient acuity levels. Understanding these divides illuminates where manufacturers must differentiate engineering investment versus cost optimization.
Product Type:
Margin pools concentrate in servo-motor configurations where real-time kinematic feedback commands premium pricing, while harness-based systems compete on capital expenditure efficiency.
- Robotic-Assisted:Electromechanical exoskeletons integrate servo-actuators with force-sensitive resistive arrays for real-time gait pattern correction. Demand clusters in German rehabilitation centers seeking EU MDR Class IIa-certified systems with measurable therapy outcomes. METI-subsidized procurement in Japan accelerates adoption for aging-in-place neurological programs.
- Treadmill-Based:Motorized belt systems with adjustable harness support dominate installed bases across institutional settings. German KBA-equivalent surveillance requirements and ISO 13485 quality mandates elevate compliance costs, filtering mid-cap suppliers from European tender processes.
- Body Weight Support:Harness-suspension architectures balance clinical efficacy against capital constraints.
- Overground Trainers:Rail-mounted parallel bar systems serve entry-level rehabilitation protocols.
- Mobile Gait Systems:Compact electromechanical units enable home-based deployment where space constraints reshape procurement criteria.
The dominant share belongs to Treadmill-Based systems, while Mobile Gait Systems are gaining share fastest through Japan's aging-in-place funding streams.
Application:
Clinical evidence requirements vary sharply by neurological condition, with stroke protocols commanding the deepest reimbursement codes and longest device replacement cycles.
- Stroke Rehabilitation:Hemiparetic gait restoration protocols require intensive repetitive task training with measurable kinematic endpoints. Japanese rehabilitation hospitals prioritize sensor-integrated platforms that quantify locomotor pattern recovery for PMDA clinical evidence submissions.
- Spinal Cord Injury Therapy:Complete and incomplete lesion presentations demand body-weight-supported ambulation with fall-protection redundancy. German neurological institutes specify ISO 13485-certified maintenance contracts for electromechanical systems under EU MDR post-market surveillance.
- Parkinson's Disease Intervention:Freezing-of-gait management drives demand for cueing-integrated platforms.
- Cerebral Palsy Management:Pediatric gait patterning requires adjustable growth-accommodating hardware.
- Multiple Sclerosis Support:Fatigue-modulated therapy sessions favor variable-intensity treadmill configurations.
Stroke Rehabilitation commands the deepest installed base, though Spinal Cord Injury Therapy shows the steepest expansion trajectory as exoskeleton evidence portfolios mature.
End User:
Procurement authority concentrates in multi-site rehabilitation networks that can amortize compliance infrastructure across device portfolios.
- Rehabilitation Centers:Multi-disciplinary facilities with dedicated neurological units specify integrated gait laboratories with real-time kinematic feedback. German networks consolidate vendor relationships to reduce EU MDR compliance fragmentation across electromechanical device fleets.
- Physical Therapy Clinics:Outpatient practices prioritize space-efficient configurations with rapid patient turnover protocols. US Medicare reimbursement code expansions for remote neurological therapy accelerate interest in tele-rehabilitation-compatible platforms.
- Neurological Institutes:Academic medical centers drive clinical evidence generation for regulatory submissions.
- Research Organizations:Biomechanics laboratories require open-architecture systems for protocol customization.
- Assisted Living Facilities:Residential care operators seek fall-risk mitigation through low-intensity gait maintenance programs.
Rehabilitation Centers retain the largest capital equipment budgets, while Physical Therapy Clinics are expanding fastest into home-based service lines.
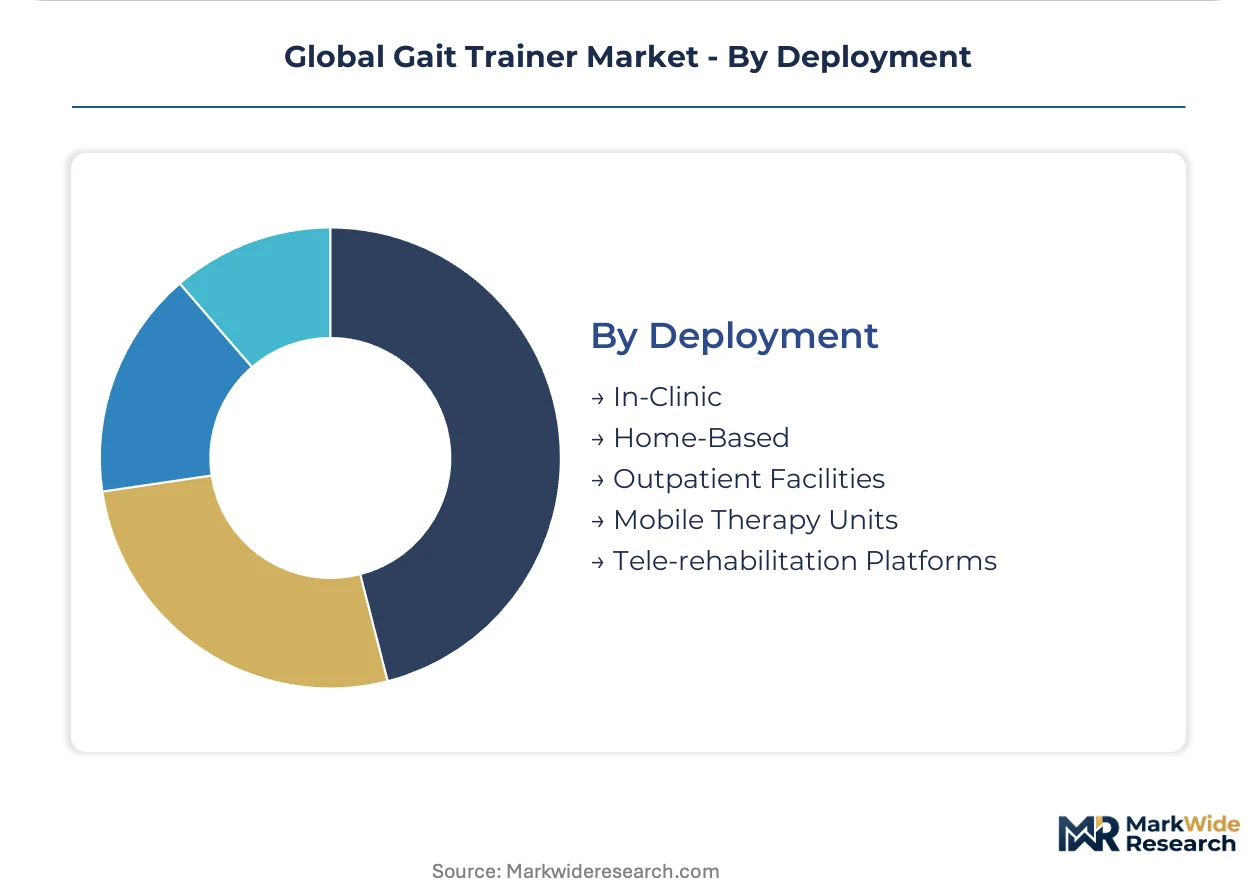
Deployment:
Reimbursement flexibility determines whether procurement favors capital-intensive fixed installations or subscription-model remote platforms.
- In-Clinic:Fixed installations with dedicated therapy spaces support intensive daily protocols. German rehabilitation centers invest in sensor-integrated treadmill architectures to satisfy KBA-equivalent surveillance requirements for systematic clinical outcome documentation.
- Home-Based:Compact electromechanical or body-weight-support systems enable patient-managed rehabilitation schedules. Japan METI funding streams subsidize mobile gait system procurement for aging-in-place neurological programs, expanding addressable populations beyond institutional settings.
- Outpatient Facilities:Shared equipment pools across therapy practices optimize utilization rates.
- Mobile Therapy Units:Vehicle-mounted systems serve rural or homebound patient populations.
- Tele-Rehabilitation Platforms:Remote monitoring software integration creates subscription revenue opportunities as US payers reassess reimbursement codes for home-based neurological therapy.
In-Clinic deployment maintains the dominant revenue share, though Home-Based configurations are climbing the fastest as reimbursement models shift toward value-based care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet processing concentrates in Chinese facilities, creating input cost asymmetries for servo-motor manufacturers serving neurological rehabilitation networks. German engineering clusters and Japanese precision manufacturing zones anchor electromechanical gait system production. Reimbursement code expansions in North American markets and METI-funded aging-in-place programs in Japan reshape demand geography.
Germany
Rehabilitation centers in Baden-Württemberg and Bavaria expand procurement of sensor-integrated treadmill architectures. EU MDR Class IIa certification requirements compress vendor timelines and elevate compliance expenditure for electromechanical systems. The KBA-equivalent medical device surveillance framework and ISO 13485 quality mandates in Stuttgart and Munich filter mid-cap suppliers from tender processes.
United States
Acute care networks in Greater Boston and the Pacific Northwest unbundle after-sales service contracts from capital equipment purchases. FDA 510(k) clearance pathways streamline predicate device referencing for robotic exoskeleton submissions. Physical therapy clinics across the Midwest and Southeast accelerate interest in tele-rehabilitation-compatible platforms as Medicare reassesses remote neurological therapy codes.
Japan
METI funding streams subsidize mobile gait system procurement for aging-in-place neurological programs in Kanto and Kansai regions. PMDA enforces stringent clinical evidence standards for robotic rehabilitation devices that filter out lower-capability entrants. Rehabilitation hospitals in Tokyo and Osaka pilot soft exoskeleton actuators for outpatient stroke recovery programs.
China
Domestic manufacturing capacity for medical electronics expands through joint venture partnerships targeting cost-optimized gait system production. NMPA regulatory pathways for Class II electromechanical devices create market access barriers for foreign manufacturers. Engineering clusters in the Yangtze River Delta and Pearl River Delta concentrate servo-actuator assembly operations.
India
PLI scheme incentives for medical electronics attract partnerships targeting South Asian rehabilitation networks. CDSCO regulatory frameworks for electromechanical medical devices remain less stringent than FDA or EU MDR equivalents. Manufacturing activity concentrates in Maharashtra and Gujarat for cost-optimized harness-based treadmill configurations serving price-sensitive procurement.
Global Gait Trainer Market Competitive Landscape
Concentration sits with dual-certified premium-tier specialists and sensor-integrated engineering houses. The vendor base spans three tiers: FDA/CE dual-certified exoskeleton manufacturers commanding hospital network anchor positions; ISO 13485-certified treadmill system suppliers serving rehabilitation center installed bases; and regional fabricators competing on capital expenditure efficiency for emerging market procurement. M&A activity targets post-market surveillance infrastructure and tele-rehabilitation software capabilities. Geographic expansion focuses on METI-funded Japanese procurement channels and German KBA-equivalent compliance service contracts.
Among German engineering houses, Tyromotion GmbH and Zebris Medical GmbH exemplify sensor-integrated treadmill specialization. Ekso Bionics occupies a position within the dual-certification archetype, anchoring premium positioning through FDA and CE portfolio breadth. Ottobock represents prosthetics-adjacent gait training concentration through clinical distribution infrastructure. These three anchors illustrate how certification depth and distribution architecture separate premium-tier positioning from capital-efficiency competition.
| Leading Market Players |
|---|
| DIH Medical Group |
| Rex Bionics Ltd. |
| Ekso Bionics |
| Zebris Medical GmbH |
| Tyromotion GmbH |
| Ottobock |
| Rifton Equipment |
| Biodex Medical Systems |
| Lifeward |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements for rare earth magnet supply lock in servo-motor cost visibility for robotic gait trainer manufacturers while exposing them to Chinese processing concentration risk. Japanese rehabilitation networks and German hospital procurement committees leverage these contract structures to secure Class IIa-certified electromechanical systems against raw material volatility.
Pricing Analysis
EU MDR Class IIa certification dictates the pricing tier structure across the European rehabilitation equipment sector. Three-tier pricing structure across premium robotic exoskeletons, standard treadmill-based systems, and economy body-weight-support configurations separates FDA/CE dual-certified platforms from ISO 13485-only suppliers. Price differentiation hinges on real-time kinematic feedback capability and bundled after-sales service contracts. Pricing pressure stems from rare earth magnet input cost volatility concentrated in Chinese processing facilities. Emerging market procurement in India and Southeast Asia exhibits highest price sensitivity, while Japanese METI-subsidized aging-in-place programs demonstrate lowest sensitivity due to reimbursement insulation.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for electromechanical component assemblies sourced from Chinese Yangtze River Delta manufacturing clusters. Supply concentrates in China for servo-actuator rare earth processing, Germany for precision sensor engineering, and Japan for soft exoskeleton textile-integrated force sensors. Raw material dependencies span neodymium-iron-boron magnets, high-torque brushless DC motors, and force-sensitive resistive arrays. Single-source vulnerability in Chinese rare earth magnet refining creates structural supply risk. Distribution runs through ISO 13485-certified clinical equipment distributors serving hospital networks and direct procurement contracts with multi-site rehabilitation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment defensive moat where EU MDR Class IIa certification and FDA 510(k) clearance create switching costs that lock hospital networks into validated vendor relationships.
For Market Incumbents: Consolidate post-market surveillance infrastructure through acquisition of ISO 13485-certified service providers to capture unbundled maintenance contracts. Deepen vertical integration into rare earth magnet supply through long-term offtake agreements with Chinese processors to defend against servo-motor input cost volatility threatening robotic platform margins. For New Entrants and Emerging Players: Anchor in Indian PLI scheme-aligned manufacturing partnerships for cost-optimized harness-based treadmill configurations serving price-sensitive South Asian rehabilitation networks. Target CDSCO regulatory pathways for Class II electromechanical devices as the most penetrable certification route outside FDA and EU MDR jurisdictions. Pursue tele-rehabilitation software integration as the primary go-to-market angle for subscription revenue capture in US physical therapy clinics. For Investors and Strategic Acquirers: The market sits at a certification consolidation phase that favors dual-certified premium-tier specialists with established hospital network anchor positions. Long-term viability over the next decade rests on patient registry infrastructure and remote monitoring platform capabilities as EU MDR post-market surveillance mandates deepen. Watch for reimbursement code expansions for home-based neurological therapy as the inflection signal for tele-rehabilitation platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Investment | Technical documentation depth filters mid-cap competitors from German rehabilitation center tenders. |
| Tele-Rehabilitation Software Development | Medicare reimbursement reassessment for remote neurological therapy creates subscription revenue pools. |
| Rare Earth Magnet Supply Agreement | Long-term offtake with Chinese processors secures servo-motor cost visibility against magnet volatility. |
| Post-Market Surveillance Infrastructure | Patient registry capabilities satisfy EU MDR systematic clinical follow-up mandates for electromechanical devices. |
| METI Funding Channel Partnership | Japanese aging-in-place subsidy alignment accelerates mobile gait system procurement beyond institutional settings. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation databases, and Japanese PMDA clinical evidence submissions. Interviews with rehabilitation center procurement directors, biomedical engineers, GPO contracts managers, and ISO 13485-certified service providers inform demand-side validation. Customs trade data for electromechanical medical device imports and hospital procurement database records provide supply-side triangulation. Bottom-up unit economics modeling and top-down market sizing converge through iterative stakeholder cross-checking.
Segmentation dimensions modeled span product type (robotic-assisted, treadmill-based, body weight support, mobile gait systems), application (stroke rehabilitation, spinal cord injury therapy, Parkinson's disease intervention), end user (rehabilitation centers, physical therapy clinics, neurological institutes), and deployment mode (in-clinic, home-based, tele-rehabilitation platforms). CAGRs derive from installed base replacement cycle analysis and reimbursement code expansion trajectories across the projection horizon. Forecast inputs incorporate EU MDR compliance timeline compression effects and METI funding stream allocation patterns.
Material uncertainties — rare earth magnet supply disruption, reimbursement code reversals, and EU MDR notified body audit delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and procurement budget continuity in German and Japanese rehabilitation networks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Home Rehabilitation Services Market
Rehabilitation Services
Behavioral Rehabilitation Market
Rehabilitation Services
Neurorehabilitation Gaming Systems Market
Rehabilitation Services
Occupational and Physical Therapy Services Market
Rehabilitation Services
Veterinary Rehabilitation Services Market
Rehabilitation Services
Rehabilitation Therapy Services Market
Rehabilitation Services
Lower Extremity Rehabilitation Robotics Market
Rehabilitation Services
United States Behavioral Rehabilitation Market
Rehabilitation Services
Speech Therapy Services Market
Rehabilitation Services
Global Robotic Rehabilitation and Assistive Technologies Market
Rehabilitation Services
US Assisted Living Facility and Neurorehabilitation Market
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
Global Women Health Rehabilitation Products Market
Rehabilitation Services
Telerehabilitation Systems Market
Rehabilitation Services
Motion Stimulation Therapy Market
Rehabilitation Services
Outpatient Rehabilitation Services Market