
 Outpatient Rehabilitation Services Market | 2026-2036
Outpatient Rehabilitation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Outpatient Rehabilitation Services Market Outlook
Multi-source contracting between health systems and independent therapy networks is expanding as hospitals seek to decouple inpatient from outpatient rehabilitation capacity. Select Medical Corporation leverages its national contract portfolio to sustain volume commitments across payers. Mayo Clinic anchors premium referral flows through integrated care pathways. U.S. Physical Therapy, Inc. competes by acquiring regional clinic groups to extend geographic density.
Outpatient rehabilitation services encompass structured therapeutic interventions delivered outside inpatient facilities, typically involving supervised exercise protocols, manual therapy techniques, and functional training regimens administered in ambulatory settings. These services restore mobility, reduce pain, and prevent rehospitalization following injury, surgery, or chronic disease progression. Physical therapy dominates service mix by volume due to orthopedic and neurological referral patterns, while teletherapy represents the fastest-growing delivery mode as remote monitoring platforms mature. Wearable devices within the technology segment concentrate margin pools through recurring data subscriptions tied to payer risk contracts.
FDA oversight of therapeutic devices and software-as-medical-device classifications shapes technology adoption timelines for biofeedback systems and robotics platforms. CMS reimbursement guidelines and state-level physical therapy practice acts jointly determine scope-of-service expansion and provider billing autonomy. Stakeholders must monitor evolving Medicare Advantage carve-out negotiations and state telehealth parity laws to anticipate network participation requirements.
Market Dynamics
Telehealth parity legislation and remote monitoring reimbursement codes are decoupling rehabilitation capacity from physical clinic footprints, forcing providers to rebuild care delivery around virtual-first intake protocols and wearable-validated outcomes.
Growth Catalysts
- Medicare Advantage carve-outs:CMS risk-adjustment models now reward plans that reduce acute episodes through preventive therapy, expanding covered sessions for chronic pain management.
- Wearable biofeedback integration:Continuous motion tracking from consumer devices enables remote therapeutic exercise validation without clinic attendance.
- Orthopedic surgical volume:Joint replacement procedures among Medicare beneficiaries generate predictable post-acute rehabilitation demand with standardized recovery protocols.
Market Restraints
- Physical therapist labor scarcity:Entry-level DPT graduates face wage compression against travel staffing agencies, destabilizing clinic staffing models.
- Site-neutral payment cuts:CMS proposals to equalize hospital outpatient department and independent clinic reimbursement threaten health system therapy margins.
- Prior authorization friction:Commercial payers impose escalating documentation requirements for episode extension requests, delaying care initiation.
Strategic Opportunities
- Rural health clinic waivers:Federally qualified health centers in frontier counties can bill Medicare for telehealth rehabilitation without originating site restrictions.
- Workers compensation carve-ins:Employers in manufacturing-heavy states are direct-contracting with therapy networks to reduce indemnity costs.
- AI-assisted documentation:Natural language processing tools are automating G-code reporting for functional limitation claims, reducing administrative burden.
Industry Challenges
- Interoperability fragmentation:EHR systems from Epic, Cerner, and Meditech lack standardized outcome measure exchange, complicating referral handoffs.
- Outcome measure validation:Payers demand patient-reported outcome instruments that lack normative data for diverse populations, creating reporting bias.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outpatient Rehabilitation Services Market |
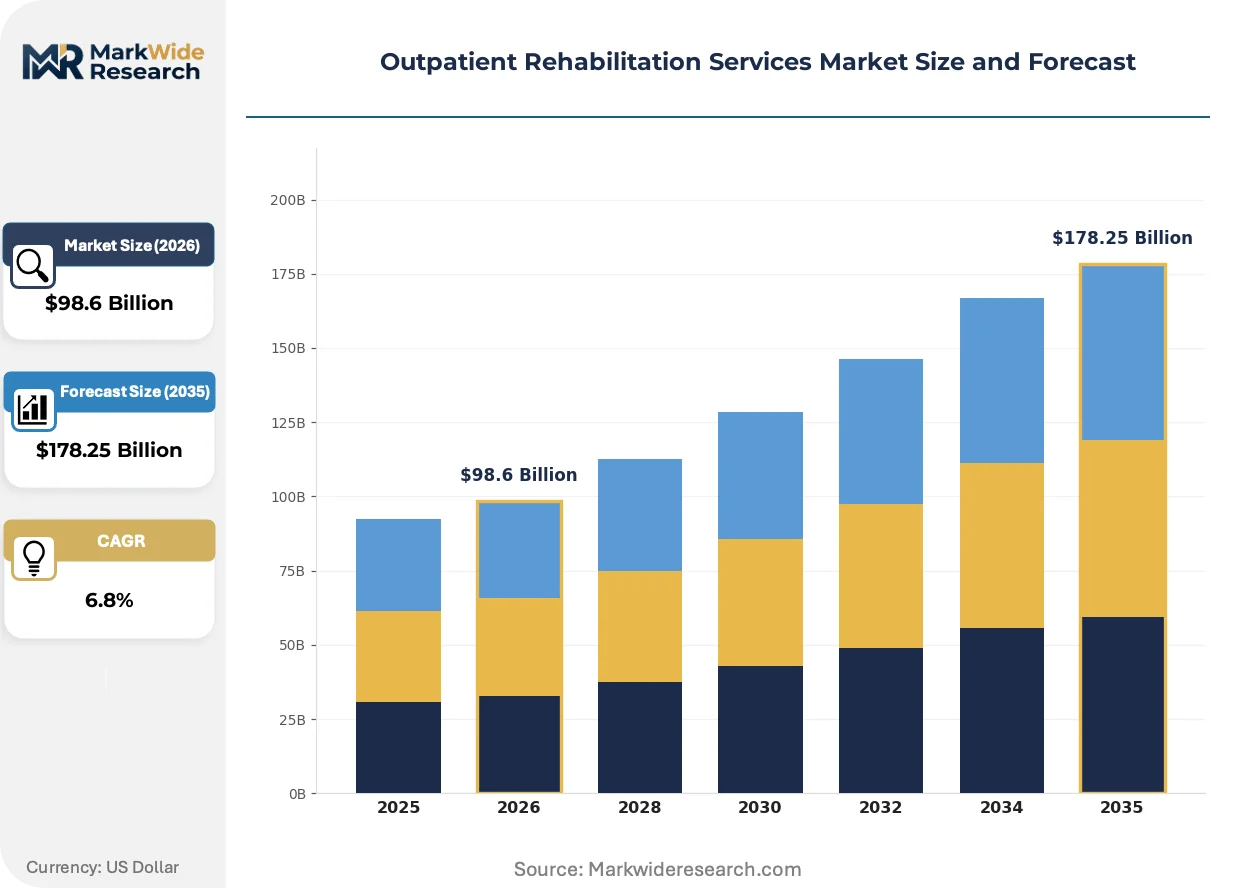
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Physical Therapy, Occupational Therapy, Speech Therapy, Rehabilitation Nursing Delivery Mode: In-Person Therapy, Teletherapy, Home Health Care, Group Sessions End User: Patients, Medical Institutions, Outpatient Clinics, Home Care Providers Technology: Wearable Devices, Virtual Reality, Robotics, Biofeedback Systems |
| Companies Covered | ATI Physical Therapy, The Mount Sinai Health System, Select Medical Corporation, Athletico Physical Therapy, Kessler Institute for Rehabilitation, Upstream Rehabilitation, Mayo Clinic, NovaCare Rehabilitation, U.S. Physical Therapy, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outpatient Rehabilitation Services Market Strategic Shifts
Rehabilitation delivery is bifurcating into high-touch manual therapy and algorithm-driven home exercise programs, with reimbursement models struggling to price the middle ground. Technology vendors and provider networks are racing to own the data layer that connects these modalities.
Robotic exoskeletons for gait training are rewriting the economics of neurorehabilitation by reducing therapist-to-patient ratios during high-intensity locomotor sessions. Spinal cord injury programs at Veterans Affairs medical centers are deploying these systems at scale. The capital cost per device is compressing as leasing models replace outright purchase, enabling community hospital access.
State telehealth parity laws are mandating equivalent reimbursement for synchronous video and in-person physical therapy evaluation, removing the financial penalty for virtual-first care models. California, Texas, and Florida have enacted comprehensive parity statutes. Independent practice associations are restructuring network contracts to capture these payments.
Self-referral demand is displacing physician-directed channels as direct access laws in all fifty states allow patients to initiate physical therapy without prior medical authorization. Employer-sponsored health plans are steering members toward this lower-cost entry point. The shift is most pronounced in musculoskeletal benefit designs within self-insured manufacturing and logistics workforces.
Outpatient Rehabilitation Services Market Segmentation
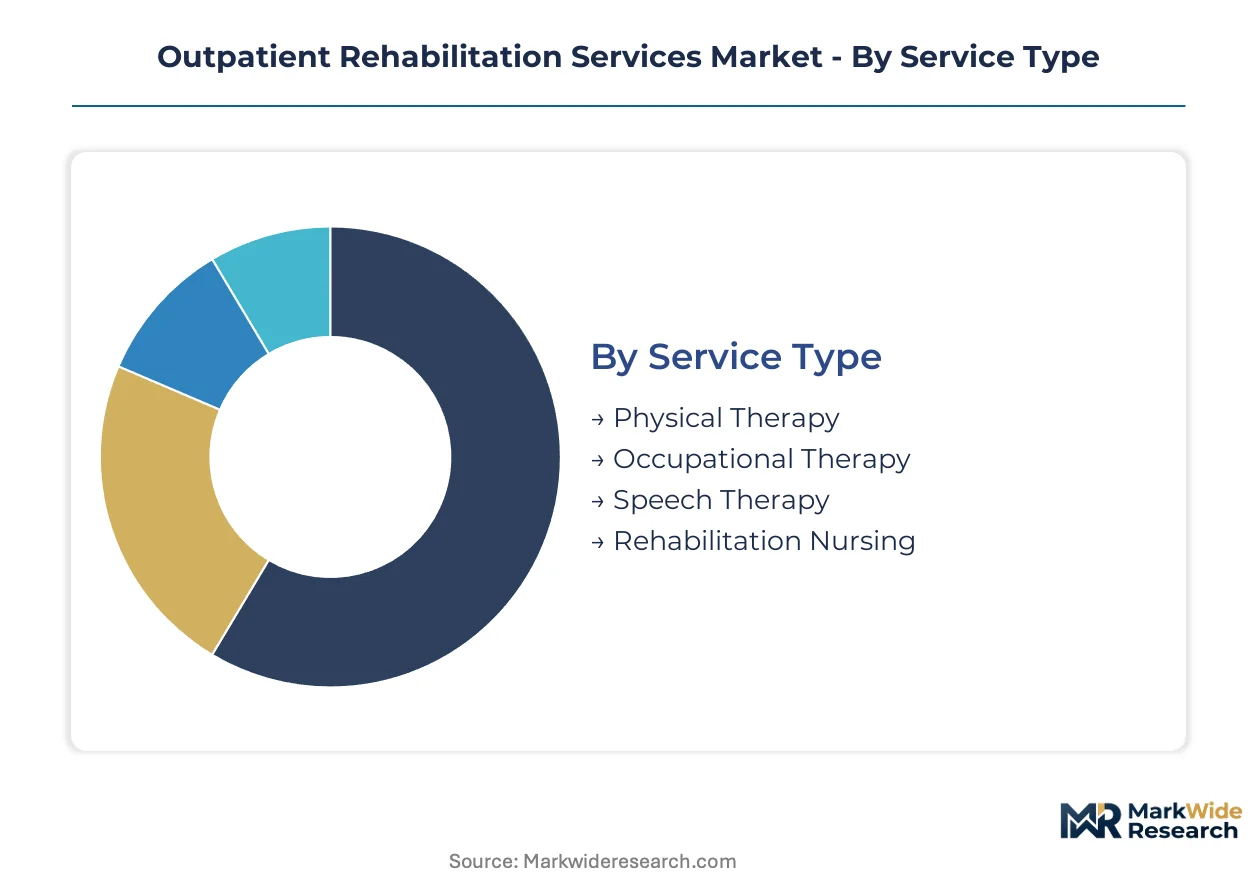
Segmentation in outpatient rehabilitation services reveals how reimbursement models and care delivery innovations are reshaping provider economics. Understanding these divisions clarifies where capital is concentrating and which modalities face margin compression.
Service Type:
Integration depth varies sharply across service lines, with some operating as standalone profit centers while others embed within broader episode-of-care contracts.
- Physical Therapy:Comprises supervised exercise protocols, manual manipulation, and functional movement training delivered by licensed PTs. Demand concentrates in post-operative orthopedic recovery among Medicare beneficiaries in Florida and Texas, where joint replacement volumes drive predictable referral flows. Site-neutral payment proposals from CMS threaten hospital outpatient department margins.
- Occupational Therapy:Focuses on restoring activities of daily living through adaptive equipment training and cognitive rehabilitation. Pediatric autism services in California and stroke recovery programs in Pennsylvania generate the steepest volume growth, though therapist supply constraints limit expansion.
- Speech Therapy:Addresses swallowing disorders and language rehabilitation through structured cognitive-linguistic exercises.
- Rehabilitation Nursing:Provides wound care, medication management, and patient education within ambulatory clinic settings.
Physical Therapy leads volumes today; Occupational Therapy is gaining share fastest.
Delivery Mode:
Cost tier stratification separates high-overhead facility-based care from distributed home and virtual models.
- In-Person Therapy:Traditional clinic-based delivery with direct therapist supervision and hands-on manual techniques. Medicare Part B reimbursement sustains network density in urban corridors, though commercial payer prior authorization requirements are lengthening intake delays.
- Teletherapy:Synchronous video evaluation and asynchronous exercise prescription through remote monitoring platforms. Rural health clinic waivers in frontier counties enable Medicare billing without originating site restrictions, accelerating adoption.
- Home Health Care:Therapist visits to patient residences for mobility training and equipment setup.
- Group Sessions:Concurrent rehabilitation for multiple patients with similar functional limitations.
In-Person Therapy retains the largest revenue base; Teletherapy is climbing the fastest.
End User:
Customer type determines contracting leverage and pricing discipline across the value chain.
- Patients:Direct access laws in all fifty states now permit self-referral without physician authorization. Self-insured employers in manufacturing and logistics sectors steer members toward this lower-cost entry point, particularly for musculoskeletal complaints.
- Medical Institutions:Health systems contract with independent therapy networks to decouple inpatient from outpatient capacity. Multi-source agreements allow selective partnership based on quality metrics and cost targets.
- Outpatient Clinics:Independent practices and franchise networks competing on geographic convenience.
- Home Care Providers:Agencies integrating rehabilitation into bundled post-acute services.
Patients represent the dominant volume channel; Medical Institutions are expanding contract value most quickly.
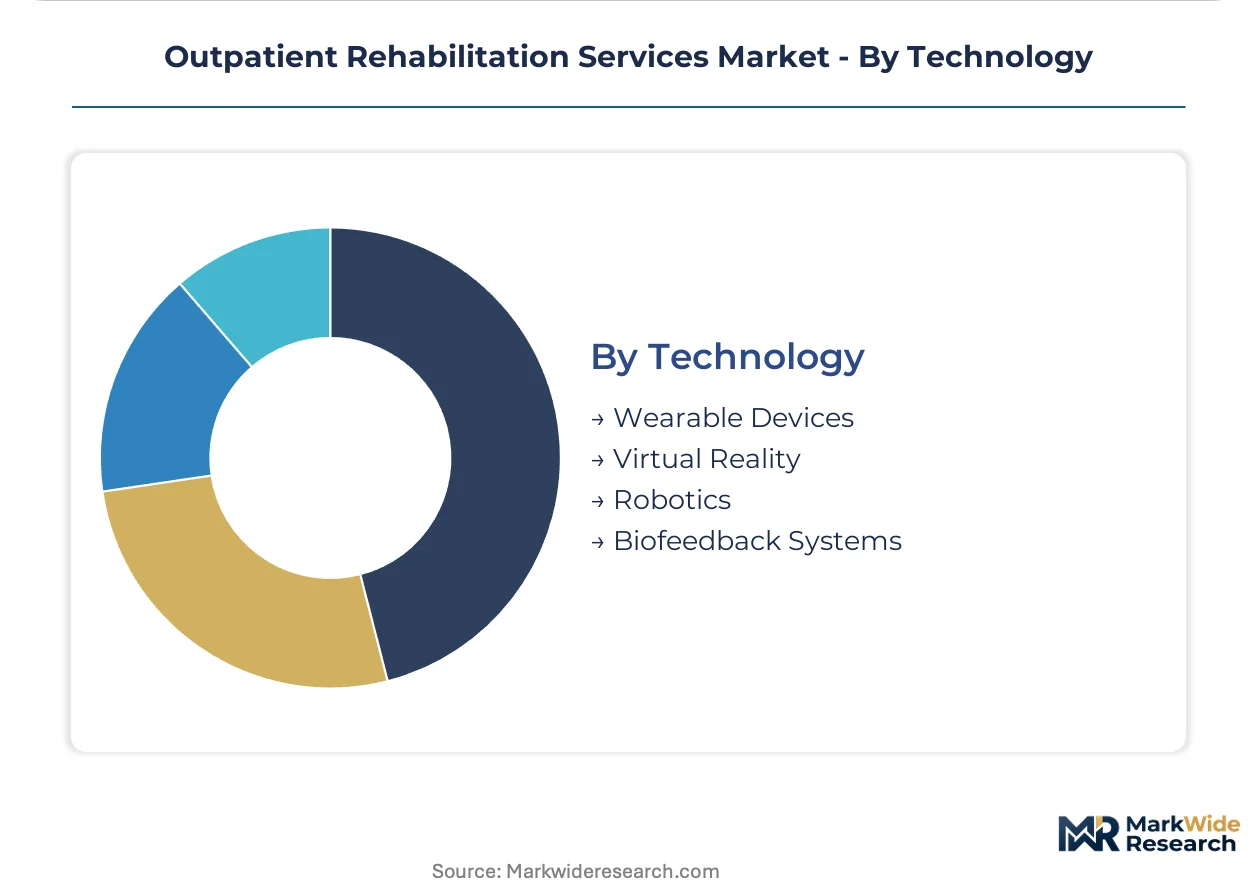
Technology:
Maturity curves separate proven reimbursement pathways from experimental platforms still seeking coverage determination.
- Wearable Devices:Consumer and clinical-grade motion sensors enabling continuous activity tracking and remote therapeutic exercise validation. Recurring data subscriptions tied to payer risk contracts concentrate margin pools for platform vendors.
- Robotics:Exoskeleton systems for gait training in spinal cord and stroke rehabilitation. VA medical centers deploy these at scale, while leasing models compress capital costs for community hospital access.
- Virtual Reality:Immersive environments for balance training and pain distraction protocols.
- Biofeedback Systems:Surface electromyography and pressure mapping for neuromuscular re-education.
Wearable Devices command the largest installed base; Robotics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas Medical Center in Houston anchors the world's largest concentration of outpatient rehabilitation facilities, with over 60 million patient visits annually driving specialized orthopedic and neurological recovery programs across multiple hospital systems.
United States
Medicare Part B reimbursement sustains dense clinic networks in Florida and Texas, where joint replacement volumes among retirees generate predictable post-operative demand. CMS site-neutral payment proposals threaten hospital outpatient department margins while expanding independent clinic opportunities. The Mayo Clinic in Rochester, Minnesota anchors premium referral flows through integrated care pathways that extend across the Upper Midwest.
Germany
Aging demographics and statutory health insurance coverage sustain robust demand for ambulatory rehabilitation following orthopedic surgery and stroke recovery. The German Social Code (SGB V) mandates employer-financed rehabilitation benefits, creating stable funding streams for outpatient networks. The Ruhr Valley industrial region concentrates occupational therapy services for manufacturing workforce injury prevention and return-to-work programs.
Japan
Super-aging society dynamics expand demand for post-acute rehabilitation outside institutional settings as bed capacity constraints intensify. METI promotes robotic rehabilitation device adoption through regulatory fast-track pathways and reimbursement pilot programs. The Kansai region around Osaka hosts concentrated development of gait training exoskeleton systems for spinal cord injury patients.
United Kingdom
NHS England's community rehabilitation transformation program shifts musculoskeletal care from hospitals to ambulatory settings, expanding independent sector capacity contracts. NICE guidelines increasingly recommend structured exercise therapy as first-line intervention for chronic pain conditions. Greater Manchester's integrated care system pilots outcome-based payment models linking therapist reimbursement to functional improvement metrics.
Australia
Medicare-subsidized chronic disease management plans expand allied health referral volumes for diabetes and cardiovascular rehabilitation in community settings. The TGA regulates therapeutic device claims for wearable biofeedback systems entering remote monitoring programs. Sydney's northern suburbs concentrate private practice networks serving affluent populations with direct-access musculoskeletal services.
Outpatient Rehabilitation Services Market Competitive Environment
Global majors compete with regional champions across contract portfolio scale, with national therapy networks leveraging payer relationships against health system-integrated providers. Market structure tilts toward consolidation as multi-source contracting between hospitals and independent clinics accelerates capacity decoupling. Three archetypes dominate: integrated health systems with captive referral flows, national contract aggregators sustaining volume commitments across payers, and geographic density builders acquiring regional clinic groups. Competitive moves center on M&A-driven scale accumulation and telehealth platform integration to capture remote monitoring reimbursement.
Within the national contract aggregator tier, Select Medical Corporation and U.S. Physical Therapy, Inc. exemplify divergent scale strategies. Select Medical leverages its national contract portfolio to sustain volume commitments across Medicare Advantage and commercial payer networks. U.S. Physical Therapy competes through regional clinic group acquisitions that extend geographic density in target metropolitan corridors. Mayo Clinic occupies a position as the integrated health system archetype, anchoring premium referral flows through care pathway integration rather than network breadth.
| Leading Market Players |
|---|
| ATI Physical Therapy |
| The Mount Sinai Health System |
| Select Medical Corporation |
| Athletico Physical Therapy |
| Kessler Institute for Rehabilitation |
| Upstream Rehabilitation |
| Mayo Clinic |
| NovaCare Rehabilitation |
| U.S. Physical Therapy, Inc. |
| Others |
Value Chain & Pricing Dynamics
Medical device component indices and physical therapist wage benchmarks cascade through outpatient rehabilitation supply chains into distinct pricing tiers, with labor cost differentials between metropolitan and rural markets creating geographic arbitrage opportunities for network operators.
Pricing Analysis
Input-cost pass-through from therapist labor and medical device procurement shapes reimbursement negotiations across service tiers. Three-tier pricing structure across premium, standard, and economy levels separates health system-integrated programs from independent clinic networks and telehealth-only providers. Price differentiation hinges on geographic density and payer contract breadth. Pricing pressure stems from CMS site-neutral payment proposals compressing hospital outpatient department margins. Self-insured employers exhibit highest price sensitivity; Medicare Advantage plans demonstrate lowest sensitivity due to risk-adjustment subsidies.
Supply Chain Analysis
Regional distribution centers for therapeutic equipment concentrate in Texas, Florida, and California, with hub-and-spoke patterns radiating to satellite clinic locations. Supply chains draw from domestic physical therapist labor pools, imported rehabilitation robotics from Japan and Germany, and wearable sensors from South Korea and China. Single-source vulnerability concentrates in exoskeleton component suppliers. Distribution runs through national therapy networks, health system central procurement, and direct-to-clinic vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outpatient rehabilitation functions as a geographic-arbitrage play where Medicare reimbursement rates in Florida and Texas exceed therapist wage costs by wider margins than in California or New York, rewarding clinic density in Sun Belt corridors.
For Market Incumbents: Acquire regional clinic networks in underserved metropolitan corridors to preempt competitor footprint expansion. Consolidate telehealth platform capabilities to capture remote monitoring reimbursement codes before parity legislation matures. Defend against independent practice association encroachment by locking multi-year payer contracts with volume guarantees. For New Entrants and Emerging Players: Capture rural health clinic waiver eligibility in frontier counties where Medicare telehealth billing lacks originating site restrictions. Target workers compensation carve-in opportunities in manufacturing-heavy states. Penetrate through direct-to-employer contracting that bypasses traditional referral channel gatekeepers. For Investors and Strategic Acquirers: Asymmetric upside sits with telehealth-enabled therapy platforms possessing wearable data integration and payer risk contract relationships. Long-term viability centers on owning the data layer connecting in-person and virtual modalities. Monitor Medicare Advantage carve-out negotiations as the inflection signal for network valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Enables CMS-compliant remote therapeutic monitoring reimbursement capture across state lines. |
| Wearable Data Partnership | Secures recurring revenue streams tied to payer risk contracts for motion validation. |
| Regional Clinic Acquisition | Extends geographic density in Sun Belt corridors with favorable Medicare wage arbitrage. |
| Workers Compensation Direct Contract | Bypasses physician referral channels in manufacturing-heavy employer markets. |
| AI-Assisted Documentation Deployment | Automates G-code functional limitation reporting to reduce administrative overhead. |
Study Parameters
Direct dialogue with outpatient rehabilitation clinic operators, physical therapy practice owners, Medicare Advantage plan contracting officers, hospital system procurement directors, and wearable device platform engineers grounded qualitative insights. Secondary validation drew from CMS Medicare data, state physical therapy practice act filings, FDA 510(k) therapeutic device clearances, and commercial payer prior authorization policy documents. Bottom-up clinic capacity modeling triangulated against top-down reimbursement flow analysis.
Segment-level projections across service type, delivery mode, end user, and technology dimensions structured the analytical framework over the projection horizon. CAGRs derived from surgical volume trajectories, demographic aging curves, and telehealth adoption elasticity estimates. Forecast inputs incorporated orthopedic procedure forecasts among Medicare beneficiaries and state-level telehealth parity legislative momentum.
Underlying measurement precision varies by segment; physical therapy volume estimates carry tighter precision than emerging robotics platform adoption curves. Forecasts reflect documented assumptions regarding CMS reimbursement stability and therapist supply elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
United States Behavioral Rehabilitation Market
Rehabilitation Services
Wearable Neurorehabilitation Devices Market
Rehabilitation Services
VR Stroke Rehabilitation Market
Rehabilitation Services
US Assisted Living Facility and Neurorehabilitation Market
Rehabilitation Services
Home Rehabilitation Services Market
Rehabilitation Services
Portable Postpartum Rehabilitation Instrument Market
Rehabilitation Services
Rehabilitation Robots Market
Rehabilitation Services
Home Rehabilitation Products Market
Rehabilitation Services
Global Robotic Rehabilitation and Assistive Technologies Market
Rehabilitation Services
Smart Portable Rehabilitation Devices Market
Rehabilitation Services
Asia-Pacific Repair and Rehabilitation Market
Rehabilitation Services
Physiotherapy Services Market
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market
Rehabilitation Services
Occupational and Physical Therapy Services Market
Rehabilitation Services
Exoskeleton and Rehabilitation Robot Safety and Performance Test Equipment Market
Rehabilitation Services
Rehabilitation Therapy Services Market