
 United States Outpatient Rehabilitation Centers Market | 2026-2036
United States Outpatient Rehabilitation Centers Market Size, Share, and Industry Trends Forecast 2026-2036
United States Outpatient Rehabilitation Centers Market Analytics
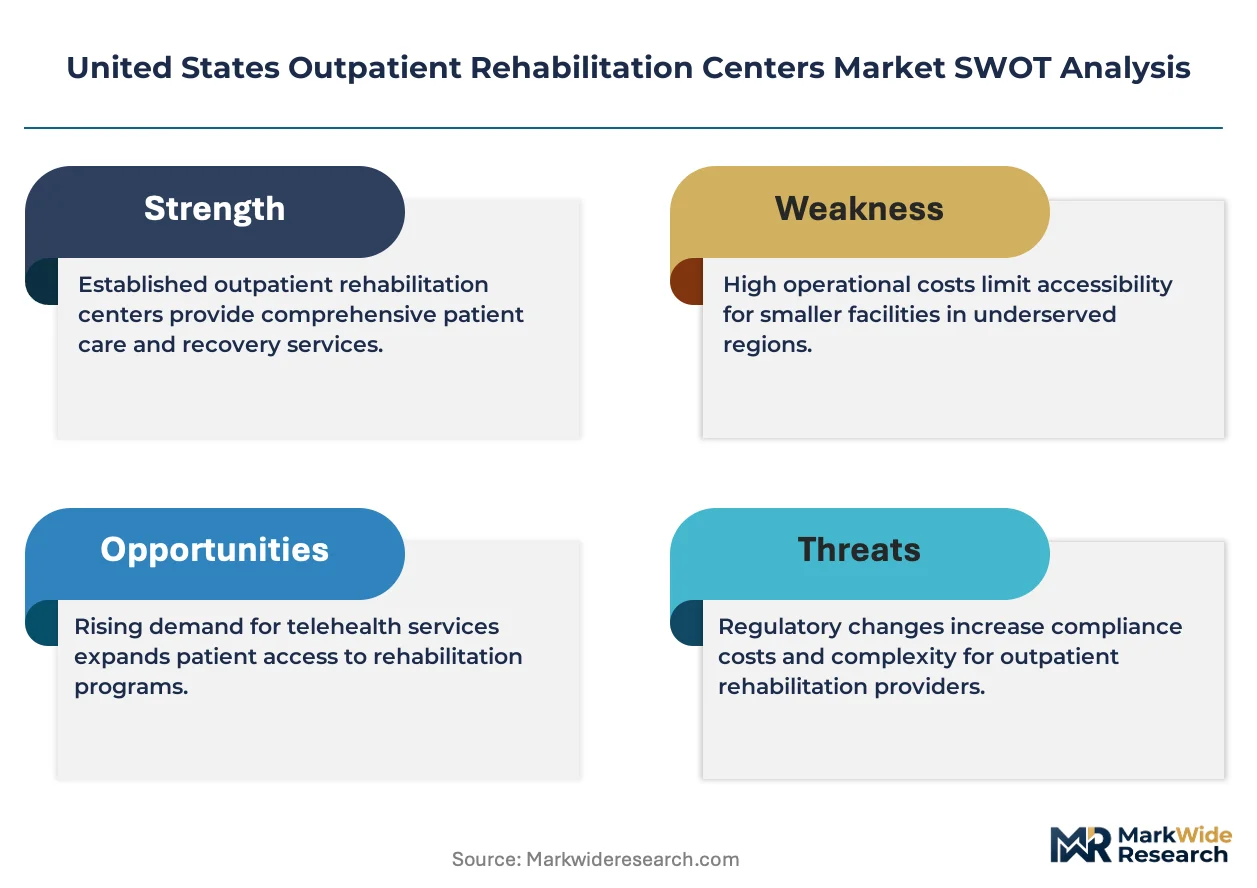
The physical therapist labor pool is collapsing across the Sun Belt, constraining expansion timelines for major chains. Select Medical Corporation leverages its hospital-affiliated outpatient network to secure steady referral flows in constrained labor markets. Encompass Health Corp. sustains geographic dominance through its integrated inpatient-to-outpatient care continuum. ATI Physical Therapy competes on employer-direct contracting, bypassing traditional payer channels in tight labor regions.
Outpatient rehabilitation centers deliver non-residential therapeutic services including joint mobilization protocols, neuromuscular re-education, and functional capacity evaluation, typically administered in 45-90 minute sessions across 6-12 week treatment courses. Physical therapy leads service type revenue due to high post-operative orthopedic volume, while telehealth services represent the fastest-expanding delivery mode as remote monitoring platforms gain clinical acceptance. Geriatric rehabilitation commands premium reimbursement rates reflecting complex comorbidity management, whereas pediatric rehabilitation occupies a narrower but defensible margin pool.
CMS value-based payment models and state-level direct access laws shape referral patterns and reimbursement structures across the market. OSHA return-to-work standards and state physical therapy licensure boards regulate scope of practice and clinic staffing ratios. Stakeholders must monitor Medicare's expanding use of prior authorization for outpatient therapy services as a determinant of volume accessibility and revenue predictability.
Market Dynamics
Medicare's accelerating shift toward value-based reimbursement is restructuring outpatient rehabilitation economics, compressing fee-for-service margins while rewarding episode-based outcomes and care coordination across the United States.
Growth Catalysts
- Direct Access Laws:State-level legislation in Texas and Arizona permits patients to self-refer to physical therapy without physician gatekeeping, expanding addressable patient volume.
- Telehealth Infrastructure:Remote therapeutic monitoring platforms now enable CMS-reimbursed virtual visits, extending clinic reach into rural counties lacking brick-and-mortar presence.
- Post-Surgical Orthopedic Volume:Rising joint replacement procedures among Medicare beneficiaries in Florida generate predictable rehabilitation demand with established clinical protocols.
Market Restraints
- Prior Authorization Expansion:CMS pilot programs imposing pre-approval requirements for outpatient therapy services create administrative friction and revenue unpredictability.
- Physical Therapist Labor Scarcity:Constrained graduation pipeline across Arizona, Texas, and Florida Sun Belt markets limits clinic expansion capacity regardless of capital availability.
- Alternative Pain Management:FDA-cleared non-opioid neuromodulation devices and interventional pain procedures divert some chronic pain patients from traditional rehabilitation.
Strategic Opportunities
- Employer Direct Contracting:Self-insured corporations in Texas and Florida seek occupational health partnerships bypassing traditional payer networks for musculoskeletal injury management.
- Home-Based Modality Convergence:Integration of wearable motion sensors with synchronous telehealth platforms enables CMS-compliant remote therapeutic monitoring expansion.
- Capitated Medicare Advantage:Risk-bearing health plans in Arizona seek exclusive rehabilitation networks, creating preferred provider positioning for integrated delivery systems.
Industry Challenges
- Documentation Burden Intensity:CMS functional limitation reporting requirements and G-code modifiers impose substantial administrative overhead on clinical staff.
- Interoperability Friction:Electronic health record integration between independent outpatient clinics and referring hospital systems remains technically fragmented.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Outpatient Rehabilitation Centers Market |
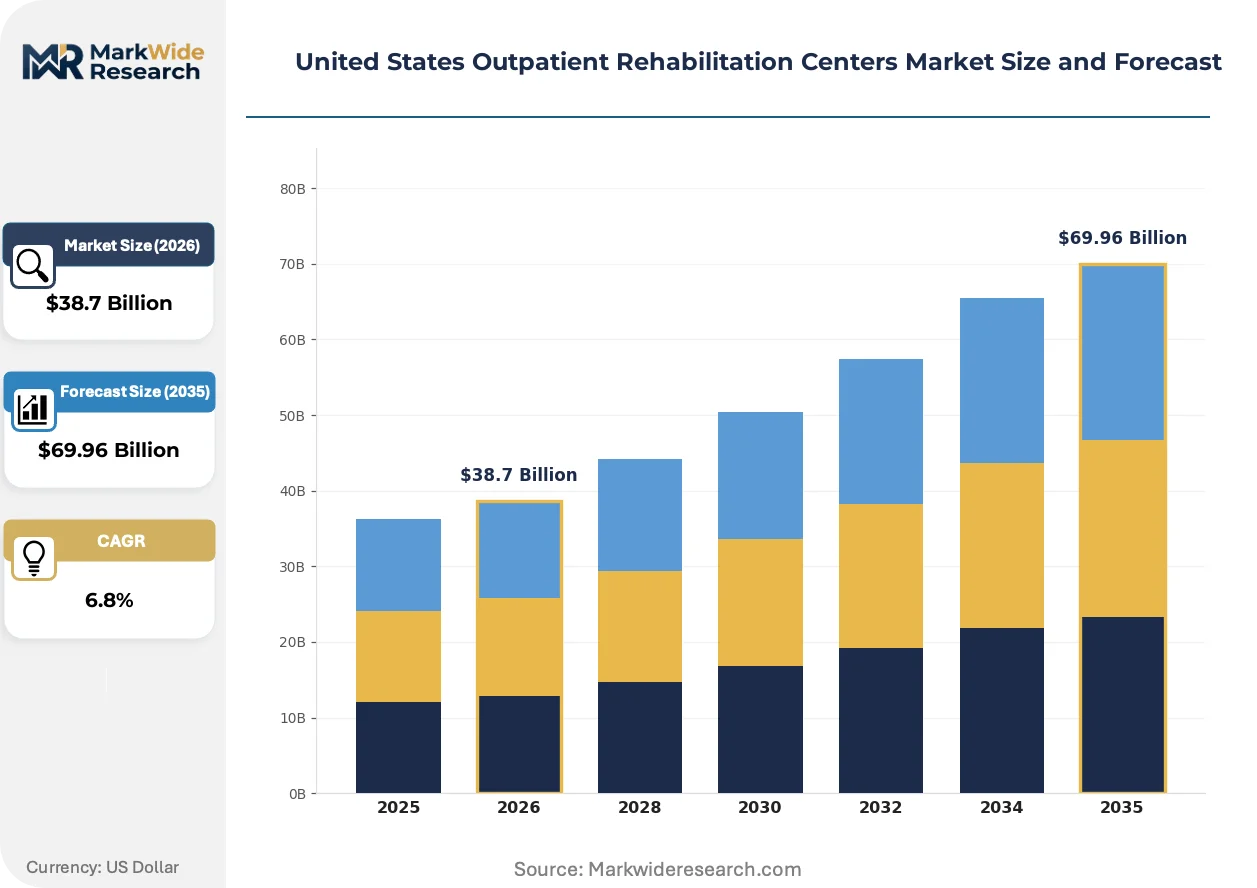
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Physical Therapy, Occupational Therapy, Speech Therapy, Rehabilitation Counseling End User: Individuals, Insurance Companies, Employers, Healthcare Providers Delivery Mode: In-Person Sessions, Telehealth Services, Home Health Care, Group Therapy Treatment Focus: Orthopedic Rehabilitation, Neurological Rehabilitation, Pediatric Rehabilitation, Geriatric Rehabilitation |
| Companies Covered | Select Medical Corporation, Encompass Health Corp., U.S. Physical Therapy Inc., ATI Physical Therapy, Athletico, Kindred Rehabilitation, Baylor Scott & White Institute for Rehabilitation, Lovelace Health System, UAB Health System, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Outpatient Rehabilitation Centers Market Evolving Landscape
Digital health infrastructure and reimbursement redesign are converging to transform how therapeutic services are delivered, measured, and compensated across the United States outpatient rehabilitation landscape.
Wearable motion capture systems employing inertial measurement units are miniaturizing from laboratory-grade equipment to consumer-accessible form factors. Post-operative orthopedic patients in Florida Medicare Advantage plans are adopting these devices for remote range-of-motion tracking. This capability is miniaturizing the traditional clinic visit into continuous home-based monitoring, compressing the required in-person touchpoints while maintaining CMS compliance.
OSHA's evolving return-to-work standards and state workers' compensation fee schedules are reshaping employer-funded rehabilitation purchasing. Industrial rehabilitation providers must now demonstrate functional capacity evaluation metrics aligned with specific job demands rather than impairment ratings alone. Texas and Florida manufacturing employers are driving this specification, demanding outcome documentation that directly correlates therapy completion with work readiness.
Consolidated health systems are unbundling rehabilitation from bundled payment episodes, creating standalone outpatient network decisions. Arizona-based integrated delivery networks now separately contract orthopedic rehabilitation outside their inpatient bundles, treating these services as discretionary cost centers. This pattern concentrates volume toward specialized outpatient chains with demonstrated outcome metrics rather than hospital-affiliated departments.
United States Outpatient Rehabilitation Centers Market Segmentation
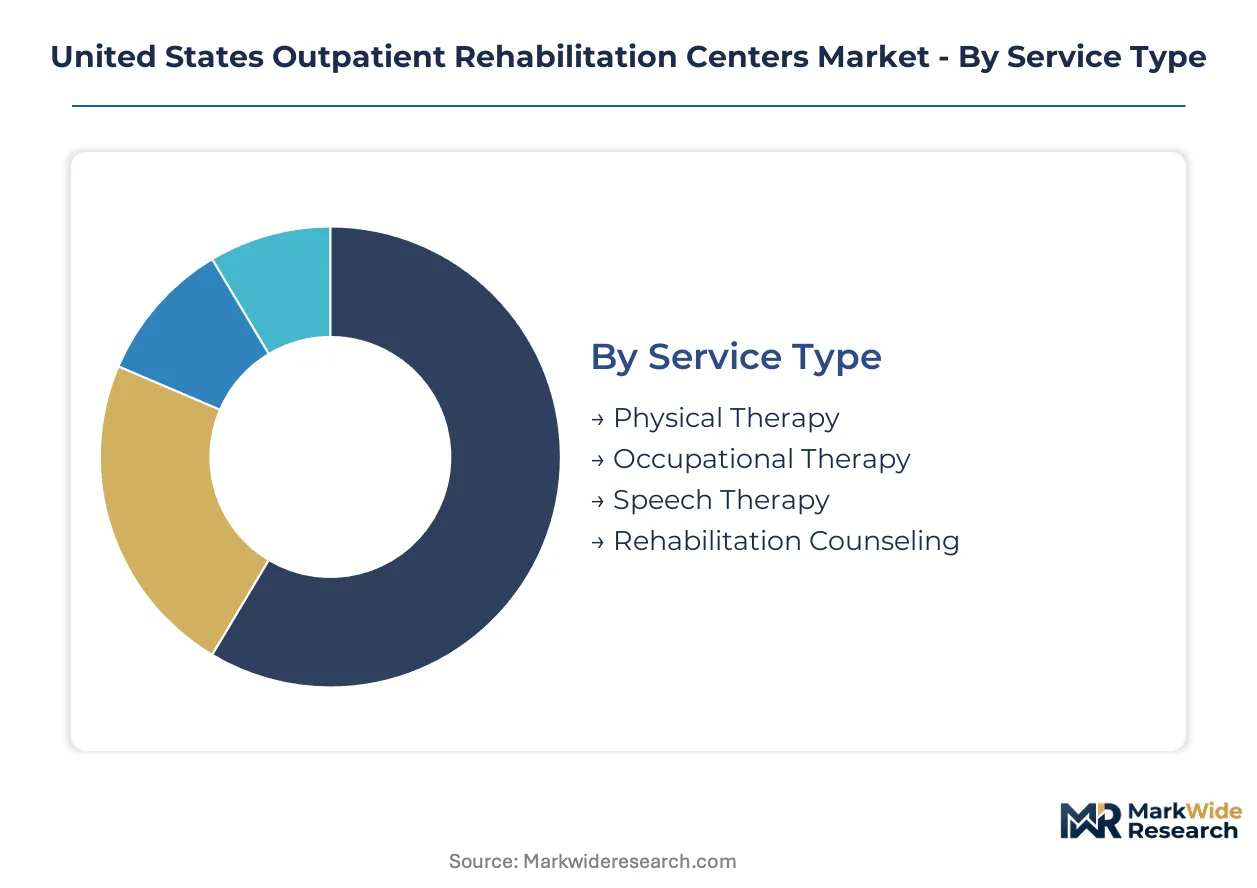
Segmentation in outpatient rehabilitation reveals how distinct patient pathways, payer relationships, and care modalities create discrete margin pools. Understanding these divisions exposes where capital allocation and operational focus generate superior returns.
Service Type:
Margin pools concentrate in high-volume, protocol-driven services where payer reimbursement rates align with treatment standardization.
- Physical Therapy:Joint mobilization protocols and neuromuscular re-education administered in 45-90 minute sessions across 6-12 week courses. Post-surgical orthopedic volume in Florida Medicare Advantage plans generates predictable revenue streams with established clinical pathways and CMS-compliant documentation frameworks.
- Occupational Therapy:Functional capacity evaluation and adaptive equipment training focused on activities of daily living restoration. Texas manufacturing employers purchasing direct-contract occupational health services demand outcome metrics correlating therapy completion with specific job demand readiness under evolving OSHA standards.
- Speech Therapy:Cognitive-linguistic rehabilitation and swallowing disorder management, typically following stroke or traumatic brain injury.
- Rehabilitation Counseling:Psychosocial adjustment and vocational guidance services, often bundled with other modalities in workers' compensation cases.
Physical Therapy holds installed capacity. Occupational Therapy is rotating up the share rankings.
End User:
Customer concentration patterns reflect how risk-bearing entities seek to control musculoskeletal spend through direct relationships or network exclusivity.
- Individuals:Out-of-pocket and high-deductible plan patients self-referring under state direct access laws. Arizona and Texas self-pay volumes expand as patients bypass physician gatekeeping, though price sensitivity constrains session completion rates.
- Insurance Companies:Traditional commercial payers and Medicare Advantage plans negotiating episode-based contracts. Florida Medicare Advantage risk-bearing entities seek exclusive rehabilitation networks, creating preferred provider positioning for integrated delivery systems with demonstrated outcome metrics.
- Employers:Self-insured corporations and workers' compensation carriers. Texas and Florida manufacturing employers drive industrial rehabilitation purchasing with functional capacity evaluation specifications aligned to job demands.
- Healthcare Providers:Hospital systems and physician groups referring into affiliated outpatient networks. Select Medical Corporation leverages hospital-affiliated positioning to secure steady referral flows in labor-constrained Sun Belt markets.
Insurance Companies anchor volume commitment. Employers are expanding fastest as direct contracting bypasses traditional payer channels.
Delivery Mode:
Technology-enabled modalities are compressing the traditional clinic visit while maintaining CMS compliance through remote monitoring infrastructure.
- In-Person Sessions:Brick-and-mortar clinic visits with hands-on manual therapy and supervised exercise. Labor scarcity across Arizona, Texas, and Florida constrains expansion capacity regardless of capital availability.
- Telehealth Services:Synchronous virtual visits combined with remote therapeutic monitoring platforms. CMS-reimbursed virtual visits extend clinic reach into rural counties lacking physical presence, representing the steepest expansion trajectory in delivery mode evolution.
- Home Health Care:Therapist-delivered services in patient residences, typically for post-acute transitions.
- Group Therapy:Concurrent treatment of multiple patients with similar conditions, common in cardiac and pulmonary rehabilitation.
In-Person Sessions retain the dominant share. Telehealth Services are climbing the fastest as wearable motion sensors enable continuous home-based monitoring.
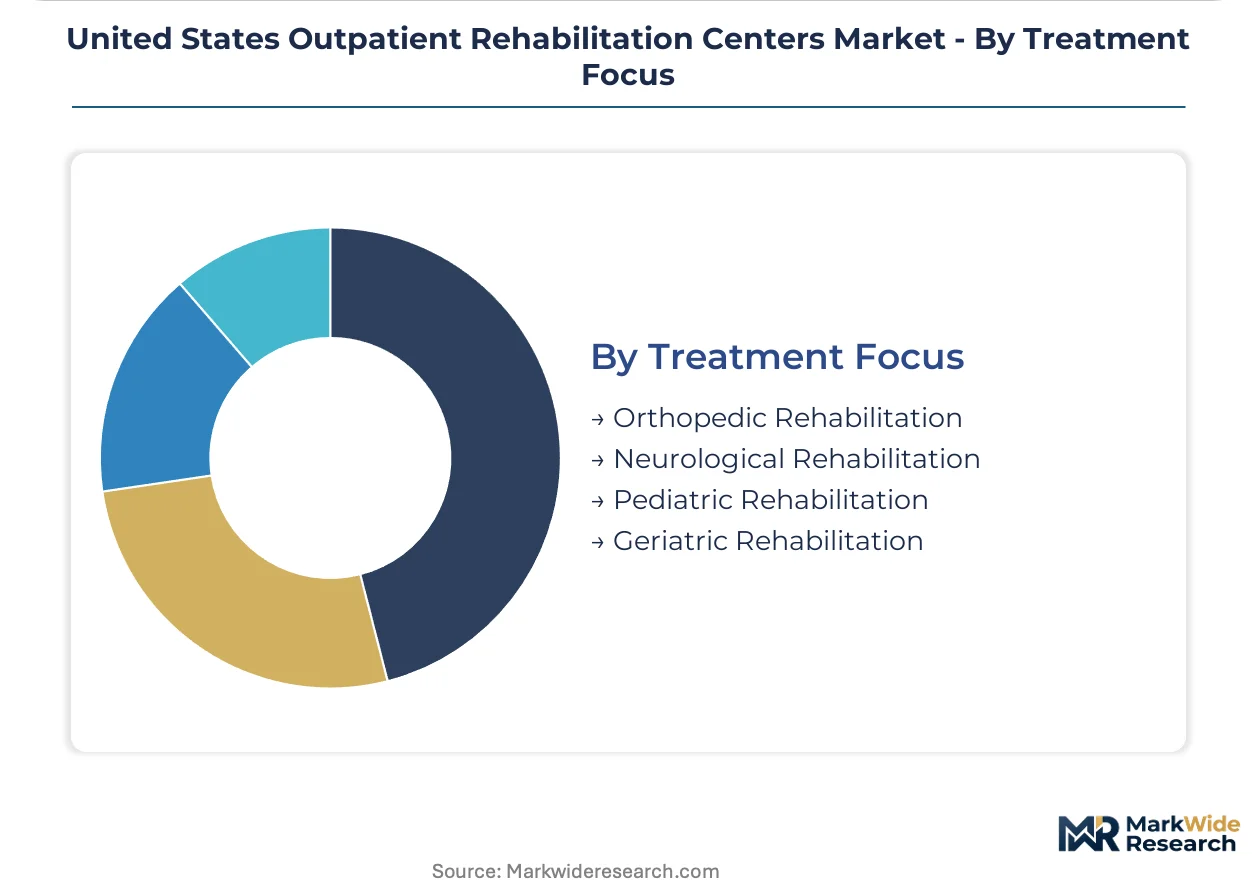
Treatment Focus:
Clinical specialization creates reimbursement tiering, with complex comorbidity management commanding premium rates over standardized protocols.
- Orthopedic Rehabilitation:Post-operative joint replacement and sports injury recovery with established clinical protocols. Rising procedure volumes among Medicare beneficiaries in Florida generate predictable demand with defined episode lengths.
- Geriatric Rehabilitation:Multi-morbidity management and fall prevention for aging populations. Complex comorbidity protocols command premium reimbursement rates reflecting higher clinical intensity and documentation requirements.
- Neurological Rehabilitation:Stroke, Parkinson's, and multiple sclerosis functional recovery programs.
- Pediatric Rehabilitation:Developmental delay and congenital condition intervention, occupying a narrower but defensible margin pool with specialized therapist certification requirements.
Orthopedic Rehabilitation maintains the largest patient flow. Geriatric Rehabilitation is gaining share fastest as retiree populations concentrate in Sun Belt states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across U.S. sub-regions, with Sun Belt states driving volume through retiree concentration while industrial corridors in Texas and the Midwest prioritize occupational rehabilitation over post-surgical protocols.
Florida
Medicare Advantage enrollment density and joint replacement procedure volume create sustained demand for orthopedic rehabilitation. CMS prior authorization pilots for outpatient therapy services impose administrative friction on Miami-Dade and Tampa Bay clinic networks. Orlando and Jacksonville health systems are unbundling rehabilitation from orthopedic bundled payments, steering volume toward specialized outpatient chains.
Texas
Direct access laws permit self-referral without physician gatekeeping, expanding addressable patient volume in Dallas-Fort Worth and Houston metros. OSHA return-to-work standards and workers' compensation fee schedules reshape employer-funded rehabilitation purchasing. Manufacturing employers in the Texas Triangle demand functional capacity evaluation metrics aligned to specific job demands.
Arizona
Retiree migration and Medicare Advantage risk-bearing entity concentration generate premium reimbursement opportunities for geriatric rehabilitation. State physical therapy licensure boards regulate clinic staffing ratios in Phoenix and Tucson markets. Integrated delivery networks are separately contracting orthopedic rehabilitation outside inpatient bundles, treating these services as discretionary cost centers.
California
Telehealth infrastructure investment and remote therapeutic monitoring platform adoption extend clinic reach into rural Central Valley counties. The state's Medicaid program and commercial payer mix create reimbursement complexity for Los Angeles and San Francisco Bay Area providers. Sacramento-area health systems are piloting wearable motion sensor integration for post-operative orthopedic monitoring.
North Carolina
Research Triangle Park employer concentration drives direct contracting demand for occupational health and musculoskeletal injury management. State-level physical therapy regulations and commercial payer prior authorization requirements affect Charlotte and Raleigh clinic operations. Hospital-affiliated outpatient networks leverage integrated electronic health record systems to secure referral flows from Duke and UNC Health systems.
United States Outpatient Rehabilitation Centers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hospital-affiliated networks and independent outpatient chains occupying distinct competitive positions. The upper tier commands referral flow security through health system integration, while mid-scale specialists compete on employer-direct relationships and geographic density. Three archetypes dominate: integrated delivery network affiliates, employer-contracting specialists, and telehealth-enabled platform operators. Consolidation through health system partnerships and direct-to-employer contract acquisition represent the dominant competitive vectors.
Within the integrated network tier, Select Medical Corporation and Encompass Health Corp. exemplify hospital-affiliated positioning that secures steady referral flows in labor-constrained Sun Belt markets. ATI Physical Therapy occupies a position within the employer-direct contracting archetype, competing outside traditional payer channels in tight labor regions. These three entities represent contrasting strategic postures: health system integration versus payer bypass versus geographic dominance through care continuum control.
| Leading Market Players |
|---|
| Select Medical Corporation |
| Encompass Health Corp. |
| U.S. Physical Therapy Inc. |
| ATI Physical Therapy |
| Athletico |
| Kindred Rehabilitation |
| Baylor Scott & White Institute for Rehabilitation |
| Lovelace Health System |
| UAB Health System |
| Others |
Value Network & Pricing Analysis
OSHA return-to-work standards and state physical therapy licensure boards simultaneously gate supplier qualification and enable price differentiation across employer-contracted and Medicare-reimbursed service tiers. This dual regulatory framing compresses margins on standardized protocols while rewarding outcome-documented specialty services with premium positioning.
Pricing Analysis
Contract-based long-term offtake agreements between self-insured employers and outpatient chains dominate Texas and Florida industrial corridors, displacing spot-market session rates. Price differentiation hinges on functional capacity evaluation certification depth and geographic proximity to manufacturing clusters. Cost compression in Medicare-reimbursed physical therapy is intensifying because CMS prior authorization pilots expand administrative overhead without corresponding rate adjustments. Self-pay patients under state direct access laws exhibit highest price sensitivity, while Medicare Advantage risk-bearing entities accept premium rates for documented episode outcomes.
Supply Chain Analysis
Inventory lead times for wearable motion sensors and remote therapeutic monitoring platforms now determine clinic expansion feasibility across rural Arizona and Texas counties. Hardware supply concentrates in China, South Korea, and Taiwan for inertial measurement unit components. Therapist labor pipeline constraints in Sun Belt states rest on university program accreditation cycles and state licensure board processing timelines. Single-source vulnerability characterizes specialized rehabilitation equipment sourcing. Distribution runs through hospital-affiliated procurement networks and direct manufacturer relationships for independent clinic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed physical therapist scarcity across Arizona, Texas, and Florida constrains every growth strategy regardless of capital deployment, making workforce pipeline access the decisive competitive moat.
For Market Incumbents: Consolidate referral flow security through exclusive hospital system partnerships in Miami-Dade and Dallas-Fort Worth corridors where orthopedic bundled payment unbundling steers volume. Acquire telehealth infrastructure capabilities to extend reach into therapist-scarce rural counties without brick-and-mortar investment. Prioritize backward integration into therapist training pipeline partnerships with state university programs. For New Entrants and Emerging Players: Accelerated Medicare Advantage network certification creates viable entry path for specialized geriatric rehabilitation platforms targeting Arizona retiree concentration zones. Employer-direct occupational health contracting in Texas manufacturing corridors offers lowest competitive density versus saturated Medicare fee-for-service markets. Pursue white-label remote therapeutic monitoring partnerships with established clinic brands lacking digital infrastructure. For Investors and Strategic Acquirers: CMS value-based payment model expansion reshapes the acquisition landscape toward platforms with demonstrated episode outcome metrics and risk-bearing payer relationships. Five-to-ten year viability favors integrated delivery networks with captive referral flows over standalone clinic rollups vulnerable to labor cost inflation. Monitor Medicare prior authorization pilot geographic expansion as volume accessibility inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures steady referral flows from orthopedic bundled payment unbundling in Florida health systems. |
| Remote Therapeutic Monitoring Platform Launch | Enables CMS-reimbursed virtual visits extending clinic reach into rural Texas and Arizona counties. |
| Employer Direct Contracting | Bypasses traditional payer channels for musculoskeletal injury management with Texas manufacturing employers. |
| Therapist Pipeline Partnership | Addresses Sun Belt labor scarcity through university program alignment and accelerated licensure pathways. |
| Medicare Advantage Network Certification | Positions for capitated risk-bearing contracts with Arizona geriatric rehabilitation premium reimbursement tiers. |
Research Methodology
Cross-validation between CMS Medicare claims data and state physical therapy licensure board records anchors the qualitative findings on labor market constraints. Primary interviews with clinic operations directors, hospital referral coordinators, employer benefits managers, and Medicare Advantage contracting officers combined with secondary validation from CMS policy releases, state direct access law compilations, and OSHA regulatory dockets. Bottom-up clinic capacity modeling and top-down payer expenditure analysis triangulate volume estimates.
Sensitivity analysis across therapist graduation pipeline scenarios, Medicare reimbursement rate assumptions, and telehealth adoption curves shapes the analytical framework. Segmentation dimensions modeled include service type, delivery mode, end user category, and treatment focus complexity tier across the projection horizon. CAGRs derive from regression-adjusted historical utilization patterns and demographic projection inputs. Forecast inputs incorporate joint replacement procedure volume trajectories and Medicare Advantage enrollment shifts.
Underlying assumptions cover stable state licensure board processing timelines and continued CMS remote therapeutic monitoring reimbursement, with deviation risk concentrated in prior authorization program expansion and alternative pain management technology substitution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Veterinary Rehabilitation Services Market
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
Telerehabilitation Systems Market
Rehabilitation Services
Occupational and Physical Therapy Services Market
Rehabilitation Services
US Physical Therapy Services Market
Rehabilitation Services
Asia-Pacific Repair and Rehabilitation Market
Rehabilitation Services
Home Rehabilitation Products Market
Rehabilitation Services
Brachial Plexus Injury Market
Rehabilitation Services
Outpatient Rehabilitation Services Market
Rehabilitation Services
Exoskeleton and Rehabilitation Robot Safety and Performance Test Equipment Market
Rehabilitation Services
Neurorehabilitation Gaming Systems Market
Rehabilitation Services
Wearable Neurorehabilitation Devices Market
Rehabilitation Services
Global Women Health Rehabilitation Products Market
Rehabilitation Services
Speech Therapy Services Market
Rehabilitation Services
Global Gait Trainer Market
Rehabilitation Services
Speech Pathology Services Market