
 Global Computerized Physician Order Entry Market | 2026-2036
Global Computerized Physician Order Entry Market Size, Share, and Industry Trends Forecast 2026-2036
Global Computerized Physician Order Entry Market Intelligence
The transition from siloed hospital deployments to integrated network-wide systems covering ambulatory services and long-term care facilities is hardening the requirement for interoperable platforms. Epic Systems Corporation dominates the large hospital system segment with its comprehensive electronic health record suite. Cerner Corporation competes directly by offering modular CPOE solutions tailored for diverse healthcare settings. Siemens Healthineers differentiates through its integration of diagnostic imaging data into the physician ordering workflow.
Computerized Physician Order Entry (CPOE) is a clinical software application allowing practitioners to enter patient orders for medications and procedures electronically. These platforms integrate clinical decision support tools at the point of care, flagging potential drug interactions, allergies, and dosing errors. Integrated modules within comprehensive EHRs constitute the largest product segment, displacing older standalone systems. Cloud-based solutions are seeing rapid uptake in hospitals and clinics due to lower upfront costs and enhanced scalability.
Regulatory frameworks governing patient data privacy, such as HIPAA in the United States and GDPR in Europe, set strict standards for CPOE system security and data handling. National health authorities, including the FDA and Health Canada, also influence system design through mandates for certified electronic health record technology. Vendor selection will increasingly hinge on a platform’s ability to demonstrate seamless interoperability across disparate care settings and compliance with evolving data security protocols.
Market Dynamics
The structural shift from siloed, on-premise software to integrated, cloud-based electronic health record platforms is the central force governing the CPOE market. This transition is driven by healthcare network consolidation and regulatory pressure for system-wide data interoperability.
Growth Catalysts
- Regulatory Mandates:Data security and privacy laws, including HIPAA in the United States and GDPR in Europe, compel healthcare providers to adopt secure, auditable electronic ordering systems, moving them away from paper-based processes.
- Value-Based Care Models:The transition to reimbursement models that reward positive patient outcomes requires the granular data capture and clinical decision support inherent in CPOE systems to track performance and reduce medical errors.
- Cloud Technology Adoption:The availability of scalable, cloud-hosted CPOE solutions lowers the barrier to entry for smaller hospitals and ambulatory clinics by reducing upfront capital expenditure and IT infrastructure requirements.
Market Restraints
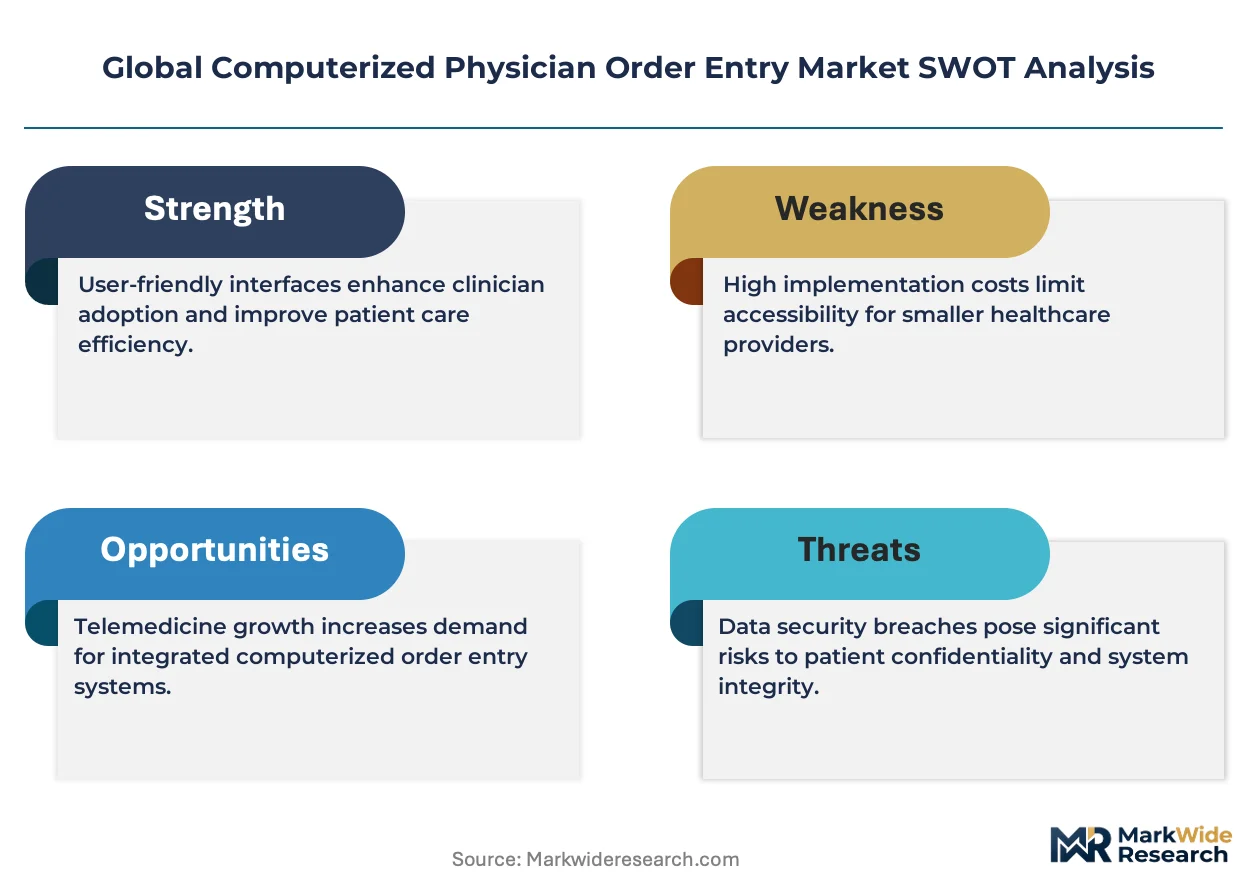
- High Implementation Costs:The significant capital investment and ongoing maintenance fees associated with comprehensive EHR systems that include CPOE modules remain a major barrier for smaller, independent, or under-funded healthcare facilities.
- Interoperability Deficiencies:A lack of universal data exchange standards between competing vendor platforms creates persistent data silos, hindering the seamless transfer of patient information across different care settings within a single network.
- Physician Workflow Disruption:Resistance from clinicians due to steep learning curves, cumbersome user interfaces, and "alert fatigue" can slow adoption rates and limit the effective use of CPOE systems within hospitals.
Strategic Opportunities
- Expansion in Emerging Economies:Targeting healthcare systems in Latin America and Southeast Asia that are undergoing digital transformation presents a significant opportunity as they invest in foundational health IT infrastructure, including CPOE platforms.
- AI and Predictive Analytics:Integrating machine learning algorithms into CPOE workflows to provide real-time, predictive decision support for diagnostics, treatment protocols, and adverse event risk can create significant product differentiation.
- Specialized Care Modules:Developing CPOE solutions tailored for underserved segments such as long-term care, behavioral health, and home healthcare addresses a growing need for specialized ordering and documentation workflows outside traditional hospital environments.
Industry Challenges
- Legacy System Integration:Integrating modern CPOE platforms with aging, disparate hospital information systems, laboratory systems, and pharmacy management software presents a significant technical and operational challenge for IT departments.
- Clinical Informatics Talent Gap:A shortage of IT professionals and clinicians with specialized training in health informatics hinders the effective implementation, customization, and optimization of complex CPOE systems.
- Data Standardization:The lack of a universally accepted terminology and data format for medical orders complicates the development of truly interoperable systems and creates friction in data sharing between providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Computerized Physician Order Entry Market |
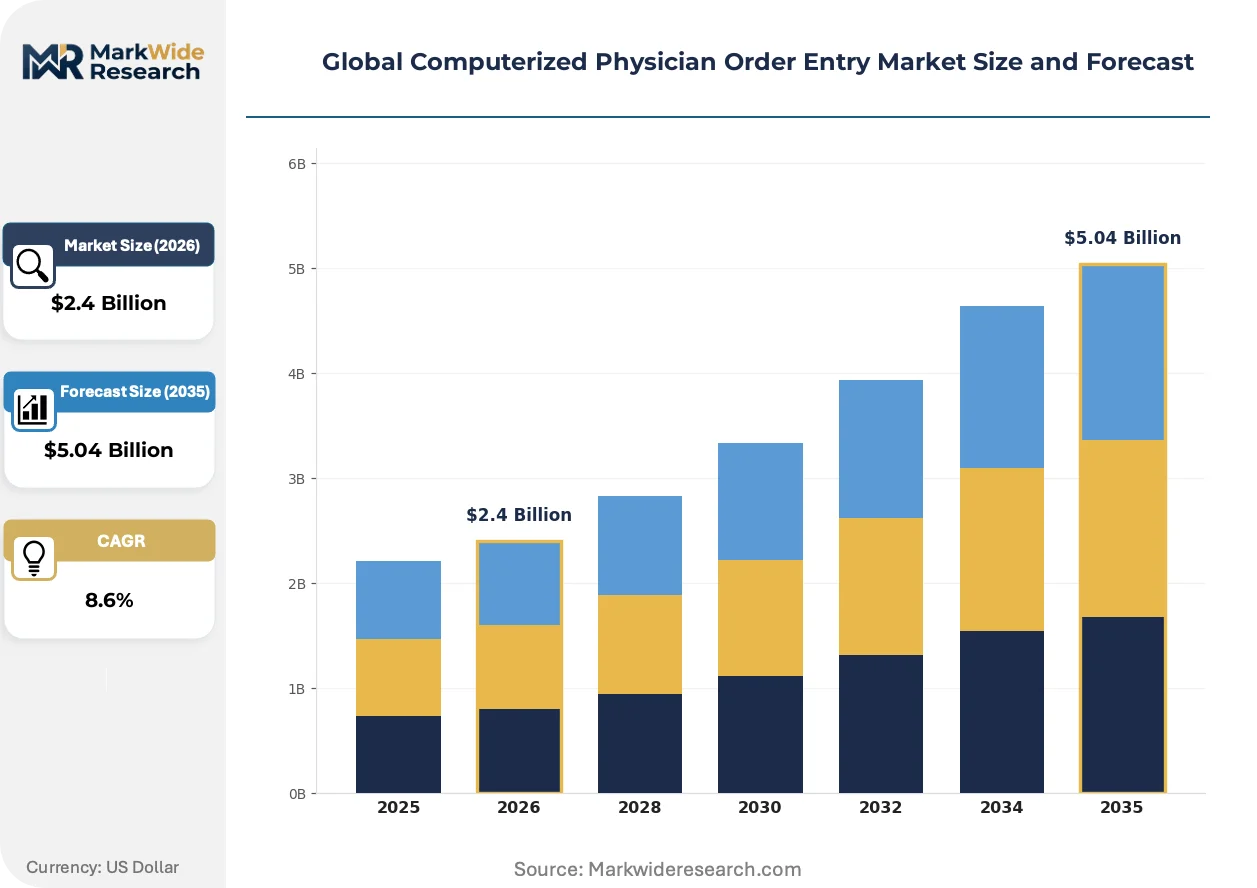
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.04 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated Modules, Cloud-Based Solutions, On-Premise Software, Hybrid Systems Application: Inpatient Management, Outpatient Management, Emergency Care, Specialty Care, Ambulatory Services Healthcare Setting: Hospitals, Clinics, Diagnostic Centers, Long-Term Care Facilities, Ambulatory Surgical Centers Deployment Mode: Cloud Deployment, On-Premises Deployment, Web-Based Access, Mobile Access, API Integration |
| Companies Covered | McKesson Corporation, Philips Healthcare, Cerner Corporation, MEDITECH, Siemens Healthineers, Epic Systems Corporation, GE Healthcare, NextGen Healthcare, Allscripts Healthcare Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Computerized Physician Order Entry Market Strategic Shifts & Innovations
The market is being reshaped by the fusion of mobility, artificial intelligence, and cloud computing. This convergence is transforming CPOE platforms from static data entry tools into dynamic, intelligent clinical assistants that are accessible at any point of care.
Mobile-first CPOE applications enable practitioners to place, review, and sign orders using tablets and smartphones. Ambulatory care providers and hospital-based physicians are adopting these solutions to enhance workflow efficiency and decision-making during patient rounds. This focus on mobile accessibility is overtaking the stationary, desktop-based terminal as the primary interface for physician interaction with the system.
Regulatory frameworks for certified health IT, such as those defined by the Office of the National Coordinator for Health Information Technology (ONC) in the U.S., are forcing vendors to prioritize interoperability. These rules mandate standardized APIs for data exchange, ensuring patient information can flow between different systems. The integrated EHR module segment is most affected, as compliance often requires deep platform-level capabilities that standalone CPOE products cannot easily provide.
A clear behavioral shift toward subscription-based Software-as-a-Service (SaaS) models is evident across the provider landscape. This model displaces the traditional perpetual license purchase, which required substantial upfront capital investment for on-premise hardware and software. The trend is most prominent among small-to-medium hospitals and large physician groups in North America and Europe seeking greater financial flexibility and scalability.
Global Computerized Physician Order Entry Market Segmentation
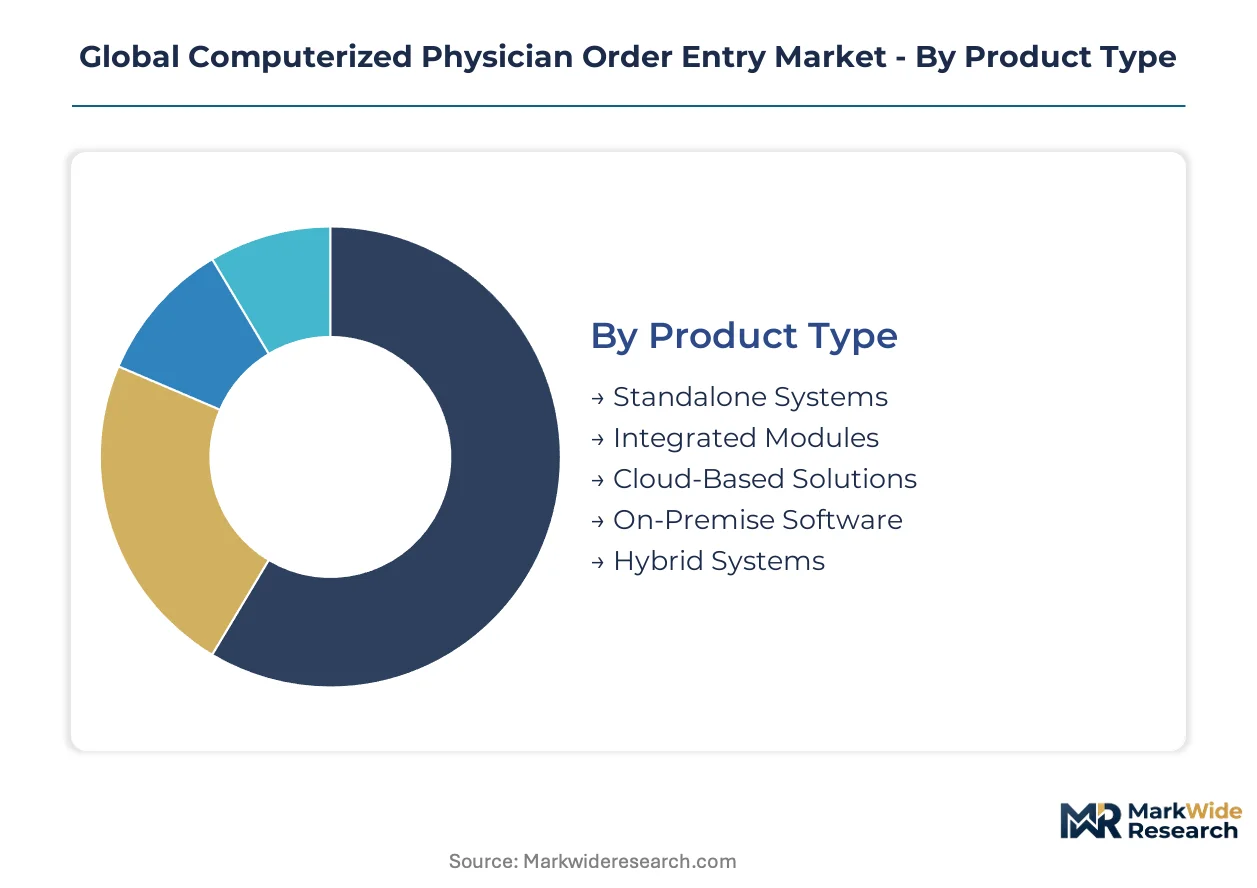
The Global Computerized Physician Order Entry market segmentation reflects the diverse technological approaches and operational demands within healthcare. Analyzing these distinct segments reveals where investment capitalizes on efficiency gains and where innovation targets specific clinical workflows. Understanding these divisions is crucial for strategic market positioning and product development.
Product Type:
Capital intensity varies significantly across CPOE product types, with integrated modules demanding substantial initial investment in comprehensive EHR platforms. Standalone systems offer a lower entry cost but often necessitate complex integration with existing hospital information systems. Hybrid systems balance on-premise control with cloud scalability, requiring a mixed infrastructure spend.
- Integrated Modules:These CPOE functionalities are embedded within larger, comprehensive Electronic Health Record (EHR) suites, providing a unified platform for patient data and clinical workflows. Demand concentrates in large hospital networks in the United States, driven by regulatory mandates for certified EHR technology.
- Cloud-Based Solutions:These platforms are hosted on remote servers and accessed via the internet, offering lower upfront costs and enhanced scalability for healthcare providers. Rapid uptake is occurring in small-to-medium hospitals across Europe due to financial flexibility and reduced IT infrastructure burdens.
- Standalone Systems:These dedicated CPOE applications function independently of broader EHR platforms, focusing solely on order entry and management.
- On-Premise Software: This software is installed and run directly on a healthcare facility's local servers, offering maximum control over data security and customization.
- Hybrid Systems: These solutions combine elements of both on-premise and cloud-based deployments, allowing for flexible data storage and accessibility.
Integrated Modules absorbs the bulk of installed capacity; Cloud-Based Solutions is expanding most quickly.
Application:
CPOE application segments highlight the diverse clinical settings where electronic order entry streamlines patient care and improves safety. Each application area presents unique requirements for workflow customization and decision support tools. The market responds to specific patient populations and care delivery models within these segments.
- Ambulatory Services:This segment encompasses CPOE use in outpatient clinics, physician offices, and urgent care centers, focusing on efficient scheduling and prescription management for non-hospitalized patients. System utility is expanding across North America due to the shift towards value-based care models.
- Inpatient Management:CPOE systems here manage orders for hospitalized patients, including medications, lab tests, and procedures, integrating with hospital information systems. This application remains a foundational segment for large medical centers globally, driven by patient safety initiatives.
- Outpatient Management:This application supports order entry for patients receiving care outside a hospital stay, including follow-up appointments and specialist referrals.
- Emergency Care:CPOE in emergency departments facilitates rapid order entry for diagnostics and treatments, crucial for time-sensitive medical interventions.
- Specialty Care:This segment addresses the unique ordering requirements of specialized medical fields such as oncology, cardiology, or pediatrics.
Ambulatory Services is gaining share fastest; Inpatient Management maintains its foundational market position.
Healthcare Setting:
The healthcare setting segmentation reveals how CPOE adoption varies by organizational structure and patient volume. Each setting demands tailored functionalities, from the comprehensive needs of large hospitals to the streamlined requirements of smaller clinics. Vendor offerings often differentiate based on the scale and complexity of these environments.
- Hospitals:This segment represents the largest deployment of CPOE systems, covering acute care, surgical, and intensive care units within major medical institutions. Large integrated delivery networks in the United States drive significant demand for enterprise-wide CPOE solutions.
- Clinics:CPOE adoption in clinics includes physician practices, specialist offices, and primary care facilities, focusing on patient record management and prescription ordering. Cloud-based CPOE solutions are gaining traction in independent clinics across Europe due to cost-effectiveness.
- Diagnostic Centers:These facilities utilize CPOE for ordering and managing laboratory tests and imaging procedures, integrating with LIS and RIS systems.
- Long-Term Care Facilities:CPOE systems in these settings manage medication and treatment orders for residents in nursing homes and assisted living facilities.
- Ambulatory Surgical Centers:CPOE here supports pre-operative, intra-operative, and post-operative orders for same-day surgical procedures.
Hospitals remain the primary revenue source; Clinics exhibit a steep expansion trajectory.
Deployment Mode:
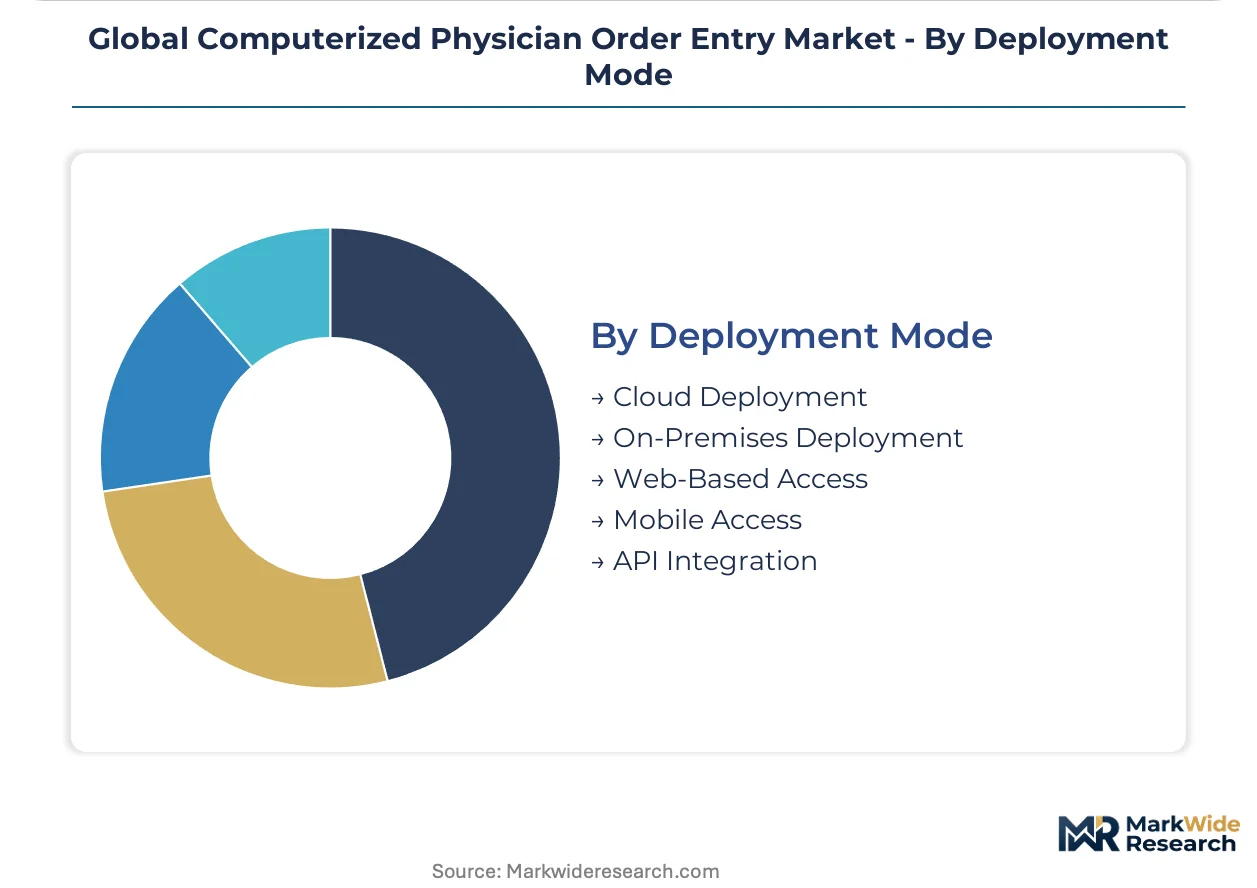
Deployment mode segmentation illustrates the technical infrastructure choices for CPOE systems, impacting accessibility, cost, and scalability. Cloud deployment offers flexibility, while on-premises provides greater control. Mobile access and API integration represent evolving approaches to system interaction and data exchange.
- Cloud Deployment:CPOE systems delivered via cloud infrastructure offer remote accessibility, automatic updates, and reduced hardware maintenance for healthcare providers. This mode is increasingly preferred by small and medium-sized enterprises in North America seeking operational efficiency and lower capital expenditure.
- Mobile Access:This mode enables CPOE functionality via smartphones and tablets, allowing practitioners to enter and review orders from any location within a facility or remotely. Mobile-first applications are transforming workflow efficiency for hospital-based physicians globally during patient rounds.
- On-Premises Deployment:This involves installing CPOE software directly on a healthcare organization's own servers, providing full control over data and customization.
- Web-Based Access:CPOE systems accessed through a web browser, offering platform independence and ease of deployment across various devices.
- API Integration:This mode facilitates the seamless exchange of CPOE data with other healthcare IT systems through Application Programming Interfaces.
On-Premises Deployment holds significant legacy market share; Cloud Deployment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption of Computerized Physician Order Entry (CPOE) platforms concentrates in mature healthcare markets, while production capabilities are distributed among established software developers globally. Major demand originates from countries with advanced digital health infrastructure and stringent regulatory environments. Developing economies are now focusing on foundational health IT infrastructure.
United States
Demand for CPOE systems is driven by large integrated delivery networks and the shift to value-based care models. HIPAA mandates for patient data security and certified EHR technology compel investment. Major health tech hubs like Boston and Silicon Valley accelerate innovation in CPOE platform development.
Germany
The country's robust healthcare system requires advanced CPOE solutions for efficient inpatient management. GDPR regulations ensure strict patient data privacy and security in CPOE deployments. Berlin and Munich are centers for digital health startups developing specialized CPOE modules.
India
Digital transformation initiatives in healthcare are boosting demand for scalable CPOE platforms. The Ayushman Bharat Digital Mission encourages electronic health record adoption and interoperability. Bengaluru and Hyderabad emerge as key technology centers for CPOE software development and implementation.
Japan
An aging population and focus on patient safety drive the need for sophisticated CPOE systems in hospitals. The Ministry of Health, Labour and Welfare promotes digital health initiatives to improve care quality. Tokyo's medical technology clusters are integrating AI into CPOE for enhanced clinical decision support.
Brazil
Investment in public and private hospitals is expanding the adoption of CPOE for better clinical workflows. The country's national health agency, ANVISA, influences medical device and software regulations. São Paulo's healthcare IT sector is seeing increased deployment of cloud-based CPOE solutions.
Global Computerized Physician Order Entry Market Key Industry Players
Top-tier vendors anchor the comprehensive Electronic Health Record (EHR) suite market, while specialized solution providers cater to specific clinical needs and smaller facilities. The market structure reflects a blend of established healthcare IT giants and agile innovators focusing on niche applications. Archetypes include integrated platform providers, modular CPOE specialists, and diagnostic data integrators offering distinct value propositions. Strategic moves involve portfolio diversification into cloud-based offerings and targeted geographic expansion into emerging economies, alongside continuous R&D for AI integration.
Within this competitive environment, Epic Systems Corporation exemplifies the integrated platform archetype, providing extensive EHR solutions for large hospital systems. Cerner Corporation occupies a strong position as a modular CPOE specialist, offering flexible solutions for diverse healthcare settings. Siemens Healthineers represents a unique blend, integrating diagnostic imaging data directly into physician ordering workflows, enhancing clinical decision support capabilities for practitioners.
| Leading Market Players |
|---|
| McKesson Corporation |
| Philips Healthcare |
| Cerner Corporation |
| MEDITECH |
| Siemens Healthineers |
| Epic Systems Corporation |
| GE Healthcare |
| NextGen Healthcare |
| Allscripts Healthcare Solutions |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure pricing models influence CPOE solution costs, flowing through vendor operational expenses to tiered subscription rates for healthcare providers. This dynamic shapes the accessibility and affordability of advanced CPOE platforms for diverse healthcare settings.
Pricing Analysis
Cost-down pressure on CPOE vendors accelerates as cloud-based solutions offer lower upfront capital expenditure for healthcare facilities. The dominant pricing model is subscription-based SaaS, which stratifies across premium, standard, and economy tiers. Price differentiation stems from feature set complexity, such as integrated clinical decision support, and deep integration capabilities with existing EHRs. Smaller hospitals and ambulatory clinics exhibit high price sensitivity, while large integrated delivery networks prioritize comprehensive functionality over marginal cost savings.
Supply Chain Analysis
Decommissioning legacy CPOE systems and managing data migration from retiring platforms constitutes a key reverse-logistics challenge for healthcare IT departments. Geographic supply concentration for CPOE software development centers in the United States, India, and Germany. The software supply chain relies on a steady stream of developer talent, robust cloud computing infrastructure, and adherence to evolving regulatory compliance frameworks. A significant structural risk is the clinical informatics talent gap, hindering effective implementation and optimization. Distribution runs through direct vendor sales to large hospital systems and partnerships with cloud service providers for smaller clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Computerized Physician Order Entry market is undergoing consolidation, driven by the intense regulatory pressure for system-wide data interoperability that marginalizes fragmented, non-compliant solutions.
For Market Incumbents:
Extend enterprise EHR platforms to encompass niche CPOE applications, securing market share against specialized entrants. Acquire smaller, innovative CPOE developers to integrate their unique functionalities and talent pools. This strategy mitigates the threat of fragmented data landscapes by offering comprehensive, unified solutions. Invest in platform interoperability standards to maintain competitive advantage in large hospital networks.
For New Entrants and Emerging Players:
Enter via specialized care modules tailored for underserved segments like long-term care or behavioral health. Target emerging economies in Southeast Asia and Latin America, which require foundational health IT infrastructure. Ambulatory clinics represent a penetrable segment due to their need for cost-effective, scalable solutions. Leverage cloud-based SaaS models to offer lower upfront costs and rapid deployment.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor integrated platform providers in North America, particularly those with strong cloud migration capabilities. CPOE remains a foundational component of digital health, ensuring long-term viability over the next decade. Target acquisition archetypes include interoperability-focused software developers and AI integration specialists. Monitor standardized API adoption rates as a key inflection indicator for market maturation and consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen EHR Integration | Unifies patient data across care settings, enhancing clinical decision support for practitioners. |
| Expand Cloud-Based Offerings | Lowers upfront costs for smaller clinics, accelerating CPOE adoption in Europe. |
| Integrate AI and Predictive Analytics | Provides real-time diagnostic support, reducing medical errors and improving patient outcomes. |
| Develop Specialized Care Modules | Addresses unique ordering needs in long-term care, extending CPOE utility beyond hospitals. |
| Pursue Geographic Expansion | Captures growth in emerging economies like Brazil, investing in foundational health IT. |
Research Approach
Document review covered FDA filings, ONC reports, academic journals, and healthcare IT vendor whitepapers, complemented by interviews with industry stakeholders. Primary research included conversations with clinicians, hospital purchasing committees, IT procurement officers, and CPOE platform engineers. This approach ensured bottom-up data validation and top-down market sizing. Secondary data provided a robust foundation for market segmentation and trend identification.
The model produced comprehensive volume and value projections across the analysis window, integrating historical growth trends and projected adoption rates. Segmentation dimensions modeled included product type, application, healthcare setting, deployment mode, and regional regulatory clusters. Compound Annual Growth Rates were derived from these inputs, reflecting market dynamics. Key forecast inputs included EHR adoption rates and healthcare IT spending.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant regulatory shifts or major cybersecurity threats. Forecasts reflect assumptions regarding healthcare IT investment and vendor innovation. Practitioners should monitor new data privacy legislation and interoperability mandates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Global Medical Scheduling Software Market
Medical Information Systems
Medical Software Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
Medical 3D Software Market
Medical Information Systems
Healthcare Mobile Computers Market
Medical Information Systems
Medical Information Market
Medical Information Systems
Medical Talent Management IT Market
Medical Information Systems
ICD-10 Market
Medical Information Systems
US Healthcare ERP Market
Medical Information Systems
Global Cardiovascular Information System Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
Medical Alert Systems Market
Medical Information Systems
OBGYN EHR Market
Medical Information Systems
Electronic Medical Record Market
Medical Information Systems
Global Allergy EMR Software Market
Medical Information Systems
Global Clinical Documentation Improvement Market