
 Lower Extremity Rehabilitation Robotics Market | 2026-2036
Lower Extremity Rehabilitation Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Lower Extremity Rehabilitation Robotics Market Insights
The EU Medical Device Regulation is expanding compliance requirements for powered rehabilitation systems sold across member states. Ekso Bionics dominates hospital sales channels in North America through direct clinical specialist teams. Hocoma leverages its Lokomat platform to anchor long-term service contracts with European rehabilitation centers. ReWalk Robotics navigates reimbursement complexity by positioning its systems within durable medical equipment frameworks.
Lower extremity rehabilitation robotics encompasses electromechanical systems designed to restore ambulatory function through programmable gait patterns, force-adjustable joint actuation, and real-time kinematic feedback with typical torque precision within two Newton-meters. These devices serve patients recovering from neurological injury, orthopedic surgery, or neurodegenerative conditions by delivering repeatable, quantifiable therapy doses that manual physical therapy cannot replicate. Exoskeletons capture the largest installed base among product categories, though assistive robots for home deployment represent the fastest-growing segment as reimbursement shifts toward outpatient settings. Stroke recovery applications generate the deepest margin pools due to established clinical evidence and payer familiarity, while sports rehabilitation remains comparatively nascent with concentrated demand at elite athletic medicine centers.
The FDA maintains premarket notification requirements for Class II powered rehabilitation devices, while the EMA's Medical Device Regulation mandates clinical performance documentation for CE marking of active therapeutic systems. ISO 13485 quality management certification shapes supplier eligibility for institutional procurement tenders across OECD markets. Stakeholders must monitor evolving CMS national coverage determinations for robotic therapy, as reimbursement clarity will determine whether home-based segments achieve projected penetration rates.
Market Dynamics
The Veterans Health Administration's dedicated procurement budgets for lower-limb robotic therapy platforms are concentrating hospital demand in the United States, while the FDA's breakthrough device designation pathway compresses commercial timelines for powered exoskeleton systems entering stroke rehabilitation protocols.
Growth Catalysts
- CMS National Coverage Determinations:The Centers for Medicare & Medicaid Services is expanding reimbursement clarity for robotic gait training, reducing payer uncertainty that previously stalled institutional adoption.
- Stroke Incidence Demographics:Aging populations in OECD markets are driving hospital-based rehabilitation departments to scale electromechanical therapy capacity for neurological recovery.
- ISO 13485 Certification:Quality management standardization is unlocking institutional procurement tenders across European rehabilitation centers and North American health systems.
Market Restraints
- Actuator Manufacturing Concentration:Precision torque motors and harmonic drive components rely on concentrated Asian supply bases, creating vulnerability for force-adjustable joint production.
- EMA MDR Clinical Documentation:The EU Medical Device Regulation's expanded performance documentation requirements for CE marking of active therapeutic systems extend compliance timelines for European market entry.
- Manual Physical Therapy Substitution:Conventional gait training remains entrenched in resource-constrained settings where capital equipment acquisition faces budget committee resistance.
Strategic Opportunities
- Home Deployment Reimbursement:Outpatient setting payment parity is opening durable medical equipment frameworks for assistive robot segments previously confined to inpatient facilities.
- Sensor-Kinematic Convergence:Real-time motion capture integration with programmable gait pattern algorithms is enabling personalized therapy dosing without continuous clinician oversight.
- India's Rehabilitation Infrastructure:The country's central medical device regulator is streamlining import pathways for Class II powered rehabilitation devices as private hospital chains expand neurorehabilitation units.
Industry Challenges
- Clinical Specialist Talent Scarcity:Rehabilitation robotics operation requires cross-trained physical therapists proficient in electromechanical troubleshooting and kinematic data interpretation.
- Legacy EMR Integration Friction:Proprietary data formats from robotic therapy platforms resist seamless incorporation into hospital electronic medical record systems, fragmenting patient outcome tracking.
- Biocompatibility Certification Delays:Repeated skin-contact surface testing for long-duration exoskeleton wear extends FDA premarket notification timelines for iterative product revisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lower Extremity Rehabilitation Robotics Market |
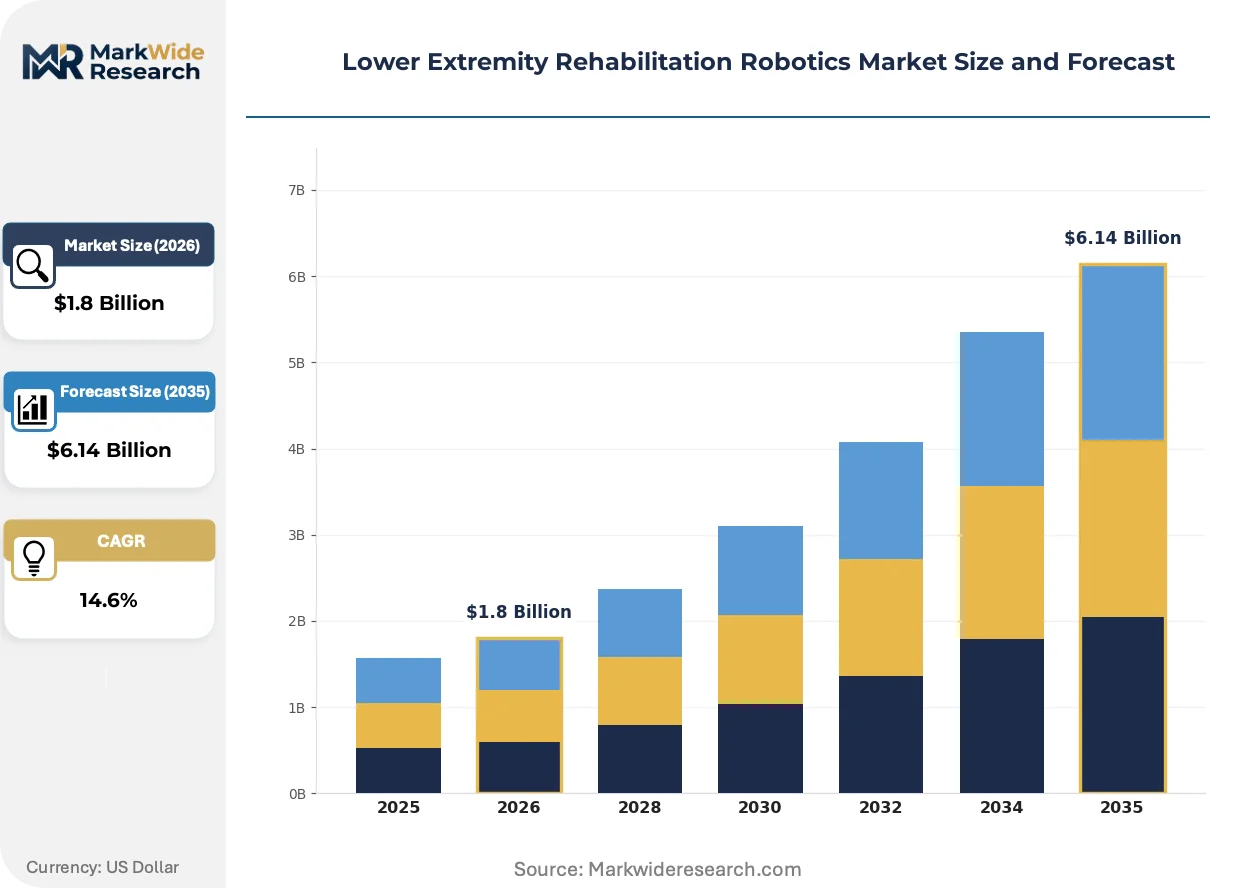
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exoskeletons, Powered Devices, Assistive Robots, Therapy Systems Application: Stroke Recovery, Sports Rehabilitation, Gait Training, Post-Surgery Recovery Technology: Active Control, Passive Movement, Biofeedback Mechanisms, Wearable Robotics End User: Hospitals, Physical Therapy Clinics, Home Care, Rehabilitation Centers |
| Companies Covered | CYBERDYNE INC., Ekso Bionics, BIONIK, Lifeward, Hocoma, ReWalk Robotics, Rex Bionics, DIH, Tyromotion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lower Extremity Rehabilitation Robotics Market Trends and Innovations
Artificial intelligence is embedding into rehabilitation robotics, shifting therapy from preprogrammed gait patterns toward adaptive response systems that modify assistance levels based on real-time patient biomechanics and fatigue indicators.
Soft exosuit technology is decentralizing the market's hardware architecture. These textile-based systems with cable-driven actuation reduce device mass by sixty percent versus rigid-frame exoskeletons. Outpatient clinics and home care agencies are adopting soft systems for cost-containment and transportability. The structural consequence is compressing the addressable market for traditional powered orthoses in sub-acute rehabilitation settings.
The EU Medical Device Regulation's clinical performance documentation mandate is reshaping product development roadmaps. Manufacturers must generate prospective clinical data for CE marking of active therapeutic systems rather than relying on predicate device equivalence. European rehabilitation centers are extending evaluation periods for new platform procurement until longitudinal outcome studies satisfy institutional review board requirements.
Hospital procurement committees are unbundling service contracts from hardware acquisition. Rehabilitation centers previously accepted bundled maintenance and software update terms; now purchasing departments separately negotiate technical support, training, and outcome analytics subscriptions. This behavioral shift is most visible in the United States, where Veterans Health Administration facilities issue distinct RFPs for platform supply versus clinical education and long-term technical support.
Lower Extremity Rehabilitation Robotics Market Segmentation
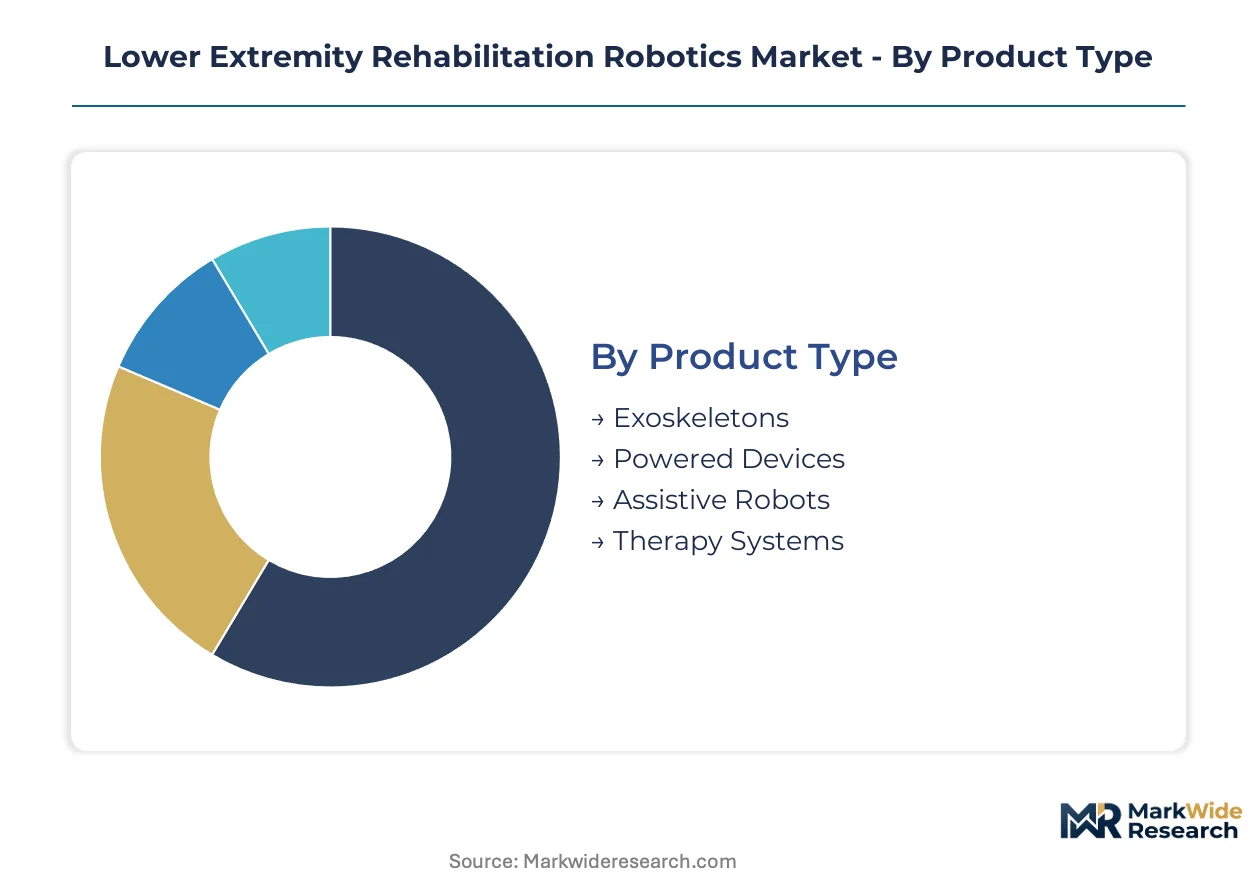
Capital allocation patterns in lower extremity rehabilitation robotics diverge sharply across hardware architectures and care settings. Procurement committees evaluate segments based on floor space requirements, clinician training burden, and reimbursement pathway clarity.
Product Type:
Capital-intensity varies dramatically across hardware categories, with full-locomotion exoskeletons demanding the largest upfront equipment investment and dedicated facility infrastructure.
- Exoskeletons:Rigid-frame systems with force-adjustable joint actuation and real-time kinematic feedback require dedicated gait training labs and ceiling-mounted fall protection. Veterans Health Administration facilities concentrate procurement in the United States, driven by established durable medical equipment reimbursement codes and dedicated therapy budgets.
- Powered Devices:Stationary electromechanical platforms with programmable gait patterns occupy fixed rehabilitation bays and demand continuous power supply. European rehabilitation centers anchor demand through long-term service contracts that bundle hardware with software maintenance and outcome analytics.
- Assistive Robots:Lightweight mobility aids with partial actuation support ambulation in corridor and community settings.
- Therapy Systems:Modular platforms integrating multiple modalities for seated and standing exercise protocols.
Most installed capacity flows through Exoskeletons. Expansion is steepest in Assistive Robots.
Application:
Clinical evidence depth determines payer familiarity and margin structure across therapeutic use cases.
- Stroke Recovery:Neurological rehabilitation protocols leverage repeatable, quantifiable therapy doses for hemiparetic gait restoration. Hospital-based rehabilitation departments scale capacity as aging populations drive incidence, with CMS national coverage determinations reducing prior authorization friction.
- Sports Rehabilitation:Orthopedic recovery applications for ACL reconstruction and Achilles repair concentrate at elite athletic medicine centers with dedicated performance divisions.
- Gait Training:Foundational ambulatory therapy across neurological and orthopedic etiologies.
- Post-Surgery Recovery:Early mobilization protocols following joint replacement and spinal procedures.
Stroke Recovery commands the deepest margin pools. Sports Rehabilitation is climbing the fastest as performance medicine budgets expand.
Technology:
Sensor integration sophistication separates premium platforms from cost-constrained alternatives.
- Active Control:Adaptive response systems modify assistance levels based on real-time patient biomechanics and fatigue indicators. AI-embedded algorithms are shifting therapy from preprogrammed patterns toward personalized dosing without continuous clinician oversight.
- Passive Movement:Motor-driven range-of-motion systems guide limbs through fixed kinematic trajectories. Resource-constrained settings favor these systems where capital equipment acquisition faces budget committee resistance and manual physical therapy substitution pressure persists.
- Biofeedback Mechanisms:Surface electromyography and force plate integration for patient engagement.
- Wearable Robotics:Textile-based soft exosuits with cable-driven actuation reducing device mass substantially versus rigid-frame alternatives.
Active Control systems anchor premium pricing tiers. Wearable Robotics is gaining share fastest through outpatient and home care penetration.
End User:
Reimbursement pathway maturity shapes customer willingness-to-pay and contract structure preferences.
- Hospitals:Inpatient rehabilitation departments with dedicated neurorecovery units require ISO 13485-certified suppliers for procurement tender eligibility. The EU Medical Device Regulation's clinical performance documentation mandate is extending evaluation periods until longitudinal outcome studies satisfy institutional review board requirements.
- Physical Therapy Clinics:Outpatient settings are unbundling service contracts from hardware acquisition, with purchasing departments separately negotiating technical support, training, and outcome analytics subscriptions.
- Home Care:Durable medical equipment frameworks are opening for assistive robot segments previously confined to inpatient facilities.
- Rehabilitation Centers:Dedicated post-acute facilities with concentrated stroke and orthopedic caseloads.
Hospitals retain the largest installed base. Home Care is expanding most quickly as outpatient reimbursement parity shifts payment settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized rehabilitation engineering talent concentrates in metropolitan medical device clusters, with university-affiliated hospitals anchoring regional demand for lower extremity robotic platforms.
United States
The Veterans Health Administration operates dedicated procurement budgets for lower-limb robotic therapy platforms across its integrated health network. FDA breakthrough device designation accelerates commercial timelines for powered exoskeleton systems entering stroke rehabilitation protocols. Pittsburgh and Boston medical device corridors host concentrated engineering talent for electromechanical rehabilitation systems.
Germany
Industrial automation expertise in Bavaria and Baden-Württemberg feeds precision actuator manufacturing for force-adjustable joint systems. EMA Medical Device Regulation mandates clinical performance documentation for CE marking of active therapeutic systems. Heidelberg and Munich rehabilitation centers anchor European demand for programmable gait pattern platforms.
Japan
Aging demographics drive hospital-based departments to scale electromechanical therapy capacity for neurological recovery. METI supports robotics commercialization through regulatory harmonization initiatives with FDA pathways. Tokyo and Osaka metropolitan areas concentrate both manufacturing capability and clinical evaluation sites.
Switzerland
Swissmedic maintains stringent premarket review for powered rehabilitation devices entering its reimbursement system. Zurich and Geneva rehabilitation institutes generate clinical evidence for European market access. The country's precision engineering base supplies harmonic drive components for torque-precision joint actuation.
South Korea
MFDS streamlines regulatory pathways for Class II powered rehabilitation devices as private hospital chains expand neurorehabilitation units. Seoul Capital Area medical centers deploy robotic gait training for stroke recovery protocols. Government-funded aging-in-place initiatives stimulate home deployment segments for assistive mobility systems.
Lower Extremity Rehabilitation Robotics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the lower extremity rehabilitation robotics landscape. The market structure shows moderate consolidation around integrated platform developers with established service networks. Three archetypes dominate: full-locomotion exoskeleton specialists, stationary therapy system providers, and emerging soft exosuit developers. Competitive moves center on unbundling service contracts from hardware sales and securing institutional procurement tender eligibility through ISO 13485 certification.
Among North American platform developers, Ekso Bionics and ReWalk Robotics occupy positions representing the durable medical equipment reimbursement pathway archetype. CYBERDYNE INC. exemplifies the Asian integrated healthcare robotics model with its regulatory-first market entry approach. European specialists including Hocoma and Tyromotion sit within the long-term service contract archetype, anchoring revenue through software maintenance and outcome analytics subscriptions rather than pure hardware transactions.
| Leading Market Players |
|---|
| CYBERDYNE INC. |
| Ekso Bionics |
| BIONIK |
| Lifeward |
| Hocoma |
| ReWalk Robotics |
| Rex Bionics |
| DIH |
| Tyromotion |
| Others |
Pricing and Supply Chain Analysis
Precision electromechanical engineering talent concentrates in Bavaria and Baden-Württemberg, where labor-cost differentials between German manufacturing hubs and Asian assembly centers drive three-hundred-basis-point spreads between premium-tier exoskeleton systems and economy-grade assistive devices.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated systems from ISO 13485-certified alternatives and basic motorized orthoses. Price differentiation rests on CE marking tier and after-sales service bundling. Cost compression in the economy tier is intensifying because manual physical therapy substitution pressure persists in resource-constrained settings. Hospital procurement committees exhibit the highest price sensitivity, while Veterans Health Administration facilities demonstrate lowest sensitivity due to dedicated therapy budgets.
Supply Chain Analysis
Dual-sourcing requirements for precision torque motors and harmonic drive components mandate multi-supplier qualification across institutional procurement tenders. Manufacturing concentrates in Germany, Japan, and South Korea. Component sourcing draws from Swiss precision engineering bases for joint actuation systems. Single-source vulnerability persists for cable-driven actuation textiles in soft exosuit production. Distribution runs through direct clinical specialist teams for hospital sales and durable medical equipment distributors for home care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between FDA breakthrough pathway timelines and EMA MDR documentation requirements creates eighteen-to-twenty-four-month commercialization windows for dual-certified platforms.
For Market Incumbents: Anticipate soft exosuit displacement of rigid-frame systems in sub-acute rehabilitation settings by securing backward integration into textile-based actuation manufacturing. Defend hospital channel control through unbundled service contracts that separate hardware acquisition from outcome analytics subscriptions, countering emerging asset-light competitors. For New Entrants and Emerging Players: Launch via durable medical equipment distribution partnerships targeting home care reimbursement parity in United States outpatient settings. India's streamlined CDSCO import pathways for Class II powered rehabilitation devices represent the most penetrable geography, with private hospital chains expanding neurorehabilitation units faster than domestic supply can satisfy. For Investors and Strategic Acquirers: Hospital systems with captive rehabilitation networks are the most active acquirer in this space, seeking vertical integration into therapy device supply. Acquisition targets with ISO 13485 certification and established Veterans Health Administration procurement relationships offer strongest five-to-ten-year viability. Watch CMS national coverage determination expansions for home-based robotic gait training as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy Development | CMS national coverage determinations reduce prior authorization friction for stroke rehabilitation protocols. |
| CE Marking Pathway Investment | EMA MDR clinical performance documentation mandates reshape European product development roadmaps. |
| Hospital System Partnership | Veterans Health Administration dedicated procurement budgets concentrate demand in United States facilities. |
| Software Companion Development | Real-time kinematic feedback integration enables personalized therapy dosing without continuous clinician oversight. |
| Backward Integration into Actuation | In-house production of precision torque motors mitigates Asian supply base concentration risks. |
Research Methodology
Coverage spans United States, Germany, Japan, Switzerland, and South Korea, with primary inputs from each market combining interviews with rehabilitation clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers alongside secondary validation through FDA 510(k) filings, EMA MDR submissions, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up and top-down triangulation cross-validates segment-level estimates against aggregate market sizing.
Granularity-level modeling disaggregates volume and value outputs across product type, application, technology, and end user dimensions, with additional stratification by regulatory approval pathway and reimbursement framework. CAGRs derive from segment-specific growth trajectories anchored to demographic stroke incidence projections and institutional capacity expansion plans. Forecast inputs incorporate Veterans Health Administration budget allocations and private hospital chain neurorehabilitation unit buildouts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EMA MDR documentation timeline extensions or CMS reimbursement determination delays. Deviation in home care payment parity adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Global Robotic Rehabilitation and Assistive Technologies Market
Rehabilitation Services
Behavioral Rehabilitation Market
Rehabilitation Services
Rehabilitation Robots Market
Rehabilitation Services
Global Women Health Rehabilitation Products Market
Rehabilitation Services
Rehabilitation Products Market
Rehabilitation Services
Rehabilitation Equipment Market
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market
Rehabilitation Services
US Assisted Living Facility and Neurorehabilitation Market
Rehabilitation Services
Global Gait Trainer Market
Rehabilitation Services
Brachial Plexus Injury Market
Rehabilitation Services
Occupational and Physical Therapy Services Market
Rehabilitation Services
Exoskeleton and Rehabilitation Robot Safety and Performance Test Equipment Market
Rehabilitation Services
Global Neurorehabilitation Devices Market
Rehabilitation Services
United States Behavioral Rehabilitation Market
Rehabilitation Services
Speech Pathology Services Market
Rehabilitation Services
Global Medical Rehabilitation Services Market